
 Garbage Collection Vehicle Market | 2026-2036
Garbage Collection Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Garbage Collection Vehicle Market Analysis
Electric powertrain architecture is fragmenting traditional diesel-centric supply chains as battery-electric and hydrogen fuel cell configurations demand entirely new chassis integration approaches. Heil leverages its refuse body expertise to develop modular electric-compatible platforms across multiple truck OEM partnerships. McNeilus Truck and Manufacturing anchors North American production with dedicated facilities serving municipal and private hauler segments. Dennis Eagle competes in European dense-urban markets with narrow-cab designs optimized for historic street layouts.
Garbage collection vehicles are purpose-built trucks featuring hydraulically actuated compaction mechanisms, payload capacities ranging from ten to thirty-two tons, and specialized lifting apparatus for standardized waste containers. Their primary function is the mechanized collection, compression, and transport of municipal solid waste from residential and commercial points to transfer stations or disposal facilities. Rear loader configurations dominate mature markets where manual bag collection persists, while automated side loader adoption accelerates in municipalities seeking labor cost reduction. Electric fuel type penetration expands fastest among urban fleets with predictable route profiles and depot-based overnight charging infrastructure.
EPA Phase 3 greenhouse gas standards and the EU Green Deal's transport decarbonization targets are forcing accelerated powertrain transitions across fleet procurement cycles. NHTSA safety regulations and ISO 9001 quality management frameworks shape manufacturing compliance and component traceability requirements. Stakeholders must monitor battery second-life applications and charging infrastructure interoperability as fleet electrification scales beyond pilot deployments.
Market Dynamics
Fleet electrification is fragmenting established powertrain supply chains as battery-electric and hydrogen fuel cell architectures demand entirely new chassis integration approaches, forcing incumbents to retool manufacturing footprints and forge unfamiliar supplier relationships.
Growth Catalysts
- EPA Phase 3 greenhouse gas standards:US municipal procurement cycles are compressing diesel replacement timelines, accelerating zero-emission vehicle tenders across state sanitation departments.
- Automated side loader technology:Labor cost reduction imperatives in dense urban environments are driving adoption of single-operator collection systems with robotic arm mechanisms.
- Germany's municipal fleet renewal:Berlin and Hamburg operate Europe's largest automated collection deployments, creating concentrated demand for narrow-cab electric-compatible chassis.
Market Restraints
- Battery cell supply concentration:Cathode material processing and cell manufacturing capacity clusters in China, exposing European and North American OEMs to geopolitical supply disruption risks.
- Depot charging infrastructure capex:Grid upgrade requirements and high-voltage installation costs strain municipal capital budgets, particularly in legacy fleet facilities with aged electrical infrastructure.
- Hydrogen fuel cell technical limitation:Energy density constraints and cryogenic storage complexity restrict fuel cell garbage trucks to specific route profiles, limiting addressable market segments.
Strategic Opportunities
- Second-life battery applications:Retired electric vehicle battery packs offer stationary energy storage for depot charging load management, creating circular economy revenue streams.
- Interoperable charging standards:ISO 15118 and OCPP protocol harmonization enables fleet operators to leverage multi-vendor charging networks, reducing vendor lock-in.
- France's urban low-emission zones:Paris and Lyon municipal mandates are accelerating early retirement of diesel refuse fleets ahead of EU-wide deadlines.
Industry Challenges
- High-voltage technician skill gap:Fleet maintenance departments lack certified personnel for battery pack diagnostics and electric powertrain repair, forcing reliance on OEM service networks.
- Integration complexity with legacy route optimization software:Electric vehicle range constraints and charging windows require algorithmic overhaul of decades-old collection scheduling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garbage Collection Vehicle Market |
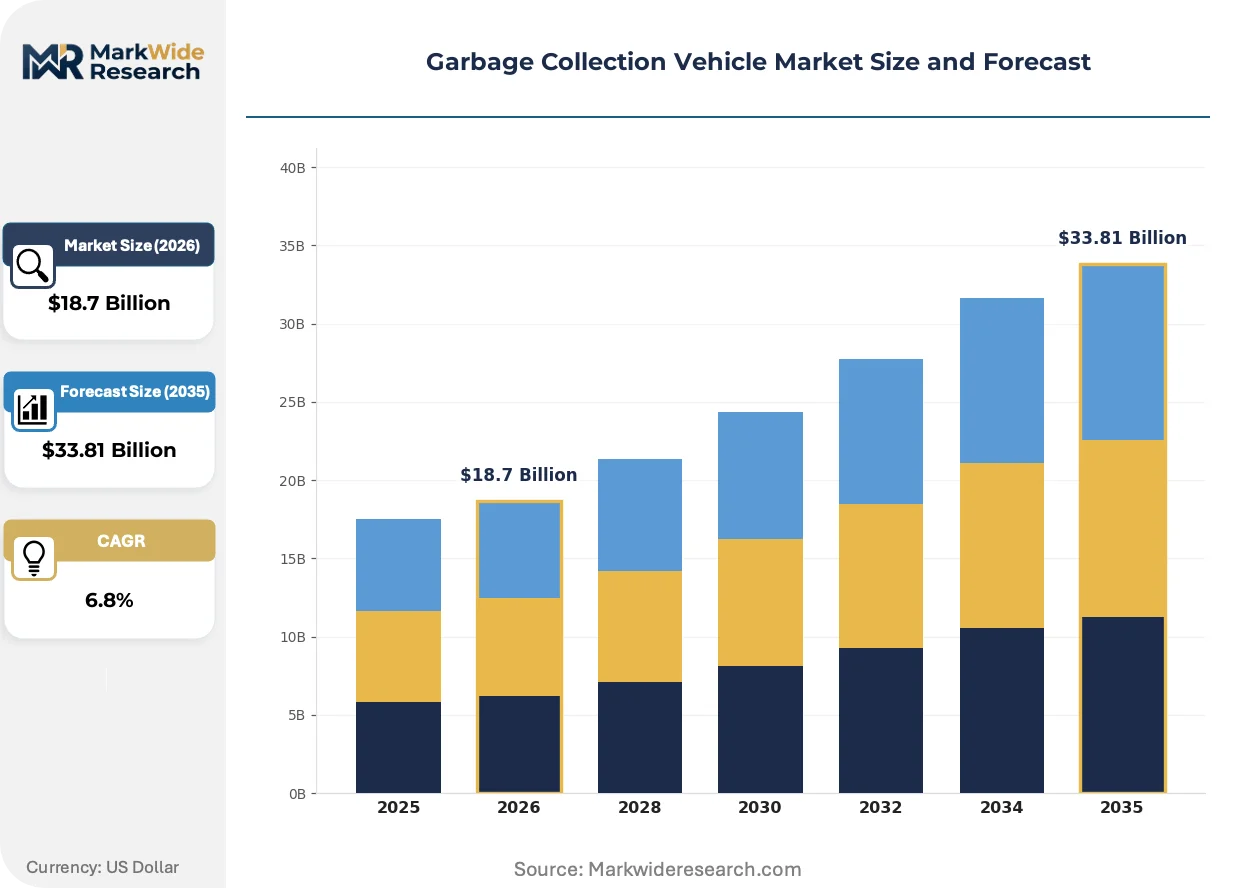
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Rear Loader, Front Loader, Side Loader, Automated Fuel Type: Diesel, Compressed Natural Gas, Electric, Hybrid Operational Mode: Manual, Semi-Automated, Fully Automated, Smart End User: Municipalities, Private Companies, Contractors, Waste Management Services |
| Companies Covered | Heil, McNeilus Truck and Manufacturing, Dennis Eagle, FAUN Umwelttechnik, New Way Trucks, Zoomlion Heavy Industry Science & Technology, XCMG, Labrie Enviroquip Group, Fujian Longma Environmental Sanitation Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garbage Collection Vehicle Market Emerging Trajectories
Digital twin technology is virtualizing vehicle development cycles, compressing prototype-to-production timelines while enabling predictive maintenance models that reshape fleet operator total cost of ownership calculations.
Telematics and route simulation software is virtualizing fleet deployment decisions before physical asset commitment. Municipal procurement teams in the Netherlands and Scandinavia now require digital twin validation of electric range performance against actual topography and stop-frequency data. This capability is compressing vendor selection cycles and reducing specification disputes between buyers and chassis suppliers.
The EU Green Deal's transport decarbonization targets are mandating zero-emission procurement preferences in public tenders. German and French municipal authorities now weight environmental performance above upfront capital cost in evaluation matrices. This policy shift is forcing incumbent diesel-centric suppliers to accelerate electric platform development or face exclusion from core market segments.
Service contract unbundling is separating vehicle supply from maintenance provision in municipal procurement. UK and Australian waste management authorities now solicit distinct bids for chassis acquisition, refuse body integration, and multi-year operational support. This fragmentation is opening entry points for specialized electric powertrain suppliers previously excluded from integrated OEM relationships.
Garbage Collection Vehicle Market Segmentation
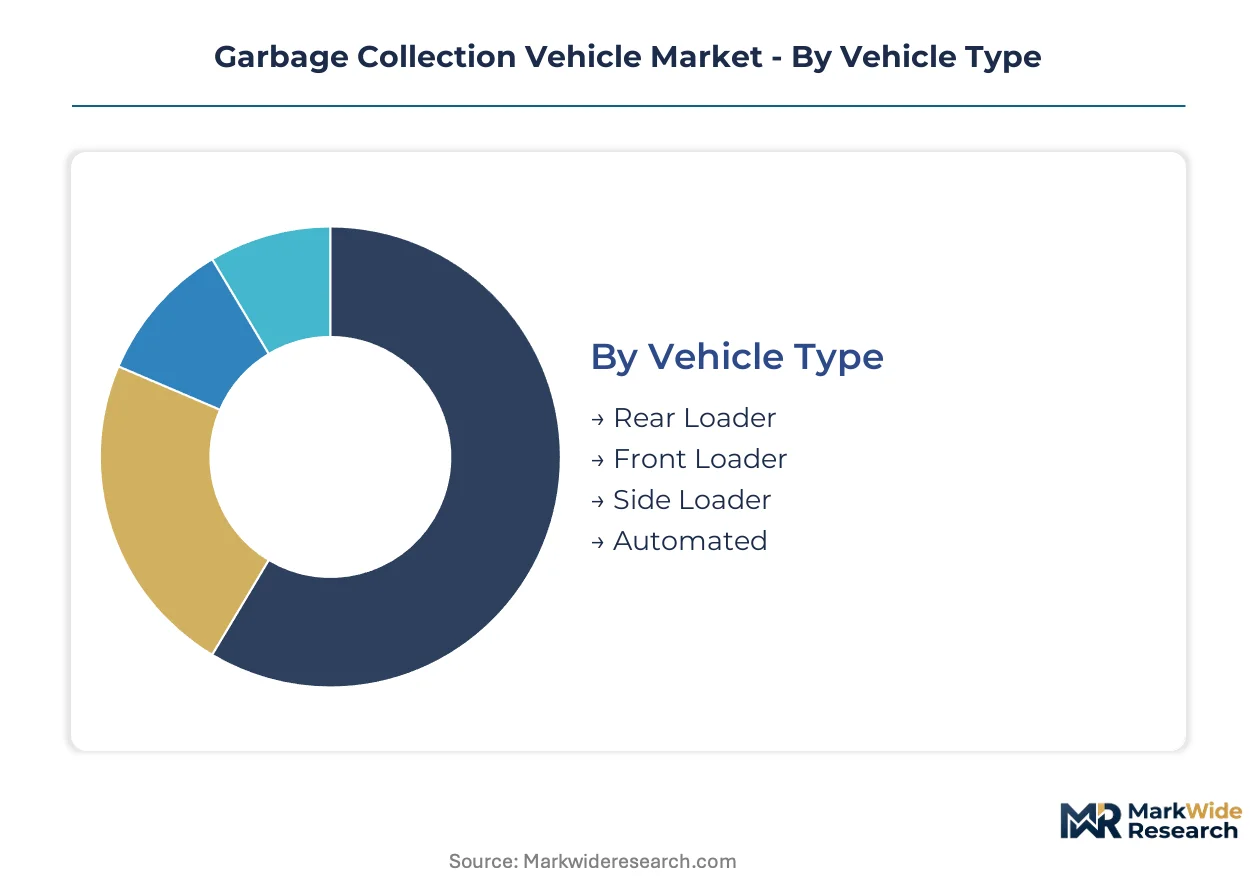
Segmentation in garbage collection vehicles reveals distinct service intensity patterns across powertrain technologies and automation levels. Electric and hydrogen fuel cell platforms demand specialized technician networks and depot infrastructure investments that reshape aftermarket profitability structures for fleet operators and OEM service divisions.
Vehicle Type:
After-sales service intensity varies sharply across loader configurations, with automated systems requiring predictive maintenance contracts and hydraulic component replacement programs that dominate lifecycle revenue.
- Rear Loader:Traditional tailgate compaction with manual bag loading dominates legacy fleet deployments. Municipal sanitation departments in Germany and France concentrate replacement demand here as diesel phase-out deadlines accelerate fleet turnover.
- Front Loader:Roll-off container handling with cab-mounted lifting arms serves commercial waste streams. Private haulers in dense urban corridors prioritize these units for construction debris and industrial collection routes where payload efficiency governs procurement decisions.
- Side Loader:Curbside container retrieval with single-operator efficiency reduces labor headcount. Narrow-cab variants optimized for historic European street layouts command premium positioning in automated fleet tenders.
- Automated:Robotic arm mechanisms with optical container recognition eliminate manual handling. Berlin and Hamburg operate Europe's largest deployments, creating concentrated demand for OEM-integrated service contracts covering hydraulic actuators and sensor calibration.
By volume, Rear Loader leads. By growth pace, Automated is ahead.
Fuel Type:
Powertrain segmentation stratifies around total cost of ownership calculations, with electric platforms requiring battery management system expertise that fragments traditional diesel mechanic networks.
- Diesel:Compression-ignition engines with established service infrastructure face accelerated retirement timelines. EPA Phase 3 greenhouse gas standards compress procurement cycles for remaining diesel acquisitions to avoid stranded asset risk.
- Compressed Natural Gas:Spark-ignited engines with dedicated refueling infrastructure serve specific municipal contracts. Limited addressability constrains growth to regions with existing CNG station networks.
- Electric:Battery-electric architectures with depot overnight charging reshape chassis integration approaches. Predictable urban route profiles with return-to-base operations concentrate demand in Netherlands and Scandinavian municipal fleets.
- Hybrid:Dual powertrain configurations with regenerative braking bridge transition timelines. Range anxiety mitigation drives adoption among contractors serving dispersed rural collection zones.
By installed base, Diesel dominates. By expansion trajectory, Electric climbs the fastest.
Operational Mode:
Automation intensity correlates directly with software update frequency and telematics subscription revenue, shifting vendor economics toward recurring service models.
- Manual:Human-operated lifting and compaction persists in emerging markets and budget-constrained municipalities. Labor availability constraints limit addressable growth in developed economies.
- Semi-Automated:Mechanized lifting with operator oversight reduces physical strain. Mid-tier procurement budgets in UK waste authorities favor this configuration for workforce retention.
- Fully Automated:Single-operator collection with robotic arm control minimizes crew requirements. German municipal fleet specifications increasingly mandate this capability for new tenders.
- Smart:AI-enabled route optimization with real-time fill-level sensors integrates fleet management platforms. Paris and Lyon low-emission zone mandates accelerate adoption alongside electric powertrain requirements.
By deployment share, Semi-Automated holds the lead. By specification momentum, Smart systems gain share fastest.
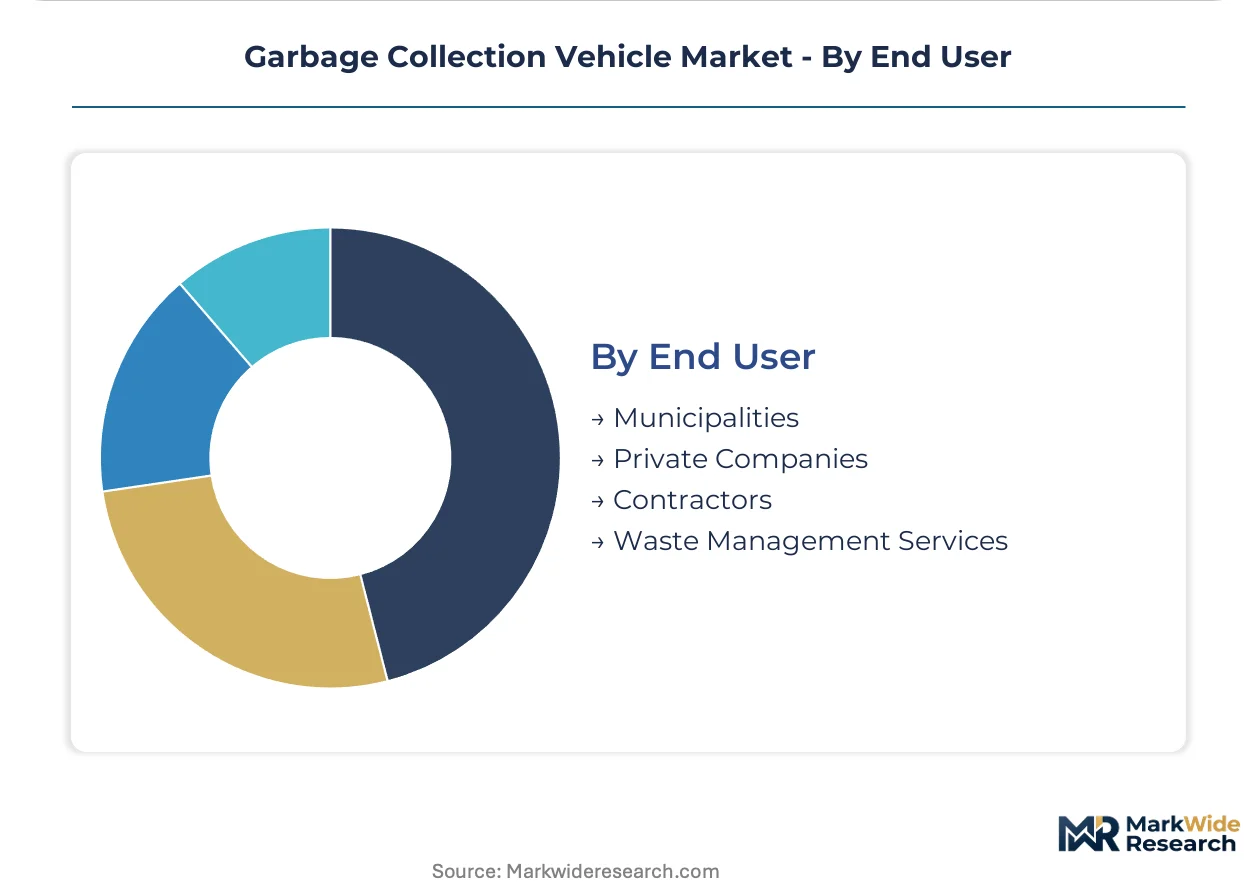
End User:
Customer segmentation determines contract structure complexity, with municipalities demanding unbundled procurement that separates chassis acquisition from refuse body integration and long-term service provision.
- Municipalities:Public sanitation departments with fleet standardization requirements and political procurement oversight. EU Green Deal transport decarbonization targets mandate zero-emission preferences in German and French evaluation matrices.
- Private Companies:Commercial waste haulers with profitability-driven equipment decisions. Service contract unbundling in UK and Australian markets opens entry points for specialized electric powertrain suppliers.
- Contractors:Third-party operators with project-specific fleet needs and flexible financing requirements. Seasonal demand fluctuations favor leasing arrangements over capital acquisition.
- Waste Management Services:Integrated collection-to-disposal operators with vertical control over logistics chains. Scale economies drive standardization across multi-site fleet deployments.
By vehicle count, Municipalities lead. By electrification pace, Private Companies move fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chassis manufacturers export electric-compatible refuse platforms to municipal fleets across Scandinavia and the Netherlands, establishing a north-south trade corridor that channels specialized narrow-cab designs into dense-urban procurement cycles.
United States
EPA Phase 3 greenhouse gas standards compress diesel replacement timelines across state sanitation departments. Municipal procurement teams in California and New York weight zero-emission vehicle specifications above upfront capital cost. Los Angeles and San Francisco operate pilot automated side loader deployments with depot-based overnight charging infrastructure.
Germany
Berlin and Hamburg anchor Europe's largest automated collection fleet concentrations, creating sustained demand for narrow-cab electric-compatible chassis. KBA type-approval requirements shape powertrain integration standards for municipal tenders. Bavarian manufacturing clusters supply refuse body integration services to Rhine-Ruhr metropolitan procurement authorities.
France
Paris and Lyon municipal mandates accelerate early retirement of diesel refuse fleets ahead of EU-wide deadlines. ANSM regulatory frameworks influence safety certification for hydraulic compaction mechanisms. Île-de-France regional authorities specify smart fleet management integration in new tender evaluations.
Netherlands
Predictable urban route profiles with return-to-base operations concentrate battery-electric adoption in Randstad metropolitan corridors. National low-emission zone expansion drives replacement demand across municipal sanitation departments. Eindhoven Region hosts telematics validation centers for digital twin route simulation services.
China
Dual carbon goals and MIIT new energy vehicle mandates redirect municipal procurement toward electric powertrain configurations. Yangtze River Delta manufacturing clusters produce chassis platforms for domestic waste management authorities. Shenzhen and Shanghai operate automated collection pilots with integrated AI-enabled fill-level sensor networks.
Garbage Collection Vehicle Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Established refuse body specialists with modular electric-compatible platforms occupy the premium procurement segment. Scale-driven chassis integrators serve volume municipal contracts through dedicated production facilities. Regional fabricators with localized service networks capture mid-tier private hauler demand. Competitive positioning hardens through OEM partnership formations and strategic unbundling of service contracts from vehicle supply.
Within the premium-tier refuse body segment, Heil and McNeilus Truck and Manufacturing exemplify modular platform strategies that span multiple truck OEM relationships. Dennis Eagle occupies a position in European dense-urban markets where narrow-cab designs address historic street layout constraints. These three anchors represent divergent geographic specializations rather than direct product competition, with each exemplifying how regional procurement preferences shape manufacturing footprint decisions.
| Leading Market Players |
|---|
| Heil |
| McNeilus Truck and Manufacturing |
| Dennis Eagle |
| FAUN Umwelttechnik |
| New Way Trucks |
| Zoomlion Heavy Industry Science & Technology |
| XCMG |
| Labrie Enviroquip Group |
| Fujian Longma Environmental Sanitation Equipment |
| Others |
Supply Flow & Price Mechanics
China's cathode material processing clusters and cell manufacturing capacity concentrate upstream battery supply, anchoring margin capture in electric powertrain tiers while forcing European and North American OEMs into long-term offtake negotiations or captive sourcing investments.
Pricing Analysis
Diesel-to-electric technology-generation pricing gaps exceed two-to-one multiples, with battery-electric chassis commanding substantial premiums over legacy compression-ignition platforms. Three-tier pricing structure across premium, standard, and economy levels separates automated narrow-cab configurations from conventional rear loaders and basic manual-loading units. Price differentiation hinges on ISO 9001 certification tier and after-sales service bundling intensity. Cost compression in mid-tier electric platforms is intensifying because battery pack commoditization and chassis integration learning curves are accelerating. Municipal sanitation departments exhibit highest price sensitivity due to political procurement oversight, while integrated waste management services demonstrate lowest sensitivity given vertical scale economies.
Supply Chain Analysis
Upstream feedstock dependence on lithium carbonate, nickel sulfate, and rare earth permanent magnets draws from concentrated extraction corridors in Chile, Indonesia, and China. Lithium-ion cell production rests on cathode precursor chemistry dominated by Chinese processing facilities. Single-source vulnerability in high-voltage power electronics and battery management systems creates procurement risk for European chassis integrators. Distribution runs through OEM-authorized dealer networks for municipal fleet contracts, with direct manufacturer relationships governing large private hauler acquisitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation across German and French metropolitan authorities has shifted bargaining power toward buyers, forcing incumbent suppliers into service contract unbundling and extended warranty concessions to maintain fleet specification access.
For Market Incumbents: Insulate core refuse body margins through backward integration into hydraulic actuator manufacturing and captive battery pack assembly in Poland or Hungary to offset Chinese cell supply exposure. Hydrogen fuel cell technical limitations threaten to strand R&D investments if route profile constraints persist unaddressed. Certification investment in EU Green Deal compliance documentation represents the priority defensive lever for German tender participation. For New Entrants and Emerging Players: Establish a beachhead in UK and Australian service contract unbundling opportunities where specialized electric powertrain suppliers previously faced integrated OEM exclusion. Automated side loader technology penetration in Netherlands municipal fleets offers the most penetrable specification entry point. Telematics platform partnerships with established route optimization software vendors provide the critical go-to-market angle for smart fleet management integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed refuse body specialists holding modular electric-compatible platforms but lacking direct chassis OEM relationships. Long-term viability across the analysis window favors suppliers with demonstrated narrow-cab European urban deployment experience and depot charging infrastructure partnership networks. Watch for EPA Phase 3 enforcement acceleration as the inflection signal indicating compressed replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Depot high-voltage installation alliances with municipal grid operators secure fleet electrification contract eligibility in California and New York. |
| Digital Twin Platform Investment | Virtual range validation capabilities against Dutch topography data compress vendor selection cycles for Randstad metropolitan tenders. |
| Battery Supply Agreement | Long-term cathode material offtakes with Chinese processors mitigate geopolitical disruption exposure for European chassis production. |
| Refuse Body Standardization | Modular electric-compatible platforms spanning multiple truck OEM partnerships reduce engineering redundancy and accelerate procurement responsiveness. |
| Aftermarket Service Unbundling | Separate maintenance provision bids in UK waste authority contracts open recurring revenue streams independent of vehicle supply cycles. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with municipal fleet procurement directors, refuse body manufacturing executives, and high-voltage technician training providers, combined with secondary validation through EPA regulatory filings, EU Green Deal implementation documents, KBA type-approval databases, and municipal tender documentation from Berlin, Hamburg, Paris, and Lyon. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction across powertrain and automation segments.
Forecast inputs considered vehicle replacement cycle compression under EPA Phase 3 standards, EU Green Deal procurement preference weighting, and battery cost learning curve trajectories across the projection horizon. Segmentation dimensions modeled include loader configuration, fuel type architecture, automation intensity tier, and end-user contract structure. CAGRs derived from logistic diffusion curves for electric powertrain penetration constrained by depot infrastructure deployment timelines and technician certification pipeline capacity.
Sensitivities concentrate around battery cell supply disruption scenarios, municipal capital budget austerity cycles, and hydrogen fuel cell technical limitation resolutions. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and infrastructure investment commitments. Cross-checking against national vehicle registration databases and municipal fleet inventory disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Global Automotive EGR Valves Market
Vehicle Components
Global Automotive Wheel Bearings Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Headlight Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Transmission Components Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
CV Brake Controls Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market