
 Mobility Aids and Transportation Equipment Market | 2026-2036
Mobility Aids and Transportation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mobility Aids and Transportation Equipment Market Analysis
The capital-intensity divergence between automated manufacturing and hand-finished customization is unwinding competitive stability in the mobility aids sector. Invacare Corporation leverages vertically integrated aluminum frame production to sustain margin control across North American distribution. Ottobock SE & Co. KGaA anchors its position through carbon fiber prosthetic-adjacent expertise that extends into ultra-lightweight wheelchair chassis design. Sunrise Medical LLC competes via modular platform architectures that reduce SKU complexity across European rehabilitation channels.
Mobility aids and transportation equipment encompass wheeled, ambulatory, and powered apparatus engineered to ISO 7176 technical standards for dimensional stability, fatigue testing, and tip-resistance validation, serving primarily to restore functional independence for users with gait, balance, or endurance limitations. Wheelchairs and scooters generate the dominant revenue pools, with electric wheelchairs capturing premium pricing through lithium-ion battery integration and programmable drive controls. Smart navigation systems represent the fastest-expanding technology segment, though manual wheelchairs retain volume leadership in institutional procurement across emerging markets where reimbursement thresholds constrain capital outlays.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) Class I/IIa classification rules shape product registration timelines, testing burdens, and post-market surveillance obligations for manufacturers seeking multi-jurisdictional placement. Japan's METI enforces JIS T 9203 standards for wheelchair structural integrity, creating additional compliance layering for exporters targeting the second-largest geriatric population base. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies, as these determinations directly gate patient access velocity and manufacturer pricing autonomy across priority markets.
Market Dynamics
Reimbursement coding fragmentation across national health technology assessment bodies is forcing manufacturers to maintain parallel regulatory dossiers and pricing architectures, elevating compliance overhead as a primary competitive filter.
Growth Catalysts
- Geriatric population expansion:Japan's METI projects sustained demand pressure through 2040 as the cohort aged 75+ exceeds 20% of total population, institutionalizing powered mobility procurement in municipal care facilities.
- ISO 7176-19 crash-testing mandates:Transport-safe wheelchair standards in the European Union are accelerating replacement cycles for legacy institutional fleets that fail frontal-impact validation.
- Lithium-ion chemistry maturation:Energy density improvements in battery cell manufacturing are extending electric wheelchair range thresholds above 25 kilometers per charge, satisfying community-access use cases previously reserved for mobility scooters.
Market Restraints
- Aluminum alloy price volatility:Frame material costs fluctuate with London Metal Exchange pricing, compressing margin buffers for manufacturers without captive smelter arrangements or long-term offtake contracts.
- Supply concentration in precision motors:Brushless DC drive systems for powered wheelchairs source predominantly from East Asian component specialists, creating single-source vulnerability for European and North American assemblers.
- Reimbursement ceiling rigidity:Germany's statutory health insurance fixes assistive device tariffs on a statutory schedule, preventing manufacturers from capturing value from feature upgrades without parallel private-pay channel development.
Strategic Opportunities
- Rural India penetration gap:District-level disability welfare schemes remain underutilized for mobility aid distribution, presenting first-mover advantage for manufacturers establishing state-level distributor networks before competitive saturation.
- Smart navigation convergence:Integration of LIDAR obstacle detection with programmable drive controls creates premium-tier differentiation for indoor autonomous operation in rehabilitation centers and aged-care facilities.
- Direct-to-consumer channel emergence:Specialized e-commerce platforms for durable medical equipment are bypassing traditional durable medical equipment dealer networks, capturing margin previously allocated to intermediary markup.
Industry Challenges
- Biomechanical assessment talent scarcity:Certified assistive technology professionals capable of prescribing complex powered seating systems remain concentrated in urban academic medical centers, limiting rural and suburban patient access to appropriate device matching.
- FDA 510(k) predicate drift:Substantial equivalence determinations for novel drive control interfaces face elongated review timelines as the agency narrows acceptable predicate device categories, delaying commercialization schedules.
- Legacy fleet interoperability:Smart wheelchair connectivity standards lack cross-manufacturer uniformity, complicating health system IT integration and remote monitoring platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobility Aids and Transportation Equipment Market |
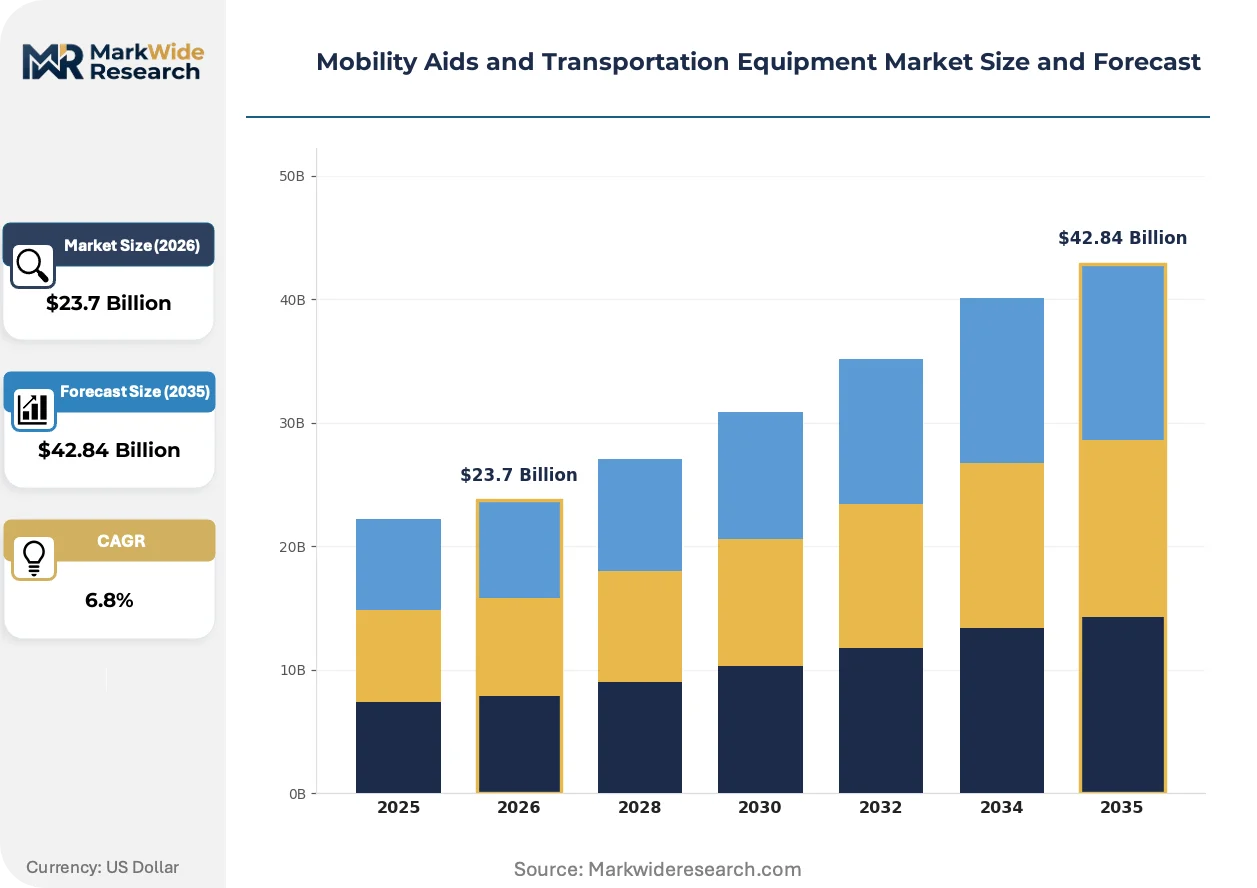
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheelchairs, Walkers, Scooters, Canes End User: Elderly, Disabled Individuals, Rehabilitation Centers, Hospitals Distribution Channel: Online Retail, Medical Supply Stores, Pharmacies, Direct Sales Technology: Electric Wheelchairs, Manual Wheelchairs, Smart Navigation, Adjustable Height |
| Companies Covered | Invacare Corporation, Sunrise Medical LLC, Ottobock SE & Co. KGaA, Permobil AB, Medline Industries, Pride Mobility Products Corporation, Drive DeVilbiss Healthcare, Stryker Corporation, Hoveround Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobility Aids and Transportation Equipment Market Emerging Trajectories
Carbon fiber chassis fabrication is fragmenting the traditional aluminum-dominant supply base, while regulatory pressure on transport safety and autonomous navigation capabilities is redefining product development priorities across the value chain.
Modular seating systems are fragmenting the conventional custom-molded prescription model. Rehabilitation centers in Germany and the Netherlands are adopting adjustable off-the-shelf configurations that reduce fitting appointment duration from three hours to forty-five minutes. This compression is enabling higher patient throughput without proportional clinical staff expansion, reshaping service economics for institutional purchasers.
The EU Medical Device Regulation Class IIa reclassification for powered wheelchairs with programmable electronics is extending notified body review timelines from eight to fourteen months. Manufacturers are responding by front-loading clinical evidence generation and establishing dedicated regulatory affairs functions in Brussels to anticipate guidance document revisions. Products with legacy CE certificates under the Medical Device Directive face mandatory technical file renewal by 2028, concentrating compliance investment in the current planning cycle.
Institutional procurement committees are consolidating vendor relationships to reduce administrative burden, displacing fragmented multi-supplier arrangements previously common in hospital system purchasing. Single-source framework agreements now cover three-to-five year horizons with performance metrics tied to uptime guarantees and spare parts availability. This concentration is most visible in the United Kingdom's National Health Service supply chain rationalization, where regional procurement hubs are awarding exclusive contracts to manufacturers with demonstrated service network density.
Mobility Aids and Transportation Equipment Market Segmentation
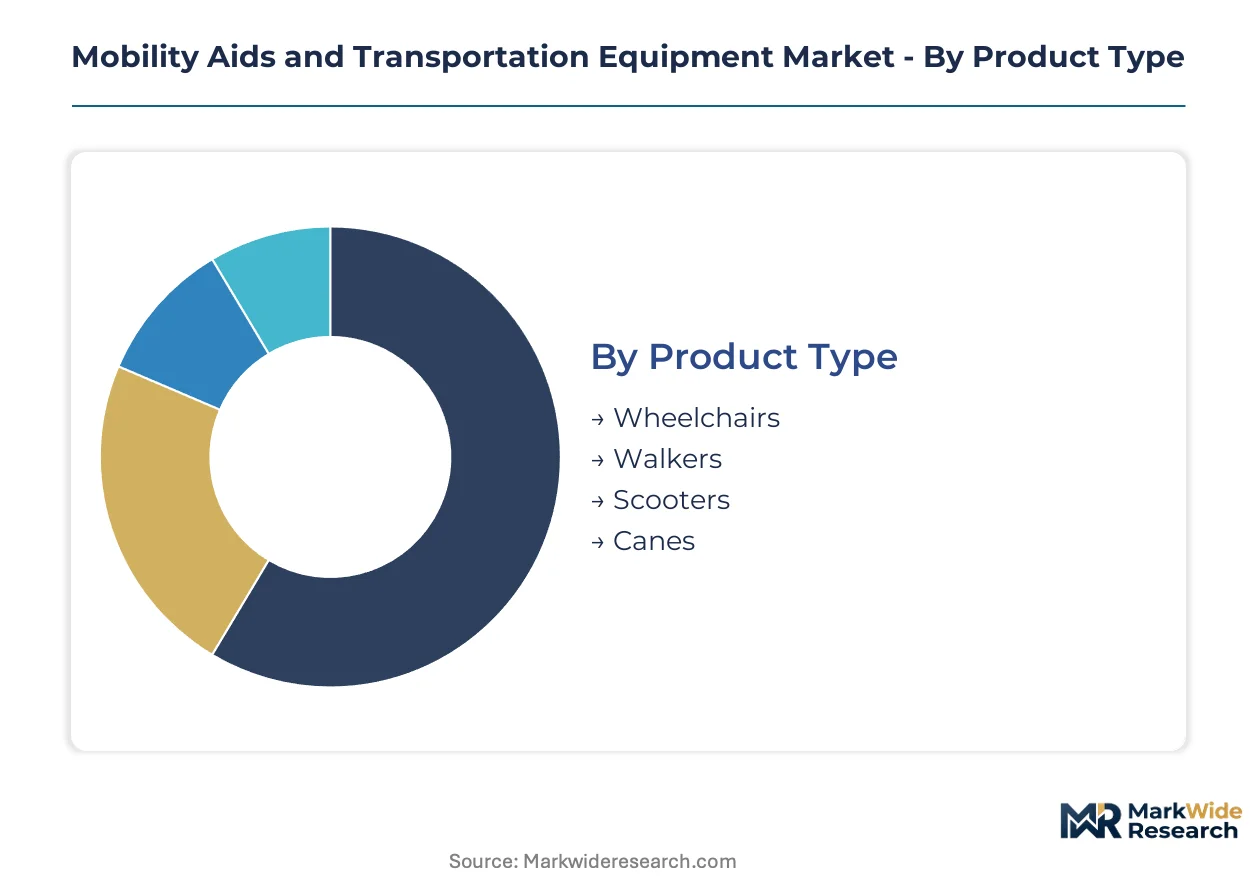
Segmentation in mobility aids determines reimbursement pathways, regulatory classification, and procurement channel selection. Product type and technology tiers dictate whether devices clear FDA 510(k) or EU MDR Class IIa pathways. End-user concentration shapes whether manufacturers prioritize institutional sales forces or direct-to-consumer platforms.
Product Type:
Wheelchairs dominate export volumes from German and Chinese manufacturing clusters, while walkers and canes concentrate in domestic production across North American and European markets due to lower shipping cost sensitivity.
- Wheelchairs:ISO 7176-certified frames in aluminum or carbon fiber configurations serve institutional procurement in Japan and Germany. Municipal care facilities in Tokyo prefecture are replacing legacy fleets ahead of METI transport-safety deadlines, accelerating replacement demand.
- Walkers:Height-adjustable aluminum frames with pressure-activated brakes dominate prescription volume in Medicare Part B channels across the United States. Rehabilitation centers prioritize rollator variants with integrated seating for patient endurance protocols.
- Scooters:Three-wheel and four-wheel configurations with tiller steering capture community-access use cases among elderly users in suburban United States markets.
- Canes:Single-point and quad-base aluminum variants serve balance-compensatory needs in retail pharmacy channels with minimal fitting requirements.
Wheelchairs command the established base. The steepest expansion runs through scooters as lithium-ion range thresholds satisfy longer-distance community mobility.
End User:
Cost tier differentiation separates premium prescription-grade equipment for rehabilitation centers from economy-tier retail products for elderly self-purchasers.
- Elderly:Self-directed purchasers in United States and Japanese markets favor lightweight manual wheelchairs and rollators available through Medicare or statutory insurance reimbursement. Private-pay channels capture premium electric wheelchair demand among affluent retirees.
- Disabled Individuals:Complex rehabilitation technology prescriptions require certified assistive technology professional assessment, concentrating demand in urban academic medical centers across Germany, the United Kingdom, and the United States.
- Rehabilitation Centers:Institutional procurement committees in the Netherlands and Germany are consolidating vendor relationships under multi-year framework agreements with uptime guarantees.
- Hospitals:Acute care discharge planning drives short-term wheelchair and walker rentals through durable medical equipment dealer networks in United States markets.
Disabled individuals anchor premium pricing tiers. Rehabilitation centers are gaining share fastest as institutional procurement rationalization concentrates volume.
Distribution Channel:
Volume concentration favors medical supply stores and pharmacies for standard mobility aids, while direct sales and online retail capture complex prescription equipment and private-pay premium segments.
- Online Retail:Specialized durable medical equipment platforms bypass traditional dealer markups for standard walkers and canes in United States and United Kingdom markets. Regulatory constraints limit powered wheelchair sales to prescription-verification workflows.
- Medical Supply Stores:Local dealer networks maintain fitting and service capabilities for Medicare and Medicaid reimbursement in United States states with competitive bidding program participation.
- Pharmacies:Retail pharmacy chains in Germany and France stock entry-level canes and basic walkers for immediate patient discharge needs.
- Direct Sales:Manufacturer-employed assistive technology specialists conduct home assessments for complex powered seating systems in private-pay channels across North America and Western Europe.
Medical supply stores retain the volume base. Online retail is climbing the fastest as platform specialization erodes traditional dealer intermediation.
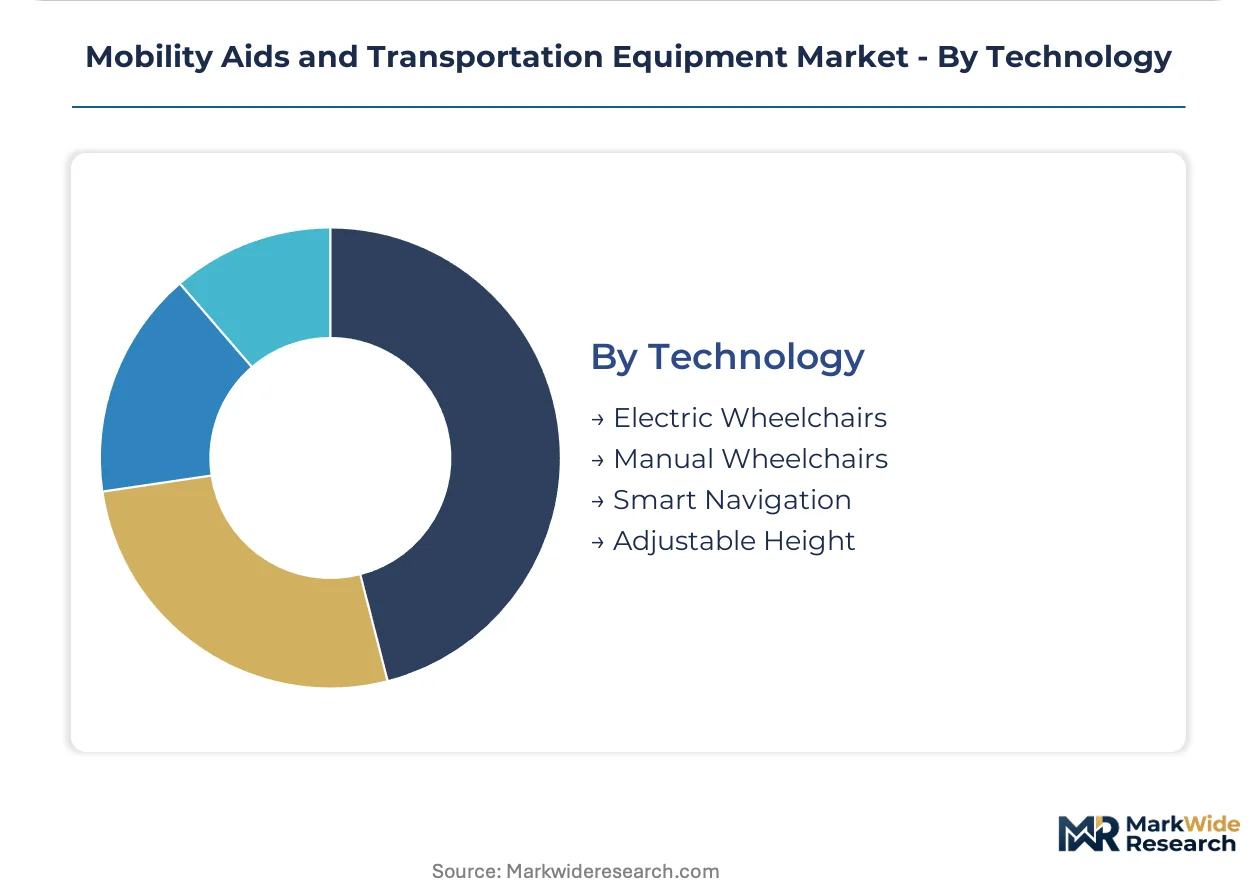
Technology:
Supply concentration in precision brushless DC motors and lithium-ion cell manufacturing shapes which technology tiers achieve cost-competitive scale.
- Electric Wheelchairs:Programmable drive controls with lithium-ion battery systems above 25-kilometer range thresholds command premium pricing in community-access segments. EU MDR Class IIa reclassification extends notified body review timelines for new entrants.
- Manual Wheelchairs:Ultra-lightweight carbon fiber and standard aluminum configurations serve institutional procurement in emerging markets where reimbursement ceilings constrain capital outlays.
- Smart Navigation:LIDAR obstacle detection and autonomous indoor operation capabilities differentiate premium tiers for rehabilitation center and aged-care facility deployment.
- Adjustable Height:Powered seat elevation mechanisms enable reach and transfer functions that qualify for separate reimbursement coding in United States Medicare channels.
Manual wheelchairs maintain the volume foundation. Smart navigation is gaining share fastest as health system IT integration demands remote monitoring capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement channels. Institutional buyers in Japan and Germany absorb premium pricing for powered seating systems, while cash-purchasers in India and Mexico prioritize aluminum-frame manual wheelchairs under $200.
United States
Medicare Part B competitive bidding programs compress margins for standard walkers and manual wheelchairs. FDA 510(k) clearance timelines for powered mobility devices average 180 days. Rehabilitation centers in Florida and Arizona are consolidating vendor relationships under multi-year framework agreements with uptime guarantees.
Germany
Statutory health insurance covers assistive device costs with fixed reimbursement schedules that prevent premium capture. EU MDR Class IIa reclassification extends notified body review timelines for powered wheelchairs. Ottobock maintains significant manufacturing presence in Duderstadt, supplying carbon fiber chassis to municipal care facilities across Lower Saxony.
Japan
METI projects sustained demand pressure through 2040 as the 75-plus cohort exceeds 20 percent of total population. JIS T 9203 standards enforce wheelchair structural integrity requirements for transport safety. Municipal care facilities in Tokyo prefecture are replacing legacy fleets ahead of compliance deadlines.
China
Domestic manufacturers dominate aluminum-frame production for export markets. NMPA medical device registration requirements create compliance layering for foreign-powered wheelchair entrants. Manufacturing clusters in Zhejiang and Guangdong provinces supply manual wheelchair components to European and North American assemblers.
India
District-level disability welfare schemes remain underutilized for mobility aid distribution. Central government procurement through the Artificial Limbs Manufacturing Corporation channels volume to state hospitals. Distributor networks in Maharashtra and Karnataka are expanding to capture first-mover advantage before competitive saturation.
Mobility Aids and Transportation Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive stability across price tiers. Premium positioning concentrates among German and Swedish specialists with carbon fiber and programmable control expertise. Scale-driven North American manufacturers compete on aluminum-frame standardization and distribution density. Two dominant competitive moves are reshaping structure: institutional procurement consolidation forcing service-network investments, and direct-to-consumer platform emergence capturing margin from traditional dealer intermediation.
Among German-anchored specialists, Ottobock SE & Co. KGaA exemplifies the premium-tier archetype through prosthetic-adjacent carbon fiber expertise extending into ultra-lightweight chassis design. Sunrise Medical LLC occupies a position within the modular-platform segment, reducing SKU complexity across European rehabilitation channels. Invacare Corporation represents the vertically integrated North American model, leveraging in-house aluminum production to sustain margin control across distribution networks.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical LLC |
| Ottobock SE & Co. KGaA |
| Permobil AB |
| Medline Industries |
| Pride Mobility Products Corporation |
| Drive DeVilbiss Healthcare |
| Stryker Corporation |
| Hoveround Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements for lithium-ion battery cells lock in supply access and price visibility for powered wheelchair manufacturers, insulating production schedules from spot-market volatility while compressing margin buffers for competitors without similar contractual coverage. German statutory health insurance reimbursement schedules fix device tariffs regardless of feature sophistication, forcing manufacturers to absorb input cost fluctuations or divert volume toward private-pay channels.
Pricing Analysis
After-sales service revenue from spare parts and preventive maintenance contracts drives lifetime value for institutional procurement relationships. Three-tier pricing structure across premium programmable seating, standard aluminum-frame manual chairs, and economy basic walkers separates reimbursement-eligible prescription equipment from retail cash purchases. Cost compression in standard walkers intensifies as Medicare competitive bidding programs squeeze dealer markups. Rehabilitation centers exhibit lowest price sensitivity due to uptime guarantee requirements, while elderly self-purchasers in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Inventory lead times for brushless DC precision motors extend to sixteen weeks, constraining assembly flexibility for North American and European wheelchair manufacturers dependent on East Asian component specialists. Manufacturing concentration in China, Germany, and the United States shapes global supply availability, with aluminum frame fabrication drawing from Zhejiang province smelters and carbon fiber chassis production anchored in Duderstadt. Single-source vulnerability in motor controllers creates procurement risk. Distribution runs through durable medical equipment dealer networks for prescription channels, while direct-to-consumer platforms capture standard product segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 510(k) predicate accumulation and EU MDR technical file renewal obligations creates substantial switching costs for institutional purchasers.
For Market Incumbents: Shield market position by deepening service network density in metropolitan corridors where rehabilitation centers consolidate vendor relationships under multi-year framework agreements. Invest in backward integration into precision motor assembly to reduce single-source exposure from East Asian suppliers. Capture margin expansion through smart navigation module development that commands separate reimbursement coding. For New Entrants and Emerging Players: Lead with direct-to-consumer platform specialization for standard walkers and canes in United States and United Kingdom markets where traditional dealer intermediation creates price arbitrage opportunity. Target rural India district-level disability welfare schemes before competitive saturation establishes incumbent distributor relationships. Deploy telehealth-integrated fitting workflows to bypass scarce certified assistive technology professional concentration in urban academic medical centers. For Investors and Strategic Acquirers: Modular platform architecture specialists with demonstrated SKU reduction capabilities across European rehabilitation channels represent the most attractive acquisition target archetype. Long-term viability hinges on reimbursement policy continuity across national health technology assessment bodies. Monitor FDA 510(k) review timeline elongation for novel drive control interfaces as inflection indicator for commercialization velocity compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Technical File Renewal | Accelerates compliance investment concentration ahead of 2028 mandatory deadline for legacy CE certificates. |
| Smart Navigation Module Development | Creates premium-tier differentiation through LIDAR obstacle detection integration with programmable drive controls. |
| Direct-to-Consumer Platform Launch | Bypasses traditional durable medical equipment dealer markups in standard walker and cane segments. |
| Service Network Density Expansion | Satisfies institutional procurement committee uptime guarantee requirements under consolidated vendor frameworks. |
| Carbon Fiber Chassis Manufacturing Scale-Up | Captures lightweight equipment demand from municipal care facilities replacing legacy aluminum fleets. |
Methodological Framework
A spread of perspectives from rehabilitation center procurement directors, certified assistive technology professionals, durable medical equipment dealer operators, and lithium-ion battery supply specialists converged on the working assumptions underlying demand modeling. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body guidance documents, CMS Medicare reimbursement schedules, and METI transport-safety compliance records. Bottom-up patient population projections and top-down manufacturing capacity assessments were triangulated to establish volume baselines.
Segmentation dimensions modeled include product type classification, technology tier differentiation, end-user concentration patterns, and distribution channel structure across the analysis window. CAGRs were derived from fitted growth curves applied to historical procurement data and projected replacement cycle acceleration. Forecast inputs incorporated ISO 7176-19 crash-testing mandate compliance deadlines and lithium-ion energy density improvement trajectories.
Forecasts assume regulatory continuity in FDA 510(k) substantial equivalence determinations and EU MDR notified body review timelines; material policy shifts would require re-modeling. Reimbursement coding revisions by national health technology assessment bodies and aluminum alloy price volatility represent primary forecast revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Global Automotive Steering Torque Sensor Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Europe Automotive Connectors Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Bus and Coach Suspension Bearing Components Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Traffic Control Device Tape Market
Vehicle Components
Ceramic Ball Bearings Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Wheel Seals Market