
 Germany Automotive Composites Market | 2026-2036
Germany Automotive Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Composites Market Foresight
The EU Green Deal is shifting the cost-of-entry calculus for automotive composites suppliers in Germany, forcing material qualification cycles that favor capital-intensive players. BASF SE leverages its Ludwigshafen chemical complex to sustain captive resin supply chains for composite formulations. SGL Carbon SE anchors carbon fiber production through its Moses Lake and Meitingen facilities, competing on aerospace-grade technology transfer. Toray Industries, Inc. differentiates through its European CFRP prepreg operations, positioning Japanese process discipline against local rivals.
Automotive composites encompass fiber-reinforced polymer matrices—typically carbon, glass, or aramid fibers embedded in thermoset or thermoplastic resins—engineered to achieve specific strength-to-weight ratios exceeding 200 MPa per g/cm³ for structural load-bearing applications. These materials primarily serve vehicle weight reduction mandates while maintaining crashworthiness integrity. Glass fiber dominates volume consumption across passenger car underbody panels and bumper beams, where cost sensitivity limits carbon fiber penetration. Resin transfer molding leads manufacturing process adoption among OEMs seeking mid-volume production flexibility, though autoclave technology commands premium positioning for electric vehicle battery enclosures requiring void-free consolidation. Compression molding is accelerating fastest among tier-1 suppliers serving commercial vehicle aerodynamic components.
KBA enforces type-approval standards that dictate composite crash performance validation, while REACH compliance governed by ECHA restricts certain epoxy hardeners and surface treatments. The EU F-Gas Regulation further constrains process gases used in autoclave curing, reshaping equipment investment decisions. Stakeholders must monitor how the EU AI Act's quality-management requirements intersect with automated fiber placement inspection systems, as algorithmic process control becomes integral to certification documentation.
Market Dynamics
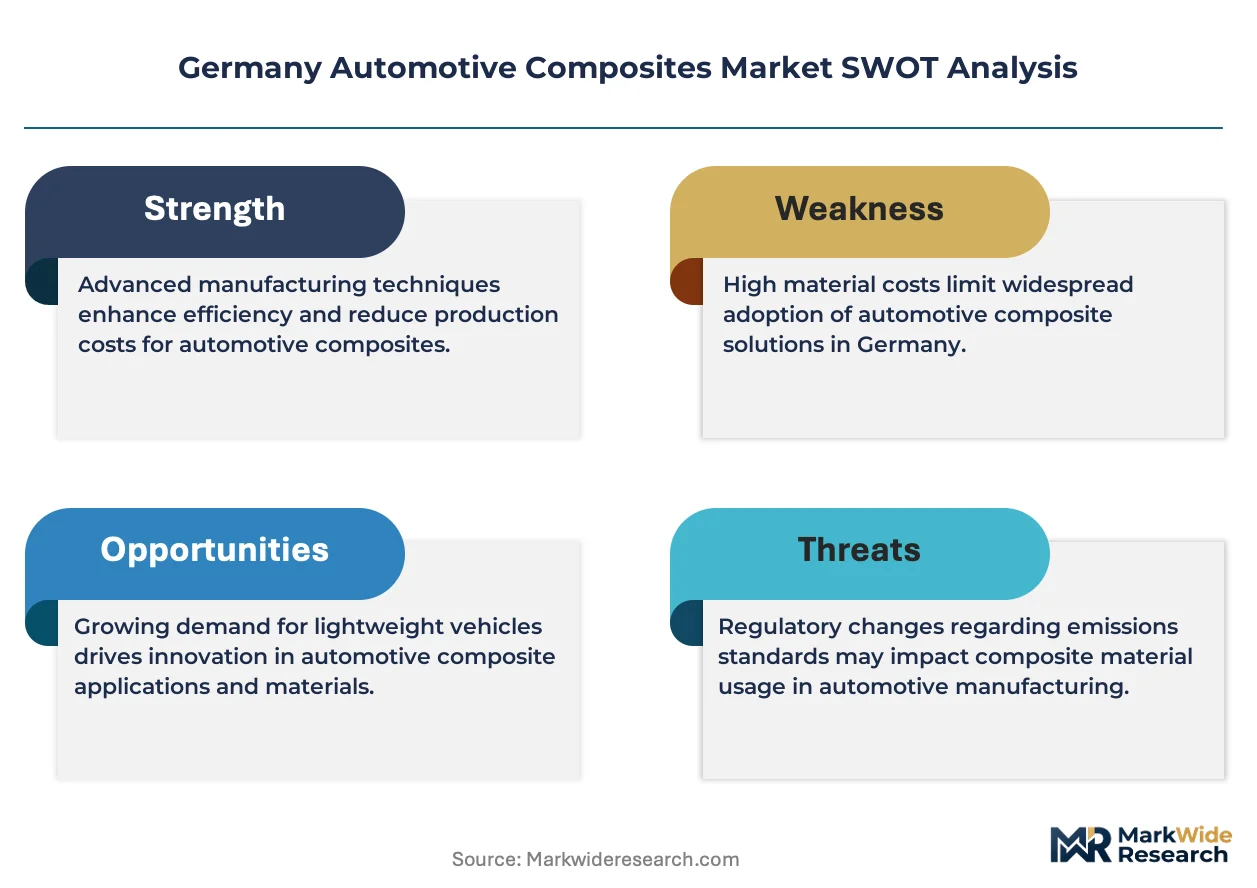
The EU Green Deal's emissions benchmarks are compressing vehicle design cycles, forcing OEMs to replace metal-intensive assemblies with fiber-reinforced polymer matrices that satisfy KBA crashworthiness validation while cutting kerb weight.
Growth Catalysts
- Electric vehicle platforms:Battery enclosure architectures demand lightweight structural components with specific strength-to-weight ratios exceeding 200 MPa per g/cm³, pulling carbon fiber into load-bearing applications previously reserved for steel.
- REACH compliance evolution:Restrictions on legacy epoxy hardeners are accelerating qualification of bio-based resin systems, creating first-mover advantage for suppliers with captive chemical synthesis capabilities.
- Bavaria's engineering corridor:Concentrated OEM R&D facilities and tier-1 supplier clusters enable rapid prototype-to-production cycles for composite-intensive vehicle programs.
Market Restraints
- Carbon fiber supply concentration:Precursor acrylonitrile availability and oxidation oven capacity constraints limit domestic production scaling, forcing dependence on Japanese and US filament sources.
- Autoclave curing energy intensity:The EU F-Gas Regulation constrains process gas selection, elevating capital costs for void-free consolidation equipment required by battery enclosure specifications.
- Aluminum extrusion substitution:Mature recycling infrastructure and lower per-kg cost position aluminum as the default lightweighting material for non-structural body panels.
Strategic Opportunities
- Baden-Württemberg supplier ecosystem:Mid-tier automotive engineering firms in Stuttgart and Karlsruhe present acquisition targets for resin formulation capabilities and automated fiber placement expertise.
- Thermoplastic composite welding:Induction bonding and ultrasonic assembly techniques are eliminating adhesive cure cycles, enabling line-speed integration with metal stamping operations.
- Commercial vehicle aerodynamics:Compression-molded glass fiber components for truck cab fairings and trailer skirts face less stringent crash certification than passenger car applications.
Industry Challenges
- Automated fiber placement programming:Shortage of technicians capable of converting CAD surfaces to machine-readable tow paths is extending commissioning timelines for new production cells.
- REACH-SCIP database compliance:Article 33 obligations for composite material disclosure across complex supply chains are generating administrative burden disproportionate to substance risk.
- Legacy paint shop integration:Composite substrate surface energy variations require dedicated primer systems, complicating mixed-material body-in-white sequences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Composites Market |
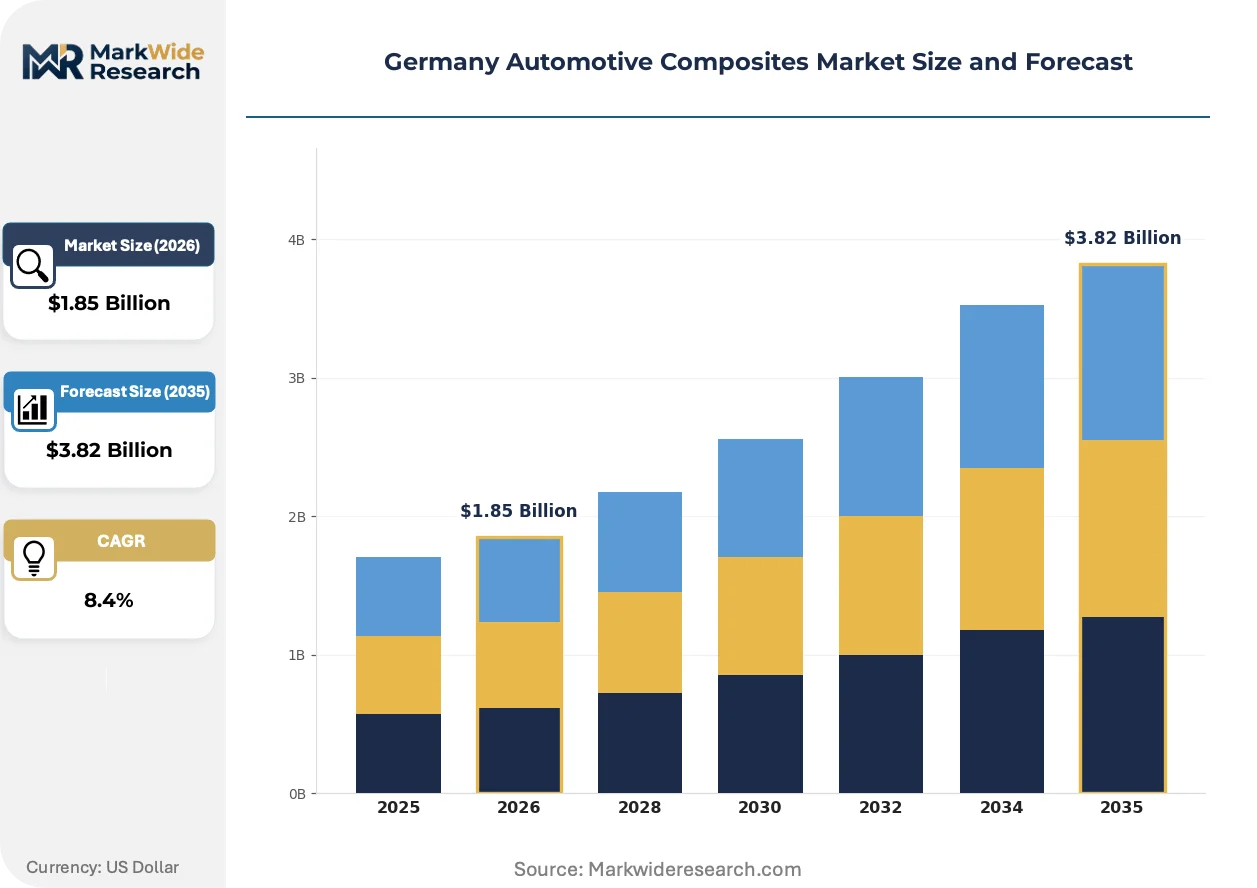
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbon Fiber, Glass Fiber, Aramid Fiber, Natural Fiber, Basalt Fiber Vehicle Class: Passenger Cars, Commercial Vehicles, Electric Vehicles, Two-Wheelers Manufacturing Process: Resin Transfer Molding, Compression Molding, Vacuum Infusion, Pultrusion, Autoclave Technology End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | BASF SE, SGL Carbon SE, Toray Industries, Inc., Teijin Limited, Hexcel Corporation, Solvay Group, Voith GmbH & Co. KGaA, Muhr und Bender KG, Cotesa GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Composites Market Shifts & Advancements
Thermoplastic resin matrices are displacing thermoset dominance in structural automotive applications, compressing cycle times and enabling post-forming recyclability that aligns with EU circular economy mandates.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are rewriting the economics of local reinforcement, allowing OEMs to place unidirectional strength exactly where load paths demand without committing entire components to carbon fiber cost structures. BMW and Mercedes-Benz have integrated these tapes into seat structures and front-end carriers, cutting blank complexity while maintaining stiffness targets. The technology is compressing the traditional trade-off between fiber volume fraction and production throughput.
The EU AI Act's quality-management requirements for high-risk industrial applications are reshaping automated fiber placement inspection protocols, mandating algorithmic traceability for defect detection decisions that feed into KBA type-approval documentation. Equipment suppliers are retrofitting deposition heads with embedded vision systems that generate auditable process parameter logs. Battery enclosure manufacturers face the steepest compliance burden given the safety-critical classification of electric vehicle energy storage systems.
Fleet procurement departments are consolidating composite component sourcing through long-term framework agreements that bundle material supply, part fabrication, and recycling take-back obligations. Tier-1 suppliers in Baden-Württemberg are responding by acquiring shredding and pyrolysis capabilities to close the loop on production scrap and end-of-life components. This behavioral shift is most pronounced in commercial vehicle segments where total cost of ownership calculations dominate specification decisions.
Germany Automotive Composites Market Segmentation
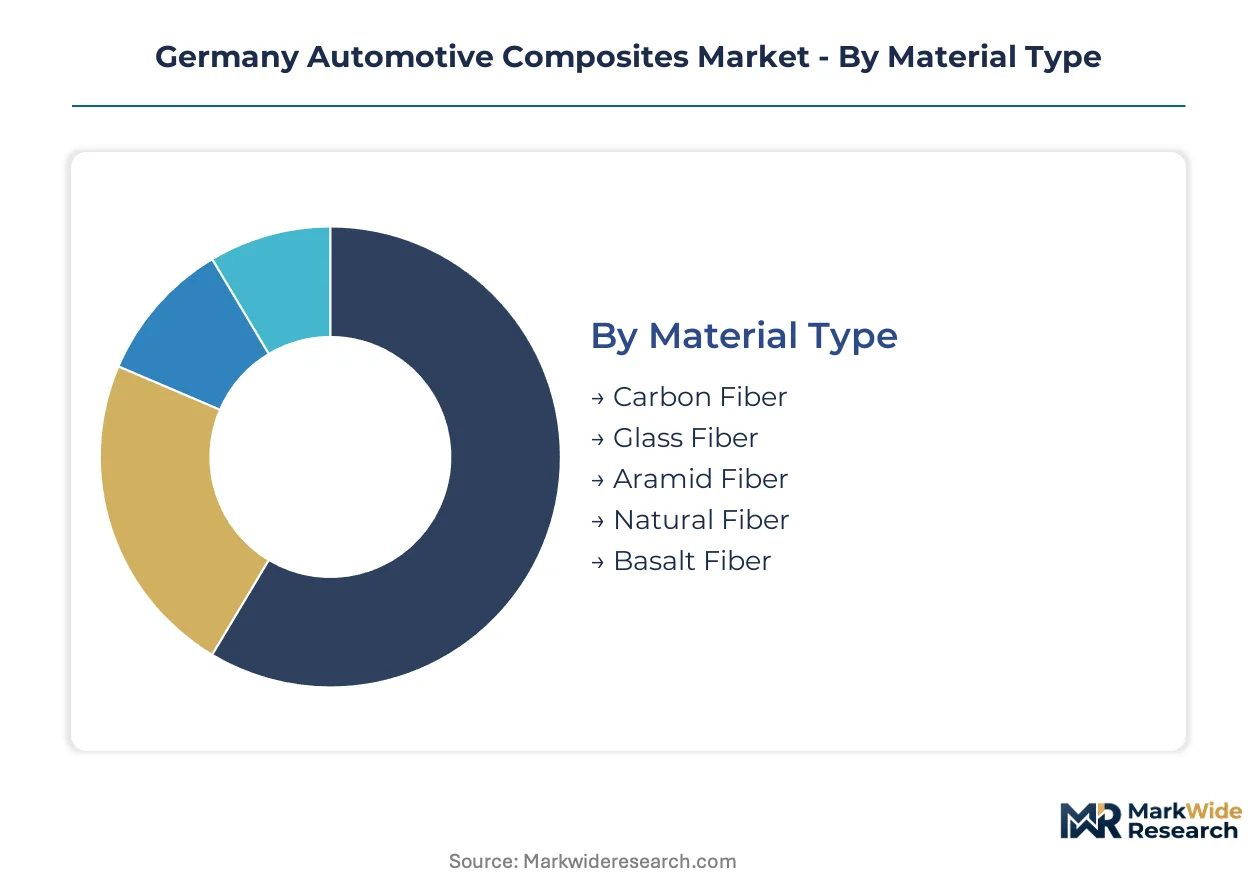
Segmentation in Germany's automotive composites market reveals how capital allocation, regulatory compliance, and manufacturing complexity intersect across material classes and process technologies. Each dimension carries distinct investment profiles and margin structures that determine supplier positioning.
Material Type:
Capital intensity varies dramatically across fiber categories, with precursor chemistry and oxidation infrastructure demanding the heaviest upfront commitments.
- Carbon Fiber:Polyacrylonitrile-based precursors undergo controlled oxidation and carbonization to achieve tensile strengths exceeding 3,500 MPa. Bavaria's OEM engineering corridors pull aerospace-grade material into battery enclosure applications where KBA crash certification mandates void-free consolidation. Precursor supply constraints and energy-intensive production limit domestic scaling.
- Glass Fiber:E-glass and S-glass variants dominate volume consumption through chopped strand mat and woven roving formats. Underbody panels and bumper beams across Baden-Württemberg supplier networks absorb the bulk of glass fiber tonnage, constrained by aluminum substitution in non-structural panels.
- Aramid Fiber:Para-aramid structures serve ballistic and high-temperature applications in limited automotive niches.
- Natural Fiber:Flax and hemp reinforcements address interior trim applications with lower mechanical requirements.
- Basalt Fiber:Intermediate properties between glass and carbon position basalt for cost-sensitive structural trials.
Glass fiber absorbs the bulk of installed capacity; carbon fiber is expanding most quickly among premium electric vehicle platforms.
Vehicle Class:
Application complexity and certification burden segment demand by how aggressively weight reduction targets override cost discipline.
- Electric Vehicles:Battery enclosure architectures and structural battery pack integration drive carbon fiber penetration into load-bearing assemblies previously reserved for steel. The EU Green Deal's emissions benchmarks compress design cycles, forcing material qualification at unprecedented speed.
- Commercial Vehicles:Compression-molded glass fiber aerodynamic components face less stringent crash certification than passenger applications. Fleet procurement departments in Stuttgart and Karlsruhe consolidate sourcing through framework agreements bundling fabrication and recycling obligations.
- Passenger Cars:Mixed-material body-in-white sequences complicate paint shop integration due to surface energy variations.
- Two-Wheelers:Limited composite adoption outside premium motorcycle fairings and electric scooter battery housings.
Electric vehicles command the steepest material qualification investment; commercial vehicles deliver the most predictable volume contracts.
Manufacturing Process:
Equipment amortization and energy intensity separate process technologies by viable production scale and part complexity.
- Autoclave Technology:Vacuum-bag consolidation under elevated temperature and pressure achieves aerospace-grade void content below 1%. Battery enclosure specifications for electric vehicle platforms mandate this precision, though EU F-Gas Regulation constraints elevate capital costs for process gas selection.
- Resin Transfer Molding:Closed-mold injection of thermoset resins enables mid-volume production flexibility with cycle times competitive for structural automotive components. OEMs favor RTM for A-surface body panels requiring Class A finish capability.
- Compression Molding:Thermoplastic and thermoset sheet molding compound processes accelerate fastest among tier-1 suppliers serving commercial vehicle aerodynamics.
- Vacuum Infusion:Open-mold resin distribution suits large-area components with moderate structural requirements.
- Pultrusion:Continuous profile production serves bumper beams and structural reinforcements with consistent cross-sections.
Resin transfer molding holds the broadest installed base; compression molding is climbing the fastest on thermoplastic composite adoption.
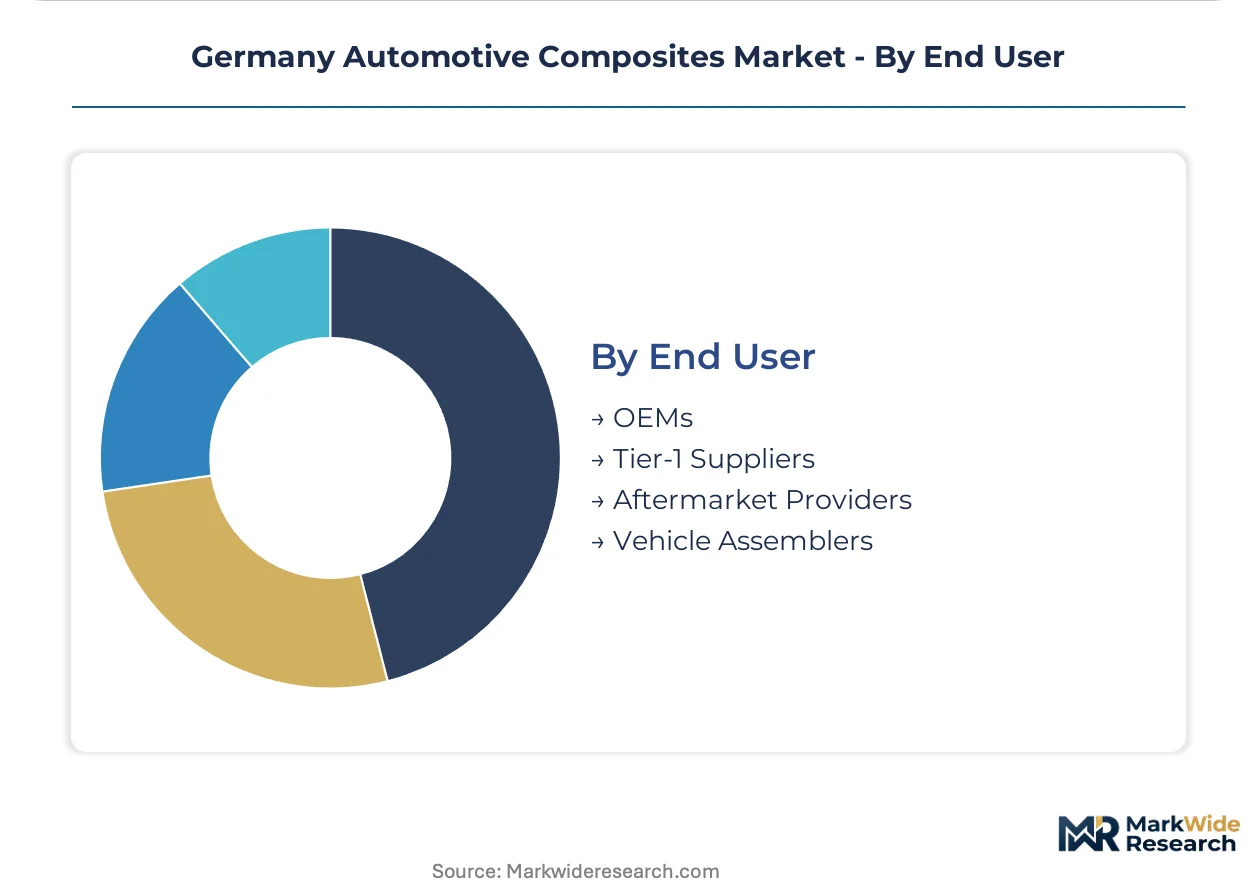
End User:
Supply chain position determines technical capability requirements and exposure to OEM direct sourcing pressure.
- Tier-1 Suppliers:Baden-Württemberg engineering firms integrate automated fiber placement, resin formulation, and recycling capabilities to defend position against OEM insourcing. REACH-SCIP database compliance obligations generate administrative burden disproportionate to substance risk across complex supply chains.
- OEMs:BMW and Mercedes-Benz internal composite centers control strategic material qualification and intellectual property for battery enclosure architectures.
- Aftermarket Providers:Limited to aesthetic body kits and replacement panels without structural certification requirements.
- Vehicle Assemblers:Contract manufacturers lack captive composite expertise, sourcing through tier-1 intermediaries.
Tier-1 suppliers concentrate the most integrated technical capabilities; OEM direct sourcing is gaining share fastest in safety-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for automotive composites concentrates in Germany's southern industrial belt, where OEM engineering centers and tier-1 supplier networks cluster within 200 kilometers of Stuttgart and Munich. The EU Green Deal's emissions benchmarks are compressing vehicle design cycles across all manufacturing regions, forcing localized material qualification investments.
Bavaria
BMW's Munich engineering headquarters and Ingolstadt production complexes pull carbon fiber into battery enclosure architectures requiring KBA crash certification. The state's High-Tech Strategy funds automated fiber placement research at Fraunhofer institutes. Suppliers cluster around Landshut and Dingolfing, where resin transfer molding cells serve electric vehicle platform launches.
Baden-Württemberg
Mercedes-Benz Sindelfingen and Porsche Zuffenhausen operations drive specification of thermoplastic composite tapes for structural reinforcement. REACH-SCIP database compliance obligations burden Stuttgart-based tier-1 suppliers managing complex material disclosure chains. Karlsruhe's polymer research institutes accelerate bio-based resin qualification cycles.
North Rhine-Westphalia
Ford Cologne and Opel Rüsselsheim facilities anchor glass fiber demand for passenger car underbody panels and bumper beams. The state's chemical industry corridor around Leverkusen and Dormagen supplies epoxy formulations constrained by ECHA hardener restrictions. Recycling infrastructure for production scrap is consolidating around Düsseldorf logistics hubs.
Lower Saxony
Volkswagen Wolfsburg headquarters specifications cascade through supplier networks for compression-molded commercial vehicle components. The EU F-Gas Regulation constrains autoclave process gas selection at Braunschweig aerospace technology transfer facilities. Hanover's commercial vehicle OEMs consolidate aerodynamic component sourcing through framework agreements bundling fabrication and recycling.
Hesse
Opel Rüsselsheim and supplier engineering centers drive mid-volume resin transfer molding adoption for A-surface body panels. Frankfurt's materials testing laboratories validate composite crash performance for KBA type-approval documentation. Darmstadt's technical universities feed automated fiber placement programming talent into regional production cells.
Germany Automotive Composites Market Competitive Landscape
German chemical conglomerates anchor one tier; Japanese carbon fiber specialists hold advanced material positioning. The supplier base stratifies between capital-intensive resin formulators with captive synthesis capabilities and fiber producers dependent on precursor supply chains. Three archetypes dominate: integrated chemical-resin compounders, aerospace-grade carbon fiber manufacturers, and tier-1 automotive fabricators with automated placement expertise. Competitive moves concentrate on backward integration into precursor supply and acquisition of thermoplastic welding technology.
Within the integrated chemical tier, BASF SE exemplifies resin formulation dominance through Ludwigshafen complex operations. SGL Carbon SE and Toray Industries, Inc. occupy positions spanning carbon fiber production and composite material supply, representing the fiber-specialist archetype against local chemical rivals. These three anchors illustrate how material qualification barriers favor players with captive upstream control.
| Leading Market Players |
|---|
| BASF SE |
| SGL Carbon SE |
| Toray Industries, Inc. |
| Teijin Limited |
| Hexcel Corporation |
| Solvay Group |
| Voith GmbH & Co. KGaA |
| Muhr und Bender KG |
| Cotesa GmbH |
| Others |
Supply & Pricing Matrix
Acrylonitrile precursor feedstock indices cascade through three distinct pricing tiers in Germany's automotive composites sector, compressing margins for carbon fiber converters while elevating premium-grade resin formulations. Bavarian OEM procurement teams leverage long-term offtake agreements to lock in aerospace-grade fiber allocations, forcing tier-1 suppliers in Baden-Württemberg to absorb spot market volatility in glass fiber rovings.
Pricing Analysis
High-volume glass fiber components trade on razor-thin unit economics while carbon fiber structural assemblies command substantial premiums tied to KBA crash certification tiers. Price differentiation hinges on void-free consolidation grades for battery enclosures and REACH-compliant bio-resin formulations. Cost compression in standard-grade chopped strand mat intensifies as Chinese filament sources displace European E-glass suppliers. Fleet procurement departments at commercial vehicle OEMs exhibit highest price sensitivity, whereas BMW and Mercedes-Benz platform engineering teams prioritize performance-grade CFRTP tapes regardless of per-kilogram premiums.
Supply Chain Analysis
Dual-sourcing mandates from KBA type-approval protocols force OEMs to qualify at least two precursor suppliers for safety-critical battery enclosure programs. Raw material flows draw from Japanese carbon fiber filaments, US oxidation oven capacity, and domestic Ludwigshafen resin synthesis operations. Single-source vulnerability concentrates in aerospace-grade PAN precursor supply, where Toray and SGL Carbon control filament specifications. Distribution runs through just-in-time cells at Landshut and Dingolfing, with scrap recycling loops closing through pyrolysis facilities in Stuttgart and Karlsruhe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's automotive composites sector sits at a thermoplastic transition inflection, with CFRTP tape technology displacing legacy thermoset autoclave curing across structural load-bearing applications.
For Market Incumbents: Acquire automated fiber placement programming capabilities and thermoplastic welding expertise to defend against OEM insourcing of battery enclosure fabrication. SGL Carbon SE and BASF SE must deepen backward integration into bio-based resin synthesis before REACH hardener restrictions tighten. Certification investment in EU AI Act-compliant vision systems for defect traceability represents the critical defensive lever against tier-1 supplier consolidation. For New Entrants and Emerging Players: Begin with compression-molded commercial vehicle aerodynamics in Lower Saxony, where fleet framework agreements bundle fabrication and recycling obligations without passenger car crash certification burdens. Target mid-tier engineering firms in Karlsruhe lacking automated fiber placement talent. A go-to-market angle anchored on induction bonding line-speed integration with metal stamping operations bypasses adhesive cure cycle bottlenecks. For Investors and Strategic Acquirers: The window for entry favors resin formulators with captive chemical synthesis and thermoplastic composite welding IP. Long-term viability hinges on circular economy positioning through pyrolysis-based carbon fiber recovery. The signal to watch is EU F-Gas Regulation enforcement intensity, which would accelerate capital equipment replacement cycles and strand legacy autoclave assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive PAN oxidation capacity insulates SGL Carbon against Japanese filament price volatility. |
| Thermoplastic Composite Welding Acquisition | Induction bonding expertise enables line-speed parity with metal stamping at BMW Munich. |
| Bio-Based Resin Qualification Acceleration | REACH-compliant hardener systems secure first-mover advantage for BASF Ludwigshafen formulations. |
| Automated Fiber Placement Talent Acquisition | Programming capabilities compress commissioning timelines for new production cells at Dingolfing. |
| Pyrolysis Recycling Infrastructure Buildout | Scarp recovery loops satisfy fleet procurement bundling requirements in Stuttgart commercial vehicle networks. |
Research Methodology
Trade databases, KBA type-approval filings, and ECHA REACH registration records formed the secondary backbone, cross-referenced against primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, Fraunhofer institute composite researchers, and automotive recycling facility operators. Bottom-up and top-down triangulation validated material flow estimates across Bavaria and Baden-Württemberg production clusters.
Bottom-up modeling aggregated vehicle production forecasts by propulsion architecture and content-per-vehicle assumptions for structural composite penetration, while top-down analysis calibrated aggregate market sizing against chemical industry resin shipment data. Segmentation dimensions spanned fiber type, manufacturing process technology, vehicle class, and end-user supply chain position. CAGRs derived from regression analysis of historical qualification cycle compression and electric vehicle platform launch timelines, with sensitivity testing against EU Green Deal emissions benchmark stringency.
Carbon fiber precursor supply disruptions, EU F-Gas Regulation enforcement intensity, and thermoplastic welding technology adoption velocity are the dominant revision risks. Deviation in REACH-SCIP database compliance burden would shift supplier consolidation patterns and margin structures materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Auto Fender Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
France Automotive Market
Automotive Components
Automotive Retarders Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Metal Timing Chain Market