
 Vehicle Trailer Hitch Market | 2026-2036
Vehicle Trailer Hitch Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Trailer Hitch Market Analysis
Market Dynamics
Class IV and V heavy-duty rating upgrades is redrawing competitive boundaries in the vehicle trailer hitch market. CURT Manufacturing LLC leverages its vertically integrated stamping and powder-coating operations to dominate the North American aftermarket channel. Horizon Global Corporation sustains broad retail distribution across multiple continents through its portfolio of brands. B&W Trailer Hitches anchors premium positioning with its made-in-USA forged steel tow & stow line.
Product Architecture
A vehicle trailer hitch is a structural coupling device, typically fabricated from SAE J684-certified steel with specified tongue weight and gross trailer weight ratings, designed to connect a tow vehicle to a towed load for cargo transport, recreational hauling, or commercial freight. Receiver hitches lead volume due to universal compatibility with 1.25-inch and 2-inch square tube dimensions, while fifth wheel hitches command the highest margin pools in the RV and heavy-haul segments. Steel remains the dominant material specification, though aluminum competes aggressively in corrosion-sensitive coastal and salt-belt applications.
Regulatory Environment
NHTSA governs tow rating disclosure and rear-impact compatibility under FMVSS regulations, while SAE International maintains J684 performance standards for hitch geometry and testing protocols. The EPA's evolving emissions frameworks for light-duty trucks indirectly shape tow vehicle availability and specification trends. Stakeholders must monitor pending revisions to SAE testing load cycles and state-level trailer brake requirements that could alter minimum hitch class thresholds.
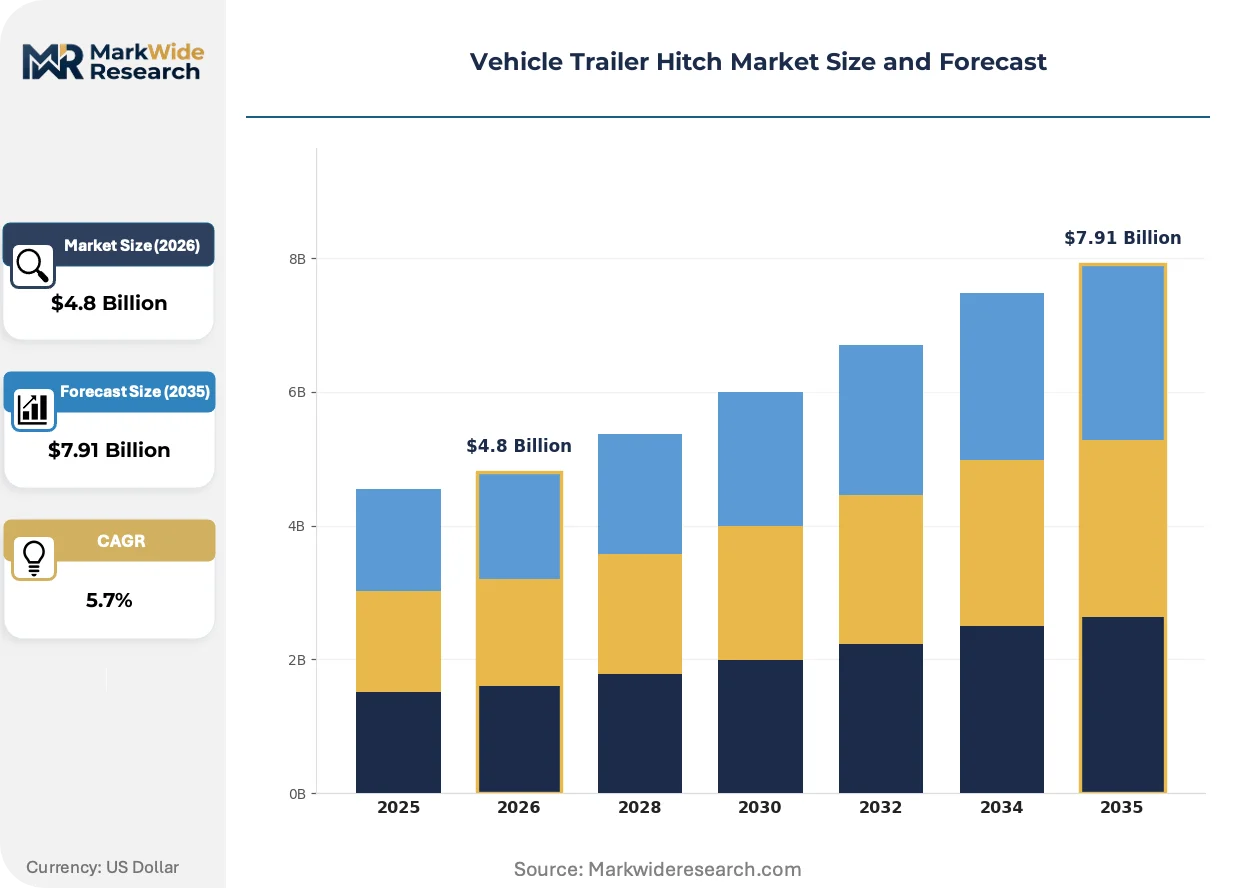
Market Dynamics
Class IV and V heavy-duty rating upgrades are redrawing competitive boundaries in the vehicle trailer hitch market. NHTSA Federal Motor Vehicle Safety Standards now mandate stricter crash compatibility and lighting integration for towed configurations, forcing manufacturers to redesign receiver geometries and test protocols.
Growth Catalysts
- Recreational Towing Surge:RV owners and outdoor enthusiasts in the United States sustain demand for Class III-V hitch receivers. Interstate hauling patterns and pickup truck culture expand the installed base.
- FMVSS Compliance Mandates:NHTSA regulations requiring rear-impact compatibility and tow rating disclosure push fleet operators toward certified SAE J684-compliant installations.
- Aluminum Alloy Adoption:Corrosion-resistant aluminum hitches gain traction in coastal and salt-belt applications where steel degradation accelerates replacement cycles.
Market Restraints
- Steel Price Volatility:SAE J684-certified steel input costs fluctuate with scrap metal and energy markets, compressing margins on economy-tier receiver production.
- Supplier Concentration Risk:North American powder-coating and stamping capacity clusters in the Midwest, creating geographic vulnerability to regional logistics disruptions.
- Technical Load Rating Ceilings:Current Class V receiver designs face structural limits near 20,000 pounds gross trailer weight, constraining heavy-haul expansion without fifth-wheel conversion.
Strategic Opportunities
- Underpenetrated Coastal Markets:Florida and Gulf Coast states show aluminum hitch penetration below national averages due to late adoption of corrosion-resistant specifications.
- Integrated Trailer Brake Controllers:Convergence of electronic brake control modules with receiver-mounted wiring harnesses creates premium retrofit opportunities for late-model truck owners.
- IRA Commercial Vehicle Incentives:Federal tax credits for electric and hybrid truck purchases indirectly expand addressable hitch demand as fleet electrification proceeds.
Industry Challenges
- Welding Certification Bottlenecks:AWS D1.1 structural welding qualifications for hitch fabrication face 12-16 week backlogs at accredited testing facilities.
- SAE J684 Revision Uncertainty:Pending updates to load cycle testing protocols force manufacturers to maintain dual tooling configurations during standards transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Trailer Hitch Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Receiver Hitches, Gooseneck Hitches, Fifth Wheel Hitches, Bumper Hitches End User: Recreational Users, Commercial Transport, Fleet Operators, Construction Services Installation Type: OEM, Aftermarket, DIY, Professional Installation Material: Steel, Aluminum, Composite, Plastic |
| Companies Covered | Bosal ACPS, Brink Group, Horizon Global Corporation, GDW Group, Tow-Trust Towbars Ltd, CURT Manufacturing LLC, AL-KO (Sawiko), Andersen Hitches, B&W Trailer Hitches, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Trailer Hitch Market Emerging Trajectories
Active integration of smart towing technologies and advanced materials is compressing traditional product lifecycles. Manufacturers now compete on connected diagnostics and modular receiver architectures rather than static load ratings alone.
Forged aluminum-magnesium alloys are displacing stamped steel in mid-duty receiver applications. Coastal fleet operators and marine towing services in Florida and California have shifted procurement toward these specifications since 2023. The transition is compressing steel-dominated supply chains while elevating foundry capacity requirements for squeeze-cast structural components.
NHTSA's pending updates to FMVSS rear-impact testing protocols will mandate enhanced energy absorption in receiver-mounted bumper systems. Hitch manufacturers must redesign crush zones and mounting geometries to maintain compliance. The RV and heavy-haul segments face the steepest re-engineering costs due to higher mass trailers in their typical configurations.
Direct-to-installer procurement through mobile service platforms is fragmenting traditional distributor channels. Independent automotive service technicians in Texas and Arizona now source hitches through app-based supply networks rather than brick-and-mortar jobbers. This shift compresses inventory holding at the wholesale tier while demanding same-day fulfillment capabilities from manufacturers.
Vehicle Trailer Hitch Market Segmentation
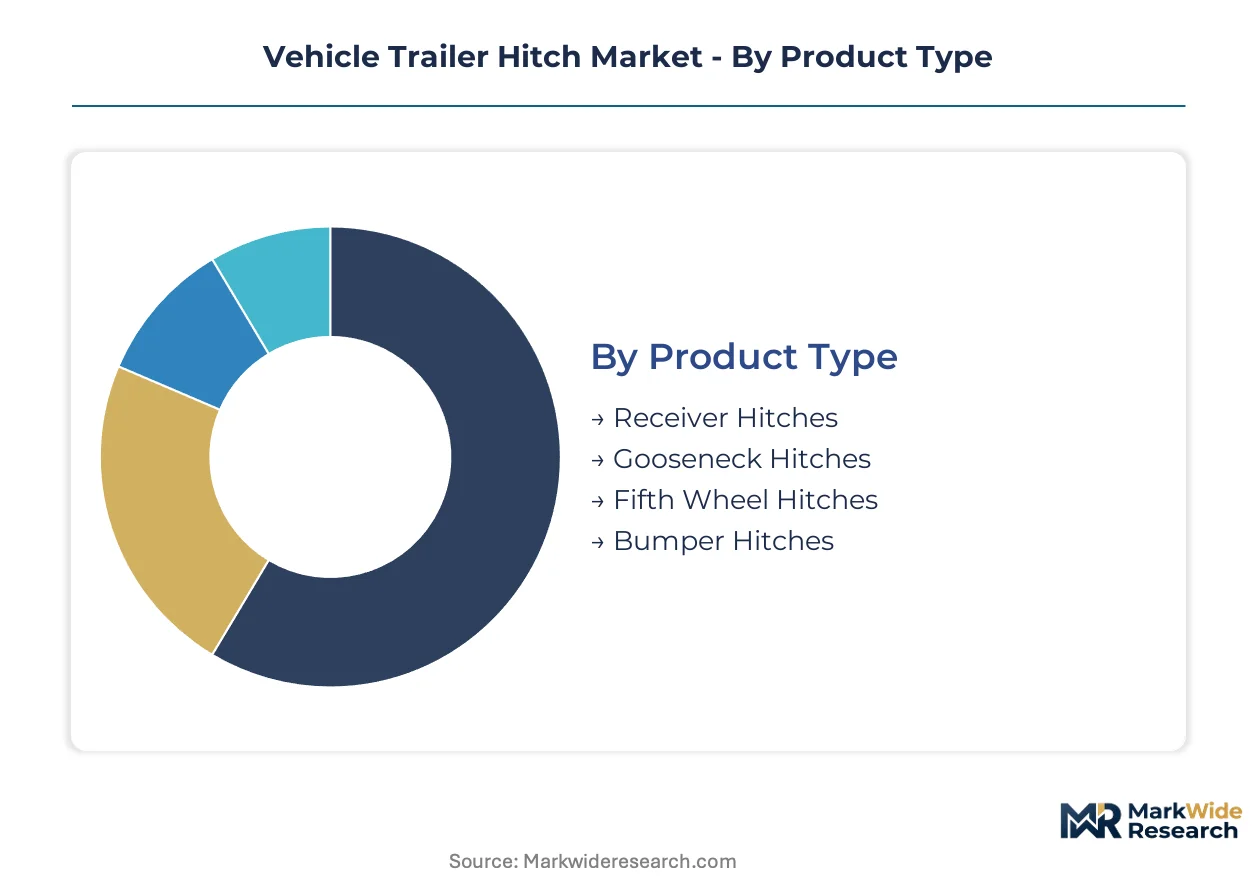
Vehicle trailer hitch segmentation reveals distinct channel economics across product architectures and customer workflows. Installer networks, retail distributors, and direct-to-consumer platforms each favor specific configurations based on technical complexity and buyer sophistication.
Product Type:
Receiver hitches and fifth wheel configurations dominate aftermarket volume through distinct channel pathways, while gooseneck and bumper variants serve narrower application sets with specialized distribution requirements.
- Receiver Hitches:These square-tube couplings in 1.25-inch and 2-inch dimensions anchor the replacement parts channel. Fleet maintenance departments in Texas and California standardize on Class III-V receiver ratings for light-duty commercial hauling. Demand concentrates through auto parts retailers and mobile installer networks serving suburban pickup truck owners.
- Fifth Wheel Hitches:Heavy-duty pivoting couplers for RV and flatbed applications command premium positioning through specialized dealers. The RV aftermarket in Florida and Arizona drives specification upgrades as owners transition from travel trailers to larger fifth-wheel configurations. Installation complexity restricts this segment to certified professional channels.
- Gooseneck Hitches:Agricultural and livestock haulers in the Midwest favor these ball-mounted couplers for high-pivot towing stability.
- Bumper Hitches:Light-duty applications in the personal watercraft and utility trailer segments sustain this entry-level category.
By volume, receiver configurations lead. By growth pace, fifth wheel specifications are climbing the fastest as RV unit sales expand.
End User:
Customer type determines specification intensity and procurement rhythm, with commercial accounts demanding certified installations and recreational buyers prioritizing modularity.
- Recreational Users:RV owners and outdoor enthusiasts in Colorado and Utah drive seasonal demand spikes for Class III receiver upgrades. These buyers source through camping specialty retailers and online platforms with emphasis on weight-distribution compatibility.
- Commercial Transport:Regional freight operators in the Southeast standardize on SAE J684-certified Class IV and V hitches for flatbed and equipment trailer configurations. Procurement runs through fleet maintenance suppliers with volume pricing agreements.
- Fleet Operators:Municipal and utility vehicle pools in the Midwest specify corrosion-resistant aluminum variants for snowplow and generator trailer duty cycles.
- Construction Services:Equipment rental yards in Texas and Arizona favor heavy-duty gooseneck and fifth wheel installations for skid-steer and mini-excavator transport.
Commercial transport accounts generate the highest per-unit revenue. Recreational users represent the steepest expansion trajectory as outdoor participation rates climb.
Installation Type:
Installation modality shapes margin capture, with professional channels retaining hardware-plus-labor economics while DIY and direct-to-installer models compress traditional distributor roles.
- OEM:Factory-installed receiver packages on full-size trucks from Detroit manufacturers anchor fleet specification. These installations command design-in relationships with chassis engineering teams and multi-year supply agreements.
- Aftermarket:Independent automotive service centers and trailer specialty shops in Florida and California handle the majority of receiver upgrades. This channel faces fragmentation as mobile service platforms gain share.
- DIY:Bolt-on receiver installations for light-duty applications sustain retail auto parts volume through chains serving suburban pickup owners.
- Professional Installation:Welded fifth wheel and gooseneck configurations require AWS D1.1-certified fabrication, restricting this segment to specialized shops with structural welding capabilities.
Aftermarket channels move the most units. Professional installation is gaining share fastest as fifth wheel and heavy-haul specifications expand.
Material:
Material selection reflects corrosion exposure and weight sensitivity, with coastal geography and fleet fuel economy priorities driving specification divergence.
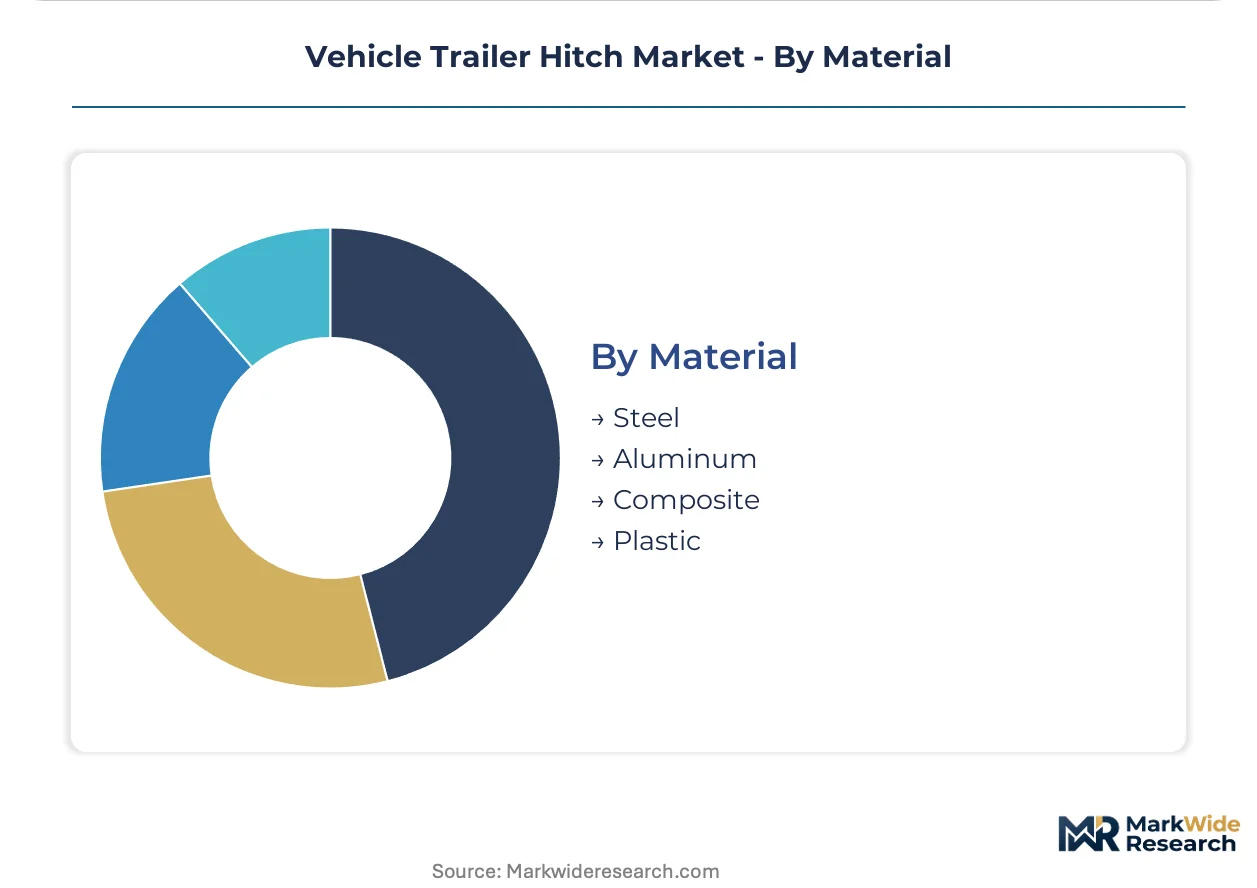
- Steel:SAE J684-certified carbon and alloy steel grades dominate interior and northern applications where salt exposure remains moderate. Stamping and powder-coating operations in Ohio and Indiana anchor this supply chain.
- Aluminum:Marine-grade aluminum-magnesium alloys displace steel in Florida, Gulf Coast, and California markets where salt corrosion accelerates replacement cycles. Foundry capacity constraints limit expansion.
- Composite:Glass-reinforced polymer prototypes target weight reduction for electric truck applications, though load rating certification remains pending.
- Plastic:Injection-molded receiver covers and cosmetic shrouds serve the accessories aftermarket with minimal structural function.
Steel retains volume leadership. Aluminum is expanding most quickly as coastal fleet operators accelerate corrosion-resistant procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in coastal corrosion zones show lowest price elasticity for aluminum specifications, while inland fleet operators remain highly sensitive to steel receiver costs. This demand-elasticity contrast shapes procurement patterns across major markets.
United States
Pickup truck culture and interstate hauling sustain the world's largest installed base of Class III-V hitch receivers. NHTSA FMVSS regulations mandate stricter crash compatibility and lighting integration for towed configurations. Manufacturing clusters in Ohio and Indiana anchor stamping and powder-coating operations for steel receiver production.
Germany
Precision engineering standards drive specification intensity for SAE J684-equivalent certified installations in commercial transport fleets. KBA vehicle type approval requirements govern tow rating disclosure and rear-impact compatibility. Industrial concentration in Bavaria and Baden-Württemberg supports specialized fabrication for heavy-duty gooseneck and fifth wheel configurations.
China
Domestic RV manufacturing expansion and agricultural mechanization create dual demand vectors for receiver and gooseneck specifications. MIIT vehicle certification protocols align with evolving GB standards for towing equipment. Yangtze River Delta foundry capacity is scaling to meet squeeze-cast aluminum-magnesium alloy requirements for corrosion-resistant applications.
Australia
Remote-area mining and livestock transport sustain premium demand for heavy-duty Class V ratings in extreme duty cycles. ADR design rules mandate compliance with SAE J684 testing protocols for aftermarket installations. Queensland and Western Australia equipment rental yards favor integrated trailer brake controller specifications for resource sector logistics.
Canada
Snowbelt fleet operators prioritize corrosion-resistant aluminum variants for municipal snowplow and generator trailer duty cycles. Transport Canada CMVSS regulations mirror NHTSA rear-impact compatibility requirements. Ontario-based powder-coating facilities serve cross-border supply chains for US Midwest distributor networks.
Vehicle Trailer Hitch Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the vehicle trailer hitch market. The vendor base organizes around three strategic tiers: vertically integrated stampers with captive coating operations, specialized forged-steel premium fabricators, and aluminum foundry-dependent corrosion specialists. Consolidation pressures concentrate in the Midwest stamping corridor while coastal markets fragment across aluminum supply chains. Dominant competitive moves include backward integration into raw steel and aluminum sourcing, plus geographic expansion through mobile installer platform partnerships.
Among North American fabricators, CURT Manufacturing LLC and B&W Trailer Hitches exemplify divergent archetype positioning. CURT represents the scale-driven, vertically integrated stamper model with Midwest production gravity. B&W occupies the premium-tier forged-steel specialist position with made-in-USA positioning. Horizon Global Corporation anchors the multi-brand portfolio archetype with broad retail distribution across multiple continents. European-based specialists including Brink Group and Bosal ACPS sit within the OEM design-in and type-approval competency cluster.
| Leading Market Players |
|---|
| Bosal ACPS |
| Brink Group |
| Horizon Global Corporation |
| GDW Group |
| Tow-Trust Towbars Ltd |
| CURT Manufacturing LLC |
| AL-KO (Sawiko) |
| Andersen Hitches |
| B&W Trailer Hitches |
| Others |
Supply Flow & Price Mechanics
SAE J684 certification requirements gate both supplier qualification and price tiering simultaneously, creating a dual-filter where only certified fabricators can access premium fleet contracts while uncertified producers compete solely on spot-price steel receiver sales to price-sensitive DIY channels.
Pricing Analysis
Aftermarket installation labor and warranty service bundles drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium forged-steel, standard stamped-steel, and economy imported specifications stratifies the market. Cost compression in economy-tier receiver production intensifies because Midwest stamping capacity faces energy and scrap metal volatility. Fleet operators exhibit lowest price sensitivity due to SAE J684 compliance mandates, while suburban DIY buyers drive aggressive price competition.
Supply Chain Analysis
Inventory cycles for powder-coated steel receivers stretch 8-12 weeks due to seasonal demand spikes ahead of summer towing season. Manufacturing gravity centers on Ohio and Indiana for stamped steel production, with Yangtze River Delta foundries scaling aluminum-magnesium squeeze-cast capacity. Raw material inputs draw from domestic scrap steel markets, imported aluminum billet, and specialized alloy formulations. Single-source vulnerability concentrates in Midwest powder-coating facilities serving cross-border distributor networks. Distribution runs through mobile installer platforms, auto parts retailers, and fleet maintenance suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AWS D1.1 welding certification backlogs and squeeze-cast aluminum foundry scarcity constrain expansion for would-be entrants, privileging incumbents with captive technical talent and existing supplier relationships.
For Market Incumbents: Consolidate Midwest stamping capacity through selective acquisition of distressed powder-coating operations to secure throughput during seasonal peaks. Deepen backward integration into scrap steel sourcing to buffer margin compression from commodity volatility. Anchor defensive positioning against aluminum foundry entrants by locking multi-year fleet supply agreements before coastal corrosion-resistant specifications fully displace steel.
For New Entrants and Emerging Players: Anchor in Florida and Gulf Coast aluminum hitch penetration gaps where salt-belt replacement cycles favor corrosion-resistant specifications over incumbent steel offerings. Target mobile installer platform partnerships in Texas and Arizona where app-based procurement fragments traditional distributor control. Pursue direct-to-installer fulfillment capabilities with same-day delivery guarantees to bypass wholesale inventory holdings.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive component parents seeking to divest non-core towing equipment divisions with stranded SAE J684 certification assets. Long-term viability hinges on electrified truck fleet expansion and IRA commercial vehicle incentives sustaining addressable demand growth. Monitor pending FMVSS rear-impact protocol revisions as inflection signal for re-engineering cost exposure among pure-play steel fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Steel Sourcing | Captive raw material supply buffers CURT Manufacturing and Horizon Global from commodity volatility. |
| Aluminum Foundry Capacity Expansion | Yangtze River Delta squeeze-cast investments enable B&W Trailer Hitches coastal market penetration. |
| Mobile Installer Platform Partnership | App-based procurement networks in Texas fragment traditional wholesale distributor economics. |
| SAE J684 Certification Investment | Dual tooling configurations during standards transition protect fleet contract eligibility. |
| Integrated Trailer Brake Controller Development | Convergence with receiver-mounted wiring harnesses captures premium retrofit opportunities. |
Methodological Framework
Operator-level perspectives from fleet maintenance directors, aftermarket service technicians, OEM platform engineers, and mobile installer network operators anchored the qualitative base. Primary interview findings triangulated against secondary sources including NHTSA FMVSS docket filings, SAE International standards documentation, vehicle production databases, and customs trade records for steel and aluminum inputs. Bottom-up channel volume estimates reconciled with top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested forecast robustness across steel price volatility scenarios, electrification adoption curves, and regulatory implementation timelines. Segmentation modeling incorporated product architecture, end-user type, installation modality, and material specification dimensions. CAGRs derived from regression-adjusted historical growth patterns and elasticity-weighted scenario outputs. Industry-specific inputs included RV unit sales trajectories, fleet electrification incentives, and coastal corrosion-driven replacement cycle acceleration.
Material uncertainties — pending SAE J684 load cycle revisions, aluminum foundry capacity constraints, and FMVSS rear-impact protocol finalization — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from regulatory, technological, or macroeconomic shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Cross Roller Bearings Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Advanced Driver Assistance System (ADAS) Sensor Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Wheel Loaders Market
Vehicle Components
Automotive Pyrofuse Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Idler Arm Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Child Seats Market
Vehicle Components
Brake Hoses Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market