
 Chassis Leveling Valves Market | 2026-2036
Chassis Leveling Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Chassis Leveling Valves Market Outlook
A widening capital-intensity gap between integrated brake system suppliers and standalone valve specialists is rotating competitive advantage toward firms with captive electronics and pneumatics capabilities. WABCO leverages its integrated air management portfolio to bundle leveling valves with braking and stability systems. Haldex sustains aftermarket channel density across European and North American distribution networks. Knorr-Bremse anchors its position through in-house production of solenoid controls and sensor modules for automated valve platforms.
Chassis leveling valves are pneumatic or electropneumatic devices that regulate air spring pressure to maintain consistent vehicle ride height under varying load conditions, typically operating within pressure ranges of 0 to 150 psi and response times under 200 milliseconds for electronic variants. Their primary commercial purpose is to protect driveline geometry, ensure headlight alignment compliance, and reduce frame stress in commercial vehicles with variable payload profiles. Electronic valve configurations command the strongest margin pools due to embedded sensor integration and software calibration requirements, while pneumatic variants retain volume dominance in emerging-market fleet retrofits. Aftermarket Providers represent the fastest-growing end-user channel as aging heavy-duty truck populations in North America and Europe extend replacement intervals.
The EPA and NHTSA in the United States, alongside the EU Green Deal and F-Gas Regulation in Europe, impose emissions and refrigerant leakage standards that indirectly tighten chassis system maintenance protocols and accelerate valve replacement cycles. China's MIIT enforces GB standards for commercial vehicle air suspension compatibility that condition market access for imported valve assemblies. Stakeholders must monitor how automated manual transmission integration and predictive load-sensing algorithms reshape specification requirements for next-generation height control modules.
Market Dynamics
Electronic height control architectures are compressing replacement cycles as fleet operators prioritize driveline protection and headlight compliance over extended pneumatic valve service intervals. The shift from mechanical to sensor-integrated systems concentrates procurement decisions among brake system integrators with captive electronics capabilities.
Growth Catalysts
- EPA Heavy-Duty Emissions Standards:Maintenance protocol tightening accelerates valve replacement in United States commercial fleets seeking inspection compliance and warranty preservation.
- Automated Manual Transmission Integration:Driveline geometry precision requirements elevate specification standards for electronic height control modules in long-haul tractor configurations.
- China Commercial Vehicle Production:GB standard enforcement for air suspension compatibility conditions market access and drives localized assembly demand.
Market Restraints
- Copper and Rare Earth Input Volatility:Solenoid coil and sensor module production faces margin compression from commodity price swings in electromagnetic component supply chains.
- Integrated Supplier Concentration:Brake system bundling reduces standalone valve specialist access to OEM specification channels in Germany and United States markets.
- Pneumatic Valve Substitution Ceiling:Emerging-market fleet retrofits retain mechanical systems due to technician familiarity and lower upfront hardware costs.
Strategic Opportunities
- Predictive Load-Sensing Convergence:Telematics integration with height control algorithms creates specification white space for valve suppliers with software calibration competencies.
- EU Green Deal Maintenance Mandates:Emissions-linked inspection protocols extend replacement demand into European aftermarket channels for aging heavy-duty populations.
- India Commercial Vehicle Fleet Expansion:Air suspension penetration in bus and truck segments opens volume potential for electropneumatic valve localization.
Industry Challenges
- Embedded Software Certification Timelines:Functional safety validation for electronic valve platforms extends development cycles and delays platform launches.
- Legacy Pneumatic System Integration:Retrofit compatibility requirements constrain electronic valve architecture decisions and fragment R&D resource allocation.
- Mechatronics Talent Scarcity:Combined pneumatics-electronics-software skill requirements outpace vocational training pipeline output in manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chassis Leveling Valves Market |
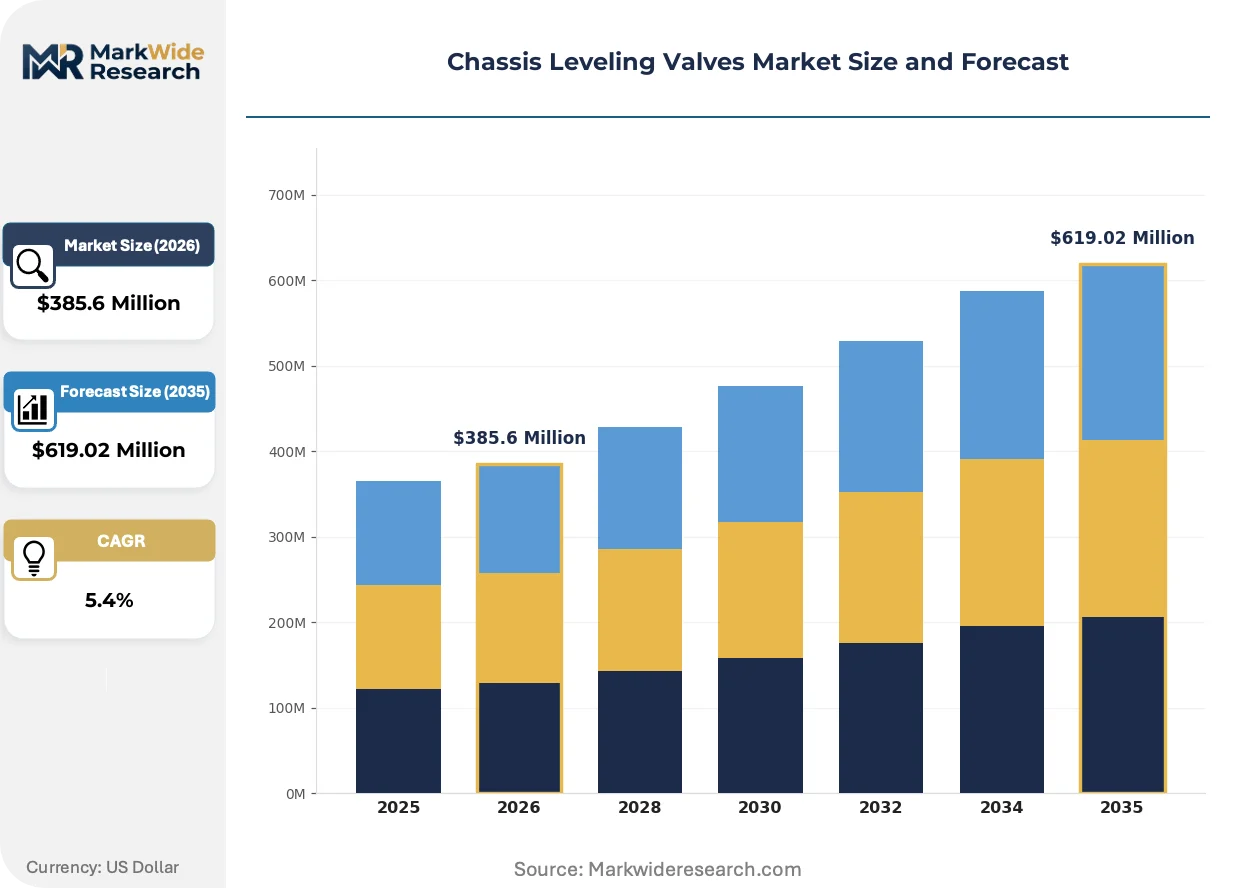
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Valve, Dual Valve, Electronic Valve, Pneumatic Valve End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Installation Type: On-Road, Off-Road, Heavy-Duty, Light-Duty Control Mechanism: Manual, Automatic, Remote Operated, Integrated |
| Companies Covered | Hendrickson, Haldex, ProVia, Ridewell Corporation, Hadley, Barksdale, WABCO, Knorr-Bremse, CoorsTek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chassis Leveling Valves Market Strategic Shifts
Sensor-integrated electronic valves are compressing the technology frontier as calibration software becomes the primary differentiation vector. Three developments are actively restructuring competitive requirements and procurement patterns.
Electropneumatic valve architectures with integrated pressure transducers and position feedback loops is supplanting purely mechanical height control in premium fleet specifications. North American long-haul operators are accelerating adoption to meet NHTSA headlight alignment mandates. The technology is compressing margins for standalone pneumatic specialists lacking embedded electronics capabilities.
REACH substance restrictions and EU F-Gas refrigerant leakage protocols are tightening chassis system maintenance documentation requirements across European commercial vehicle fleets. Inspection record retention obligations now extend to air suspension components including leveling valve replacement intervals. Aftermarket service networks in Germany and France are responding by certifying technician competencies in electronic valve diagnostics.
Fleet procurement departments are consolidating brake and air management system sourcing under single-supplier framework agreements. Traditional component distributors are losing specification influence as direct OEM-channel contracts capture electronic valve volumes. The concentration is most visible in United States heavy-duty truck manufacturing clusters where integrated brake suppliers control height control module allocation.
Chassis Leveling Valves Market Segmentation
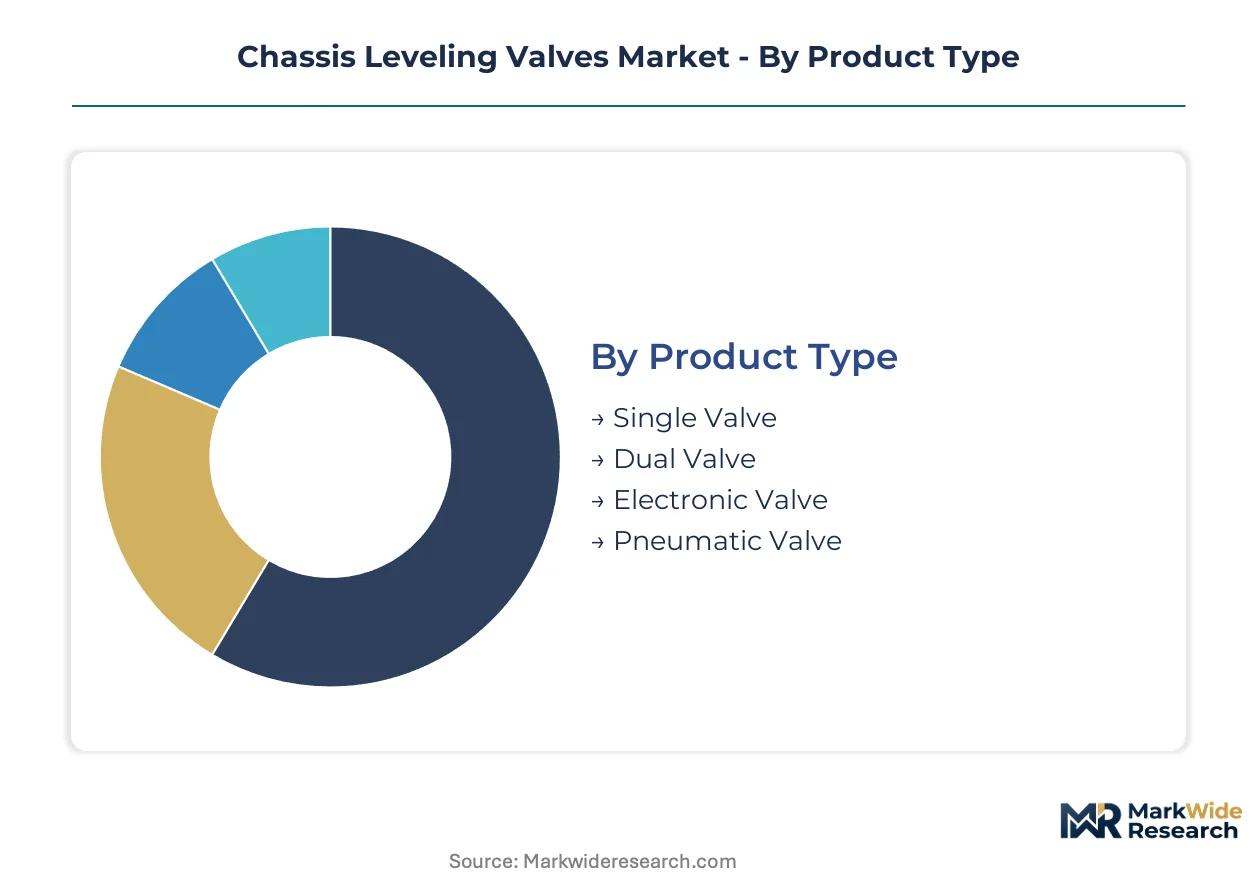
Segmentation in the chassis leveling valves market reveals divergent procurement patterns across product architectures and channel structures. Electronic valve configurations command premium positioning through embedded sensor integration, while pneumatic variants retain cost-driven volume in fleet retrofit applications. Understanding these divides enables suppliers to align R&D allocation with margin concentration zones.
Product Type:
Dual Valve and Electronic Valve segments concentrate in United States and German OEM supply chains where driveline precision mandates dominate specification sheets. Single Valve and Pneumatic Valve production serves emerging-market fleet operators through localized aftermarket channels in China and India.
- Electronic Valve:Sensor-integrated architectures with pressure transducers and position feedback loops operate below 200 millisecond response thresholds. Demand clusters in North American long-haul tractor configurations where NHTSA headlight alignment compliance drives specification upgrades. EPA emissions-linked maintenance protocols accelerate replacement cycles in United States commercial fleets.
- Pneumatic Valve:Purely mechanical height control devices utilizing diaphragm-actuated mechanisms without embedded electronics. Volume concentrates in China and India aftermarket retrofits where technician familiarity and lower hardware costs sustain mechanical system preference. GB standard enforcement for air suspension compatibility conditions import valve assembly market access.
- Single Valve:Basic height regulation units for single-axle applications in light-duty commercial vehicles.
- Dual Valve:Tandem-axle configurations providing independent pressure control for multi-axle suspensions in heavy-duty tractors.
Electronic Valve commands the established base. The steepest expansion runs through Pneumatic Valve retrofit demand in emerging-market fleet segments.
End User:
Fleet Operators and Aftermarket Providers drive margin expansion through recurring replacement demand, while OEMs and Vehicle Assemblers anchor volume concentration in new vehicle production corridors.
- Aftermarket Providers:Independent service networks and distributor channels supplying replacement valves for aging heavy-duty truck populations. Demand concentrates in United States and Germany where extended vehicle lifecycles and emissions inspection mandates sustain replacement interval compression. REACH documentation requirements and EU F-Gas refrigerant leakage protocols tighten maintenance record retention obligations across European fleets.
- Fleet Operators:Direct procurement by commercial vehicle owners prioritizing driveline protection and warranty preservation over extended service intervals. Large North American operators are consolidating brake and air management sourcing under framework agreements with integrated system suppliers. Predictive load-sensing algorithm integration creates specification white space for telematics-capable valve platforms.
- OEMs:Original equipment manufacturers specifying valves for new commercial vehicle production.
- Vehicle Assemblers:Contract assembly operations integrating leveling valves into completed chassis configurations.
Aftermarket Providers capture the replacement volume base. Fleet Operators are climbing the fastest through telematics-integrated procurement consolidation.
Installation Type:
Heavy-Duty and On-Road installations concentrate specification value in premium fleet segments, while Off-Road and Light-Duty applications fragment across regional equipment markets with divergent durability requirements.
- Heavy-Duty:Severe-service applications in long-haul trucking, construction, and mining equipment requiring sustained pressure tolerance above 120 psi. Demand anchors in United States manufacturing clusters where automated manual transmission integration elevates driveline geometry precision requirements. Copper and rare earth input volatility in solenoid coil production compresses margins for electromagnetic component supply chains.
- On-Road:Highway-legal commercial vehicle installations subject to federal safety and emissions inspection protocols. Specification standards tighten under EPA heavy-duty vehicle emissions standards and NHTSA safety mandates in United States markets. Electronic height control architectures displace mechanical systems in premium fleet configurations seeking inspection compliance.
- Off-Road:Agricultural, mining, and construction equipment applications with extreme duty cycles.
- Light-Duty:Delivery vans and small commercial vehicles with reduced payload variability profiles.
Heavy-Duty commands the specification premium base. On-Road is gaining share fastest through regulatory compliance acceleration.
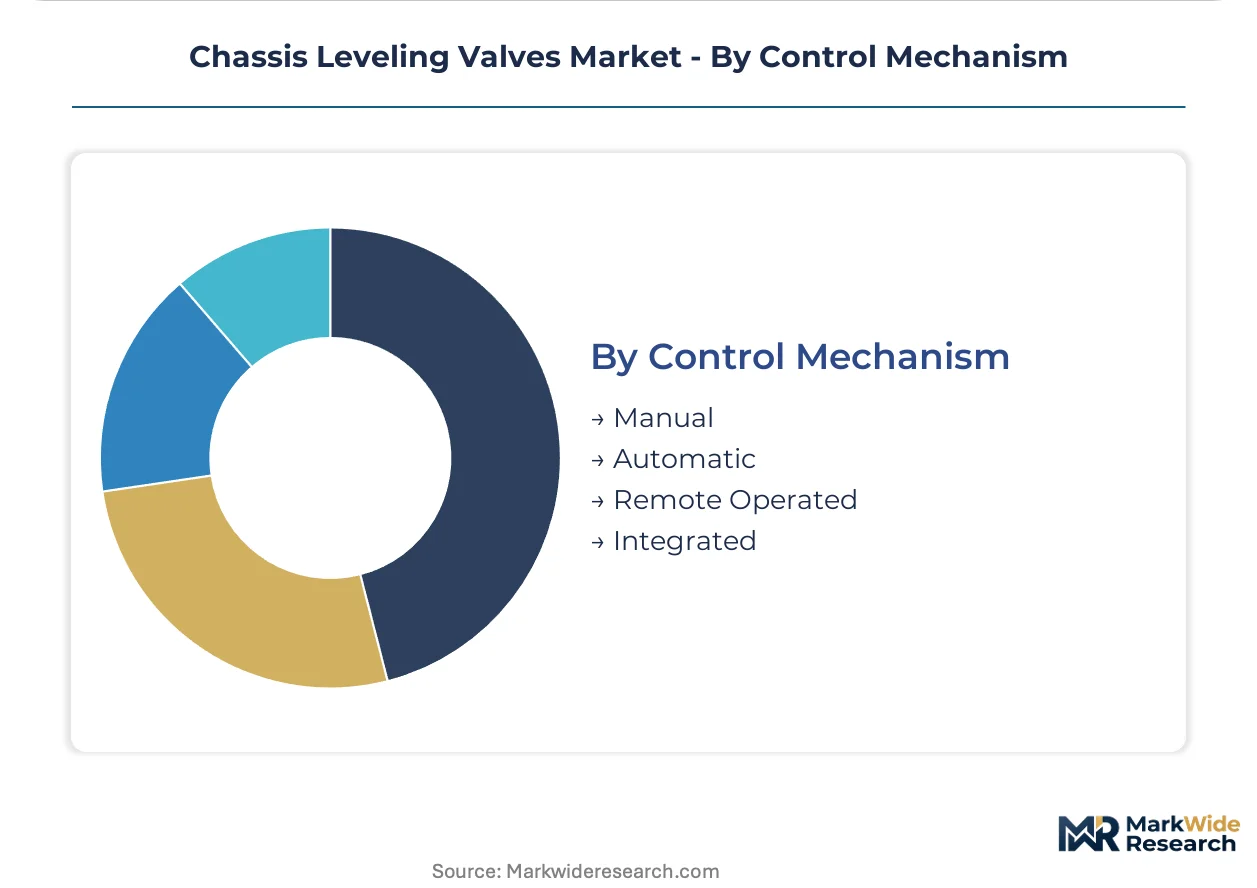
Control Mechanism:
Automatic and Integrated control systems concentrate development resources in brake system supplier R&D pipelines, while Manual and Remote Operated configurations retain niche positioning in specialized equipment segments.
- Integrated:Control modules embedded within broader brake and stability management systems with shared sensor networks and calibration software. Procurement concentrates among WABCO, Haldex, and Knorr-Bremse captive electronics capabilities in Germany and United States markets. Functional safety validation timelines extend development cycles and delay platform launches for embedded software certification.
- Automatic:Self-regulating height control responding to load changes without operator intervention. Adoption accelerates in European fleets under EU Green Deal maintenance mandates linking emissions performance to air suspension component inspection intervals. Mechatronics talent scarcity across pneumatics-electronics-software skill combinations constrains manufacturing expansion.
- Manual:Operator-actuated height adjustment through mechanical linkage or basic pneumatic switches.
- Remote Operated:Wireless or cab-mounted control interfaces for specialized vehicle configurations.
Integrated commands the technology frontier base. Automatic shows the steepest expansion trajectory through regulatory-linked maintenance mandate enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and United States manufacturing corridors where integrated brake suppliers bundle electronic height control modules, while emerging-market retrofit demand compresses margins in China and India where pneumatic valve volumes dominate aftermarket channels.
United States
Long-haul fleet operators drive specification upgrades for electronic height control systems to preserve driveline geometry under automated manual transmission integration. NHTSA headlight alignment mandates and EPA heavy-duty emissions standards accelerate replacement cycles in commercial vehicle populations. Manufacturing clusters in Michigan and Ohio anchor OEM supply chains for integrated brake and air management systems.
Germany
Commercial vehicle OEMs specify sensor-integrated electronic valves for premium tractor configurations serving pan-European logistics corridors. EU Green Deal maintenance mandates and REACH documentation requirements tighten inspection protocols for air suspension components. Industrial concentration in Baden-Württemberg and Bavaria sustains captive electronics capabilities among integrated system suppliers.
China
Domestic commercial vehicle production volumes drive localized assembly demand for valve components compatible with GB standard air suspension requirements. MIIT enforcement conditions market access for imported valve assemblies while supporting indigenous supplier development. Manufacturing corridors in the Yangtze River Delta and Shandong Peninsula concentrate electropneumatic valve production for regional fleet retrofit applications.
India
Bus and truck fleet expansion creates volume potential for air suspension penetration in medium and heavy commercial vehicle segments. Central government PLI scheme incentives support component localization for automotive electronics and pneumatic systems. Industrial clusters in Maharashtra and Tamil Nadu attract valve assembly operations serving domestic aftermarket channels and export markets.
Japan
Precision manufacturing standards elevate specification requirements for electronic valve response thresholds and sensor calibration protocols in domestic commercial vehicle production. METI industrial policy supports mechatronics competency development across pneumatics-electronics-software skill combinations. Manufacturing concentration in the Chubu region around Nagoya sustains tier-one supplier relationships with integrated brake system architects.
Chassis Leveling Valves Market Competitive Environment
Concentration sits with integrated brake system suppliers possessing captive electronics and pneumatics capabilities, while standalone valve specialists face narrowing specification access as OEM procurement consolidates under framework agreements. Market structure tilts toward tiered consolidation where scale-driven integrators, regional aftermarket distributors, and component specialists occupy distinct competitive positions. Dominant competitive moves include backward integration into solenoid coil and sensor module production, plus geographic expansion through localized assembly partnerships in emerging-market production corridors.
Among Germany-based integrated system architects, Knorr-Bremse and WABCO exemplify the captive electronics archetype, anchoring positions through in-house production of control modules for automated valve platforms. Haldex represents the aftermarket channel density model, sustaining distribution network coverage across European and North American replacement markets. These three players illustrate how competitive positioning diverges between technology-forward specification capture and volume-driven service network penetration.
| Leading Market Players |
|---|
| Hendrickson |
| Haldex |
| ProVia |
| Ridewell Corporation |
| Hadley |
| Barksdale |
| WABCO |
| Knorr-Bremse |
| CoorsTek |
| Others |
Value Chain & Pricing Dynamics
EPA heavy-duty emissions standards and NHTSA safety mandates simultaneously gate supplier qualification and stratify price tiers in United States commercial vehicle procurement. Electronic valve configurations with embedded sensor modules command substantial premiums over pneumatic alternatives because certification documentation and warranty preservation requirements compress buyer price elasticity.
Pricing Analysis
Configured-to-order pricing for sensor-integrated electronic valves spreads 40-60% above standard pneumatic valve catalogs. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Price differentiation hinges on embedded software calibration capabilities and functional safety validation documentation. Fleet operators in North America show lowest price sensitivity due to warranty preservation priorities, while emerging-market retrofit buyers in China and India drive cost compression in mechanical valve tiers.
Supply Chain Analysis
Inventory cycles for solenoid coils and pressure transducers now extend 16-20 weeks, constraining just-in-time assembly schedules for electronic valve platforms. Manufacturing concentrates in Germany, China, and the United States where integrated brake suppliers maintain captive electronics capabilities. Production draws from copper and rare earth magnet supply chains exposed to commodity price volatility. Single-source vulnerability sits with electromagnetic component foundries in East Asian manufacturing corridors. Distribution runs through OEM direct channels and certified aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic height control architectures are displacing mechanical systems, forcing incumbents to defend against margin compression in pneumatic valve portfolios while capturing specification influence in integrated brake system procurement.
For Market Incumbents: Compound specification capture by deepening backward integration into solenoid coil and sensor module production. Anchor aftermarket channel density through technician certification programs in electronic valve diagnostics. Prioritize functional safety validation investments to compress embedded software certification timelines against emerging brake system integrators.
For New Entrants and Emerging Players: Anchor in India commercial vehicle fleet expansion where air suspension penetration remains below 15% in heavy-duty segments. Target electropneumatic valve localization partnerships under PLI scheme incentives. Pursue white-label manufacturing contracts with European aftermarket distributors seeking GB-standard compliant supply alternatives.
For Investors and Strategic Acquirers: EU Green Deal maintenance mandates reshape the acquisition landscape toward telematics-integrated valve platforms with predictive load-sensing capabilities. Long-term viability favors targets with software calibration competencies and captive pneumatics-electronics manufacturing. Monitor NHTSA headlight alignment enforcement intensity as inflection indicator for electronic valve specification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Modules | Captive supply of pressure transducers insulates margins from rare earth price volatility. |
| Technician Certification Programs | REACH documentation requirements in Germany and France create certified service network lock-in. |
| Predictive Load-Sensing Platform Development | Telematics integration with height control algorithms opens specification white space among fleet operators. |
| Localized Assembly Partnerships | MIIT GB standard enforcement in China conditions market access for imported valve assemblies. |
| Functional Safety Validation Investment | ISO 26262 certification accelerates platform launches for automated manual transmission integration. |
Study Parameters
A standing panel of fleet maintenance directors, OEM platform engineers, aftermarket distributor procurement leads, and brake system integrator R&D heads provided ongoing calibration across the study. Primary fieldwork combined structured interviews with tier-one supplier executives and validation against customs records, vehicle production databases, EPA certification filings, and NHTSA safety recall documentation. Secondary sources encompassed SEC 10-K disclosures from listed component suppliers, IHS Markit commercial vehicle registration data, and EU F-Gas regulatory impact assessments. Bottom-up unit economics triangulated against top-down market size estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture, end-user channel structure, installation duty cycle, and control mechanism integration complexity. CAGRs derived from logistic adoption curves fitted to regulatory mandate enforcement schedules and fleet replacement interval compression patterns. Forecast inputs incorporated copper and rare earth price trajectory assumptions alongside automated manual transmission penetration rates.
Material uncertainties — commodity price volatility, regulatory enforcement intensity variation, and mechatronics talent pipeline constraints — sit outside the modeled envelope. Forecasts reflect documented assumptions about technology substitution velocity and aftermarket channel consolidation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Grille Guard Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Forklift Seats Market
Vehicle Components
High Efficiency Rolling Bearings Market
Vehicle Components
Steering Gear Market
Vehicle Components
Motor Lamination Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
HCV Axles Market
Vehicle Components
Suction Road Sweeper Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Trailer Spindles Market