

Hooklift Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Hooklift Trailer Market Insights
Equipment leasing and project finance for municipal fleet procurement is rewriting competitive access in the hooklift trailer sector. Palfinger leverages its Austrian manufacturing scale to anchor supply contracts with European waste utilities. Hiab competes through crane-hydraulic integration expertise that extends its value proposition beyond bare chassis. Meiller sustains dominance in German-speaking markets through specialized steel-fabrication depth for high-cycle applications.
A hooklift trailer is a demountable container carrier comprising a truck-mounted hydraulic arm and locking mechanism that tilts, lifts, and slides interchangeable cargo bodies onto a chassis frame, typically engineered with high-tensile steel booms rated for 15-20 ton payloads and sub-90-second container exchange cycles. Its primary purpose is to maximize vehicle utilization by allowing one tractor to service multiple container types across waste, construction, and bulk-material logistics. Standard hooklift configurations occupy the mature volume segment where margin pools have compressed amid fleet-standardization pressures, while side-loader variants are capturing disproportionate interest from urban municipal operators constrained by narrow street access and overhead clearance limits. Articulated designs for mining and heavy construction applications represent the fastest-growing structural category, driven by payload-capacity escalation and terrain-mobility requirements that command premium pricing over rigid-frame alternatives.
EU Green Deal waste-framework targets and F-Gas Regulation compliance for hydraulic systems are reshaping product-design requirements across European manufacturing bases, with CE marking and national type-approval processes administered by Germany's KBA and France's ANSM governing market access. ECHA REACH restrictions on chromium-based corrosion coatings are forcing steel-supplier qualification changes that ripple through fabrication cost structures. Stakeholders must monitor how EU AI Act provisions on autonomous fleet-logistics software interface with hooklift telematics and remote-diagnostic systems now embedded in premium product tiers.
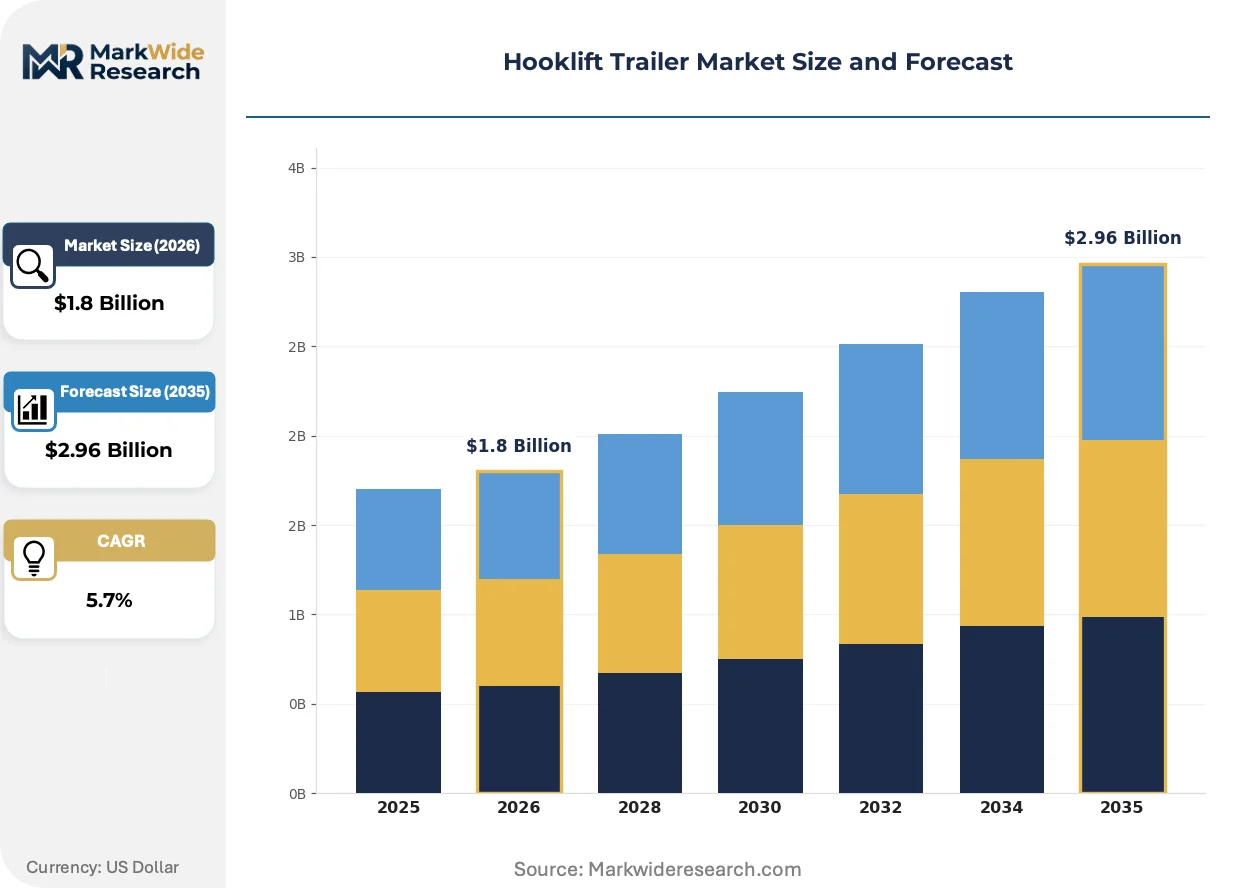
Market Dynamics
EU Green Deal circular-economy mandates are forcing municipal waste fleets across Western Europe to consolidate procurement around high-cycle hooklift systems with sub-90-second container exchange capability. This regulatory pressure is compressing equipment replacement timelines and concentrating buying power with rental service providers who can amortize specialized chassis across diversified container pools.
Growth Catalysts
- EU Green Deal waste-framework targets:Municipal operators in Germany, France, and Italy face binding diversion-rate mandates that require fleet densification and container standardization, directly expanding hooklift deployments.
- Steel-hydraulic payload optimization:High-tensile steel boom fabrication advances are extending rated capacities to 20 tons while reducing tare weight, enabling single-tractor multi-container logistics that improve asset turns.
- Urban street-access constraints:Narrow historic centers and overhead clearance limits in Italian and French municipalities are accelerating specification of side-loader variants over conventional rear-load configurations.
Market Restraints
- ECHA REACH chromium-coating restrictions:Corrosion-protection chemistry changes are forcing steel-supplier requalification that extends procurement lead times and elevates fabrication cost structures.
- Hydraulic fluid compliance costs:F-Gas Regulation phase-down schedules for synthetic hydraulic fluids are compelling system redesigns and inventory transitions that strain mid-tier fabricators.
- CE marking and national type-approval fragmentation:Divergent certification pathways through Germany's KBA versus France's ANSM create duplicate testing burdens that disadvantage smaller manufacturers.
Strategic Opportunities
- Autonomous fleet-logistics integration:EU AI Act provisions on telematics and remote-diagnostics systems are opening premium-tier positioning for hooklift OEMs embedding predictive-maintenance software.
- Articulated mining configurations:Payload-capacity escalation and terrain-mobility requirements in heavy construction and extractive sectors are commanding pricing premiums over rigid-frame alternatives.
- Equipment-leasing channel expansion:Project-finance structures for municipal fleet procurement are shifting volume toward rental service providers who aggregate demand across smaller haulage operators.
Industry Challenges
- Hydraulic-technician scarcity:Specialized repair capacity for high-pressure steel-boom systems concentrates with OEM-authorized service networks, extending downtime for independent operators.
- Telematics-legacy fleet incompatibility:Retrofitting remote-diagnostic modules onto installed hooklift bases requires chassis-electronics upgrades that many municipal garages lack capability to execute.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hooklift Trailer Market Trends and Innovations
Steel-fabrication and hydraulic-system engineering are converging around payload-optimized designs that compress container-exchange cycles while accommodating stricter corrosion-coating chemistries. Three forces are reconfiguring product architecture and procurement patterns.
Electro-hydraulic actuation is hybridizing traditional pump-and-cylinder architectures with variable-speed electric drives that modulate power draw during lift cycles. German municipal fleets are piloting these systems under KBA-monitored field trials to document fuel-consumption reductions. The technology is hybridizing competitive positioning by enabling OEMs to bundle energy-efficiency guarantees with equipment leases, compressing pure-hardware margins while expanding service-revenue pools.
F-Gas Regulation compliance deadlines are mandating hydraulic-fluid formulation shifts that eliminate high-GWP synthetic bases. Fabricators serving French and Italian markets through ANSM and KBA approval pathways must recertify seal-compatibility and thermal-performance specifications. Waste-collection OEMs are responding by vertically integrating fluid-supply contracts to lock in qualified chemistry volumes ahead of phase-down dates.
Outcome-based fleet-availability contracts are displacing traditional equipment-purchase models among municipal procurement offices. Rental providers now guarantee container-exchange uptime percentages rather than delivering bare chassis, transferring operational risk from haulage companies to equipment lessors. This pattern concentrates most visibly in German-speaking markets where Meiller and Palfinger anchor long-term service agreements with major city utilities.
Hooklift Trailer Market Segmentation
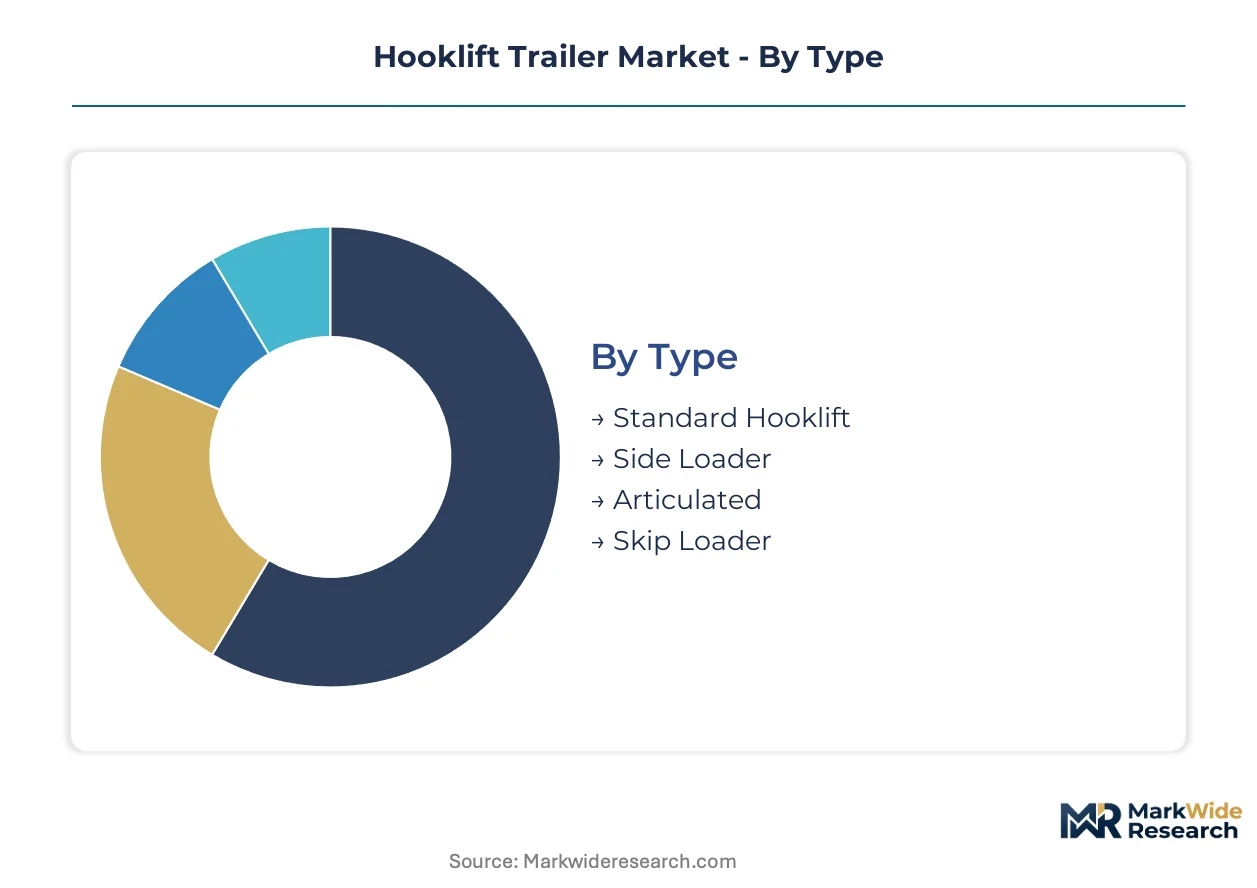
Hooklift trailer segmentation reveals divergent service-intensity requirements across configurations. After-sales contract structures vary sharply by type and payload tier, with high-cycle municipal fleets demanding uptime guarantees that reshape OEM revenue models.
Type:
After-sales service intensity climbs steeply with operational complexity, as hydraulic cycle frequency and boom articulation multiply preventive-maintenance touchpoints.
- Standard Hooklift:Rigid-frame designs with fixed pivot geometry dominate volume production for conventional waste-collection routes. German and French municipal fleets concentrate procurement here, driven by EU Green Deal container-standardization mandates that prioritize interchange speed over terrain adaptability.
- Side Loader:Lateral container-handling arms enable operation within narrow street envelopes and sub-3-meter overhead clearances. Italian historic-center municipalities specify this configuration disproportionately, constrained by medieval urban fabric that prohibits rear-load maneuvers.
- Articulated:Pivot-steer chassis with oscillating hitches serve mining and heavy construction applications requiring terrain articulation. Payload ratings extend beyond 20 tons for extractive sector contracts.
- Skip Loader:Simplified cable-lift mechanisms for lower-cycle construction debris transport. Rental fleets favor this type for price-sensitive short-term deployment.
By volume, Standard Hooklift leads. By growth pace, Articulated configurations are climbing the fastest.
Payload Capacity:
Cost tier stratification separates premium-rated systems from economy-positioned alternatives, with steel-grade specification and hydraulic component sourcing as primary cost drivers.
- 20 Tons:High-tensile steel boom fabrication with reinforced chassis rails serves mining and heavy construction sectors. Premium pricing reflects metallurgical qualification overhead and extended warranty structures.
- 15 Tons:Municipal waste-collection standard across Western European fleets. CE marking and KBA type-approval concentrate procurement with qualified fabricators capable of documented fatigue-cycle testing.
- 10 Tons:Mid-tier positioning for regional haulage operators balancing payload flexibility with axle-weight regulations. ANSM certification pathways in France create distinct specification requirements from German KBA routes.
- 5 Tons:Compact urban delivery and light construction applications. Equipment-leasing channels aggregate fragmented demand across small independent operators.
By volume, 15 Tons leads. By growth pace, 20 Tons is gaining share fastest.
Industry Use Case:
Application-specific duty cycles determine hydraulic-fluid formulation and corrosion-coating specifications, with ECHA REACH compliance costs varying by exposure severity.
- Waste Management:High-frequency container exchange with corrosive leachate exposure demands specialized seal compounds and accelerated maintenance intervals. EU Green Deal diversion-rate targets are expanding fleet deployments across German, French, and Italian municipalities.
- Construction:Debris handling with abrasive particulate loads accelerates boom-surface wear. Rental service providers aggregate demand through project-finance structures that transfer operational risk from contractors.
- Mining:Continuous-duty extraction logistics with terrain-mobility requirements. Articulated configurations dominate this segment with premium pricing over rigid-frame alternatives.
- Agriculture:Seasonal grain and biomass transport with lower cycle frequency. Price sensitivity concentrates procurement with economy-tier fabricators.
By volume, Waste Management leads. By growth pace, Mining shows the steepest expansion trajectory.
End User:
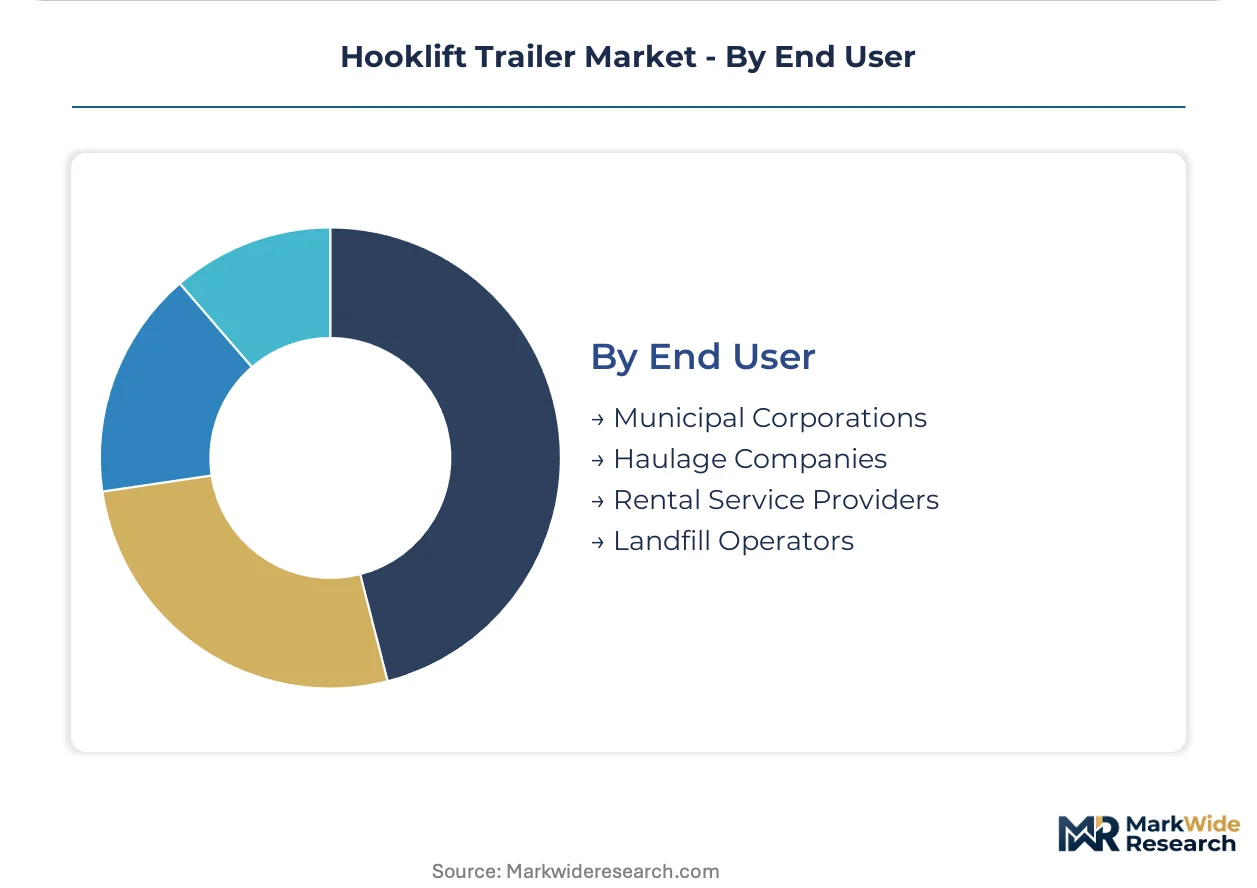
Customer-type concentration patterns reveal diverging procurement capabilities, with municipal scale enabling outcome-based contracts that independent operators cannot replicate.
- Municipal Corporations:City and regional waste utilities with binding fleet-densification mandates under EU circular-economy frameworks. Long-term service agreements with guaranteed uptime percentages are displacing equipment purchase.
- Haulage Companies:Private logistics operators serving construction and industrial accounts. Procurement concentrates with rental providers who amortize chassis across diversified container pools.
- Rental Service Providers:Equipment-leasing specialists aggregating fragmented demand. Project-finance structures concentrate buying power with Palfinger and Meiller through multi-year fleet agreements.
- Landfill Operators:Site-specific container positioning with lower mobility requirements. Specification emphasizes durability over exchange-cycle speed.
By volume, Municipal Corporations lead. By growth pace, Rental Service Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in hooklift trailer equipment reveal Western European fabrication dominance balanced against emerging assembly capacity in Eastern Europe and Asia. Germany, Austria, and Italy maintain net export positions in high-tensile steel boom systems, while import dependency concentrates in markets lacking qualified hydraulic-system certification pathways.
Germany
Municipal fleet densification under EU Green Deal diversion mandates drives procurement concentration with KBA type-approved fabricators. ECHA REACH chromium-coating restrictions force steel-supplier requalification that extends lead times for corrosion-protected booms. The Munich-Stuttgart industrial corridor anchors high-cycle manufacturing for waste-collection OEMs serving city utilities.
France
ANSM certification pathways create distinct specification requirements from German KBA routes, fragmenting procurement for mid-tier haulage operators. F-Gas Regulation hydraulic-fluid phase-down schedules compel system redesigns among fabricators serving French municipal markets. The Lyon-Grenoble cluster concentrates side-loader variant production for historic-center waste logistics.
Italy
Narrow street envelopes in medieval urban centers accelerate side-loader specification over rear-load configurations among municipal operators. CE marking alignment with national type-approval processes governs market access for imported chassis systems. Northern industrial districts around Bologna and Milan host specialized steel-fabrication capacity for sub-3-meter clearance applications.
United States
Construction debris logistics and independent haulage operator demand sustain import flows from European premium-tier fabricators. EPA emissions compliance for truck-mounted hydraulic systems shapes equipment specification at state fleet procurement offices. The Great Lakes manufacturing belt concentrates domestic assembly capacity serving rental service provider channels.
China
Domestic infrastructure investment and mining sector expansion drive articulated configuration demand for terrain-mobility applications. GB standards and MIIT equipment certification govern market access for imported hydraulic-component suppliers. Yangtze River Delta fabrication clusters scale production for export-oriented standard hooklift configurations.
Hooklift Trailer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of final assembly. The vendor base organizes around three functional layers: full-system OEMs delivering chassis-integrated solutions, hydraulic-component suppliers providing pump-and-cylinder subassemblies, and steel-fabrication houses specializing in high-tensile boom structures. Two competitive vectors dominate: backward integration into qualified steel supply to secure corrosion-coating chemistry compliance, and geographic expansion through equipment-leasing channel partnerships that aggregate fragmented municipal demand.
Among European-based fabricators, Palfinger anchors Austrian manufacturing scale for supply contracts with waste utilities, while Hiab occupies a position bridging crane-hydraulic integration expertise. Meiller represents specialized steel-fabrication depth for high-cycle applications in German-speaking markets. These three exemplify how regional certification concentration—KBA in Germany, ANSM in France—shapes competitive access patterns across Western European procurement.
| Leading Market Players |
|---|
| Palfinger |
| Hiab |
| Hyva Group |
| Krampe Fahrzeugbau |
| Marrel SAS |
| Meiller |
| Stellar Industries |
| SwapLoader USA |
| VDL Containersystemen |
| Others |
Pricing and Supply Chain Analysis
The Munich-Stuttgart industrial corridor concentrates high-tensile steel boom fabrication capacity for KBA type-approved systems, translating supply scarcity into pricing leverage for qualified fabricators serving German municipal utilities. CE marking and national type-approval fragmentation through Germany's KBA versus France's ANSM create dual certification burdens that compress margins for mid-tier manufacturers while concentrating premium pricing power with established OEMs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium positioning rests on KBA fatigue-cycle documentation and extended uptime guarantees, while economy tiers compete on bare chassis procurement for rental fleet aggregation. Cost compression in standard configurations is intensifying because ECHA REACH chromium-coating requalification extends steel-supplier lead times. Municipal corporations show least price sensitivity due to outcome-based contract structures, whereas independent haulage operators concentrate in economy tiers.
Supply Chain Analysis
EU dual-use export controls on high-pressure hydraulic component technology limit flows of specialized pump-and-cylinder subassemblies to non-CE marking markets. Germany, Austria, and Italy anchor fabrication capacity for qualified steel boom systems, while hydraulic seal compounds and corrosion-coating chemistries draw from qualified European chemical suppliers. Single-source vulnerability concentrates in high-tensile steel mills capable of ECHA REACH compliant metallurgical certification. Distribution runs through equipment-leasing channels that aggregate fragmented municipal demand across Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hooklift trailer sector exhibits cyclical recovery characteristics as EU Green Deal waste-framework mandates force accelerated fleet replacement timelines across municipal procurement offices.
For Market Incumbents: Harden KBA and ANSM certification depth to defend against mid-tier fabricators disadvantaged by duplicate testing burdens. Prioritize backward integration into qualified steel supply to lock in corrosion-coating chemistry volumes ahead of ECHA REACH phase-down dates. Expand captive service-network density to address hydraulic-technician scarcity that extends downtime for independent operators. For New Entrants and Emerging Players: Eastern European municipal markets outside core German-French-Italian procurement clusters present underpenetrated demand for standard hooklift configurations. Target Italian historic-center municipalities with side-loader variants engineered for sub-3-meter clearance applications. Pursue equipment-leasing partnerships rather than direct OEM competition to bypass incumbent service-network advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors steel-fabrication specialists with electro-hydraulic actuation pilot programs under KBA-monitored field trials. Long-term viability rests on OEMs capable of bundling energy-efficiency guarantees with outcome-based fleet-availability contracts. Monitor F-Gas Regulation hydraulic-fluid phase-down compliance rates as inflection indicator for fabrication cost structure divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Qualified Steel Supply | Secures ECHA REACH compliant corrosion-coating chemistry ahead of supplier requalification bottlenecks. |
| Electro-Hydraulic Actuation Pilot Programs | Enables KBA-documented fuel-consumption reductions that support premium lease bundling. |
| Equipment-Leasing Channel Partnerships | Aggregates fragmented municipal demand across smaller haulage operators in German-speaking markets. |
| Side-Loader Variant Development | Captures Italian historic-center procurement constrained by medieval urban fabric clearance limits. |
| Predictive Maintenance Software Integration | Aligns hooklift telematics with EU AI Act provisions for autonomous fleet-logistics positioning. |
Research Methodology
A standing panel of municipal fleet managers, rental service provider procurement heads, steel-fabrication plant engineers, and hydraulic-system aftermarket service directors provided ongoing calibration across the research period. Primary interview data combined with secondary validation from KBA type-approval registries, ANSM certification databases, ECHA REACH restriction updates, and EU Green Deal implementation tracking. Bottom-up volume modeling across payload capacity tiers and top-down demand triangulation from municipal budget disclosures established analytical convergence.
Scenario-bracketing around EU circular-economy diversion-rate mandate enforcement and F-Gas Regulation phase-down schedules bounded projection uncertainty across the analysis window. Segmentation dimensions modeled include hooklift type, payload capacity tier, industry use case, and end-user procurement structure. CAGRs derived from equipment replacement cycle compression and rental channel expansion trajectories. Industry-specific forecast inputs incorporated hydraulic-technician labor market tightness and telematics retrofit capability gaps in municipal garage infrastructure.
Practitioners should monitor ECHA REACH coating chemistry restriction timelines and KBA electro-hydraulic field trial documentation for early signals of fabrication cost structure shifts. Forecasts reflect assumptions regarding EU Green Deal mandate continuity and qualified steel mill capacity expansion. Material shifts in F-Gas Regulation enforcement severity or ANSM-KBA certification pathway harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.