
 UAE Transportation Infrastructure Construction Market | 2026-2036
UAE Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Transportation Infrastructure Construction Market Analytics
Public-private partnership financing is reconfiguring competitive access across the UAE transportation infrastructure construction sector. Bechtel Corporation leverages its engineering-procurement-construction integration to anchor large-scale airport and rail mandates. ALEC Engineering & Contracting LLC dominates high-rise and horizontal infrastructure through its captive precast capabilities in Dubai Industrial City. China State Construction Engineering Corp. Middle East extends its cost-engineered delivery model to compete on volume-driven road packages.
UAE transportation infrastructure construction encompasses the planning, engineering, and physical assembly of roadways, bridges, railways, and airport facilities using concrete, asphalt, steel, and aggregate composites to achieve specified load-bearing capacities and design lifespans. The primary purpose is to enable safe, efficient movement of passengers and freight across the Emirates' urban corridors and logistics hubs. Airport and railway project types command premium engineering margins due to specialized MEP and systems integration requirements. Precast and sustainable construction methods are gaining share as MOCCAE green building regulations tighten embodied carbon thresholds for federal contracts.
MOCCAE green building regulations, the UAE Net Zero 2050 strategy, and Dubai Municipality construction codes collectively shape material specifications, contractor eligibility, and project approval timelines across the Emirates. Federal procurement rules now mandate sustainability scoring for infrastructure bids above specified value thresholds. Stakeholders must monitor how evolving carbon accounting standards affect precast concrete sourcing and asphalt mix designs in upcoming transport packages.
Market Dynamics
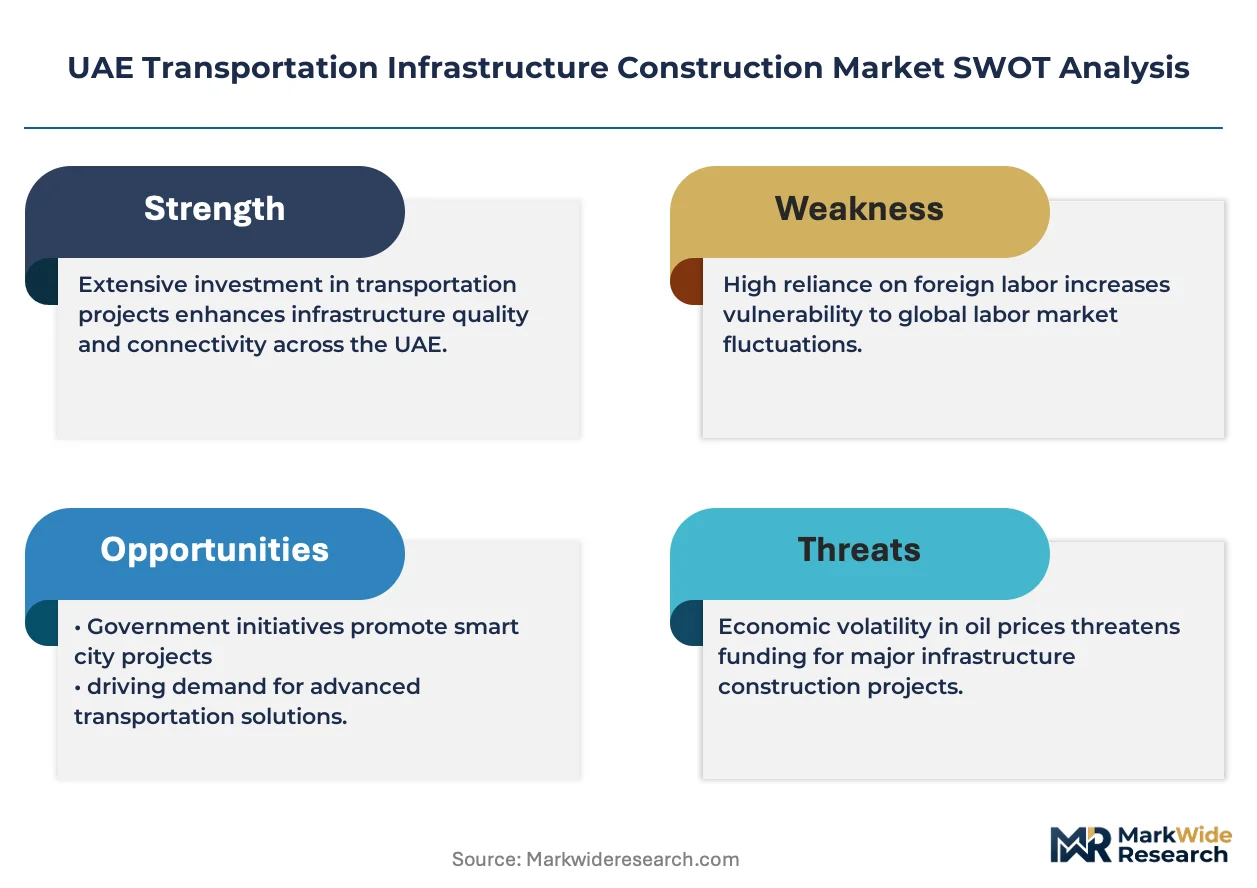
Federal sustainability mandates and precast concrete adoption are compressing traditional construction timelines while elevating technical qualification barriers for UAE contractors bidding on transport packages.
Growth Catalysts
- MOCCAE Green Building Regulations:Embodied carbon thresholds for federal contracts above specified value thresholds are accelerating demand for low-carbon asphalt mixes and recycled aggregate composites in road and bridge projects.
- Dubai Metro Extensions:Horizontal infrastructure expansion across the emirate's urban corridors is pulling specialized MEP integration capabilities and rail systems engineering into the construction value chain.
- Abu Dhabi Rail Corridors:Freight and passenger network development is concentrating demand for heavy-duty trackbed materials and long-span bridge engineering across the emirate's logistics hubs.
Market Restraints
- Steel Price Volatility:Global commodity fluctuations for structural reinforcement steel are compressing margins on fixed-price federal contracts with extended delivery timelines.
- Specialized Labor Concentration:Certified bridge welders and rail systems technicians cluster in Dubai and Abu Dhabi, creating geographic bottlenecks for projects in northern emirates.
- Technical Specification Rigor:Load-bearing capacity requirements for airport runway substrates exceed capabilities of standard road-building equipment, limiting contractor pools.
Strategic Opportunities
- Ras Al Khaimah Transport Corridors:Underdeveloped highway and port connectivity infrastructure in the northern emirate offers first-mover positioning for contractors with captive aggregate quarries.
- Digital Twin Integration:Convergence of BIM platforms with IoT sensor networks during construction phases is opening premium service contracts for engineering firms with software capabilities.
- Federal PPP Frameworks:New public-private partnership financing structures for transport assets are creating alternative revenue streams through availability-based payment mechanisms.
Industry Challenges
- Emiratization Workforce Targets:Federal mandates for local citizen employment in technical and supervisory roles outpace vocational training program output, constraining project staffing.
- Legacy System Integration:New rail and metro infrastructure must interface with existing Dubai Metro Red and Green Line control systems, complicating signaling and power supply engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Transportation Infrastructure Construction Market |
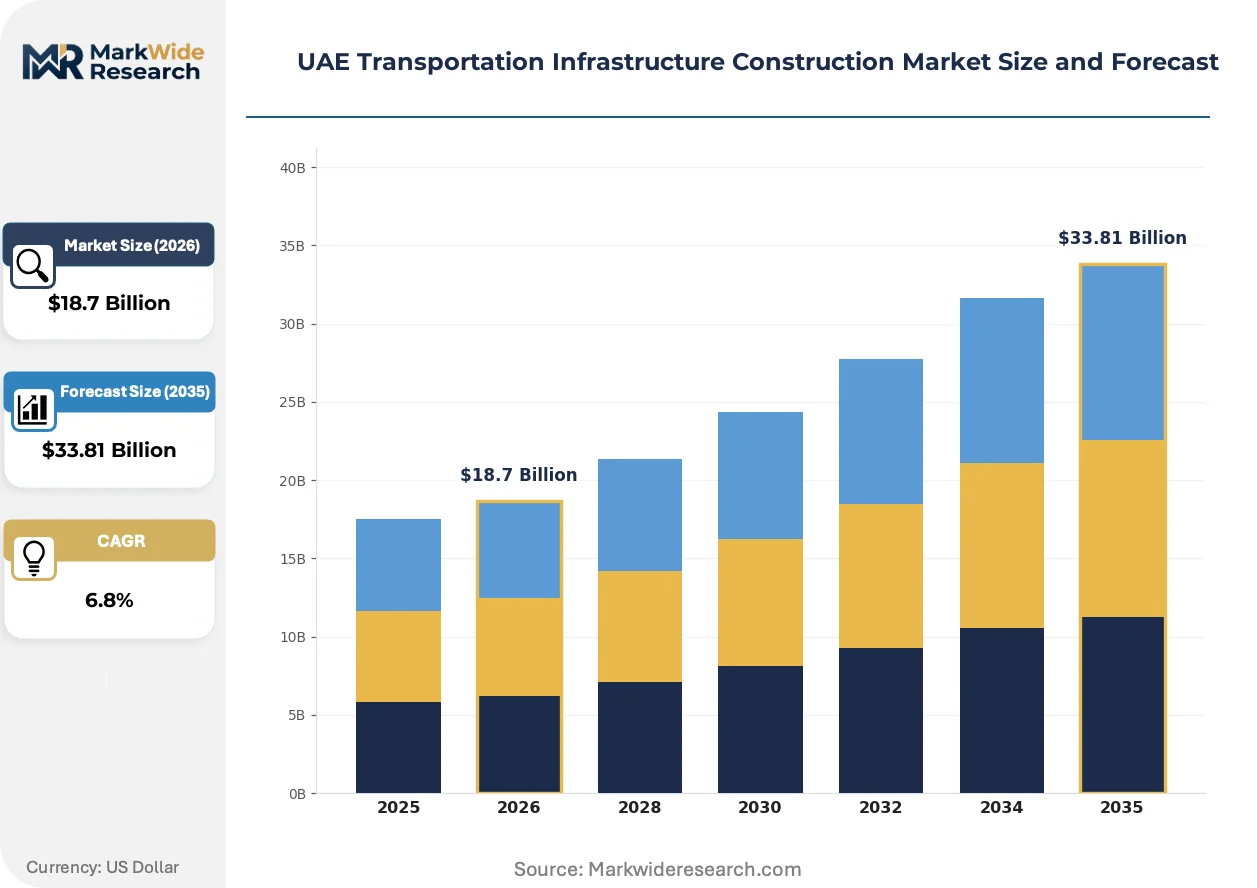
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Airports Material Type: Concrete, Asphalt, Steel, Aggregates Construction Method: Traditional, Modular, Precast, Sustainable End User: Government, Private Sector, Contractors, Consultants |
| Companies Covered | National Contracting and Transport CO, Bechtel Corporation, Al-Futtaim Group, Vinci Construction Grands Projets, Larsen & Toubro Construction, ALEC Engineering & Contracting LLC, Khansaheb, China State Construction Engineering Corp. Middle East, Consolidated Contractors Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Transportation Infrastructure Construction Market Evolving Landscape
Precast manufacturing methods and digital construction platforms are compressing project delivery timelines while MOCCAE carbon accounting rules reshape material sourcing protocols across federal transport packages.
Ultra-high-performance concrete (UHPC) is hybridizing traditional precast bridge element production with reduced section depths and extended spans. Federal contractors are adopting UHPC for Dubai Metro viaduct segments to minimize visual intrusion and foundation footprints. This material convergence is compressing structural steel tonnage requirements in elevated transport infrastructure while demanding specialized batching plant investments.
MOCCAE embodied carbon disclosure mandates for infrastructure contracts are forcing asphalt suppliers to document lifecycle emissions from bitumen extraction through pavement placement. Contractors must now submit verified Environmental Product Declarations for federal road packages above threshold values. Dubai Municipality construction codes are tightening fastest, with Abu Dhabi and Sharjah municipalities tracking implementation timelines six to twelve months behind.
Transport authorities are consolidating design-build procurement for major corridor packages, collapsing traditional multi-stage tender processes into single-source accountability structures. This consolidation favors contractors with integrated engineering and fabrication capabilities over pure construction plays. Abu Dhabi's Department of Transport has advanced furthest in this transition, with Dubai's Roads and Transport Authority piloting similar frameworks on metro extension segments.
UAE Transportation Infrastructure Construction Market Segmentation
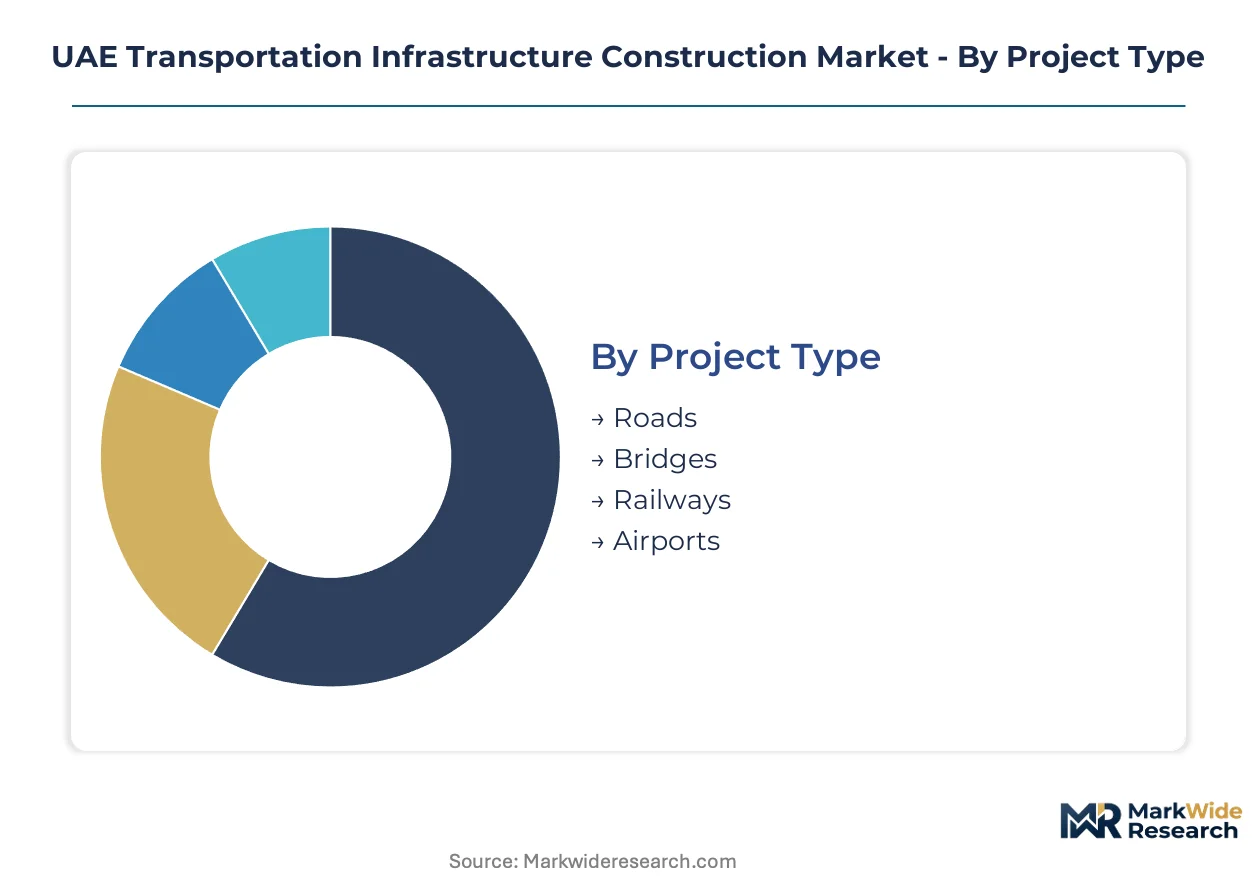
Project type and material composition determine procurement pathways and contractor qualification tiers across UAE federal transport packages. Construction method selection increasingly governs bid eligibility under MOCCAE carbon disclosure mandates.
Project Type:
Railways and airports run longest from tender to commissioning, while road resurfacing cycles compress to months. Bridge programs occupy the middle tier with multi-year horizons tied to foundation complexity.
- Roads:Surface and subsurface engineering using asphalt and aggregate composites for arterial highways, urban distributors, and local access networks. Demand clusters in Dubai's corridor densification and Ras Al Khaimah's underdeveloped northern connectivity, driven by federal budget allocations for last-mile logistics access.
- Bridges:Long-span structural assemblies combining precast concrete segments with steel reinforcement for viaducts, interchanges, and water crossings. Abu Dhabi's rail corridor integration and Dubai Metro extension mandates concentrate specialized design-build procurement for elevated transport infrastructure.
- Railways:Heavy-duty trackbed construction and station civil works for freight and passenger networks. Etihad Rail's phased rollout anchors demand for ballast, sleepers, and electrification infrastructure across the emirates.
- Airports:Runway substrates, terminal structures, and airside pavement engineering with specialized load-bearing specifications. Dubai International and Al Maktoum expansion programs pull premium asphalt and concrete sourcing for Federal Aviation Authority compliance.
Roads dominate installed base across the Emirates. Railways is where expansion concentrates as Etihad Rail advances inter-emirate connectivity.
Material Type:
Cost tier separates commodity inputs from engineered composites with certified performance envelopes. Steel and UHPC command premium positioning against bulk aggregate and standard concrete grades.
- Concrete:Standard and high-performance mixes for structural elements, pavements, and precast fabrication. MOCCAE embodied carbon thresholds are forcing suppliers to document clinker substitution rates and supplementary cementitious material sourcing for federal contracts.
- Asphalt:Bituminous binders and surface courses with specified penetration grades and polymer modifications. Dubai Municipality's accelerated green code implementation is tightening lifecycle emission documentation requirements ahead of other emirates.
- Steel:Structural reinforcement, bridge girders, and rail infrastructure components subject to global commodity price volatility. Fixed-price federal contracts with extended delivery timelines expose margin compression when raw material costs spike.
- Aggregates:Crushed stone, sand, and gravel for sub-base, concrete batching, and asphalt production. Ras Al Khaimah's captive quarry resources offer logistics advantages for northern emirate corridor development.
Concrete and asphalt dominate installed base by volume. Steel and UHPC composites are where specification premiums and technical qualification barriers concentrate.
Construction Method:
Maturity separates legacy cast-in-place techniques from emerging modular and sustainable approaches with shorter site footprints and lower carbon intensity.
- Traditional:Cast-in-place concrete and on-site asphalt paving with established equipment fleets and labor protocols. Remains default for small-scale road maintenance and remote emirate projects with limited precast logistics access.
- Modular:Prefabricated bridge elements and standardized structural components for rapid assembly. Gaining traction in Dubai Metro viaduct segments where traffic disruption minimization drives procurement scoring.
- Precast:Factory-cast concrete elements with controlled curing environments and dimensional precision. ALEC Engineering's Dubai Industrial City capabilities anchor regional supply for horizontal infrastructure with compressed delivery timelines.
- Sustainable:Low-carbon concrete mixes, recycled aggregate incorporation, and renewable-powered batching operations. Federal procurement rules now mandate sustainability scoring above specified contract value thresholds, accelerating method adoption.
Traditional methods dominate legacy installed base. Precast and sustainable construction are where MOCCAE compliance requirements and federal scoring incentives concentrate expansion.
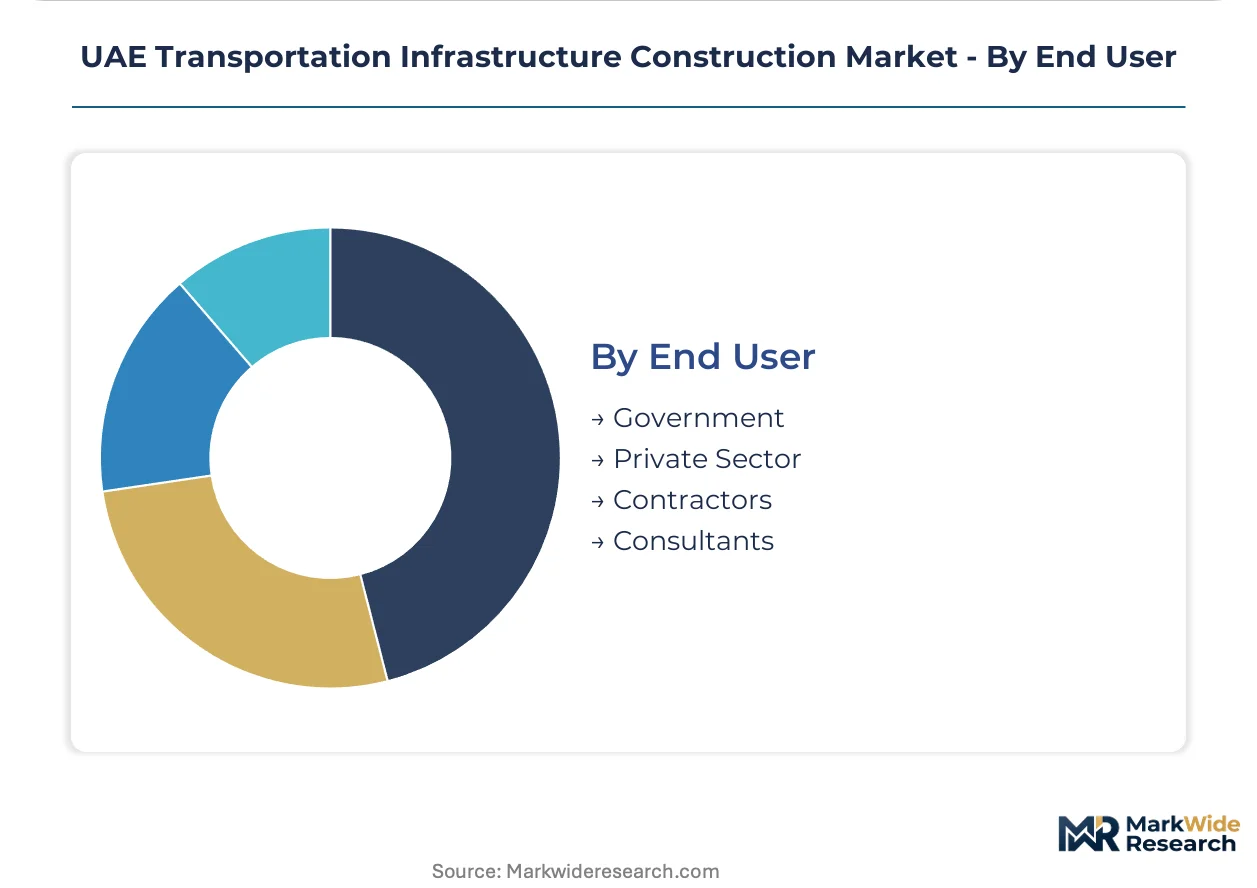
End User:
Customer type determines procurement authority, technical specification control, and payment security across the project lifecycle.
- Government:Federal and emirate-level transport authorities with design-build and traditional tender frameworks. Abu Dhabi's Department of Transport leads procurement consolidation into single-source accountability structures.
- Private Sector:Logistics operators, airport concessionaires, and industrial developers with self-funded infrastructure requirements. Dubai South and KIZAD free zones generate demand for customized access roads and freight handling facilities.
- Contractors:Tier-1 construction firms and specialized subcontractors executing federal packages under engineering-procurement-construction integration. Bechtel Corporation anchors large-scale mandates through combined design-build capabilities.
- Consultants:Engineering advisory firms for feasibility, environmental impact, and construction supervision. Digital twin integration and BIM platform convergence are opening premium service contracts for software-capable practices.
Government procurement dominates contract value and technical specification authority. Private sector and consultant roles are where alternative delivery models and digital service premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure budgets and emirate-level development mandates are redistributing construction activity across the UAE, with transport corridors emerging as the primary allocation mechanism for public investment.
Dubai
Dubai Metro extensions and Al Maktoum International Airport expansion anchor the emirate's transport construction pipeline. Dubai Municipality construction codes enforce the nation's tightest embodied carbon thresholds for asphalt and concrete sourcing. Dubai Industrial City hosts ALEC Engineering's captive precast facilities, supplying viaduct segments for elevated rail infrastructure with compressed delivery timelines.
Abu Dhabi
Etihad Rail freight corridors and passenger network development concentrate demand for heavy-duty trackbed materials and long-span bridge engineering. The Department of Transport leads procurement consolidation into single-source design-build accountability structures. KIZAD free zone and Khalifa Port generate customized access road and freight handling facility requirements for logistics operators.
Sharjah
Inter-emirate highway connectivity improvements and port expansion at Hamriyah Free Zone drive road and bridge construction demand. Sharjah Municipality tracks Dubai's green building implementation timeline with a six-to-twelve-month lag. The emirate's industrial zones attract mid-tier contractors seeking volume-driven road packages with lower technical qualification barriers.
Northern Emirates
Ras Al Khaimah's underdeveloped highway and port connectivity infrastructure offers first-mover positioning for contractors with captive aggregate quarries. Federal budget allocations for last-mile logistics access are accelerating corridor development. Fujairah's strategic location on the Gulf of Oman generates demand for freight handling facilities and coastal road upgrades.
UAE Transportation Infrastructure Construction Market Competitive Landscape
On the supply side, the industry is tiered between integrated engineering-procurement-construction operators and specialized horizontal infrastructure contractors. Federal procurement consolidation favors players with combined design-build capabilities and captive material production. Two strategic archetypes dominate: multinational EPC integrators leveraging technical qualification premiums, and regional specialists exploiting logistics proximity and precast manufacturing scale. Competitive positioning hinges on sustainability scoring compliance and precast capacity expansion.
Within the integrated EPC tier, Bechtel Corporation represents multinational engineering-procurement-construction integration, while ALEC Engineering & Contracting LLC exemplifies regional precast manufacturing scale. China State Construction Engineering Corp. Middle East occupies a position bridging cost-engineered delivery models with federal contract eligibility. These three anchors illustrate how technical qualification, captive production, and volume pricing each carve distinct competitive positions.
| Leading Market Players |
|---|
| National Contracting and Transport CO |
| Bechtel Corporation |
| Al-Futtaim Group |
| Vinci Construction Grands Projets |
| Larsen & Toubro Construction |
| ALEC Engineering & Contracting LLC |
| Khansaheb |
| China State Construction Engineering Corp. Middle East |
| Consolidated Contractors Company |
| Others |
Value Network & Pricing Analysis
Etihad Rail freight corridors tie transport construction pricing to aggregate quarry proximity and precast batching scale, compressing margins for contractors without captive material sources while enabling premium bids from integrated operators. Dubai Municipality's accelerated carbon disclosure timelines widen spreads between certified low-carbon asphalt suppliers and standard-grade competitors.
Pricing Analysis
Certification level under MOCCAE green building regulations creates the primary spread between federal contract tiers. Three-tier pricing structure across premium, standard, and economy levels reflects embodied carbon documentation depth and precast manufacturing integration. Pricing pressure stems from steel reinforcement volatility on fixed-price mandates with extended delivery horizons. Tier-2 contractors in Sharjah and Ras Al Khaimah exhibit highest price sensitivity due to thinner balance sheets and limited precast capacity.
Supply Chain Analysis
Extended payment terms from federal transport authorities and supply-chain finance facilities anchor working capital structures for precast concrete suppliers. Raw material flows draw from UAE captive quarries, Indian structural steel mills, and Chinese specialty cementitious additives. Single-source vulnerability concentrates in certified low-carbon bitumen shipments subject to Dubai Municipality's tightening documentation windows. Distribution runs through emirate-level transport authority procurement portals with design-build consolidation favoring integrated EPC accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin integration and BIM-enabled construction supervision services expand faster than physical infrastructure hardware, creating recurring-revenue layers for engineering firms with software capabilities. Post-commissioning asset monitoring contracts for rail signaling and airport MEP systems offer multi-year service attach opportunities.
For Market Incumbents: Entrench precast manufacturing scale in Dubai Industrial City and Abu Dhabi logistics corridors to defend against China State Construction Engineering Corp.'s cost-engineered road packages. Backward integration into captive aggregate quarries in Ras Al Khaimah secures margin buffers against steel price volatility on fixed-price federal mandates. For New Entrants and Emerging Players: Pursue digital twin service contracts for Etihad Rail corridor segments where incumbent EPCs lack BIM-IoT convergence capabilities. White-space concentrates in northern emirate bridge welding and rail systems technician staffing, with geographic arbitrage against Dubai-Abu Dhabi labor bottlenecks offering entry angles. For Investors and Strategic Acquirers: Specialized MEP integration firms with Federal Aviation Authority runway certification represent the priority acquisition archetype for airport expansion exposure. Long-term viability hinges on MOCCAE compliance capability depth rather than pure construction volume. Watch for Abu Dhabi Department of Transport design-build procurement consolidation as inflection signal for integrated EPC valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Precast Capacity Expansion | ALEC Engineering's Dubai Industrial City facilities anchor compressed delivery timelines for metro viaduct segments. |
| Backward Integration into Quarries | Ras Al Khaimah captive aggregate resources secure logistics advantages for northern emirate corridor development. |
| Digital Twin Platform Integration | BIM-IoT convergence opens premium service contracts for engineering firms with software capabilities. |
| Green Certification Investment | MOCCAE embodied carbon documentation mandates force asphalt suppliers to verify lifecycle emissions. |
| Design-Build Procurement Consolidation | Abu Dhabi Department of Transport single-source accountability structures favor integrated EPC operators. |
Research Methodology
Cross-validation between primary interviews with project directors at tier-1 contractors and secondary validation through federal procurement databases anchors the qualitative findings. Stakeholder discussions encompassed transport authority procurement officers, precast plant managers, structural engineering consultants, and asphalt supplier technical directors. Secondary sources included Dubai Municipality construction code filings, MOCCAE green building regulation updates, Etihad Rail project development disclosures, and UAE federal budget transport allocations. Bottom-up project pipeline aggregation and top-down emirate-level infrastructure spending analysis enabled triangulation.
Calibration against historical federal contract award values and announced project timelines shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed project type, material composition, construction method maturity, and end-user procurement authority. CAGRs derive from weighted average of disclosed project values and announced completion schedules. Industry-specific inputs included Etihad Rail phased rollout milestones and Dubai Metro extension segment awards.
Sensitivities concentrate around steel commodity price trajectories and MOCCAE carbon accounting standard evolution. Forecasts reflect assumptions on federal sustainability mandate enforcement consistency and precast manufacturing capacity expansion timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Dominican Republic Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
Oman Construction Market
Building Construction
Australia Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
US Offsite Construction Market
Building Construction
China Building Construction Market
Building Construction
South Korea Data Center Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
Latin America Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
China Construction Market
Building Construction
UAE Facade Market