
 Latin America Construction Market | 2026-2036
Latin America Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Construction Market Outlook
ISO 14001 environmental management certification is bifurcating the Latin America construction competitive landscape into qualified and non-qualified bidders for public-private partnerships. Andrade Gutierrez S.A. leverages its integrated engineering capabilities across energy and transport megaprojects. Mota-Engil anchors Portuguese-language market access through its Africa-Latin America corridor expertise. Techint Engineering & Construction competes on heavy industrial execution, particularly in oil, gas, and mining infrastructure.
Latin America construction encompasses the physical assembly of buildings and civil works using concrete, structural steel, reinforced masonry, and glass curtain wall systems designed to withstand seismic loads and tropical climate exposure. Residential construction leads volume contribution across the region, while infrastructure commands the deepest margin pools due to long-dated government payment guarantees and limited competition. Material type segmentation shows cement sustaining dominant share, with steel gaining in commercial high-rise applications. End-user dynamics reveal government entities as the gatekeepers of mega-project awards, though private developers accelerate decision cycles on medium-scale commercial builds.
Brazil's ABNT technical standards, Mexico's NOM construction regulations, and Chile's OGUC urban planning codes collectively shape material specifications, seismic design requirements, and environmental permitting timelines. Compliance with these overlapping frameworks determines market access for foreign contractors and equipment suppliers. Stakeholders must monitor fiscal capacity shifts in federal infrastructure budgets and emerging subnational green procurement rules.
Market Dynamics
Federal infrastructure budgets across Brazil, Mexico, and Chile are tightening fiscal capacity while green procurement mandates at subnational levels are rewriting material specifications and contractor qualification criteria.
Growth Catalysts
- LEED-Aligned Green Building Codes:Municipal sustainability mandates in São Paulo and Mexico City are accelerating demand for low-carbon concrete and certified structural steel across commercial high-rise developments.
- Brazil:Expanding mortgage access through Caixa Econômica Federal's Casa Verde e Amarela program is pulling residential construction volume in secondary cities beyond São Paulo and Rio de Janeiro.
- Cross-Laminated Timber:Engineered wood products certified under ABNT NBR 15575 are penetrating mid-rise residential markets as developers seek lighter seismic-load alternatives to reinforced masonry.
Market Restraints
- Cement Input Cost Volatility:Energy-intensive clinker production faces natural gas price spikes tied to Argentine pipeline supply disruptions, compressing margin pools for ready-mix suppliers.
- Structural Steel Supply Concentration:Import dependence on Chinese H-beam and rebar shipments creates vulnerability to tariff volatility under Brazil's Camex administrative trade measures.
- Seismic Design Complexity:Chile's OGUC urban planning codes impose rigorous soil-structure interaction studies that extend permitting timelines by 8-14 months for high-rise projects in Santiago's alluvial basin.
Strategic Opportunities
- Colombia's Infrastructure Gap:The 4G and 5G highway concession programs offer entry points for contractors with ISO 14001 certification and experience in mountainous terrain tunneling.
- Peru's Mining-Linked Construction:Copper and lithium project expansions in the Andean corridor are generating demand for remote-site worker housing and processing plant infrastructure.
- Digital Twin Integration:Convergence of BIM platforms with IoT sensor networks is enabling predictive maintenance contracts for transport megaprojects, shifting revenue models toward lifecycle service arrangements.
Industry Challenges
- ISO 14001 Certification Bottleneck:Limited accredited auditors in Central America are creating 6-9 month qualification delays for contractors bidding on Panamanian public-private partnership tenders.
- Legacy Equipment Integration:Retrofitting GPS-guided earthmoving fleets with telematics systems compatible with existing maintenance depots demands capital outlays that strain mid-tier contractor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Construction Market |
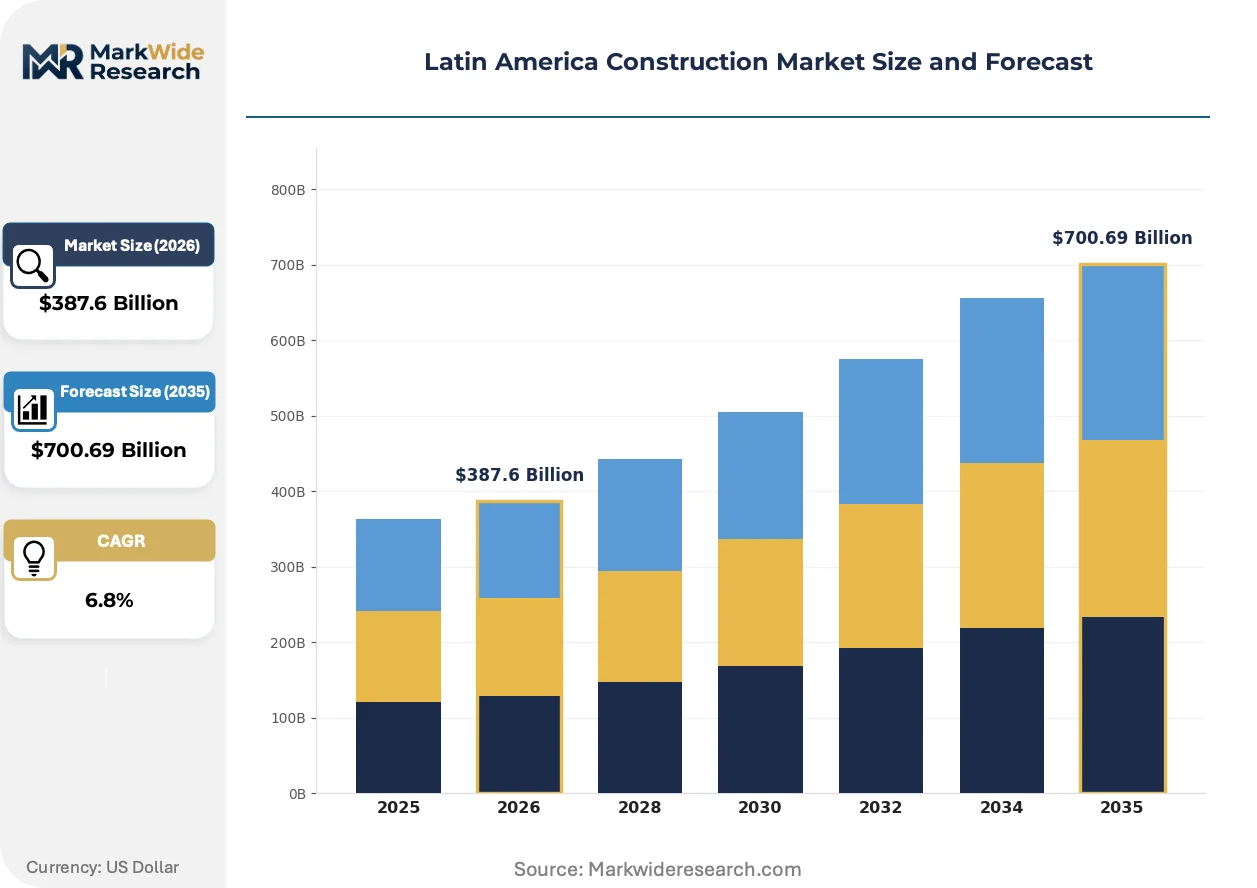
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: Residential, Commercial, Industrial, Infrastructure Material Type: Cement, Steel, Wood, Glass End User: Contractors, Developers, Government, Investors Project Size: Small, Medium, Large, Mega |
| Companies Covered | Andrade Gutierrez S.A., Mota-Engil, Sigdo Koppers, Construtora Camargo Correa, SalfaCorp S.A., Techint Engineering & Construction, Empresa ICA, Constructora Meco S.A. (MECO), Grupo Carso, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Construction Market Strategic Shifts
Material substitution pressures and digital workflow adoption are compressing traditional construction timelines while elevating technical qualification barriers for market participation across Latin America's major economies.
Geopolymer concrete formulations utilizing fly ash and slag substitutes are displacing ordinary Portland cement in foundation and structural applications across Brazil's commercial sector. Developers targeting LEED Gold certification in São Paulo and Belo Horizonte are specifying these binders to reduce embodied carbon footprints. The displacement is compressing demand for traditional clinker imports and reshaping supplier relationships toward industrial waste stream partnerships.
Mexico's NOM-020-ENER-2011 energy efficiency standards for buildings are mandating thermal performance upgrades in envelope systems. The regulation is forcing specification changes toward high-performance glazing and insulated precast panels in the Mexico City-Querétaro infrastructure corridor. Commercial developers are responding by pre-qualifying facade subcontractors based on blower door test capabilities and thermal bridge modeling expertise.
Public-sector procurement agencies in Chile and Colombia are consolidating contractor pre-qualification around integrated design-build capabilities rather than traditional separated contracts. The consolidated bidding model is favoring firms with in-house engineering and environmental permitting teams. Santiago's Ministry of Public Works and Bogotá's IDU urban development authority are the most advanced in this transition, with Rio de Janeiro's state government trailing by approximately 18-24 months.
Latin America Construction Market Segmentation
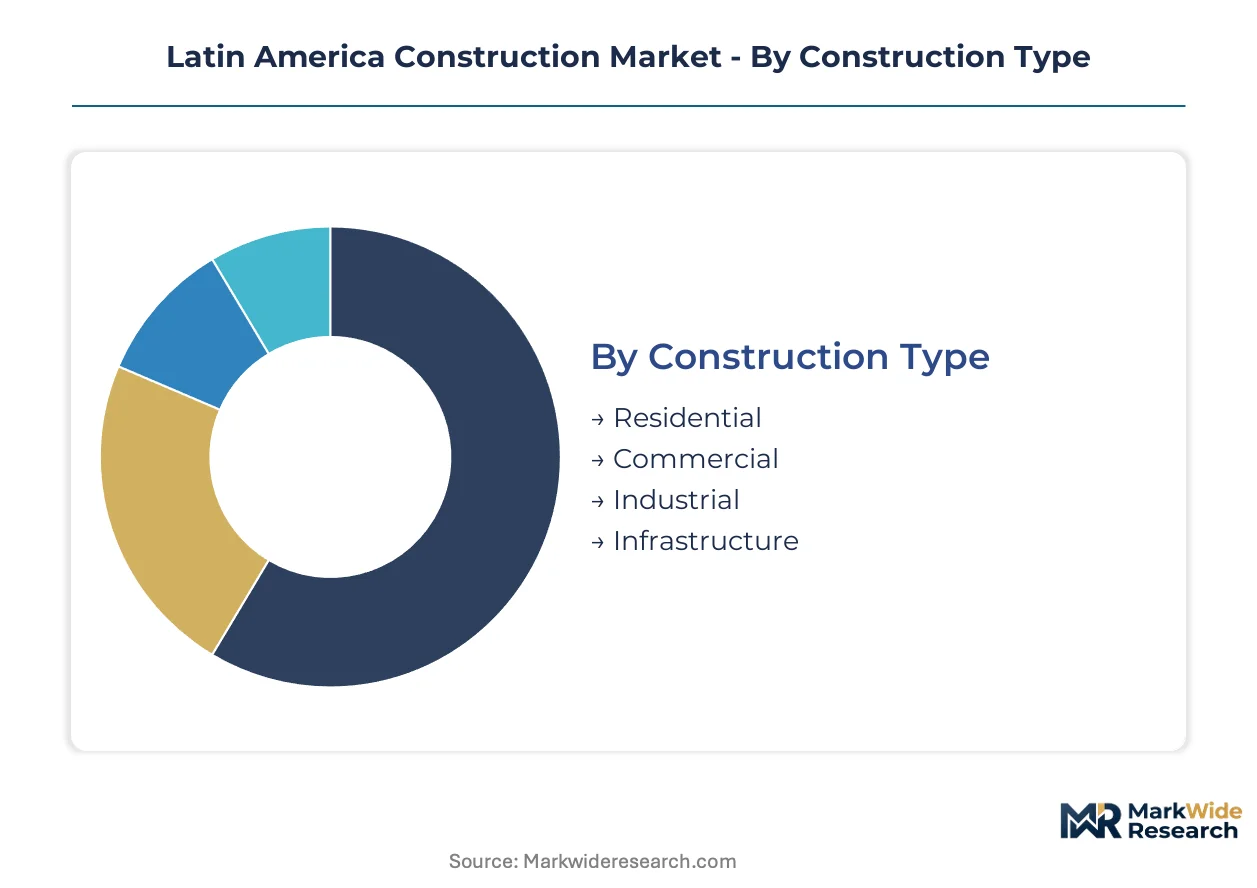
Construction type segmentation determines regulatory compliance pathways across Brazil's ABNT standards, Mexico's NOM regulations, and Chile's OGUC codes. Material specifications and project scale thresholds trigger distinct permitting timelines and contractor qualification requirements in each national jurisdiction.
Construction Type:
Brazil's Casa Verde e Amarela program, Mexico's INFONAVIT mortgage expansion, and Chile's MINVU housing subsidies each impose divergent technical standards on residential versus commercial execution.
- Residential:Multi-family and single-family dwellings utilizing reinforced masonry and concrete frame systems. Brazil's secondary cities beyond São Paulo and Rio de Janeiro concentrate volume through Caixa Econômica Federal financing, though seismic design requirements under NBR 15421 elevate foundation costs in high-risk zones.
- Infrastructure:Transport, energy, and water megaprojects commanding extended payment guarantees and ISO 14001 pre-qualification. Colombia's 4G and 5G highway concessions and Peru's mining-corridor expansions anchor demand for tunneling and bridge specialists.
- Commercial:Office towers, retail centers, and hospitality developments specifying high-performance glazing and HVAC integration. Mexico City-Querétaro corridor projects face NOM-020-ENER-2011 thermal envelope mandates.
- Industrial:Manufacturing facilities, processing plants, and logistics warehouses requiring heavy slab foundations and crane-ready steel framing. Techint Engineering & Construction anchors execution in Argentine and Brazilian oil-gas-linked industrial zones.
Established volume favors Residential; emerging adoption favors Infrastructure.
Material Type:
Cost tier differentiation separates commodity-grade inputs from certified low-carbon alternatives required for LEED-aligned municipal mandates.
- Cement:Portland and blended cements dominating foundation and structural applications across the region. Fly ash and slag-based geopolymer formulations displace traditional clinker in São Paulo commercial developments seeking embodied carbon reductions.
- Steel:Structural H-beams, rebar, and cold-formed sections for high-rise and industrial frames. Import dependence on Chinese mill shipments creates tariff exposure under Brazil's Camex administrative measures, compressing margin pools for distributors.
- Wood:Cross-laminated timber and glulam beams certified under ABNT NBR 15575 penetrating Brazilian mid-rise residential markets as lighter seismic-load alternatives.
- Glass:Curtain wall and high-performance glazing systems mandated by Mexico's energy efficiency standards for commercial envelope assemblies.
Commodity cement maintains volume dominance; certified low-carbon steel and engineered wood are climbing the fastest.
End User:
Customer type determines procurement complexity, with government gatekeeping slowing award cycles while private developers compress decision timelines.
- Government:Federal and subnational agencies controlling mega-project awards through consolidated design-build tenders. Chile's Ministry of Public Works and Bogotá's IDU urban development authority lead procurement modernization.
- Developers:Private residential and commercial sponsors leveraging pre-qualification relationships to accelerate permitting. Brazil's residential developers exploit Caixa Econômica Federal mortgage liquidity to scale secondary-city projects.
- Contractors:General and specialty construction firms bidding on separated or integrated contracts based on in-house engineering depth.
- Investors:Pension funds, infrastructure funds, and sovereign wealth vehicles structuring long-dated concession finance for transport and energy assets.
Government gatekeeping secures Infrastructure margins; Developer agility captures Residential and Commercial velocity.
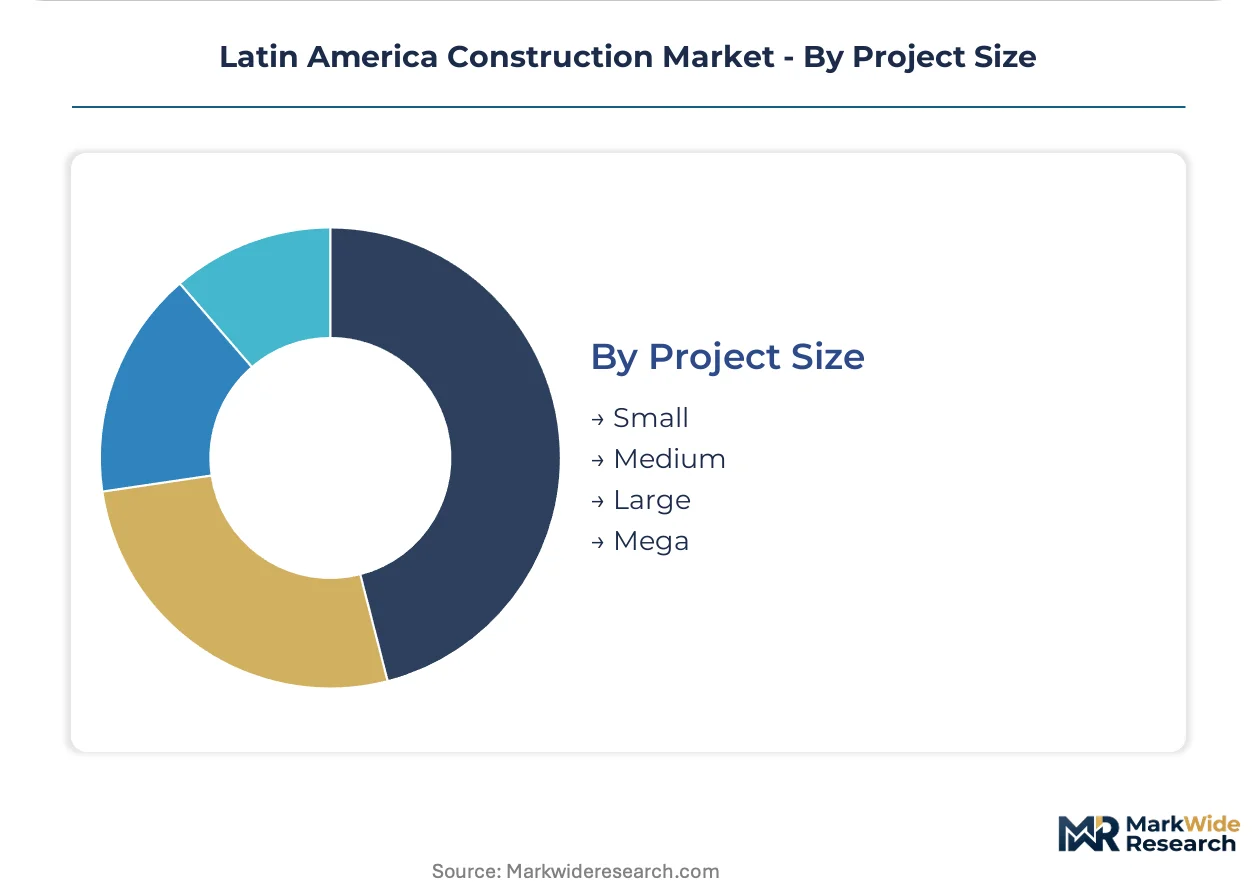
Project Size:
Scale thresholds trigger distinct environmental impact assessment requirements and contractor bonding capacities across national regulatory regimes.
- Mega:Projects exceeding 500 million USD requiring multi-year execution, international consortium formation, and political risk insurance. Brazil's pre-salt logistics corridors and Colombian 5G highway segments exemplify this tier.
- Large:Developments between 50-500 million USD anchoring contractor revenue stability through phased payment schedules. Santiago high-rise towers in alluvial basin zones face extended OGUC soil-structure study timelines.
- Medium:Projects between 5-50 million USD enabling mid-tier contractor participation with reduced bonding requirements. Mexico City-Querétaro corridor commercial builds concentrate in this tier.
- Small:Sub-5 million USD residential and light commercial work dominated by local builders with limited ISO certification penetration.
Mega-project concentration favors integrated engineering firms; Medium-scale agility opens pathways for specialized regional contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mexico City-Querétaro high-speed rail corridor anchors Mexico's infrastructure expansion while Brazil's pre-salt logistics networks and Colombia's 5G highway concessions concentrate capital deployment across the region's three largest economies.
Brazil
Caixa Econômica Federal's Casa Verde e Amarela mortgage program is pulling residential construction into secondary cities beyond São Paulo and Rio de Janeiro. ABNT NBR 15421 seismic standards elevate foundation costs in high-risk zones. The São Paulo metropolitan corridor dominates commercial high-rise development as developers specify geopolymer concrete for LEED-aligned municipal mandates.
Mexico
The INFONAVIT mortgage expansion and nearshoring-driven industrial facility demand are accelerating construction velocity in the Bajío Region. NOM-020-ENER-2011 energy efficiency standards mandate thermal envelope upgrades for commercial buildings. The Mexico City-Querétaro infrastructure corridor concentrates specification changes toward high-performance glazing and insulated precast panels.
Chile
MINVU housing subsidies and copper-mining-linked processing plant expansions are generating dual-track demand for residential and industrial construction. OGUC urban planning codes impose rigorous soil-structure interaction studies that extend permitting timelines by 8-14 months for Santiago high-rises in alluvial basin zones. The Santiago metropolitan area anchors design-build procurement consolidation led by the Ministry of Public Works.
Colombia
The 5G highway concession program and Bogotá metro expansion are creating entry points for tunneling specialists with ISO 14001 certification. IDU urban development authority procurement modernization favors integrated design-build capabilities over traditional separated contracts. The Andean corridor between Bogotá and Medellín concentrates mountainous terrain infrastructure awards.
Peru
Copper and lithium project expansions in the Andean corridor are generating demand for remote-site worker housing and processing plant infrastructure. The national environmental certification framework shapes contractor pre-qualification for mining-linked construction. The Lima-Callao metropolitan area and southern mining provinces anchor industrial facility development.
Latin America Construction Market Competitive Environment
Listed leaders compete with private specialists across capital access and project scale dimensions. The Latin America construction market structures around a tiered competitive landscape where integrated engineering conglomerates, regional specialists, and international contractors divide project awards by complexity and geographic scope. Three archetypes dominate: Portuguese-language corridor specialists leveraging Africa-Latin America expertise, heavy industrial execution firms anchored in oil-gas-mining infrastructure, and integrated domestic conglomerates with energy-transport megaproject capabilities. Consolidated bidding models and ISO 14001 certification requirements are reshaping competitive positioning while design-build integration and environmental permitting depth emerge as decisive qualification factors.
Among Portuguese-language market specialists, Mota-Engil occupies a position exemplifying Africa-Latin America corridor expertise. Techint Engineering & Construction represents the heavy industrial execution archetype particularly in oil, gas, and mining infrastructure. Andrade Gutierrez S.A. anchors the integrated domestic conglomerate tier with capabilities spanning energy and transport megaprojects.
| Leading Market Players |
|---|
| Andrade Gutierrez S.A. |
| Mota-Engil |
| Sigdo Koppers |
| Construtora Camargo Correa |
| SalfaCorp S.A. |
| Techint Engineering & Construction |
| Empresa ICA |
| Constructora Meco S.A. (MECO) |
| Grupo Carso |
| Others |
Value Chain & Pricing Dynamics
Clinker kiln capacity utilization above 85 percent in southeastern Brazil concentrates pricing power among integrated cement producers while compressing margin pools for ready-mix distributors dependent on spot market purchases. Scale economies in geopolymer concrete production are reshaping supplier relationships toward industrial waste stream partnerships that alter traditional price floors for foundation-grade materials.
Pricing Analysis
Certification level creates the primary spread between qualified and non-qualified bidders for public-private partnerships. Project-based contract pricing dominates mega-infrastructure awards, with ISO 14001 pre-qualification commanding premium positioning against uncertified competitors. Cost compression in commodity cement runs through energy-intensive clinker production exposed to Argentine natural gas pipeline volatility. Government procurement entities show lowest price sensitivity due to long-dated payment guarantees, while mid-tier commercial developers face acute pressure from mortgage liquidity constraints.
Supply Chain Analysis
Just-in-time delivery preferences clash with strategic stockpiling of Chinese H-beam and rebar inventories among Brazilian distributors hedging Camex administrative tariff exposure. Geographic supply concentration centers on China for structural steel, domestic Brazil for Portland cement, and Chile for copper-intensive electrical infrastructure. Raw material dependencies include fly ash from thermal power plants, slag from steelmaking operations, and imported rebar for seismic-resistant framing. Single-source vulnerability pervades Chinese mill shipments under trade remedy investigations. Distribution runs through consolidated ready-mix networks in São Paulo and project-specific direct sourcing for Andean mining corridor developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated government procurement agencies consolidating design-build tenders, fragmenting access for contractors lacking integrated engineering depth.
For Market Incumbents: Fortify ISO 14001 certification maintenance and backward integration into geopolymer binder production to defend margin position against cross-laminated timber substitution in mid-rise residential markets. Anchor capacity in the Mexico City-Querétaro corridor where NOM-020-ENER-2011 thermal envelope mandates create specification stickiness for high-performance glazing subcontractors. For New Entrants and Emerging Players: Differentiate on digital twin integration capabilities for predictive maintenance contracts in Colombian 5G highway concessions. Target Peru's mining-linked remote-site worker housing segment where environmental certification requirements remain less stringent than Chilean or Brazilian benchmarks. Pursue white-label BIM platform partnerships with established regional contractors seeking IoT sensor network deployment without internal R&D overhead. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contractors with captive geopolymer concrete formulation expertise and in-house environmental permitting teams. Five-to-ten year viability hinges on exposure to subnational green procurement rule acceleration rather than federal infrastructure budget cyclicality. Acquisition candidates should demonstrate IDU or Ministry of Public Works design-build track records. The signal to watch is Bogotá metro expansion contractor shortlist announcements indicating procurement modernization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14001 Certification Investment | Unlocks Panamanian and Colombian public-private partnership bidding tiers previously inaccessible. |
| Geopolymer Concrete Formulation Partnership | Secures fly ash supply contracts with Brazilian thermal generators for embodied carbon reduction. |
| Digital Twin Platform Integration | Enables lifecycle service revenue models for Chilean Ministry of Public Works transport assets. |
| Cross-Laminated Timber Certification | Captures ABNT NBR 15575-compliant mid-rise residential share from reinforced masonry incumbents. |
| Andean Mining Corridor Expansion | Positions contractors for Peru copper-lithium project remote-site infrastructure awards. |
Study Parameters
Initial hypotheses were tested against primary input from project development officers at federal infrastructure agencies, procurement leads at subnational urban development authorities, EPC contractor bid estimation teams, and ready-mix supplier commercial directors, then refined through secondary validation against ANVISA regulatory filings, ABNT technical standards documentation, SEC 10-K disclosures from listed construction conglomerates, and customs records of Chinese steel import flows. Bottom-up project pipeline aggregation was triangulated against top-down federal budget appropriation analysis.
Variance decomposition across construction type, material specification grade, project scale tier, and national regulatory jurisdiction shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating mortgage liquidity expansion rates, green building code adoption curves, and mining capital expenditure cycles. Industry-specific forecast inputs included Caixa Econômica Federal disbursement velocity indices and Colombian 4G/5G concession award timelines.
The analysis sits within stated boundaries; outcomes outside sustained federal infrastructure budget execution or accelerated subnational green procurement mandate enforcement would require recalibration. Forecasts reflect assumptions regarding Argentine natural gas supply stability and Chinese steel trade policy continuity. Revision becomes warranted when seismic design code amendments in Chile or Mexico alter foundation cost structures beyond modeled thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Bangladesh Construction Market
Building Construction
Guatemala Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
India Commercial Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
India Prefabricated Buildings Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Middle East Building Construction Market
Building Construction
Construction Market
Building Construction
Sweden New Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Egypt Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Indonesia Infrastructure Market
Building Construction
North America Modular Construction Market
Building Construction
China Modular Construction Market