
 China Construction Market | 2026-2036
China Construction Market Size, Share, and Industry Trends Forecast 2026-2036
China Construction Market Analysis
The gap between premium smart infrastructure and conventional commodity construction is shifting project economics across China's built environment. China State Construction Engineering Corporation leverages its state-backed balance sheet to dominate mega-transit hubs, while China Communications Construction Group anchors coastal port and bridge development through specialized marine engineering capabilities. Shanghai Construction Group competes in the premium tier by controlling high-rise commercial delivery in the Yangtze Delta corridor.
China Construction encompasses the planning, design, material procurement, assembly, and commissioning of buildings and civil infrastructure using concrete, structural steel, and composite systems engineered to GB seismic and fire-resistance specifications. Its primary purpose spans residential habitation, commercial activity, industrial production, and public service delivery across urban and rural territories. Residential and infrastructure project types absorb the deepest capital pools, though green building methods are gaining fastest as MEE emissions enforcement tightens. Prefabrication methods concentrate margin capture where steel and composite material sourcing meets factory-controlled quality standards.
MIIT building energy codes, MEE environmental impact assessments, and SAMR construction material safety standards collectively raise compliance costs while filtering out undercapitalized regional contractors. NMPA certification protocols for structural components now extend to imported composite systems, reshaping procurement channels for foreign material suppliers. Stakeholders must monitor how dual carbon enforcement timelines alter cement and steel intensity rules before committing to long-dated project portfolios.
Market Dynamics
Dual carbon enforcement timelines are compressing project approval windows across China's construction sector, forcing contractors to front-load green material certification and energy modeling before breaking ground.
Growth Catalysts
- MIIT Green Building Mandates:Factory certification requirements for prefabricated steel components are channeling capital toward automated production lines that slash on-site labor intensity.
- Yangtze River Delta Urban Renewal:Shanghai's satellite city integration absorbs disproportionate infrastructure allocation, concentrating demand for transit-linked mixed-use development.
- MEE Emissions Enforcement:Tighter cement and steel intensity rules are accelerating substitution toward low-carbon concrete formulations and recycled aggregate systems.
Market Restraints
- Imported Composite Certification:NMPA protocols now extend to foreign structural components, creating procurement friction for offshore material suppliers unfamiliar with GB testing regimes.
- Regional Contractor Filtering:SAMR construction material safety standards raise compliance costs that undercapitalized provincial players cannot absorb, consolidating bid pools.
- Specialized Marine Engineering Bottleneck:Coastal port and bridge development faces capacity constraints where deep-water pile driving and corrosion-resistant alloy sourcing concentrate in limited yards.
Strategic Opportunities
- Greater Bay Area Water Infrastructure:Municipal governments in Guangdong prioritize wastewater treatment and flood control systems under tighter environmental compliance timelines.
- Digital Twin Integration:Convergence of BIM platforms with IoT sensor networks enables predictive maintenance contracts that extend contractor revenue streams past commissioning.
- Green Bond Financing Channels:Policy bank lending preferences for certified low-carbon projects unlock cheaper capital for developers meeting MEE pre-approval standards.
Industry Challenges
- GB Seismic Code Talent Scarcity:Structural engineers with dual expertise in high-rise design and performance-based seismic analysis command premiums that strain mid-tier firm payrolls.
- Prefabrication Capex Burden:Automated steel and composite production lines require nine-figure upfront investment before securing municipal offtake commitments.
- Legacy System Integration:BIM adoption clashes with paper-based permitting workflows at county-level housing authorities, delaying project starts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Construction Market |
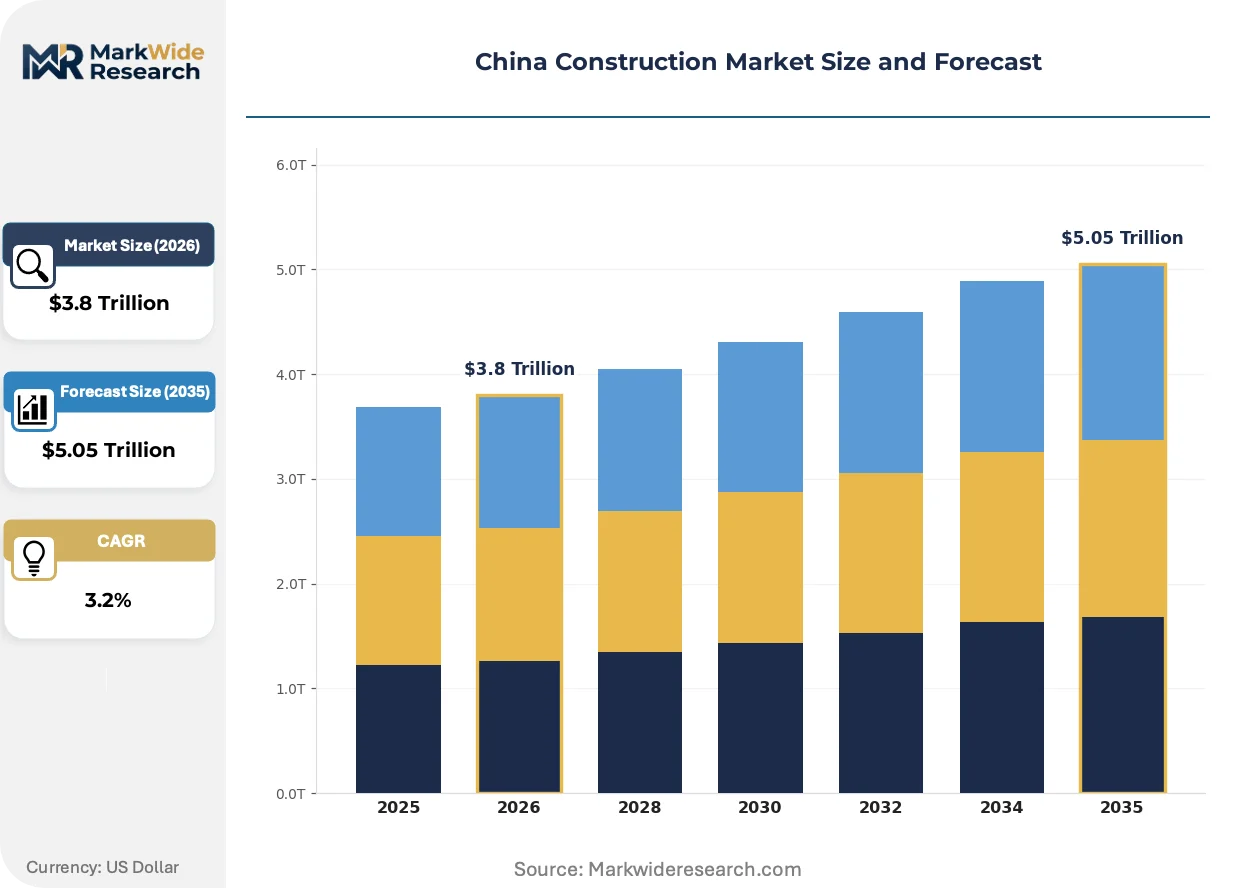
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $5.05 Trillion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Construction Method: Modular, Traditional, Prefabrication, Green Building Material Type: Cement, Steel, Wood, Composite Client Type: Government, Private Sector, Developers, Investors |
| Companies Covered | China Communications Construction Group, China Metallurgical Group Corporation, China State Construction Engineering Corporation, Shanghai Construction Group, China Energy Engineering Corporation, China Railway Group Limited, Power Construction Corporation of China, Shaanxi Construction Engineering Group, China Railway Construction Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Construction Market Emerging Trajectories
Construction methods across China's built environment are bifurcating between premium smart infrastructure and conventional commodity delivery, with technology adoption curves diverging by project scale and ownership structure.
Modular steel-composite hybrid systems are rewriting project economics for high-rise commercial towers in the Yangtze Delta corridor. Shanghai Construction Group and state-backed developers are specifying factory-cured floor cassettes that cut structural steel waste and compress floor-cycle times. The technology is compressing traditional cast-in-place concrete market share in premium segments where GB fire-resistance certification can be pre-validated off-site.
MIIT building energy codes now mandate real-time energy monitoring for public buildings exceeding 20,000 square meters, forcing MEP contractors to spec IoT-enabled HVAC and lighting control networks. The industrial consequence is a qualification split between integrators with software development capabilities and traditional mechanical installers. Commercial office developers in Beijing and Shenzhen are responding by bundling smart building warranties into lease agreements.
Buyer concentration among state-owned developers is consolidating procurement leverage, compressing subcontractor margins and extending payment cycles to 180 days or more. Tier-1 general contractors now demand performance bonds and material pre-financing from mid-tier suppliers that lack state-backed balance sheets. The shift is most visible in infrastructure megaprojects where China State Construction Engineering Corporation and China Communications Construction Group dominate bid pools.
China Construction Market Segmentation
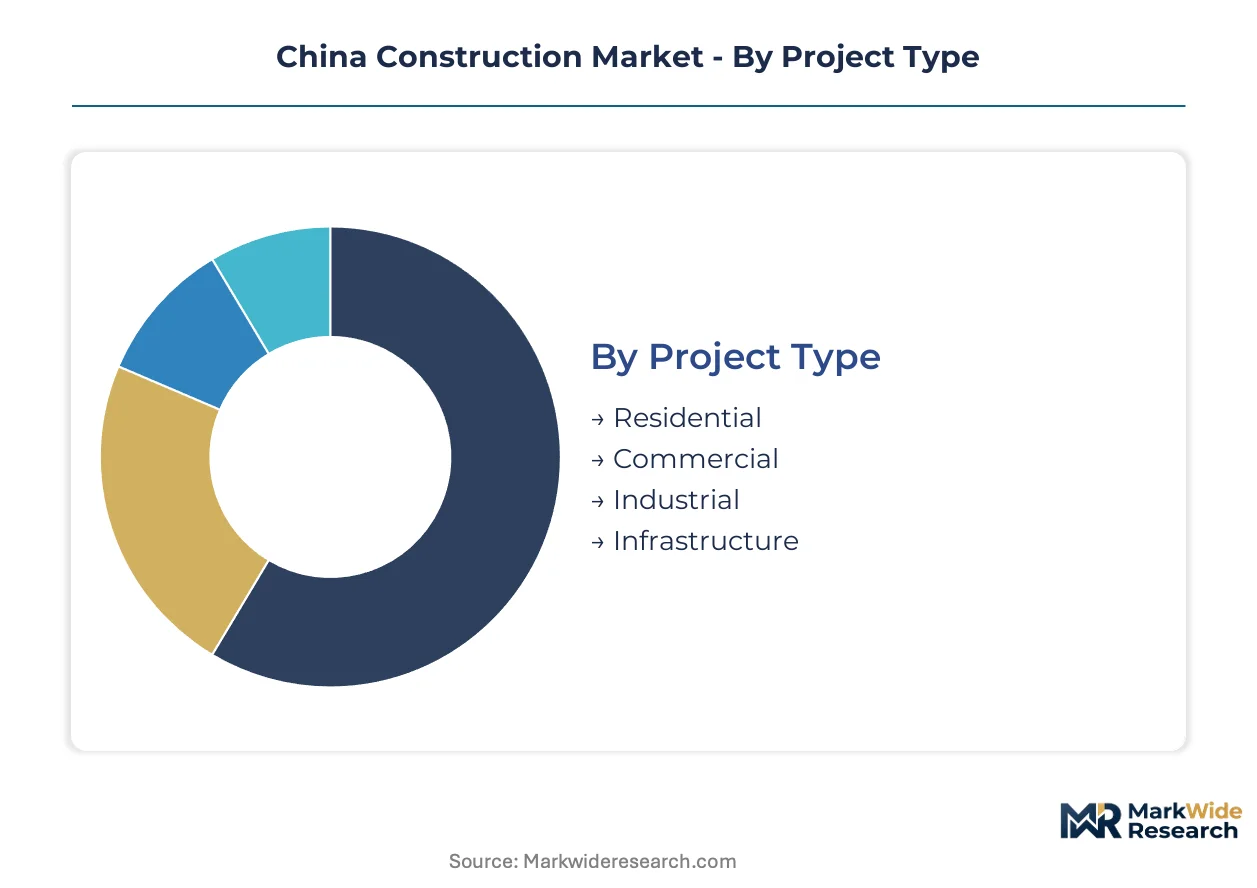
Construction demand across China fragments along four critical dimensions that determine procurement patterns, compliance burdens, and margin structures. Project type and construction method classifications dictate capital intensity and regulatory exposure, while material and client type segments reveal where pricing power concentrates.
Project Type:
Standardized public infrastructure procurement contrasts with bespoke residential and commercial development where design flexibility commands premium pricing.
- Infrastructure:Transit corridors, water systems, and energy grids absorb the deepest capital pools under MIIT green building mandates. Yangtze River Delta municipalities front-load environmental compliance to secure approval windows.
- Residential:High-rise towers and satellite city housing clusters dominate volume, though prefabrication adoption varies sharply between premium Shanghai developments and commodity provincial stock.
- Commercial:Mixed-use towers in Beijing and Shenzhen bundle smart building warranties into lease agreements, requiring IoT-enabled MEP integration.
- Industrial:Factory and logistics facilities face dual carbon enforcement timelines that compress steel intensity allowances.
Leading the category by volume: Infrastructure. Growing fastest: Residential smart building retrofits.
Construction Method:
Cost tier stratification separates capital-intensive factory automation from labor-dependent site assembly, with compliance thresholds acting as the sorting mechanism.
- Green Building:MIIT energy codes and MEE emissions enforcement now mandate real-time monitoring for public buildings exceeding 20,000 square meters, forcing HVAC and lighting network upgrades.
- Prefabrication:Factory-cured steel and composite components slash on-site labor intensity while satisfying GB fire-resistance certification through pre-validation.
- Modular:Steel-composite hybrid floor cassettes compress structural waste and accelerate floor-cycle times in Yangtze Delta high-rise commercial towers.
- Traditional:Cast-in-place concrete retains share in provincial markets where automated production line investment remains uneconomical.
Green Building commands the steepest expansion trajectory as dual carbon deadlines tighten. Traditional methods retain dominant share in county-level housing approvals.
Material Type:
Supply concentration around coastal steel mills and northern cement clinker capacity shapes regional contractor qualification tiers.
- Steel:Structural sections and rebar face intensity rule compression under MEE enforcement, accelerating substitution toward recycled content formulations.
- Cement:Clinker production concentrates in Shanxi and Henan provinces where environmental compliance costs filter out undercapitalized regional suppliers.
- Composite:NMPA certification protocols now extend to imported structural systems, creating procurement friction for offshore suppliers unfamiliar with GB testing regimes.
- Wood:Cross-laminated timber gains niche traction in low-rise commercial and institutional projects where seismic performance requirements permit.
Steel leads by tonnage deployed. Composite materials gain share fastest in premium commercial specifications.
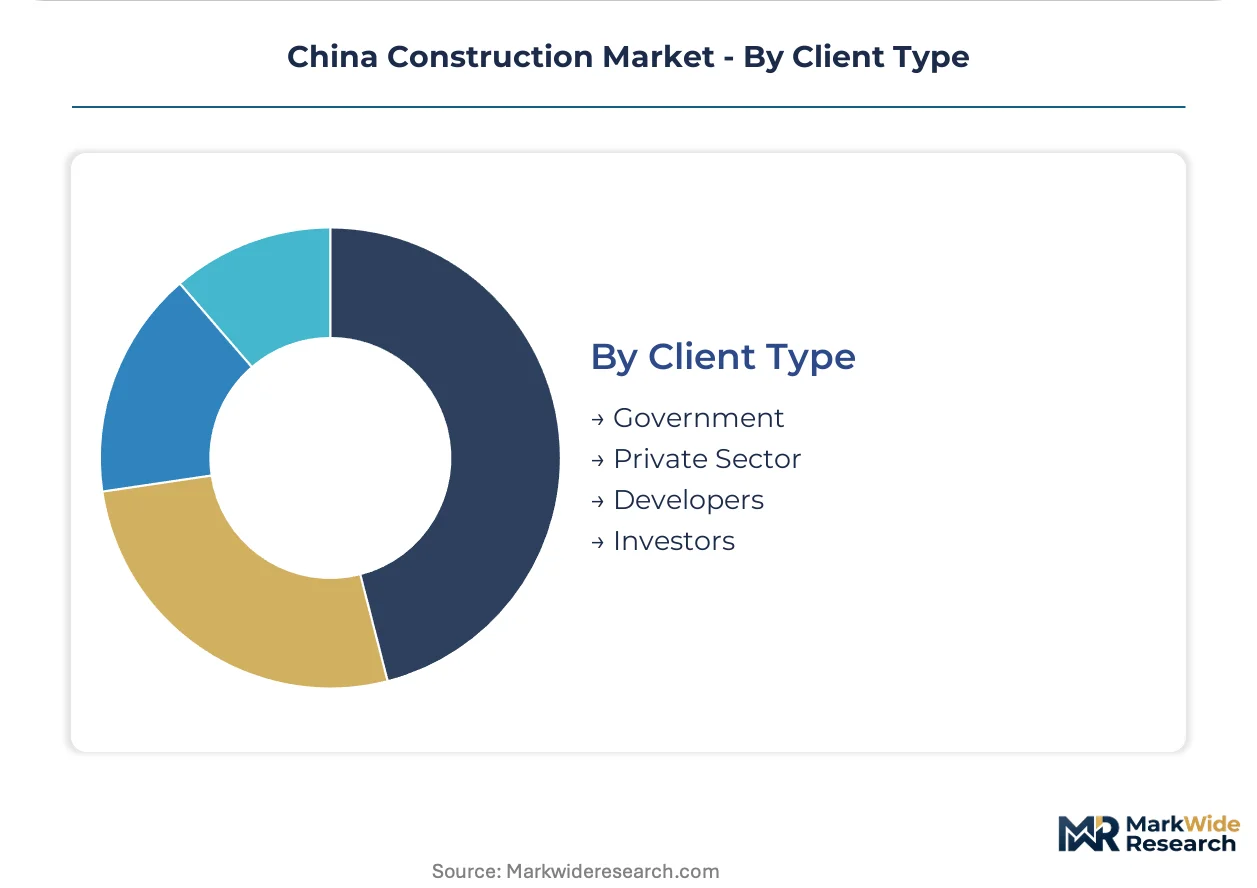
Client Type:
Payment cycle duration and performance bond requirements divide state-backed balance sheet strength from private capital constraints.
- Government:Municipal procurement of transit and water systems prioritizes environmental compliance under tightening MEE timelines, consolidating bid pools around state-owned contractors.
- Developers:Tier-1 general contractors demand material pre-financing and extended payment cycles stretching 180 days, compressing subcontractor margins.
- Private Sector:Corporate headquarters and retail developers in Beijing and Shenzhen specify smart building integration to differentiate lease terms.
- Investors:Green bond financing channels unlock cheaper capital for projects meeting MEE pre-approval standards, reshaping portfolio construction.
Government clients dominate by project value. Investor participation climbs fastest as policy bank lending preferences shift toward certified low-carbon developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors construction capital allocation across the Yangtze River Delta, absorbing disproportionate infrastructure investment through satellite city integration and urban renewal corridors.
Yangtze River Delta
Transit-linked mixed-use development absorbs the deepest capital pools as municipal governments prioritize environmental compliance under tightening MEE timelines. MIIT green building mandates channel prefabricated steel component orders toward automated production lines. Shanghai Construction Group dominates high-rise commercial delivery across the corridor.
Pearl River Delta
Greater Bay Area water infrastructure procurement accelerates as Guangdong municipalities prioritize wastewater treatment and flood control systems. MEE emissions enforcement compresses cement and steel intensity allowances for industrial facility construction. Shenzhen smart building integration requirements reshape MEP contractor qualification tiers.
Beijing-Tianjin-Hebei
Public infrastructure procurement concentrates around transit corridors and energy grid modernization under SAMR construction material safety standards. Dual carbon enforcement timelines filter undercapitalized regional contractors from bid pools. Beijing commercial office developers bundle IoT-enabled warranties into lease agreements.
Sichuan-Chongqing
Western China infrastructure expansion targets transportation connectivity and hydropower integration under GB seismic code requirements. Prefabrication adoption lags coastal corridors due to factory-cured component logistics constraints. Chongqing high-rise residential clusters drive steel demand despite lower green building penetration.
Shandong Peninsula
Port and coastal infrastructure development concentrates marine engineering capability around Qingdao and Yantai. NMPA certification protocols for corrosion-resistant alloys reshape procurement channels for specialized structural components. Regional cement clinker capacity faces environmental compliance cost pressures from Shanxi and Henan suppliers.
China Construction Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification capability and state-backed balance sheet strength. The vendor base stratifies into three tiers: state-owned enterprises with policy bank access, provincial construction groups with regional government relationships, and specialized marine engineering contractors with deep-water pile driving capability. Dominant competitive moves include automated production line investment for prefabrication capacity and strategic partnerships with municipal governments for transit-linked development rights.
Within the state-owned enterprise tier, China State Construction Engineering Corporation and China Communications Construction Group occupy positions defined by mega-project execution capability and policy bank financing access. Shanghai Construction Group represents the premium-tier specialist archetype through Yangtze Delta commercial high-rise concentration. China Railway Group Limited and Power Construction Corporation of China anchor infrastructure-specific bidding pools where specialized engineering qualifications filter competition.
| Leading Market Players |
|---|
| China Communications Construction Group |
| China Metallurgical Group Corporation |
| China State Construction Engineering Corporation |
| Shanghai Construction Group |
| China Energy Engineering Corporation |
| China Railway Group Limited |
| Power Construction Corporation of China |
| Shaanxi Construction Engineering Group |
| China Railway Construction Corporation |
| Others |
Supply Flow & Price Mechanics
State-owned developer concentration in municipal transit and water procurement compresses subcontractor margins through extended payment cycles and performance bond demands. Tier-1 general contractors exploit balance sheet asymmetry to extract material pre-financing commitments from mid-tier suppliers lacking policy bank access.
Pricing Analysis
Outcome-based pricing anchors premium commercial towers where smart building warranties bundle IoT-enabled MEP performance guarantees into lease agreements. Three-tier pricing structure across premium, standard, and economy levels separates green-certified projects from conventional builds and commodity provincial stock. Cost compression in the mid-tier intensifies because SAMR safety standards filter undercapitalized regional players from bid pools. Provincial housing authorities exhibit highest price sensitivity, while Beijing and Shenzhen corporate developers absorb premiums for digital twin integration.
Supply Chain Analysis
Skilled technician scarcity in Shanxi and Henan cement clinker operations constrains output expansion despite environmental compliance cost pressures. Structural steel sourcing centers on coastal mills in Jiangsu and Hebei, while composite component fabrication concentrates in Guangdong export zones. The chain draws from imported corrosion-resistant alloys for marine engineering, low-carbon concrete formulations, and factory-cured prefabricated cassettes. Single-source vulnerability sits with deep-water pile driving capacity concentrated in limited Qingdao and Yantai yards. Distribution runs through state-owned contractor procurement portals with 180-day payment terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual carbon enforcement timelines and MIIT green building mandates are forcing a consolidation play as compliance costs extinguish undercapitalized provincial contractors. SAMR safety standards and NMPA certification protocols act as structural filters, concentrating viable bid capacity around state-backed balance sheets.
For Market Incumbents: Hedge margin erosion by securing automated prefabrication lines in Yangtze Delta corridors before municipal offtake commitments harden. Backward integration into low-carbon cement and recycled steel aggregate sourcing defends against MEE intensity rule compression. Channel control through exclusive digital twin platform partnerships with Beijing and Shenzhen developers locks in recurring predictive maintenance revenue.
For New Entrants and Emerging Players: BIM-to-IoT convergence software offers a technology-first wedge into mid-tier MEP contractor qualification gaps where traditional mechanical installers lack software development capabilities. Target county-level housing authorities in Sichuan-Chongqing where paper-based permitting workflows delay project starts and legacy system integration creates procurement friction. Lead with rapid commissioning guarantees and simplified GB fire-resistance pre-validation to bypass incumbent factory certification advantages.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized marine engineering contractors with deep-water pile driving capability in Shandong Peninsula corridors where coastal port development faces capacity bottlenecks. Long-term viability hinges on exclusive municipal relationships for transit-linked development rights and automated production line deployment ahead of green bond financing preference shifts. Watch MEE pre-approval standard adoption rates as the inflection signal for policy bank lending flow redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Prefabrication Line Investment | Factory-cured steel cassettes satisfy MIIT green mandates while compressing on-site labor intensity. |
| Digital Twin Platform Integration | BIM-IoT convergence enables predictive maintenance contracts extending revenue past commissioning. |
| Low-Carbon Material Backward Integration | Captive supply of recycled aggregate and low-clinker cement defends against MEE intensity rules. |
| Municipal Transit-Linked Development Rights | Exclusive satellite city integration agreements in Yangtze Delta anchor multi-year project pipelines. |
| GB Seismic Code Certification Investment | Performance-based structural engineering capabilities command premiums in high-rise commercial segments. |
Methodological Framework
Document review covered MIIT building energy code filings, MEE environmental impact assessment databases, and SAMR construction material safety standards, complemented by interviews with tier-1 general contractor procurement directors, prefabrication facility plant managers, municipal infrastructure planning officers, and green bond structuring specialists at policy banks. Secondary validation drew from customs trade data on structural steel and composite component flows, provincial housing authority permitting statistics, and state-owned enterprise annual procurement disclosures. Bottom-up project pipeline aggregation and top-down sectoral expenditure analysis were triangulated against regulatory timeline assumptions.
Market size outputs and growth trajectories across the analysis window reflect segment-level modeling of project type, construction method, material category, and client archetype interactions. CAGRs were derived from municipal capital expenditure budget trajectories, green building certification velocity, and prefabrication adoption curves. Industry-specific forecast inputs incorporated dual carbon enforcement timeline scenarios and NMPA certification protocol expansion schedules for imported structural systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE emissions rule acceleration or sudden cement clinker capacity shutdowns in Shanxi and Henan. Projections reflect documented assumptions on policy bank lending preference shifts and municipal approval window compression rates. Material deviation in GB seismic code talent availability or BIM-to-legacy permitting workflow integration speed warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
France Prefab Wood Building Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
South Korea Data Center Construction Market
Building Construction
Australia Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
France Prefab Homes Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
United States Commercial Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Swiss Prefabricated Buildings Market