
 Dominican Republic Construction Market | 2026-2036
Dominican Republic Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Dominican Republic Construction Market Insights
Capital-intensity divergence between heavy civil specialists and mid-scale residential developers is bifurcating competitive dynamics across the Dominican Republic. Noval SRL leverages its vertical integration in concrete supply and batching plants to dominate large-scale infrastructure bids. Contratistas Civiles y Mecanicos SA anchors its position through sustained equipment fleets and long-term government contracts. Paredes y Asociados Constructora differentiates via specialized commercial and institutional builds in Santo Domingo and Santiago.
The Dominican Republic construction sector encompasses the planning, engineering, procurement, and physical assembly of buildings and infrastructure using reinforced concrete, structural steel, masonry, and glass systems engineered to seismic and hurricane-resistant standards. Its primary purpose spans shelter provision, commercial activity facilitation, and economic connectivity through transport and utility networks. Residential Buildings and Infrastructure Projects command the largest current spend pools, while Renovation applications are expanding fastest as aging stock in Santo Domingo's colonial core and 1980s commercial districts requires structural retrofitting and energy-efficiency upgrades. Commercial Structures concentrate margin in tourism-adjacent hospitality and retail formats along the eastern seaboard.
The Ministry of Public Works and Communications sets contracting rules and technical specifications for federal projects, while the Dominican Chamber of Construction coordinates industry standards and workforce certification protocols. Compliance with seismic-resistant design codes and environmental impact assessments for coastal developments shapes project timelines and material selection. Stakeholders must monitor how fiscal constraints and election-cycle funding shifts affect public works pipelines, while private developers should evaluate land-banking strategies in secondary cities as logistics and manufacturing investment spreads beyond the capital.
Market Dynamics
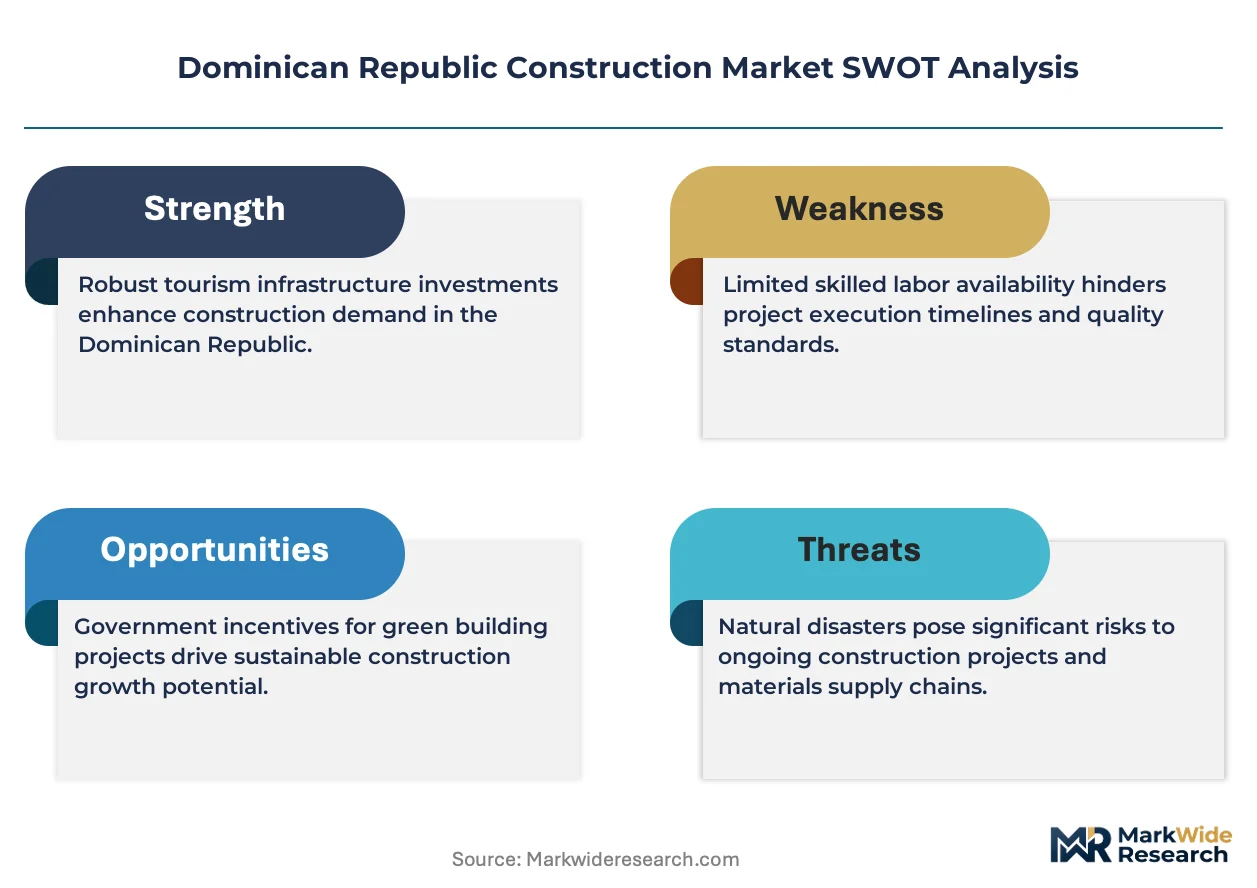
Tourism-driven resort construction along the Punta Cana corridor is compressing project timelines and reshaping material procurement patterns across the Dominican Republic, forcing contractors to synchronize concrete pours with international hospitality brand opening schedules.
Growth Catalysts
- National Housing Plan:The government's social housing initiative under the Ministry of Public Works channels federal investment into low-income residential developments across Greater Santo Domingo and secondary cities.
- Port Modernization:Caucedo and Haina port expansion projects are generating demand for marine-grade concrete and specialized civil engineering capacity.
- Hospitality Investment:All-inclusive resort developers are driving specification upgrades for hurricane-resistant glazing and seismic structural systems in the eastern provinces.
Market Restraints
- Steel Import Dependency:Reinforcing bar supply concentrates on mills in Mexico and the United States, exposing contractors to currency fluctuation and shipping cost volatility.
- Skilled Labor Scarcity:Certified welders and structural engineers command wage premiums that compress margins on fixed-price government contracts.
- Coastal Environmental Review:The Ministry of Environment's extended impact assessment timelines for beachfront projects delay permitting by eight to fourteen months.
Strategic Opportunities
- Santiago Logistics Hub:Manufacturing investment spreading north from the capital creates demand for industrial warehouse and cold-storage construction in the Cibao Valley.
- Energy Retrofit Mandate:New efficiency standards for commercial buildings over ten thousand square meters open renovation contracts in Santo Domingo's 1980s office stock.
- Modular Prefabrication:Panelized concrete systems from Spanish and Colombian suppliers are reducing on-site labor hours for mid-rise residential towers.
Industry Challenges
- Certification Bottlenecks:Dominican Chamber of Construction workforce credentialing programs lag behind project start dates, delaying crew deployment.
- Equipment Financing Access:Local banks impose collateral requirements that exclude mid-scale developers from crane and earthmover fleet expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dominican Republic Construction Market |
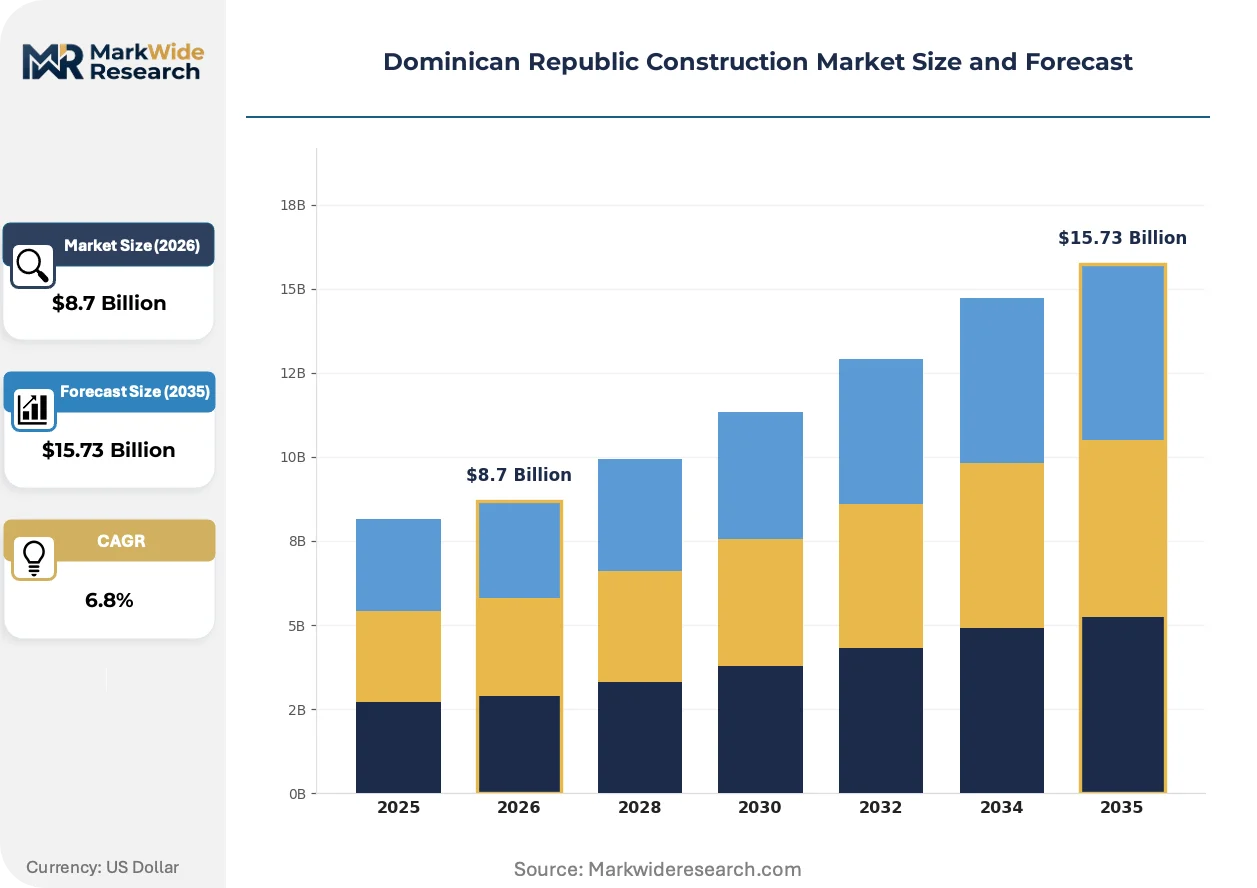
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Buildings, Commercial Structures, Infrastructure Projects, Industrial Facilities Material: Cement, Steel, Wood, Glass Application: Urban Development, Road Construction, Public Works, Renovation End User: Government Agencies, Private Developers, Contractors, Homeowners |
| Companies Covered | Noval SRL, Contratistas Civiles y Mecanicos SA, Paredes y Asociados Constructora, Therrestra SAS, Moya Supervisiones y Construcciones SA, Consorcio Odebrecht Tecnimont Estrella, Metro Country Club SA, Abi Karram Morilla Ingenieros Arquitectos SA, Constructora Rizek y Asociados, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dominican Republic Construction Market Trends and Innovations
Digital project management tools and alternative cement chemistries are compressing delivery schedules while the Ministry of Public Works tightens seismic design enforcement, creating simultaneous pressure on speed and compliance.
Low-carbon concrete formulations incorporating supplementary cementitious materials are bifurcating the ready-mix market. Hospitality developers pursuing LEED-equivalent certifications specify these blends for resort foundations and podium structures. Price premiums of fifteen to twenty-five percent separate compliant suppliers from conventional batching operations, concentrating specification-compliant capacity among vertically integrated producers.
The Ministry of Public Works and Communications implemented revised seismic-resistant design codes following Caribbean building failure analyses. Structural engineering firms must now submit peer-reviewed calculations for buildings exceeding four stories. Santiago and Santo Domingo commercial developers are absorbing additional design-phase costs to secure occupancy permits.
Developer procurement of construction management services is fragmenting as international hospitality brands bring captive project oversight teams to Punta Cana. Local general contractors are responding by unbundling design-build offerings into discrete permitting, subcontractor coordination, and quality assurance modules sold separately to foreign owners seeking direct control.
Dominican Republic Construction Market Segmentation
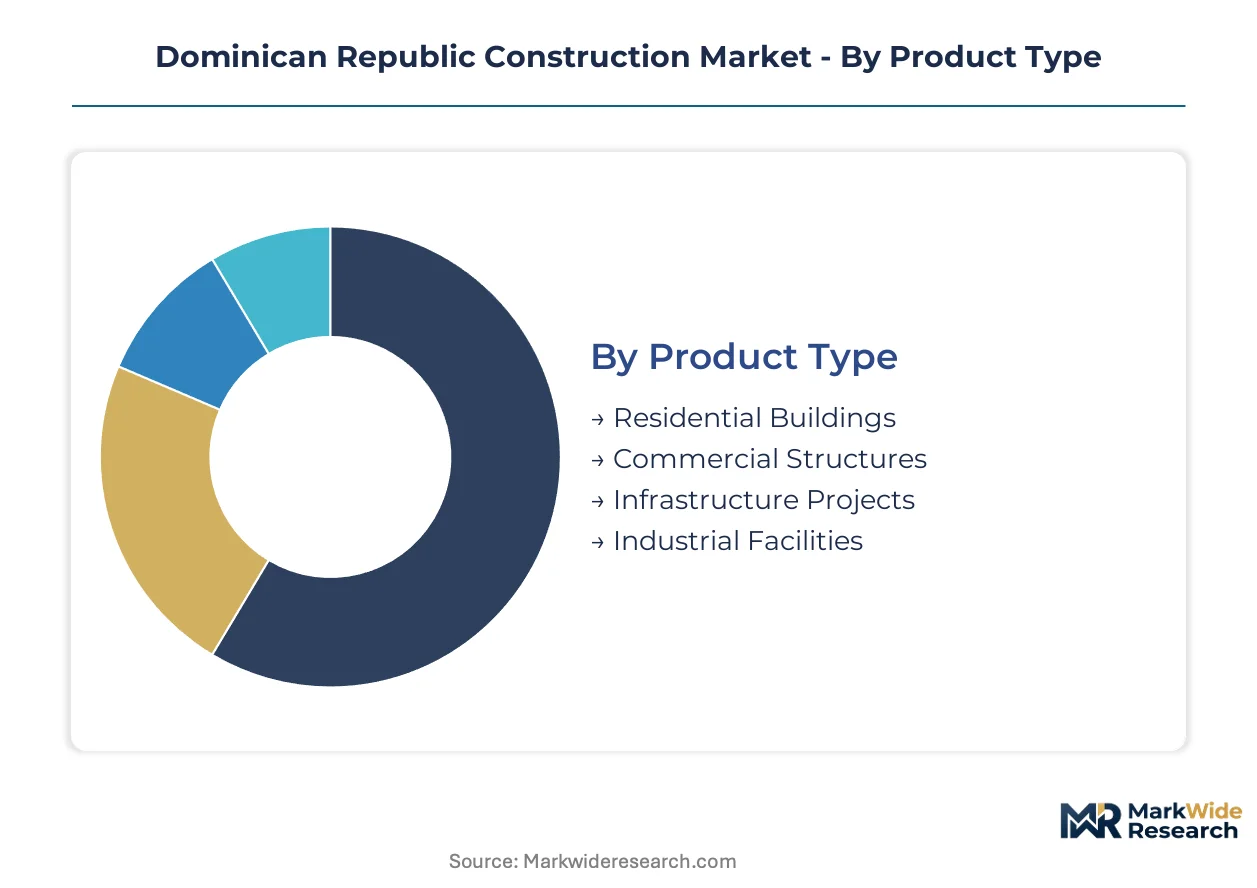
Construction demand across the Dominican Republic fragments across distinct procurement channels, material specifications, and client risk profiles. Understanding these divides clarifies where public investment concentrates versus where private capital drives specification upgrades.
Product Type:
Geographic concentration varies sharply by product type, with tourism-linked commercial builds clustering along the eastern seaboard while residential and infrastructure spreads across the interior.
- Residential Buildings:Low-rise concrete block construction dominates social housing initiatives under the Ministry of Public Works, while mid-rise towers concentrate in Greater Santo Domingo's densifying corridors. Demand splits between government-subsidized units and private condominiums targeting the emerging middle class.
- Commercial Structures:Hospitality developments along the Punta Cana corridor specify hurricane-resistant glazing and elevated seismic standards. Mixed-use retail and office formats in Santiago and Santo Domingo absorb premium engineering capacity.
- Infrastructure Projects:Road networks, bridges, and port modernization at Caucedo and Haina generate demand for marine-grade concrete and heavy civil engineering.
- Industrial Facilities:Manufacturing investment spreading into the Cibao Valley drives warehouse and cold-storage construction.
Residential Buildings commands the established base. The steepest expansion runs through Commercial Structures.
Material:
Cost tier differentiation separates commodity suppliers from specification-grade providers, with seismic and environmental compliance acting as the primary sorting mechanism.
- Cement:Ready-mix operations with captive aggregate sources control pricing in Greater Santo Domingo. Low-carbon formulations incorporating supplementary cementitious materials command fifteen to twenty-five percent premiums for hospitality developers pursuing sustainability certifications.
- Steel:Reinforcing bar supply concentrates on Mexican and US mills, exposing contractors to currency fluctuation and shipping cost volatility. Domestic fabrication capacity remains limited to secondary structural elements.
- Wood:Tropical hardwoods face harvest restrictions under Ministry of Environment protocols, pushing residential finish carpentry toward imported softwoods.
- Glass:Hurricane-resistant glazing specifications for coastal hospitality projects source primarily from Colombian and US fabricators.
Cement anchors volume throughput. Glass is climbing the fastest on specification intensity.
Application:
Customer type and funding source shape project timelines, with public works subject to election-cycle disruption and private development tracking tourism brand opening schedules.
- Urban Development:Greater Santo Domingo's densification drives vertical construction and utility network expansion. Santiago follows with logistics-adjacent industrial zoning.
- Road Construction:Federal highway modernization under the Ministry of Public Works channels equipment-intensive spending across the national network.
- Public Works:Social housing, schools, and healthcare facilities concentrate in secondary cities with weaker private construction markets.
- Renovation:Energy retrofit mandates for commercial buildings over ten thousand square meters unlock Santo Domingo's aging 1980s office stock.
Road Construction absorbs the largest public allocation. Renovation is gaining share fastest on regulatory pressure.
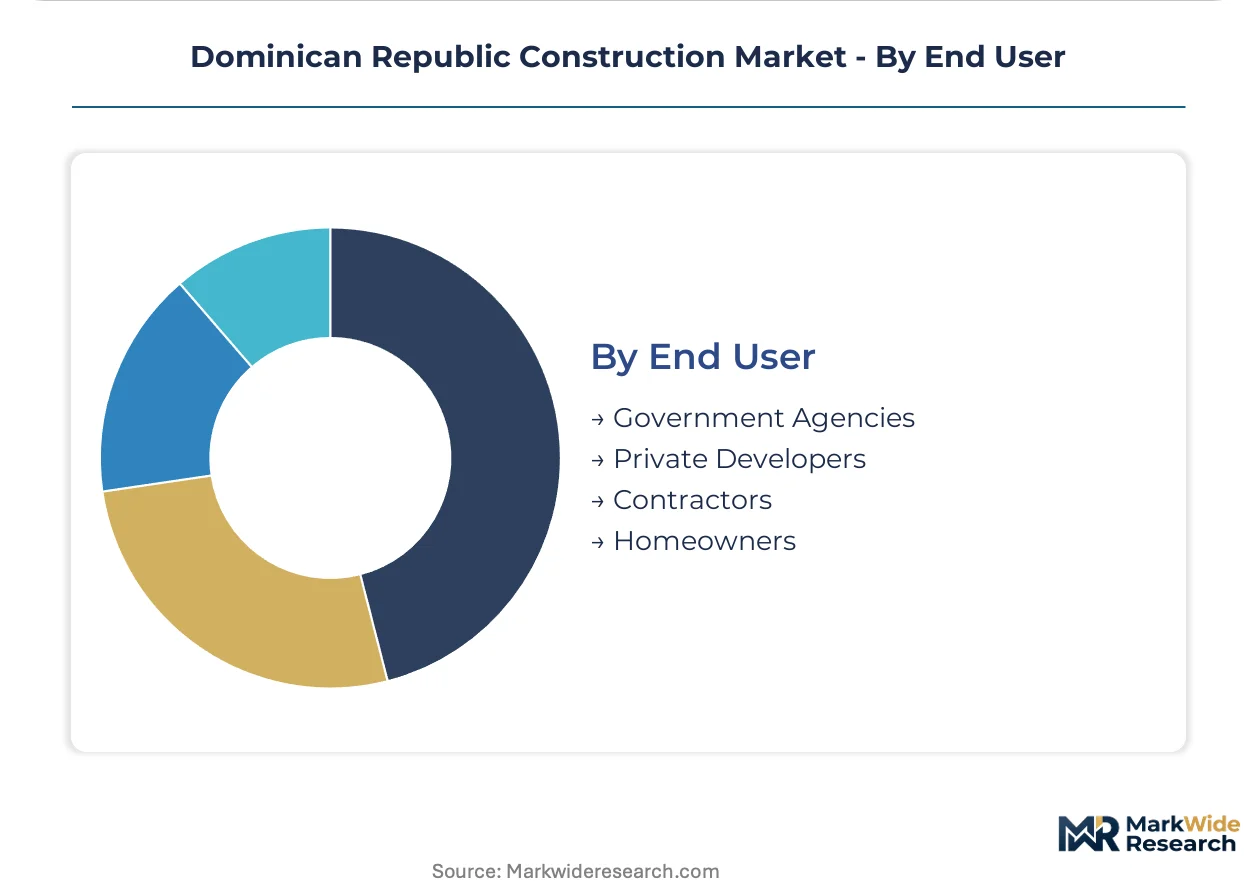
End User:
Procurement sophistication separates institutional buyers with technical specification teams from price-driven residential clients.
- Government Agencies:The Ministry of Public Works and Communications sets contracting rules and technical specifications for federal projects. Fixed-price contracts compress margins when material costs spike.
- Private Developers:International hospitality brands bring captive project oversight teams to Punta Cana, fragmenting traditional general contractor relationships.
- Contractors:Heavy civil specialists and mid-scale residential developers diverge on capital intensity and equipment fleet requirements.
- Homeowners:Informal construction dominates the lower tier, with limited access to formal financing or certified workforce.
Government Agencies anchor procurement volume. Private Developers are expanding fastest on tourism investment inflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dominican Republic's construction sector draws material inputs through Caucedo and Haina ports, with finished structures rarely exported given the immobile nature of buildings. Import dependency for reinforcing steel and specialty glazing creates currency exposure that shapes regional procurement strategies across the island.
Greater Santo Domingo
Vertical densification and commercial expansion dominate demand in the capital corridor. The Ministry of Public Works channels federal investment into road networks and social housing through its national housing plan. Urban core retrofitting accelerates as 1980s office stock faces energy-efficiency mandates.
Punta Cana Corridor
Tourism-driven resort construction compresses timelines to synchronize with international hospitality brand openings. Coastal environmental reviews under the Ministry of Environment extend permitting timelines. Hurricane-resistant glazing and seismic structural systems command specification premiums.
Santiago and Cibao Valley
Manufacturing investment spreading north from the capital generates demand for industrial warehouse and cold-storage facilities. Logistics-adjacent zoning reforms attract distribution center developers. Secondary city land-banking strategies gain traction as capital-region saturation intensifies.
Northern Coast and Puerto Plata
Cruise port expansion and tourism diversification drive hospitality-adjacent construction beyond the eastern corridor. Infrastructure connectivity improvements link coastal zones to Santiago's industrial base. Modular prefabrication from regional suppliers reduces on-site labor dependencies.
Border Provinces and Elias Pina
Cross-border trade infrastructure and agricultural processing facilities anchor public works allocation. Road modernization under federal highway programs improves connectivity to Haitian markets. Social housing initiatives concentrate in secondary cities with weaker private construction markets.
Dominican Republic Construction Market Competitive Landscape
Concentration sits with vertically integrated heavy civil specialists and mid-scale residential developers operating on divergent capital-intensity models. The market structure bifurcates between equipment-intensive infrastructure bidders and leaner urban residential operators. Three archetypes dominate: concrete-integrated infrastructure specialists, government-contract anchored civil mechanics, and commercial-institutional builders. Competitive moves center on captive supply chain control and strategic unbundling of design-build services.
Within the vertically integrated tier, Noval SRL exemplifies the infrastructure specialist archetype through its concrete supply and batching plant operations. Contratistas Civiles y Mecanicos SA occupies a position among equipment-intensive government contractors. Paredes y Asociados Constructora represents the commercial-institutional specialization vector in Santo Domingo and Santiago markets.
| Leading Market Players |
|---|
| Noval SRL |
| Contratistas Civiles y Mecanicos SA |
| Paredes y Asociados Constructora |
| Therrestra SAS |
| Moya Supervisiones y Construcciones SA |
| Consorcio Odebrecht Tecnimont Estrella |
| Metro Country Club SA |
| Abi Karram Morilla Ingenieros Arquitectos SA |
| Constructora Rizek y Asociados |
| Others |
Pricing and Supply Chain Analysis
Seismic-resistant design code enforcement by the Ministry of Public Works gates both contractor qualification and price differentiation simultaneously. Contractors bearing peer-reviewed engineering certifications command fifteen to twenty-five percent premiums over conventional batching operations, while uncertified suppliers face exclusion from federal project pipelines.
Pricing Analysis
Configured-to-order pricing for low-carbon concrete formulations diverges sharply from standard ready-mix commodity rates. Project-based contracting dominates public works, with price differentiation driven by certification tier and vertical integration depth. Cost compression in conventional concrete is intensifying because hospitality developers increasingly specify supplementary cementitious material blends. Government agencies exhibit highest price sensitivity due to fixed-price contract structures, while international hospitality brands show lowest sensitivity on specification-grade materials.
Supply Chain Analysis
Mexico and the United States anchor reinforcing bar supply for Dominican contractors, while Colombia and Spain feed panelized prefabrication systems. Raw material dependencies center on imported steel, marine-grade cement additives, and hurricane-resistant glazing substrates. Single-source vulnerability concentrates in rebar procurement, where currency fluctuation and shipping cost volatility transmit directly to project margins. Distribution runs through Caucedo and Haina ports, with captive batching plant networks controlling last-mile concrete delivery in Greater Santo Domingo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dominican Republic construction market sits in cyclical recovery, underpinned by tourism investment inflows accelerating resort development timelines beyond historical norms.
For Market Incumbents: Compound equipment fleet utilization through long-term government contract extensions while absorbing certified welder wage premiums into cost-plus pricing structures. Threaten emerging modular prefabrication entrants by locking aggregate quarry access in Greater Santo Domingo. Priority lever rests on deepening backward integration into concrete additive supply.
For New Entrants and Emerging Players: Differentiate on energy retrofit execution speed for Santo Domingo's 1980s commercial stock, where regulatory mandates outpace incumbent capacity. Target Santiago logistics-adjacent industrial construction as the most penetrable geography, with cold-storage specification expertise as the go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hospitality construction specialists holding Punta Cana corridor relationships. Long-term viability over a five-to-ten year window hinges on land-banking positions in secondary cities ahead of manufacturing dispersion from the capital. Watch Ministry of Public Works social housing allocation shifts as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aggregate Supply | Captive quarry access insulates Noval SRL from cement price volatility in federal bidding. |
| Modular Prefabrication Partnership | Spanish and Colombian panel systems reduce on-site labor hours for mid-rise residential towers. |
| Seismic Certification Investment | Peer-reviewed engineering capacity unlocks Ministry of Public Works contracts exceeding four stories. |
| Santiago Logistics Hub Development | Cibao Valley warehouse construction captures manufacturing investment spreading north from the capital. |
| Energy Retrofit Specialization | Commercial building efficiency mandates open renovation contracts in Santo Domingo's aging office stock. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with heavy civil contractors, hospitality project developers, Ministry of Public Works procurement officers, and ready-mix plant operators; alongside secondary validation through customs import records, Dominican Chamber of Construction workforce certification databases, and federal project award disclosures. Bottom-up project pipeline enumeration triangulated against top-down construction spending aggregates from national accounts.
Across the analysis window, the forecasting framework modeled demand by product type, material specification tier, application channel, and end-user procurement sophistication. CAGRs derived from weighted regression across historical spend patterns and announced project commitments. Industry-specific inputs incorporated tourism arrival projections and social housing unit targets under federal plans.
The analysis sits within stated boundaries; outcomes outside sustained tourism investment flows or election-cycle public works continuity would require recalibration. Forecasts reflect documented assumptions on material cost trajectories and permitting timeline stability. Recalibration cycles align with material shifts in Ministry of Environment coastal review protocols and federal housing plan allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Sweden New Construction Market
Building Construction
Turkey Construction Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Prefabricated Buildings Market
Building Construction
Indonesia Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
China Construction Market
Building Construction
Oman Construction Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Malaysia Construction Market
Building Construction
United States Commercial Construction Market