
 Australia Construction Market | 2026-2036
Australia Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Construction Market Analysis
Queensland's infrastructure pipeline is rewriting procurement calendars across Australia's eastern states. Lendlease anchors large-scale mixed-use precinct development through integrated project delivery models. Hansen Yuncken competes aggressively in health and education verticals where technical complexity filters out smaller bidders. Icon leverages modular construction capabilities to compress program timelines on constrained urban sites.
Australia construction encompasses the physical assembly, alteration, and maintenance of buildings and civil structures using engineered materials such as reinforced concrete achieving 50 MPa compressive strength, structural steel grades AS/NZS 3678, and cross-laminated timber panels rated for fire resistance up to 60 minutes. Residential construction dominates current output volumes yet faces margin compression from interest rate sensitivity and land scarcity in capital cities. Infrastructure commands the deepest project backlogs, with transport and energy transmission assets attracting sustained government allocation through bilateral funding agreements. Commercial construction differentiates through green building certification thresholds, where 5-star Green Star ratings increasingly determine tenant retention and financing terms.
The Australian Building Codes Board administers the National Construction Code, which mandates minimum energy efficiency and structural performance standards that directly shape material selection and design methodology across jurisdictions. State-level planning instruments, including Victoria's Planning and Environment Act and New South Wales' Environmental Planning and Assessment Act, layer additional compliance pathways that extend approval timelines but elevate built-form quality. The Clean Energy Finance Corporation's construction-linked lending criteria now embed embodied carbon thresholds, redirecting procurement toward lower-carbon steel and concrete alternatives. Stakeholders must monitor how tightening disclosure obligations intersect with supply chain capacity for certified low-carbon materials.
Market Dynamics
The Australian construction sector is recalibrating around embodied carbon accounting as the National Construction Code tightens thermal performance minimums and the Clean Energy Finance Corporation embeds emissions thresholds into project finance eligibility. Material procurement protocols now hinge on verified Environmental Product Declarations, compressing supplier qualification timelines and elevating vertically integrated fabricators.
Growth Catalysts
- Transport infrastructure bilateral funding:Federal-state agreements for Sydney Metro West and Melbourne Suburban Rail Loop are unlocking multi-decade capital commitments. These projects absorb expanded steel and concrete volumes.
- Cross-laminated timber fire-rated panels:Engineered timber achieving 60-minute fire resistance ratings is penetrating mid-rise residential and commercial verticals. The Australian Building Codes Board's 2025 deemed-to-satisfy provisions accelerate structural timber specification.
- Queensland Olympics 2032 pipeline:Precinct development across Brisbane, Gold Coast and Sunshine Coast is front-loading procurement calendars. Early works contracts are compressing traditional design-bid-build cycles.
Market Restraints
- Reinforcing steel supply concentration:Domestic rebar fabrication capacity clusters in Port Kembla and Whyalla, exposing eastern seaboard projects to single-source disruption risk during blast furnace maintenance cycles.
- 50 MPa concrete input cost volatility:Cementitious binder prices fluctuate with fly ash import dependence and alternative supplementary cementitious material qualification delays. Margin compression hits fixed-price residential contracts.
- Technical limitation in low-carbon concrete scale:Geopolymer and calcined clay blends face batch consistency challenges at commercial volumes. Quality assurance protocols lag material innovation.
Strategic Opportunities
- Western Australia lithium processing infrastructure:Downstream battery chemical plants require specialized containment structures and acid-resistant concrete systems. Engineering procurement construction firms with mining credentials pivot into this vertical.
- Green Star 6-star certification pathway:The Green Building Council of Australia's net-zero carbon ready standard creates premium positioning for contractors mastering whole-life carbon modeling. Tenant pre-commitment rates favor early adopters.
- Modular bathroom pod manufacturing:Prefabricated wet-area units are hybridizing with cross-laminated timber floor cassettes. Compression of on-site trade sequencing addresses skilled plasterer and tiler shortages.
Industry Challenges
- Structural engineer shortage:Complex facade engineering and computational design capabilities concentrate in Melbourne and Sydney consultancies. Regional project feasibility suffers from technical review bottlenecks.
- Environmental Product Declaration certification timeline:Third-party verification of embodied carbon data for concrete and steel extends 6-12 months. Project tender deadlines preclude uncertified material specification.
- Legacy project management software integration:Common Data Environment platforms clash with proprietary building information modeling workflows. Data loss during design handover corrupts quantity surveying accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Construction Market |
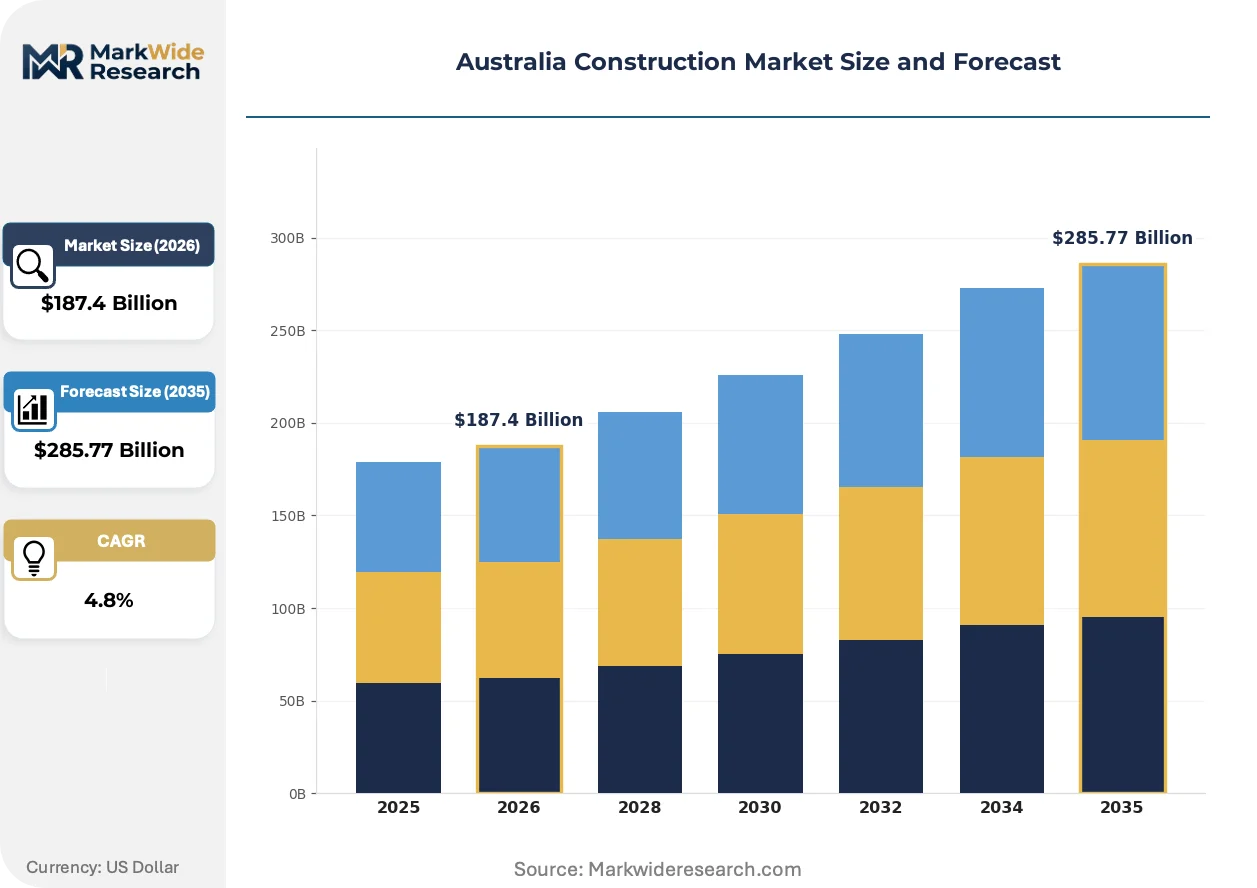
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Infrastructure, Industrial End User: Private Developers, Government Agencies, Contractors, Consumers Material Type: Steel, Concrete, Wood, Bricks Service Type: Design, Construction, Project Management, Consulting |
| Companies Covered | Icon, Hansen Yuncken, John Holland Group, Lendlease, Hutchinson Builders, Multiplex, ADCO Constructions, Hindmarsh, Built, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Construction Market Emerging Trajectories
Digital fabrication and material chemistry advances are compressing traditional construction timelines while regulatory disclosure mandates force transparency through supply chains. Three developments are restructuring competitive positioning.
Cross-laminated timber is hybridizing with structural steel moment frames in mid-rise commercial buildings. Developers targeting 5-star Green Star ratings specify hybrid systems to optimize embodied carbon against lateral load requirements. The combination enables 12-storey heights previously reserved for concrete cores, expanding timber's addressable market.
The National Construction Code 2025 revision mandates minimum 7-star NatHERS thermal performance for residential construction. This elevates glazing specification, insulation continuity detailing, and air tightness testing protocols. Volume homebuilders in Melbourne's growth corridors are consolidating supplier panels to manage compliance complexity.
Buyers are consolidating procurement around integrated project delivery contracts with shared risk-reward mechanisms. State infrastructure agencies in New South Wales and Victoria favor alliance contracting for rail and hospital projects. Traditional lump-sum tendering retreats to standardized residential and warehouse segments.
Australia Construction Market Segmentation
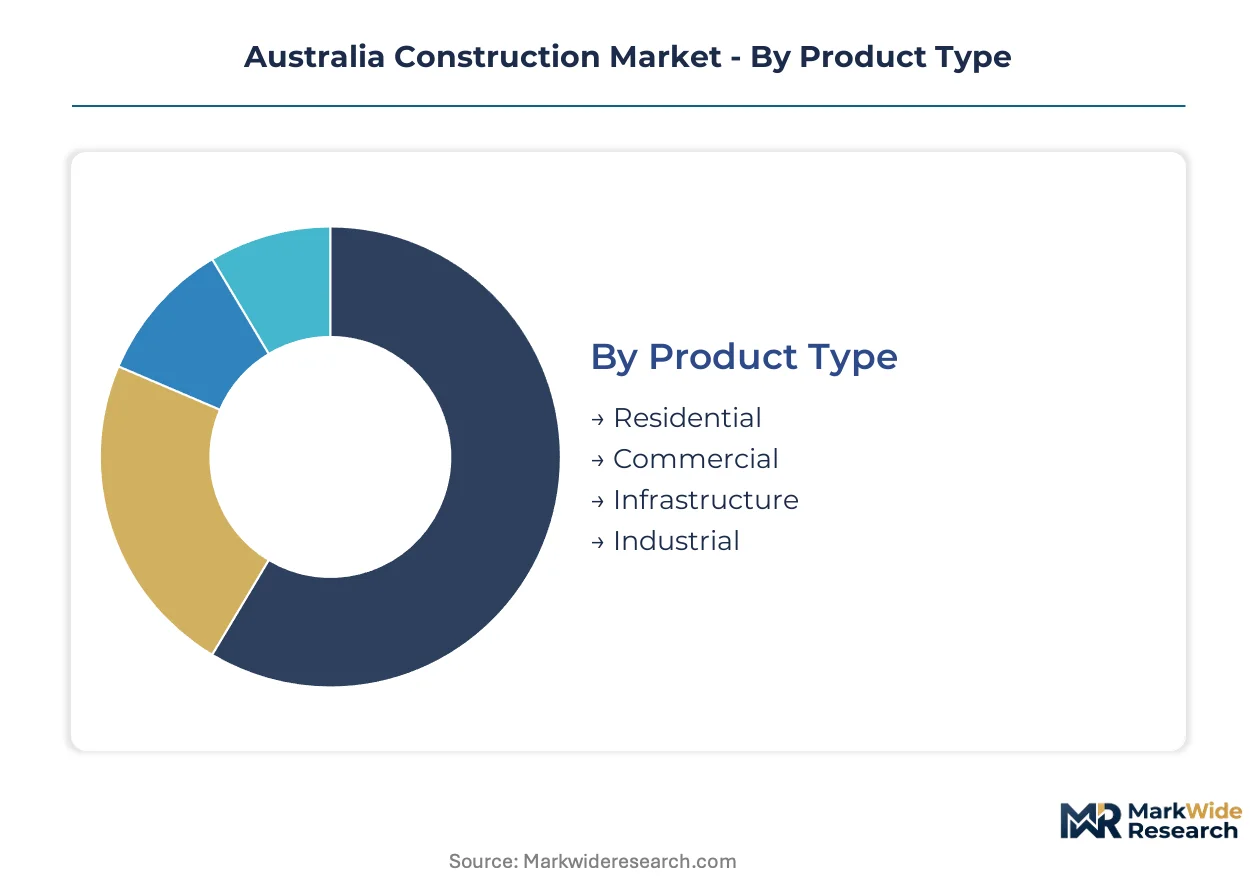
Segmentation in the Australian construction market reveals how procurement calendars, regulatory compliance burdens, and material certification timelines concentrate differently across project types and stakeholder configurations. Understanding these divisions exposes where capital flows meet technical bottlenecks.
Product Type:
After-sales service intensity varies sharply across product segments, with infrastructure demanding decades of asset maintenance protocols while residential builders face compressed defect liability periods under state home warranty schemes.
- Infrastructure:Transport and energy assets require specialized structural health monitoring systems and long-term pavement management contracts. Queensland's Olympic precinct developments and Melbourne's Suburban Rail Loop are absorbing expanded engineering procurement construction capacity for alliance-contracted delivery.
- Residential:High-density apartments in Sydney's corridor and detached housing in Melbourne's growth corridors dominate output volumes. Interest rate sensitivity and land scarcity compress margins for volume homebuilders managing National Construction Code thermal performance upgrades.
- Commercial:Green Star certification thresholds determine tenant retention and financing access. Speculative office developments concentrate in Brisbane's inner-city renewal zones.
- Industrial:Western Australia's lithium processing plants require acid-resistant concrete containment and specialized ventilation infrastructure. Mining credentials differentiate eligible contractors.
By volume, residential construction leads. By growth pace, infrastructure is climbing the fastest on sustained federal-state bilateral funding commitments.
End User:
Cost tier stratification separates government agencies with multi-decade capital pipelines from private developers managing cyclical funding access and margin volatility.
- Government Agencies:State infrastructure bodies in New South Wales and Victoria favor alliance contracting with shared risk-reward mechanisms. Procurement calendars extend across election cycles, requiring political continuity for project delivery.
- Private Developers:Institutional capital partners with integrated project delivery specialists for mixed-use precincts. Pre-commitment thresholds for green building certification determine project finance eligibility.
- Contractors:Tier-one firms compete for technically complex health and education verticals where computational design capabilities filter out smaller bidders.
- Consumers:Individual homeowners drive renovation activity and volume housing demand, with NatHERS rating awareness rising among purchasers.
By project value concentration, government agencies lead. By transaction velocity, private developers are expanding most quickly through institutional capital deployment.
Material Type:
Supply concentration geography dictates procurement risk profiles, with domestic rebar fabrication clustering in Port Kembla and Whyalla while engineered timber sources distribute more broadly.
- Concrete:50 MPa compressive strength mixes incorporating fly ash and alternative supplementary cementitious materials face batch consistency challenges at commercial scale. Cementitious binder price volatility hits fixed-price residential contracts.
- Steel:Structural grades AS/NZS 3678 and reinforcing bar specifications dominate high-rise and infrastructure applications. Blast furnace maintenance cycles at single-source eastern seaboard plants expose projects to disruption risk.
- Wood:Cross-laminated timber panels rated for 60-minute fire resistance penetrate mid-rise residential and commercial verticals. The Australian Building Codes Board's deemed-to-satisfy provisions accelerate structural timber specification.
- Bricks:Clay masonry retains share in suburban residential and heritage-sensitive commercial projects where aesthetic specification overrides cost optimization.
By tonnage deployed, concrete leads. By specification growth rate, engineered timber is gaining share fastest on embodied carbon advantages.
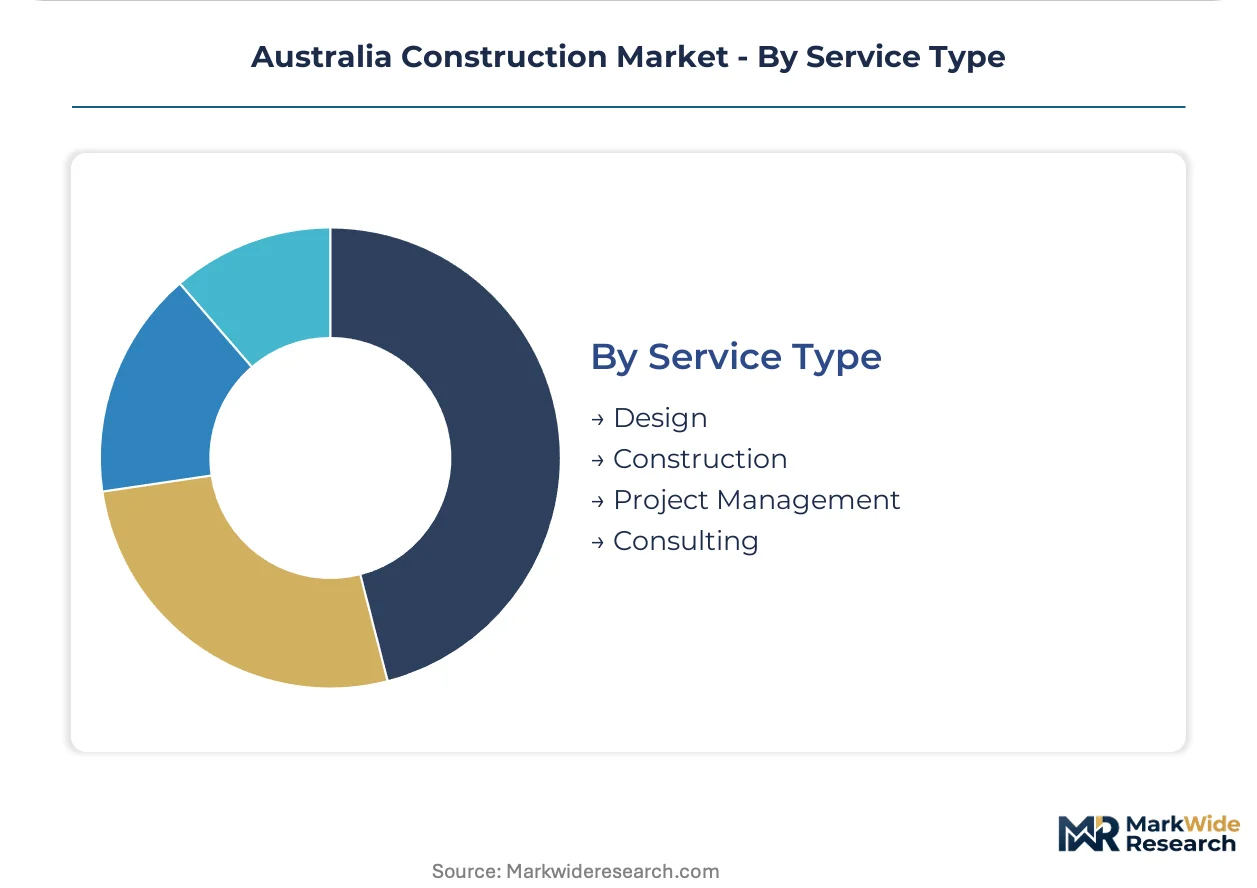
Service Type:
Margin structure separates capital-intensive construction execution from advisory services where labor leverage determines profitability.
- Construction:On-site assembly absorbs the largest workforce deployment and equipment capital. Modular prefabrication capabilities compress program timelines on constrained urban sites.
- Project Management:Common Data Environment platform integration with proprietary building information modeling workflows creates data integrity risks during design handover.
- Design:Complex facade engineering and computational design capabilities concentrate in Melbourne and Sydney consultancies. Regional project feasibility suffers from technical review bottlenecks.
- Consulting:Whole-life carbon modeling and Environmental Product Declaration procurement advisory services expand on tightening Clean Energy Finance Corporation lending criteria.
By employment scale, construction leads. By fee growth trajectory, carbon-focused consulting is climbing the fastest on regulatory disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic rebar fabrication capacity clusters in Port Kembla and Whyalla, exposing eastern seaboard projects to single-source disruption risk during blast furnace maintenance cycles. This supply-side concentration shapes procurement calendars across state-level infrastructure pipelines.
New South Wales
Sydney Metro West and high-density residential corridors absorb expanded steel and concrete volumes. The Environmental Planning and Assessment Act layers compliance pathways that extend approval timelines. Parramatta's transit-oriented precincts concentrate alliance-contracted project delivery.
Victoria
Melbourne's Suburban Rail Loop unlocks multi-decade capital commitments across suburban precincts. The Planning and Environment Act mandates additional built-form quality standards. Geelong's emerging rail manufacturing hub attracts specialized engineering procurement construction capacity.
Queensland
Brisbane's 2032 Olympics pipeline front-loads procurement calendars across Gold Coast and Sunshine Coast precincts. State infrastructure agencies favor integrated project delivery models with shared risk-reward mechanisms. Cross River Rail early works compress traditional design-bid-build cycles.
Western Australia
Downstream lithium processing plants demand specialized containment structures and acid-resistant concrete systems. The Clean Energy Finance Corporation's construction-linked lending criteria embed embodied carbon thresholds. Kwinana's industrial zone attracts engineering procurement construction firms with mining credentials.
Australia Construction Market Vendor Landscape
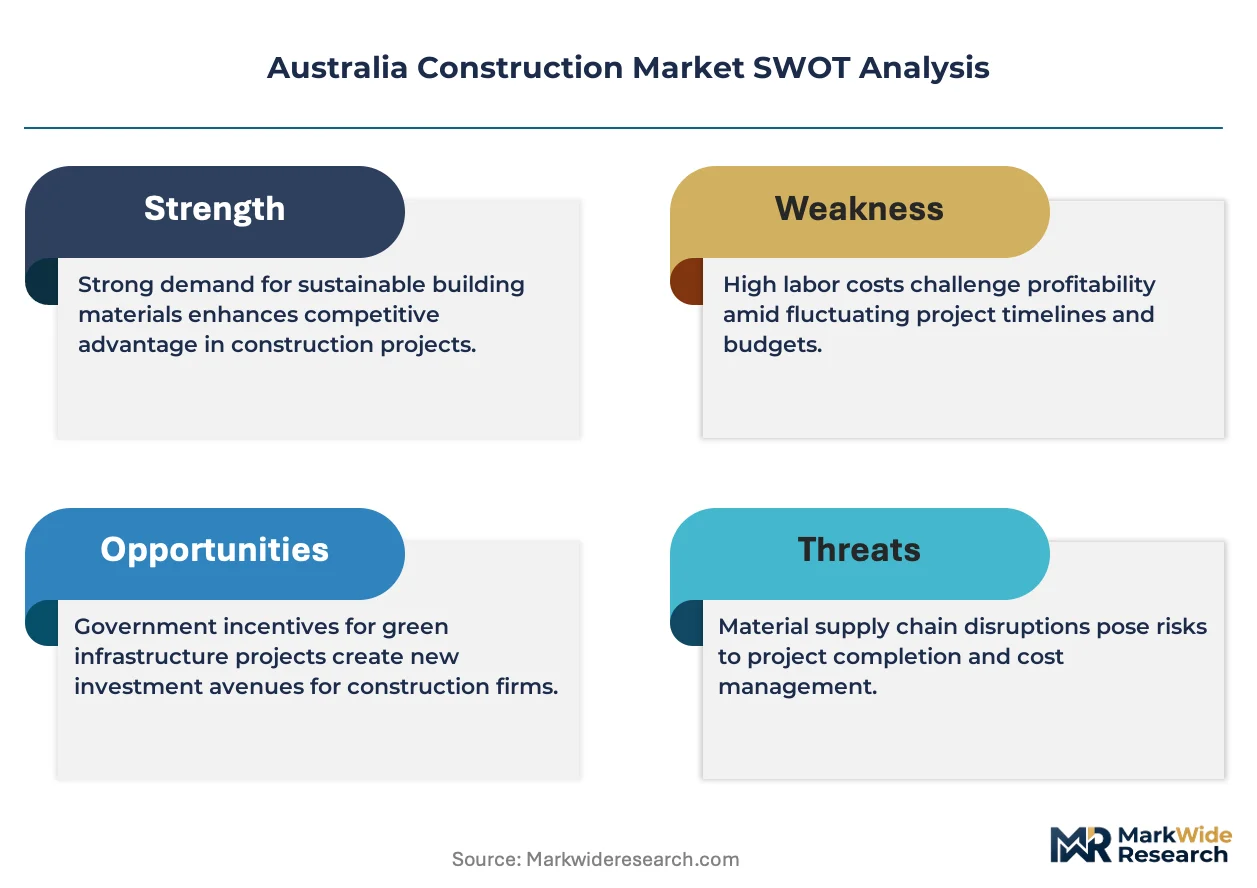
Platform integrators command the system tier; component specialists sit upstream in fragmented supply niches. The Australian construction sector exhibits tiered consolidation, with large-scale precinct developers competing against regional specialists in health and education verticals. Three archetypes dominate: integrated project delivery platforms, modular construction specialists, and mining-credentialed engineering procurement construction firms. Competitive dynamics center on alliance contracting penetration and vertical integration into prefabrication capabilities.
Within the integrated delivery tier, Lendlease anchors large-scale mixed-use precinct development through alliance-contracted models. Hansen Yuncken occupies a position in technically complex health and education verticals where computational design capabilities filter out smaller bidders. Icon exemplifies the modular construction archetype, compressing program timelines on constrained urban sites through prefabricated wet-area units and cross-laminated timber floor cassettes.
| Leading Market Players |
|---|
| Icon |
| Hansen Yuncken |
| John Holland Group |
| Lendlease |
| Hutchinson Builders |
| Multiplex |
| ADCO Constructions |
| Hindmarsh |
| Built |
| Others |
Supply Flow & Price Mechanics
Port Kembla and Whyalla anchor domestic rebar fabrication capacity, concentrating blast furnace output in two eastern seaboard locations. This geographic clustering grants single-source suppliers pricing leverage during maintenance cycles, while fixed-price residential contracts absorb cementitious binder volatility without pass-through mechanisms.
Pricing Analysis
The National Construction Code dictates the pricing tier structure across residential, commercial, and infrastructure segments. Green Star certification thresholds separate premium-rated assets from standard construction, with 5-star and 6-star ratings commanding financing advantages that justify higher upfront capital deployment. Cost compression in volume homebuilding intensifies as interest rate sensitivity constrains purchaser budgets, making Melbourne's growth corridor buyers the most price-sensitive segment. Government alliance contractors exhibit lowest price sensitivity due to multi-decade procurement horizons and risk-reward sharing mechanisms.
Supply Chain Analysis
Export-control regimes on critical mineral processing technology limit domestic value-addition capacity for lithium infrastructure inputs. Australian construction draws from Chinese steel billet, Vietnamese engineered timber, and domestic Portland cement clinker. Fly ash import dependence and supplementary cementitious material qualification delays create single-source vulnerability for high-strength concrete blends. Distribution runs through state-level infrastructure agencies and tier-one engineering procurement construction firms with alliance contracting credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia construction market sits in a cyclical recovery phase, with transport infrastructure bilateral funding providing sustained capital commitment visibility across election cycles.
For Market Incumbents: Insulate project margins by deepening backward integration into modular fabrication capabilities, capturing value from cross-laminated timber floor cassettes and prefabricated wet-area units. Secure captive supply of Environmental Product Declaration-certified low-carbon concrete before third-party verification timelines extend beyond tender deadlines. Capacity concentration in Port Kembla rebar fabrication represents the primary supply disruption threat requiring dual-sourcing protocols. For New Entrants and Emerging Players: Establish a beachhead in Western Australia's lithium processing infrastructure vertical, where acid-resistant concrete containment expertise and mining credentials filter out established residential builders. Target alliance subcontracting roles on Queensland Olympics 2032 precinct developments, where compressed procurement calendars favor nimble specialist firms. Lead with whole-life carbon modeling advisory services to differentiate against legacy quantity surveying incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-services compounding play because federal-state bilateral funding agreements lock in multi-decade capital deployment irrespective of residential cycle volatility. Acquisition targets should display modular construction capabilities or Green Star 6-star certification track records. Watch for Clean Energy Finance Corporation lending criteria tightening as the inflection signal redirecting procurement toward verified low-carbon material suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Alliance Contracting Capability | Shared risk-reward mechanisms unlock state infrastructure agency procurement calendars in New South Wales and Victoria. |
| Modular Prefabrication Scale-Up | Cross-laminated timber floor cassettes compress program timelines on constrained Sydney and Melbourne urban sites. |
| Environmental Product Declaration Certification | Third-party verified embodied carbon data satisfies Clean Energy Finance Corporation lending eligibility thresholds. |
| Green Star 6-Star Pathway Investment | Net-zero carbon ready standard commands tenant pre-commitment premiums in Brisbane commercial developments. |
| Western Australia Lithium Infrastructure Pivot | Acid-resistant concrete containment expertise captures downstream battery chemical plant construction demand. |
Methodological Framework
Operator-level perspectives from project directors at tier-one engineering procurement construction firms, procurement leads at state infrastructure agencies, and sustainability officers at institutional developers anchored the qualitative base. Secondary validation drew from Australian Bureau of Statistics construction activity data, Infrastructure Australia priority project listings, and Green Building Council of Australia certification registers. Bottom-up project pipeline aggregation triangulated against top-down state government capital expenditure commitments.
Scenario-bracketing around interest rate sensitivity, material cost volatility, and regulatory disclosure timelines framed the analytical envelope across the projection horizon. Segmentation modeling spanned product type, end user archetype, material specification, and service delivery mode, with regional granularity at state level. CAGRs derived from weighted project flow projections incorporating bilateral funding agreement durability and Olympic precinct front-loading effects.
Stress conditions across reinforcing steel supply disruption, cementitious binder price spikes, and Environmental Product Declaration certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on political continuity for infrastructure pipelines and Clean Energy Finance Corporation lending criteria stability. Material shifts in National Construction Code thermal performance mandates or blast furnace maintenance scheduling would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Indonesia Commercial Construction Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
Italy Construction Market
Building Construction
Prefabricated Buildings Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
US Modular Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
China Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Dominican Republic Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
Kuwait Construction Market
Building Construction
North America Modular Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Middle East Data Center Construction Market