
 China Prefabricated Buildings Market | 2026-2036
China Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
China Prefabricated Buildings Market Insights
Steel fabricators across Jiangsu and Zhejiang provinces are repositioning capacity toward modular unit output. China State Construction Engineering Corp. leverages its state-backed project pipeline to dominate turnkey prefabricated developments. CIMC Modular Building Systems sustains export-grade manufacturing standards that differentiate its container-derived modules. Hangxiao Steel Structure specializes in high-rise steel frameworks that anchor commercial prefabricated construction in eastern China.
Prefabricated buildings are structures manufactured off-site in standardized sections and assembled on location, with steel frames typically fabricated to GB 50017 design codes and concrete panels cured under controlled humidity before transport. Their primary purpose is compressing construction schedules while reducing on-site labor and material waste. Modular units command premium margins in residential applications where factory finishing includes integrated MEP systems. Steel material segments lead volume in industrial applications due to span requirements and seismic performance demands. Hybrid construction methods are gaining traction as developers blend prefabricated structural elements with cast-in-place cores to optimize cost and flexibility.
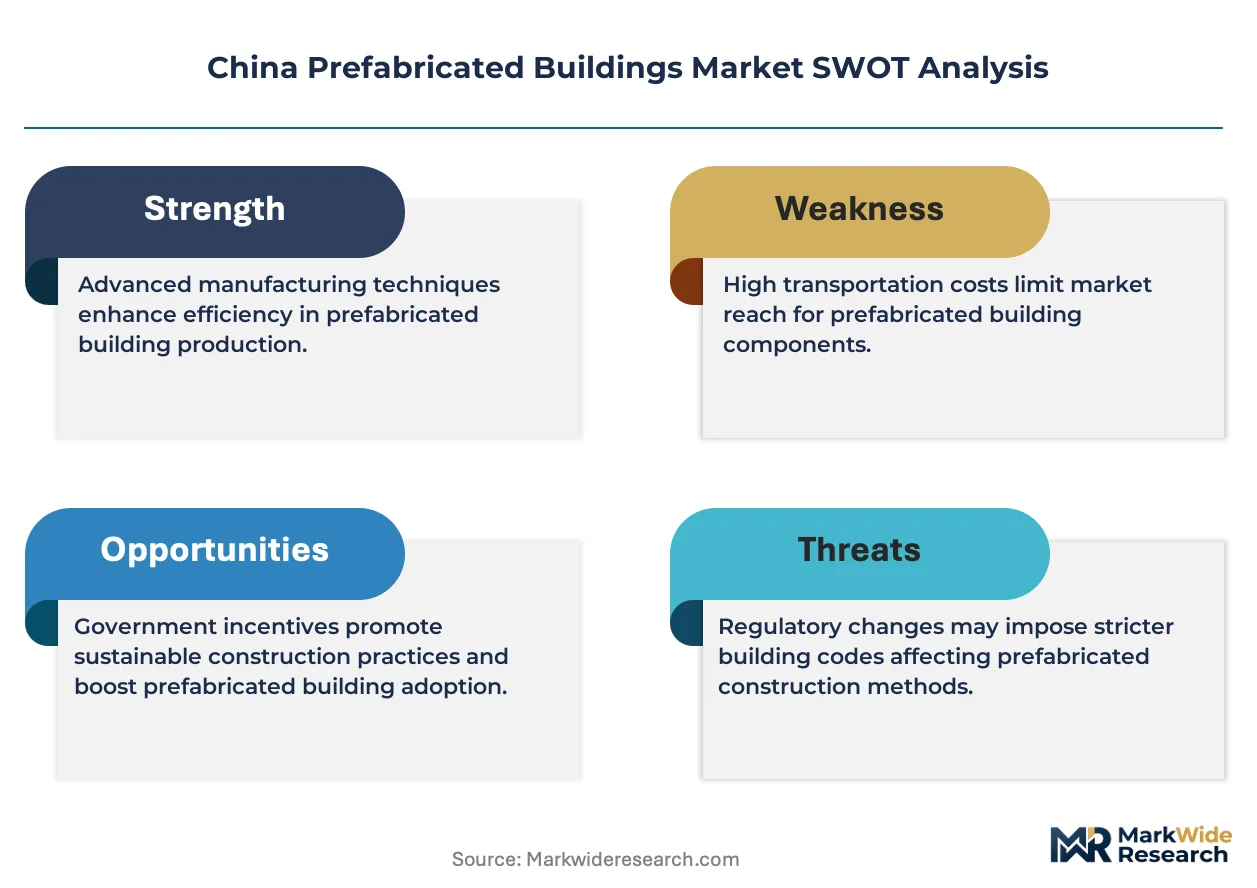
MIIT promotes industrialized construction through equipment upgrade directives, while MEE enforces embodied carbon limits that favor factory-controlled production over conventional site casting. SAMR oversees GB standard compliance for structural connectors and fire-rated assemblies, creating certification barriers for unqualified suppliers. Stakeholders must monitor how provincial governments translate national dual carbon targets into local procurement mandates that reshape competitive access across China's construction markets.
Market Dynamics
MIIT's industrialized construction directives are compressing project timelines while MEE's embodied carbon limits force developers toward factory-controlled production methods over conventional casting.
Growth Catalysts
- Dual carbon policy enforcement:MEE mandates on embodied carbon favor off-site manufacturing with controlled energy inputs, redirecting municipal housing procurement toward modular units.
- Yangtze River Delta concentration:Shanghai and Jiangsu province cities anchor demand clusters where steel fabricators reposition capacity toward modular output.
- GB 50017 seismic standards:Upgraded design codes for steel frameworks accelerate adoption of prefabricated high-rise commercial structures in eastern China.
Market Restraints
- Steel price volatility:Raw material cost swings compress margins for fabricators without captive supply arrangements or long-term procurement contracts.
- Jiangsu-Zhejiang supply concentration:Regional clustering of qualified manufacturers creates bottleneck risk during demand surges and limits geographic diversification.
- Transportation diameter limits:Maximum module dimensions for highway transit constrain design flexibility and force on-site assembly complexity for larger structures.
Strategic Opportunities
- Western China penetration:Chengdu-Chongqing corridor infrastructure investment opens underserved markets where prefabricated construction penetration lags coastal benchmarks.
- Hybrid construction convergence:Developers blend prefabricated structural elements with cast-in-place cores to optimize cost and seismic performance in mid-rise residential.
- SAMR certification acceleration:Streamlined approval pathways for GB-compliant structural connectors reduce time-to-market for qualified component suppliers.
Industry Challenges
- MEP integration skill scarcity:Factory-based mechanical-electrical-plumbing system installation requires technicians cross-trained in manufacturing and construction protocols.
- Fire-rated assembly certification timelines:SAMR testing protocols for multi-story residential modules extend product development cycles beyond conventional construction bidding windows.
- Legacy site-casting labor displacement:Trade unions and subcontractor networks resist workflow shifts that reduce on-site workforce requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Prefabricated Buildings Market |
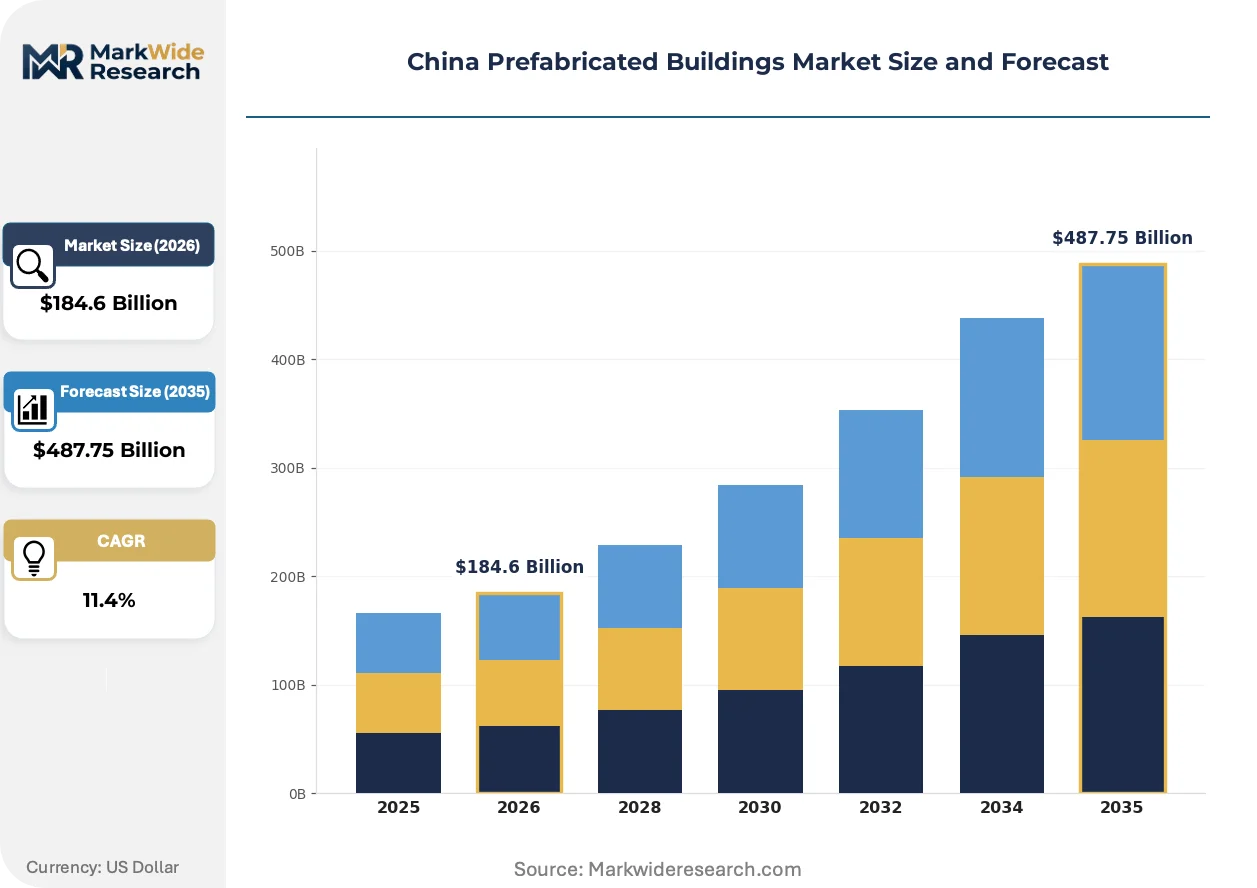
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $487.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
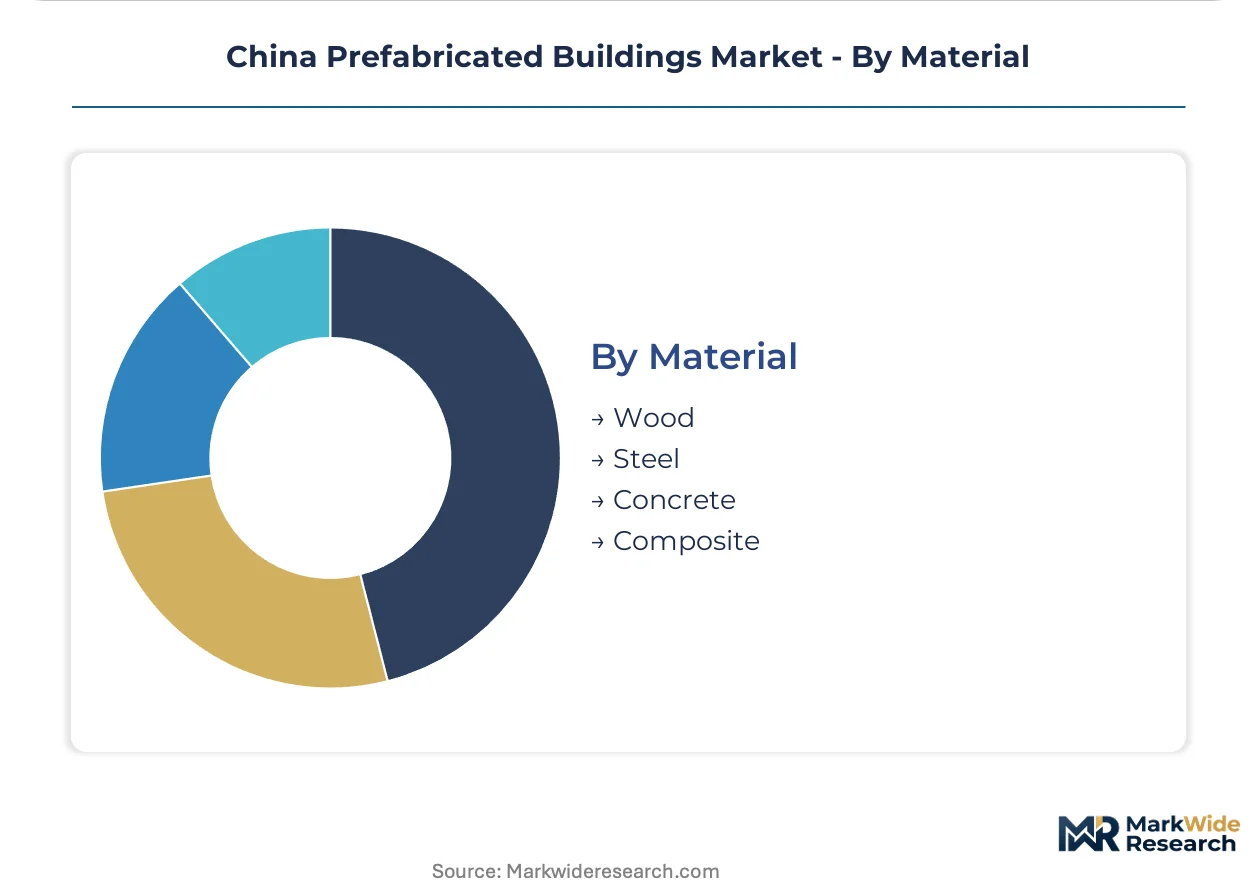
| Segmentation | Product Type: Wall Panels, Roof Panels, Modular Units, Foundation Systems Application: Residential, Commercial, Industrial, Institutional Construction Method: Traditional, Modular, Hybrid, Off-site Material: Wood, Steel, Concrete, Composite |
| Companies Covered | China State Construction Engineering Corp., CIMC Modular Building Systems, Hangxiao Steel Structure, Ningbo Deepblue Smart House, Ark Prefab, Broad Group, Atlantic Modular System, Zhejiang Putian Integrated Housing, China Railway Construction Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Prefabricated Buildings Market Trends and Innovations
Digital fabrication and policy tightening are restructuring how buildings materialize, with factory precision displacing field tolerance and carbon accounting reshaping material selection.
BIM-to-fabrication workflows are electrifying steel processing plants across Jiangsu province. Commercial developers in Shanghai's Pudong district now specify digital twins for structural modules, compressing coordination cycles between architects and fabricators. This integration is electrifying competitive positioning for mid-cap specialists with captive CNC cutting and robotic welding capacity.
GB/T 51231 technical standards for prefabricated concrete structures are tightening quality thresholds for panel curing and connection detailing. SAMR enforcement of these provisions is disqualifying smaller precast suppliers lacking climate-controlled casting facilities. Residential developers in Hangzhou and Nanjing now require third-party certification of module structural integrity before site delivery.
Municipal housing authorities are consolidating supplier rosters around turnkey capability. Shanghai's affordable housing procurement now favors contractors delivering finished units with integrated MEP over component-only vendors. This consolidation is visible in Jiangsu province bidding documents that specify single-point accountability for weather-tightness and energy performance.
China Prefabricated Buildings Market Segmentation
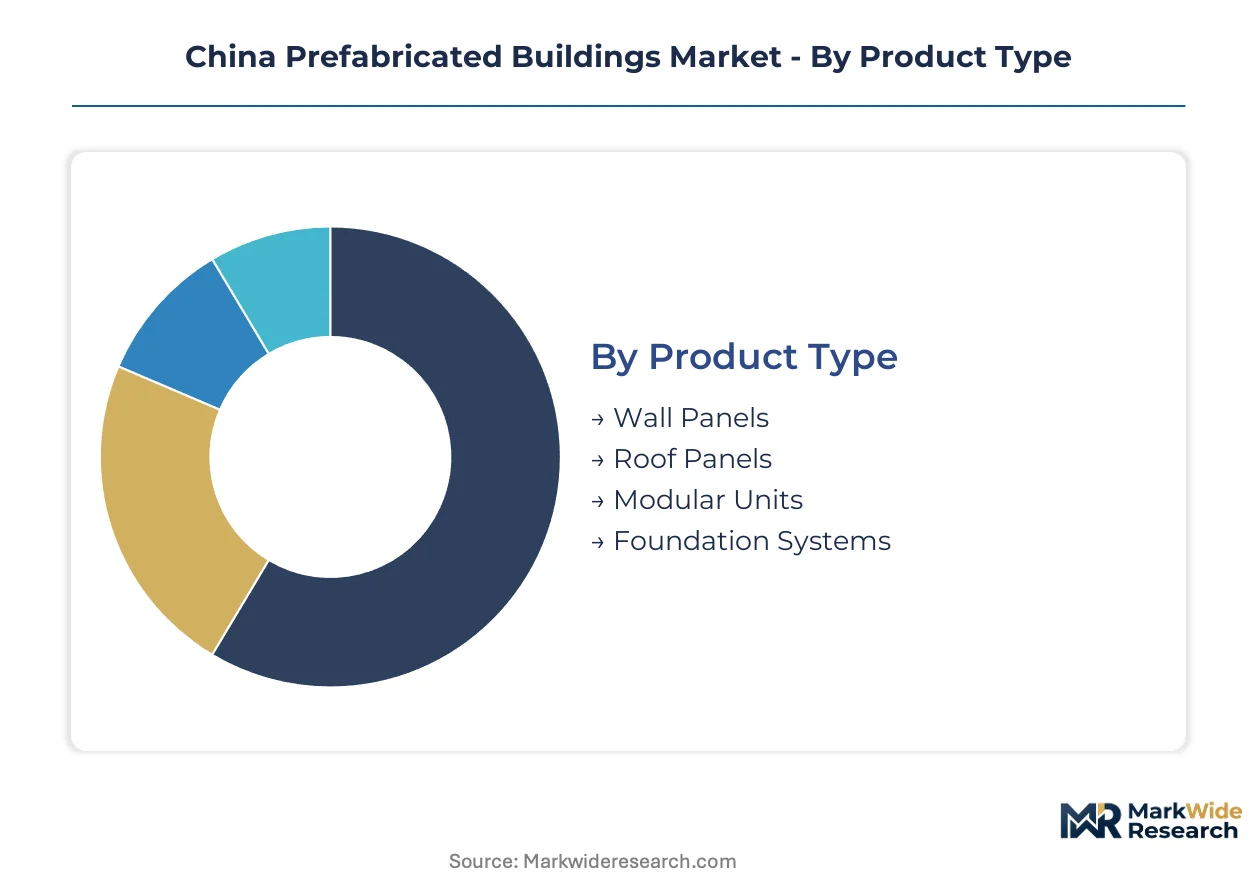
Prefabricated construction in China fragments across material systems, structural methods, and end-use applications. Each dimension carries distinct regulatory requirements under GB standards and MIIT directives that reshape supplier economics and procurement patterns.
Product Type:
Volume concentrates in standardized panels while premium margins accrue to finished modular units with integrated MEP systems.
- Modular Units:Factory-finished volumetric sections arrive site-ready with mechanical, electrical, and plumbing systems pre-installed. Shanghai municipal housing authorities now specify turnkey modular delivery for affordable housing projects, compressing construction schedules by eliminating on-site trade coordination.
- Wall Panels:Precast concrete and composite cladding panels dominate industrial and commercial facades. Jiangsu province fabricators reposition capacity toward panel production as GB/T 51231 quality thresholds disqualify smaller suppliers lacking climate-controlled curing facilities.
- Roof Panels:Insulated sandwich panels serve warehouse and logistics applications where span requirements favor lightweight steel-core construction.
- Foundation Systems:Precast pile caps and grade beams accelerate groundworks in Yangtze River Delta projects facing compressed timelines.
Today's leader: Modular units. Tomorrow's challenger: Wall panels.
Application:
Residential procurement drives volume through municipal mandates while commercial projects generate premium pricing for seismic-rated steel frameworks.
- Residential:Municipal housing authorities in Shanghai and Hangzhou consolidate supplier rosters around contractors delivering finished units with single-point accountability for weather-tightness and energy performance.
- Commercial:High-rise steel frameworks anchor Pudong district developments where GB 50017 seismic standards accelerate prefabricated structural adoption.
- Industrial:Warehouse and manufacturing facilities favor wide-span steel modules that reduce column interference with production layouts.
- Institutional:Schools and healthcare facilities adopt hybrid methods blending prefabricated envelopes with cast-in-place cores for flexibility.
Residential commands current procurement volume. Commercial offers the steepest expansion trajectory as seismic codes tighten.
Construction Method:
Hybrid approaches gain traction as developers optimize between factory precision and design flexibility.
- Hybrid:Combines prefabricated structural elements with cast-in-place cores to balance cost control with seismic performance in mid-rise residential. Chengdu-Chongqing corridor developers increasingly specify this method.
- Modular:Complete volumetric units minimize on-site labor but face highway transportation diameter constraints that limit design flexibility.
- Off-site:Panelized and component-based systems reduce site labor without modular unit scale requirements.
- Traditional:Cast-in-place methods persist where design changes late in development cycles outweigh prefabrication schedule benefits.
Hybrid methods currently dominate new specifications. Pure modular approaches face scaling headwinds from transport infrastructure limits.
Material:
Steel leads industrial applications while concrete retains cost advantage in residential mass housing.
- Steel:Fabricated to GB 50017 design codes, steel frames dominate commercial high-rises and industrial spans where seismic performance and rapid erection justify material premiums. Jiangsu and Zhejiang fabricators concentrate capacity here.
- Concrete:Precast panels and modules serve cost-sensitive residential segments where SAMR-certified suppliers with controlled curing facilities capture municipal procurement.
- Composite:Fiber-reinforced and sandwich panels penetrate facade applications requiring thermal performance without steel weight penalties.
- Wood:Engineered timber gains niche traction in low-rise institutional projects emphasizing carbon sequestration accounting under MEE embodied carbon limits.
Steel anchors premium commercial positioning. Concrete defends mass-market residential share through municipal cost discipline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redistributing prefabricated construction capacity toward provinces with streamlined GB standard compliance pathways. Cost-of-compliance gaps between coastal manufacturing clusters and inland development zones are accelerating production migration.
Yangtze River Delta
Shanghai municipal housing authorities consolidate procurement around turnkey modular contractors. MIIT industrialized construction directives compress project timelines for affordable housing developments. Steel fabricators across Jiangsu province reposition capacity from conventional structural steel toward modular unit fabrication.
Pearl River Delta
Guangdong province developers adopt hybrid construction methods blending prefabricated envelopes with cast-in-place cores. SAMR enforces GB/T 51231 quality thresholds that disqualify smaller precast suppliers lacking climate-controlled facilities. Shenzhen and Guangzhou anchor demand clusters where digital fabrication workflows electrify competitive positioning.
Beijing-Tianjin-Hebei
Hebei province steel producers supply structural frameworks for high-rise commercial projects under tightened GB 50017 seismic codes. MEE embodied carbon limits redirect municipal procurement toward factory-controlled production methods. Tianjin port infrastructure supports module export logistics for coastal fabricators.
Sichuan-Chongqing
Chengdu-Chongqing corridor infrastructure investment opens underserved markets where prefabricated construction penetration lags coastal benchmarks. Provincial governments translate national dual carbon targets into local procurement mandates. Chongqing developers increasingly specify hybrid methods for mid-rise residential projects.
Shandong Peninsula
Qingdao and Jinan anchor industrial prefabricated demand for warehouse and logistics applications. Steel material segments lead volume due to span requirements and seismic performance demands. Local fabricators concentrate capacity in wide-span steel modules that reduce column interference with production layouts.
China Prefabricated Buildings Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue export-grade manufacturing differentiation. State-backed contractors dominate turnkey developments through project pipeline control. The vendor base clusters around three archetypes: integrated state-owned enterprises, export-specialized module fabricators, and regional steel framework specialists. Competitive moves concentrate on capacity repositioning toward modular output and procurement of long-term steel supply contracts.
Among state-backed contractors, China State Construction Engineering Corp. occupies a position exemplifying turnkey capability dominance. CIMC Modular Building Systems and Hangxiao Steel Structure represent contrasting specialization vectors—container-derived export modules versus high-rise steel frameworks. These three entities anchor the competitive structure: one through state project pipeline access, one through manufacturing standard differentiation, and one through technical specialization in seismic-rated commercial structures.
| Leading Market Players |
|---|
| China State Construction Engineering Corp. |
| CIMC Modular Building Systems |
| Hangxiao Steel Structure |
| Ningbo Deepblue Smart House |
| Ark Prefab |
| Broad Group |
| Atlantic Modular System |
| Zhejiang Putian Integrated Housing |
| China Railway Construction Corp. |
| Others |
Pricing and Supply Chain Analysis
Dual carbon policy enforcement gates qualified supply access and premium-tier pricing power, as MEE embodied carbon limits disqualify conventional site-casting methods and redirect municipal procurement toward factory-certified modular units with integrated MEP systems.
Pricing Analysis
Distributor margins for Jiangsu province fabricators compress under steel price volatility, while direct-to-developer contracts with state-backed contractors secure volume discounts. Three-tier pricing structure across SAMR-certified premium, GB-compliant standard, and uncertified economy levels separates turnkey modular delivery from component-only supply. Cost compression in standard-tier wall panels intensifies as climate-controlled curing facility investments raise fixed-cost barriers. Municipal housing authorities exhibit highest price sensitivity, while commercial developers in Shanghai's Pudong district prioritize seismic performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Jiangsu and Zhejiang provinces anchor hub-and-spoke patterns serving Yangtze River Delta demand clusters. Manufacturing concentrates in China, with steel feedstock drawn from Hebei province mills and connector hardware sourced from specialized Zhejiang fabricators. Single-source vulnerability persists for SAMR-certified structural connectors, where qualified supplier rosters remain narrow. Distribution runs through state-backed contractor logistics networks for turnkey developments, while component vendors rely on highway-bounded module dimensions that constrain design flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's prefabricated buildings market represents a late-cycle quality story as municipal procurement consolidates around turnkey contractors delivering finished units with single-point accountability for weather-tightness and energy performance.
For Market Incumbents: Lock in long-term steel supply contracts with Hebei province mills to defend margin position against raw material cost swings. Secure SAMR certification acceleration for GB-compliant structural connectors to raise competitive barriers against unqualified suppliers threatening component-tier pricing. For New Entrants and Emerging Players: MIIT industrialized construction directives in Jiangsu province open a window for specialized MEP integration technicians cross-trained in manufacturing and construction protocols. Target Chengdu-Chongqing corridor infrastructure investment with hybrid construction method expertise, positioning as regional hybrid-method specialists rather than pure modular competitors. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap steel fabricators with captive CNC cutting and robotic welding capacity because digital fabrication workflows electrify competitive positioning and create acquisition currency. Monitor provincial government translation of national dual carbon targets into local procurement mandates as the inflection indicator for competitive access reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Feedstock | Hebei province mill partnerships reduce exposure to spot price volatility for Jiangsu fabricators. |
| SAMR Certification Acceleration | Streamlined GB-compliant connector approval reduces time-to-market for qualified component suppliers. |
| Digital Fabrication Workflow Investment | BIM-to-fabrication integration electrifies competitive positioning for mid-cap specialists in Jiangsu. |
| Hybrid Construction Method Specialization | Chengdu-Chongqing corridor developers increasingly specify blended prefabricated-cast-in-place approaches. |
| Turnkey Modular Capability Buildout | Shanghai municipal housing procurement now favors finished units with integrated MEP over component-only vendors. |
Research Methodology
Bottom-up municipal housing procurement modeling reconciled against top-down steel fabricator capacity tracking forms the analytical core of this study. Primary interviews with procurement officers at China State Construction Engineering Corp., plant managers at Jiangsu province fabricators, and regulatory affairs specialists navigating SAMR certification pathways combined with secondary validation from MIIT industrialized construction directives, GB standard technical documents, and provincial bidding records. Triangulation across these sources ensures segment-level accuracy.
Input-output matrices map steel material flows through fabrication stages to end-use applications across the projection horizon. Segmentation dimensions include material system, construction method, application, and regional regulatory cluster. CAGRs derive from volume trajectory analysis calibrated against policy implementation timelines and infrastructure investment cycles. Forecast inputs incorporate MEE embodied carbon limit enforcement schedules and provincial dual carbon target translations.
Revisions become necessary when steel price volatility exceeds historical bands or when SAMR accelerates GB standard compliance timelines beyond modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Vertical Garden Construction Market
Building Construction
Turkey Construction Market
Building Construction
Malaysia Construction Market
Building Construction
North America Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
South Korea Data Center Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
Bangladesh Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Saudi Arabia Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
Europe Prefab Wood Buildings Market