
 Modular and Portable Building Market | 2026-2036
Modular and Portable Building Market Size, Share, and Industry Trends Forecast 2026-2036
Modular and Portable Building Market Insights
Healthcare infrastructure is repositioning the end-use vertical mix for modular and portable buildings, with hospitals and clinics now representing a faster-growing procurement channel than traditional construction site offices. Clayton Homes leverages its manufacturing scale to dominate the North American permanent modular housing segment. Bouygues Construction anchors its European position through advanced prefabrication capabilities and stringent sustainability compliance. Skanska competes on integrated project delivery, combining modular fabrication with its construction management expertise across multiple continents.
Modular and portable buildings comprise factory-manufactured volumetric units, typically steel-framed or timber-framed, assembled under controlled conditions and transported to final sites for installation with utility connections. These structures achieve primary commercial purpose through accelerated project timelines, reduced on-site labor, and repeatable quality standards that conventional construction struggles to match. Modular homes currently occupy the largest product type position, while portable offices generate concentrated margin pools from short-term rental arrangements in remote locations. The education end-user segment is gaining structural share as school districts pursue faster capacity expansion, and custom units command premium positioning where dimensional flexibility addresses site-specific constraints.
FDA guidelines influence modular healthcare facility specifications, while OSHA standards govern factory fabrication worker safety and on-site assembly protocols in the United States. The EU Green Deal and CE marking requirements are reshaping material sourcing and energy performance thresholds for European manufacturers seeking market access. Stakeholders must monitor evolving national building codes and carbon disclosure mandates that will determine which prefabrication technologies achieve regulatory preference in priority markets.
Market Dynamics
Healthcare infrastructure investment is compressing project timelines and forcing procurement departments toward factory-fabricated alternatives that bypass weather-dependent site work. The EU Green Deal's embodied carbon thresholds are disqualifying traditional concrete-heavy methods from public tenders.
Growth Catalysts
- EU Green Deal compliance mandates:European public procurement now prioritizes modular structures with verified lifecycle carbon footprints, redirecting hospital and school construction budgets toward offsite fabrication.
- Remote mining operations in Australia:Fly-in-fly-out workforce housing requirements sustain large-volume orders for relocatable dormitories and site offices with rapid deployment specifications.
- Cross-laminated timber (CLT) panelization:Engineered wood systems reduce foundation loads and enable crane-set installation in dense urban infill sites where conventional concrete delivery proves impractical.
Market Restraints
- Steel price volatility:Cold-formed steel framing constitutes the dominant structural system for volumetric units, exposing fabricators to scrap metal commodity swings that compress bid margins.
- Transportation diameter constraints:Highway corridor width and bridge clearance limits in Japan and the United Kingdom cap module dimensions, forcing design compromises that sacrifice interior efficiency.
- Skilled welder scarcity:Factory fabrication of steel-framed volumetric units depends on certified structural welders, with labor pool shortages in Germany and Australia extending production lead times.
Strategic Opportunities
- Disaster relief stockpiling in Indonesia:National disaster management agencies are pre-positioning flat-packed emergency housing units, creating recurring procurement channels distinct from commercial construction cycles.
- Battery energy storage integration:Modular buildings paired with containerized BESS units serve grid-isolated mining camps and remote healthcare clinics, opening cross-selling opportunities with clean power developers.
- CE marking acceleration:Harmonized European technical approval processes for modular structural systems reduce country-by-country certification burdens, lowering market entry costs for compliant manufacturers.
Industry Challenges
- Building information modeling (BIM) interoperability:Factory design software and site civil engineering platforms use incompatible data formats, forcing manual translation errors during module-to-foundation coordination.
- Utility connection standardization:Municipal water, sewer, and electrical hookup specifications vary by jurisdiction, preventing plug-and-play installation and requiring costly field adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular and Portable Building Market |
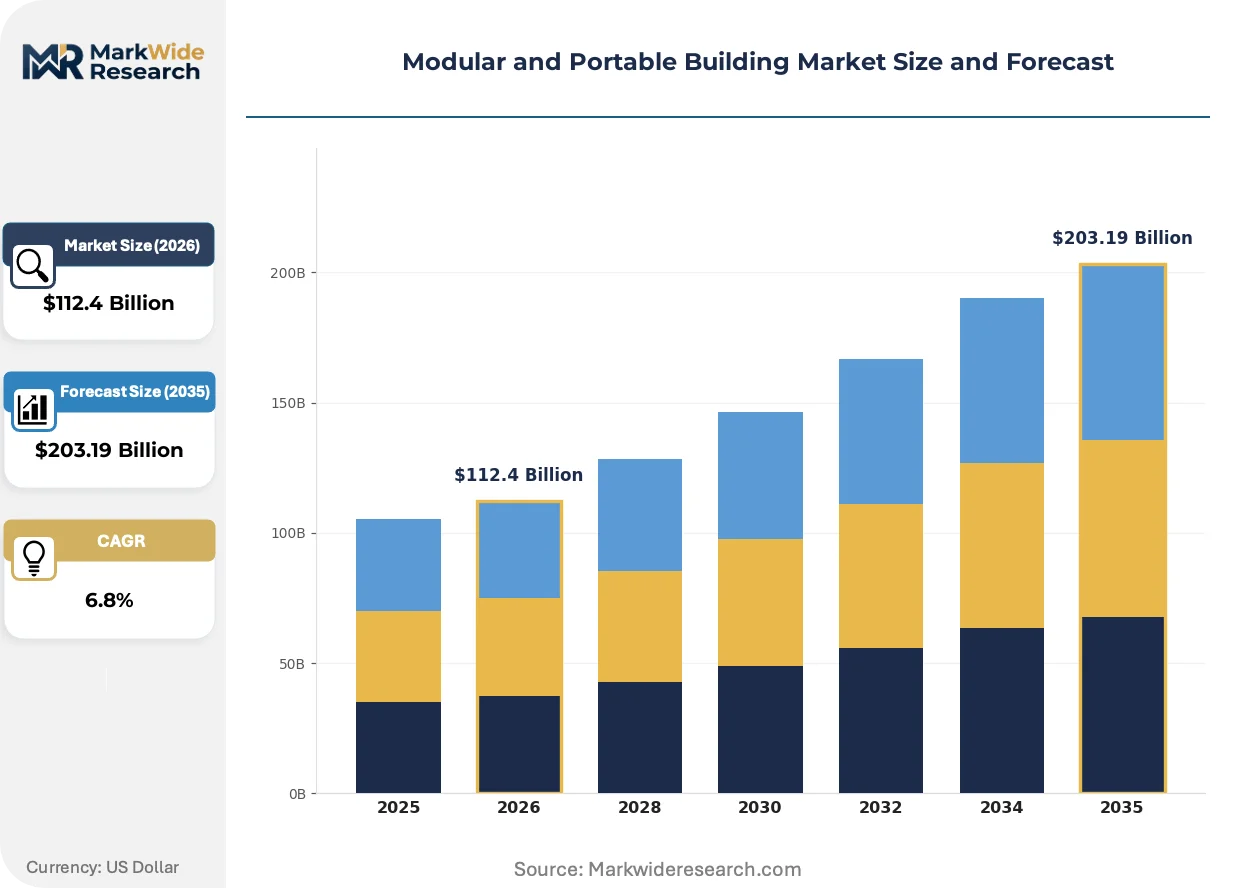
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Portable Offices, Temporary Structures, Shipping Containers End User: Construction, Education, Healthcare, Military Deployment: On-Site, Remote Locations, Urban Areas, Rural Areas Size: Small Scale, Medium Scale, Large Scale, Custom Units |
| Companies Covered | Red Sea International, Bouygues Construction, Laing O'Rourke, Modulaire Group, ATCO Ltd., Skanska, Balfour Beatty, Clayton Homes, Lendlease Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular and Portable Building Market Trends and Innovations
Digital fabrication and regulatory carbon accounting are converging to redefine competitive advantage in offsite construction. Factory environments now enable precision that site-based methods cannot replicate.
Light-gauge steel framing combined with automated roll-forming is overtaking traditional stick-built timber in multi-story modular housing. Student housing developers in the United Kingdom and the Netherlands specify steel volumetric units for fire-rated vertical stacking. This shift is overtaking timber-dominated mid-rise construction in markets where insurance premiums penalize combustible structural systems.
REACH chemical restrictions and the EU Green Deal's embodied carbon disclosure requirements are forcing resin and insulation suppliers to reformulate core materials. Manufacturers must now document cradle-to-gate environmental product declarations for steel, concrete, and composite components. Hospital construction teams in France and Germany are rejecting modules lacking verified EPDs, redirecting specification authority toward sustainability-certified fabricators.
Lease-to-own financing structures are displacing outright purchase for portable classroom and site office fleets. School districts in Texas and Florida now contract for temporary capacity with embedded purchase options, transferring residual value risk to rental providers. Mining operators in Western Australia have adopted identical structures for workforce housing, consolidating procurement under long-term service agreements rather than capital budgets.
Modular and Portable Building Market Segmentation
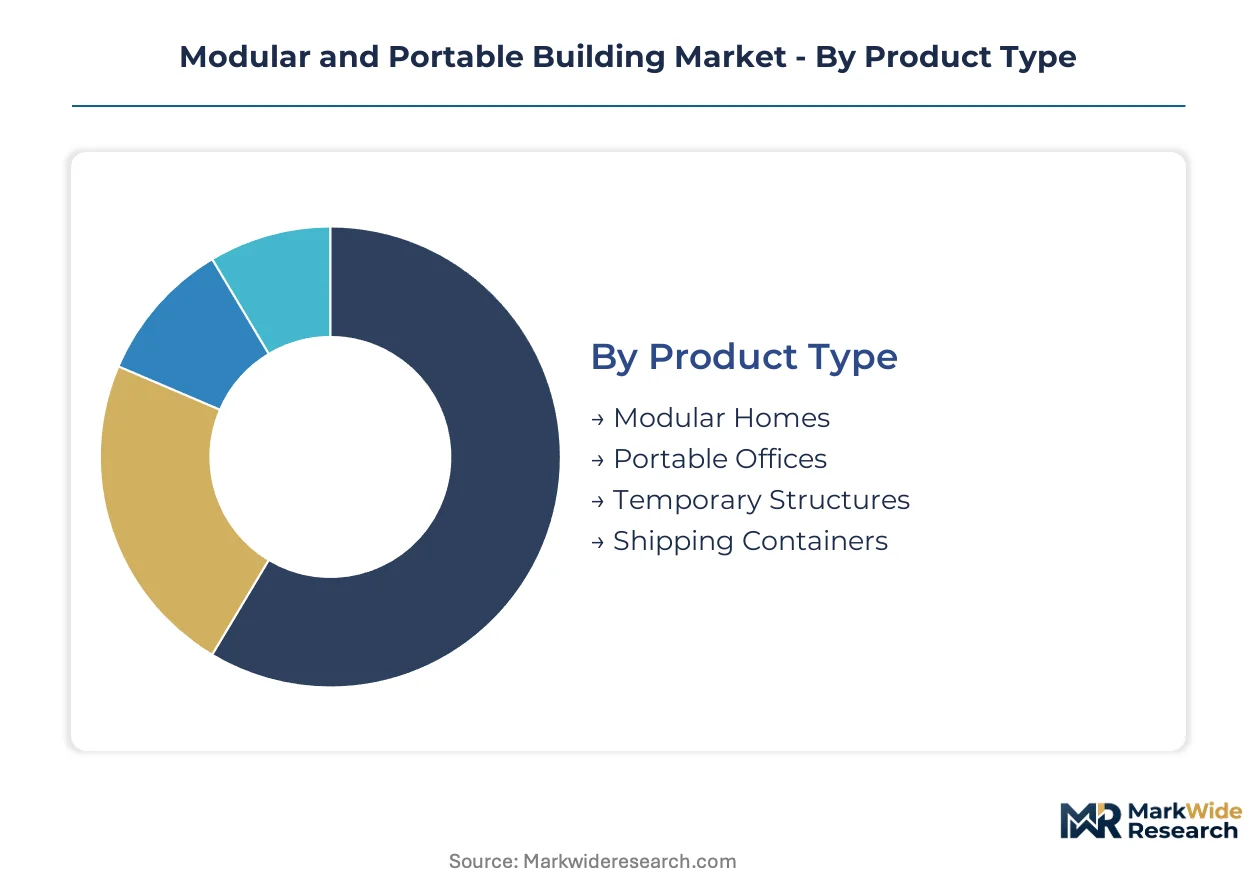
Segmentation in the modular and portable building market reveals how procurement priorities diverge across structural permanence, end-use requirements, and site constraints. Factory-fabricated units serve fundamentally different economic functions depending on whether they anchor long-term occupancy or satisfy transient workforce housing needs.
Product Type:
Standalone permanent installations dominate capital deployment, while embedded rental fleets generate recurring service revenue through rapid redeployment cycles.
- Modular Homes:Steel-framed or timber-framed volumetric units engineered for permanent foundation anchoring and full utility integration. Demand concentrates in France and Germany where hospital construction teams reject modules lacking verified environmental product declarations under EU Green Deal procurement rules.
- Portable Offices:Relocatable single or multi-unit configurations designed for short-term lease with crane-assisted transport. Mining operators in Western Australia contract for workforce housing through long-term service agreements rather than capital budgets, consolidating procurement under embedded purchase options.
- Temporary Structures:Rapid-assembly fabric or panel systems for event and emergency deployment.
- Shipping Containers:Repurposed intermodal units modified for habitation with cutouts for fenestration and MEP routing.
Volume placements concentrate in modular homes; the faster expansion belongs to portable offices.
End User:
Public sector procurement channels reward lifecycle carbon documentation, while private extractive industries prioritize deployment velocity over certification depth.
- Construction:Site offices, worker dormitories, and material storage modules serving project-phase occupancy. School districts in Texas and Florida now contract for temporary classroom capacity with lease-to-own structures, transferring residual value risk to rental providers.
- Healthcare:Clinics, diagnostic facilities, and hospital expansion wings requiring FDA-compliant MEP specifications and infection control protocols. French and German hospital construction teams specify only modules with cradle-to-gate environmental product declarations.
- Education:Classroom additions and campus expansion for enrollment surge accommodation.
- Military:Barracks, command posts, and field hospitals with blast-resistant and CBRN protection specifications.
Construction absorbs the highest unit volumes; healthcare claims the steepest expansion trajectory as infrastructure investment compresses project timelines.
Deployment:
Site accessibility determines module dimension limits and foundation system selection, with transportation corridors imposing hard constraints on volumetric geometry.
- Remote Locations:Grid-isolated sites requiring self-contained power, water, and waste systems. Mining camps in Western Australia pair modular dormitories with containerized battery energy storage units, opening cross-selling channels with clean power developers.
- Urban Areas:Dense infill sites where crane-set installation and minimal foundation loads prove essential. Cross-laminated timber panelization enables mid-rise student housing in the United Kingdom and Netherlands where insurance premiums penalize combustible structural systems.
- On-Site:Adjacent-to-foundation placement with direct utility tie-in.
- Rural Areas:Low-density settings with septic-dependent waste systems and well or rainwater catchment supply.
Remote locations sustain premium pricing; urban areas are climbing the fastest as land scarcity forces vertical stacking solutions.
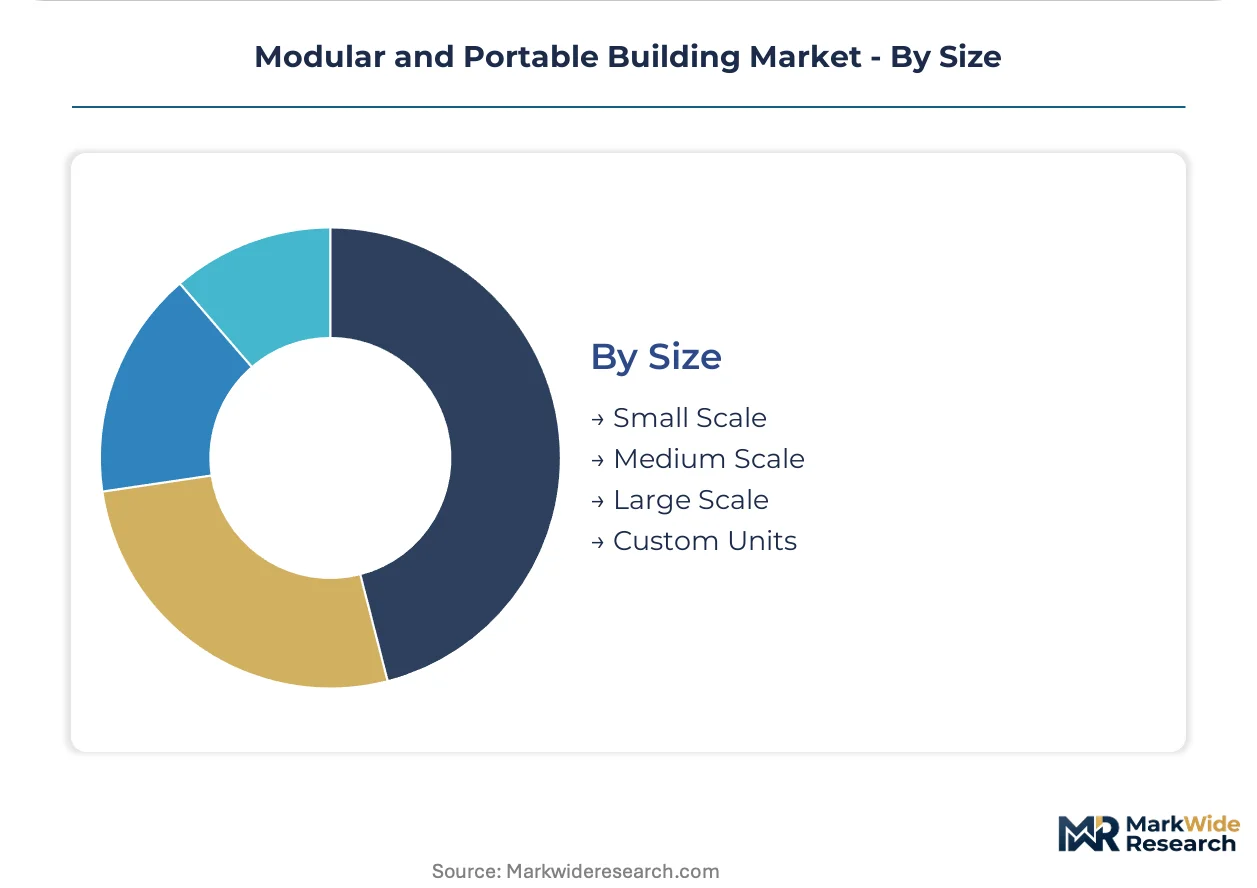
Size:
Economies of scale in factory production favor dimensional standardization, though site-specific constraints perpetuate custom specification for constrained footprints.
- Large Scale:Multi-module interconnected complexes exceeding single-transport dimensions. Highway corridor width and bridge clearance limits in Japan and the United Kingdom cap module dimensions, forcing design compromises that sacrifice interior efficiency.
- Custom Units:Dimensional flexibility addressing irregular sites, heritage adjacency, or specialized equipment housing. Factory design software and site civil engineering platforms use incompatible data formats, forcing manual translation errors during module-to-foundation coordination.
- Small Scale:Single-transport modules within standard truckbed dimensions.
- Medium Scale:Two-to-four module assemblies requiring sequential crane placement.
Large scale captures institutional procurement volumes; custom units gain share fastest where municipal utility connection specifications vary by jurisdiction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Western Australia concentrate fly-in-fly-out workforce housing procurement, while EU Green Deal compliance zones in France and Germany redirect hospital construction budgets toward certified fabricators. Remote mining corridors and disaster-prone archipelagos sustain premium pricing for rapid-deployment units.
United States
Lease-to-own financing structures for portable classrooms concentrate procurement in Texas and Florida school districts. OSHA standards govern factory fabrication worker safety and on-site assembly protocols. Clayton Homes anchors manufacturing scale in the permanent modular housing segment across the Southeast and Midwest.
Australia
Remote mining operations sustain large-volume orders for relocatable dormitories and site offices with rapid deployment specifications. National disaster management agencies pre-position flat-packed emergency housing units, creating recurring procurement channels. Western Australia's mining camps pair modular facilities with containerized battery energy storage units.
Germany
Hospital construction teams reject modules lacking verified environmental product declarations under EU Green Deal procurement rules. CE marking requirements reshape material sourcing and energy performance thresholds for manufacturers seeking market access. Skilled welder scarcity extends production lead times for steel-framed volumetric units in industrial clusters.
United Kingdom
Student housing developers specify steel volumetric units for fire-rated vertical stacking in dense urban infill sites. Highway corridor width and bridge clearance limits cap module dimensions, forcing design compromises. Cross-laminated timber panelization enables mid-rise construction where insurance premiums penalize combustible structural systems.
France
Healthcare infrastructure investment compresses project timelines and forces procurement departments toward factory-fabricated alternatives. REACH chemical restrictions force resin and insulation suppliers to reformulate core materials. Hospital construction teams in Paris and Lyon specify only modules with cradle-to-gate environmental product declarations.
Modular and Portable Building Market Competitive Landscape
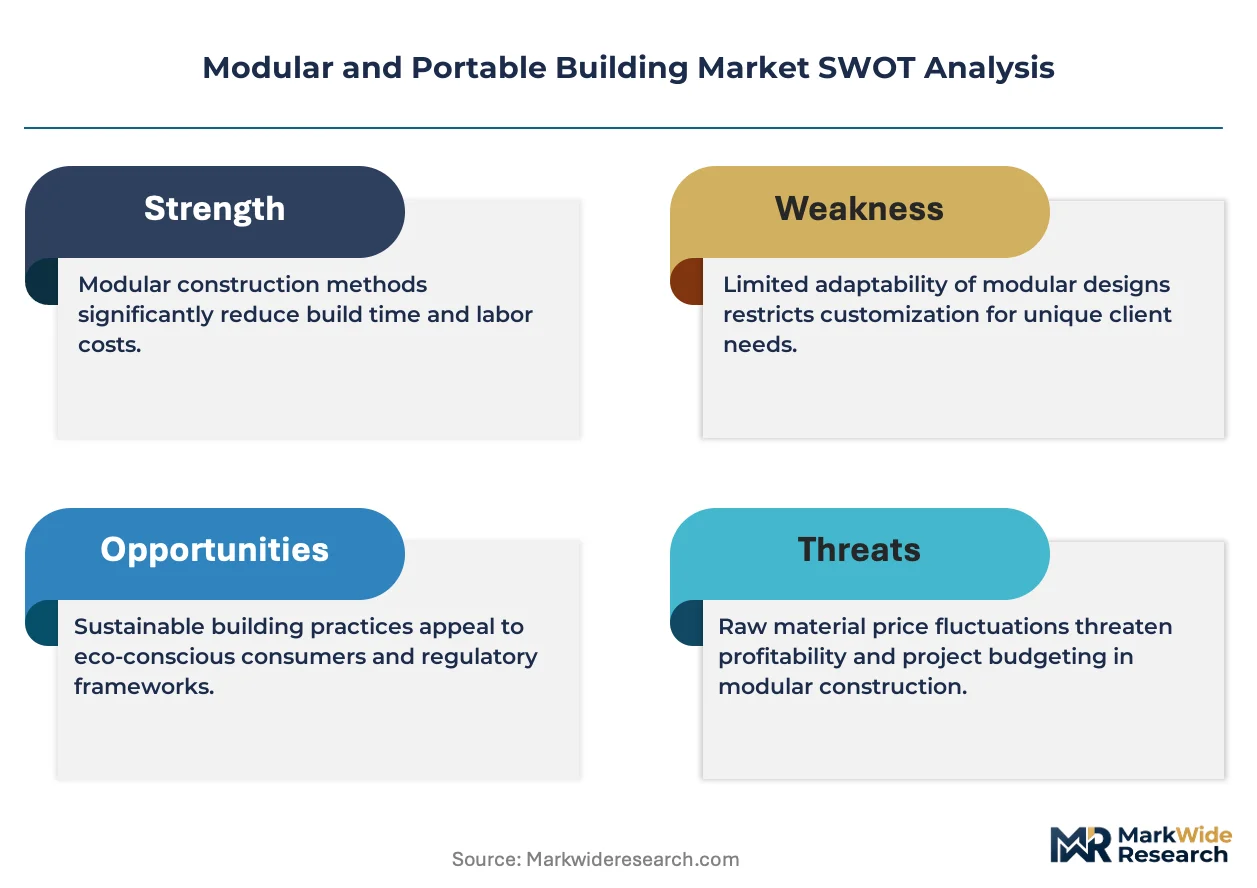
Branded specialists and contract manufacturers split share differently across segments, with permanent modular housing consolidating around scale-driven fabricators while portable rental fleets fragment across regional service providers. The vendor base organizes into three archetypes: integrated construction conglomerates with captive fabrication capacity, pure-play modular specialists leveraging manufacturing density, and rental fleet operators monetizing asset turnover. Dominant competitive moves include strategic partnerships pairing modular fabrication with clean power developers, and portfolio diversification into battery energy storage integration for grid-isolated deployments.
Among North American fabricators, Clayton Homes exemplifies the scale-driven permanent housing archetype, while Bouygues Construction anchors European positioning through advanced prefabrication capabilities and stringent sustainability compliance. Skanska occupies a position combining modular fabrication with integrated project delivery expertise across multiple continents.
| Leading Market Players |
|---|
| Red Sea International |
| Bouygues Construction |
| Laing O'Rourke |
| Modulaire Group |
| ATCO Ltd. |
| Skanska |
| Balfour Beatty |
| Clayton Homes |
| Lendlease Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive fabrication capacity in Germany and Australia anchors supply positions for steel-framed volumetric units, with in-house production of cold-formed steel framing insulating fabricators from commodity scrap metal swings while concentrating pricing power among scale operators. This integration choice compresses bid margins for outsourced competitors but enables premium positioning for certified fabricators meeting EU Green Deal embodied carbon thresholds.
Pricing Analysis
Premium pricing for sub-12-week lead times commands 15-25% markups over standard 16-20 week delivery windows, with spot inventory of pre-certified modules trading at further discounts. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking status, environmental product declaration depth, and after-sales service bundling. Cost compression in economy-tier portable offices is intensifying because school districts and mining operators consolidate procurement under long-term service agreements. Healthcare construction teams in France and Germany exhibit lowest price sensitivity, prioritizing verified lifecycle carbon documentation over unit cost.
Supply Chain Analysis
Workforce availability constraints in German industrial clusters and Western Australian fabrication yards extend production lead times for certified structural welders, forcing capacity allocation toward highest-margin healthcare contracts. Supply concentrates in Germany, Australia, and the United States, with cold-formed steel, cross-laminated timber panels, and mineral wool insulation as critical inputs. Single-source vulnerability in European resin and insulation supply chains under REACH chemical restrictions threatens material reformulation timelines. Distribution runs through direct-to-project logistics for permanent modular housing and rental fleet operators for portable offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around certified structural welders and environmental product declaration documentation prop pricing power for compliant fabricators, creating durable margin pools for incumbents with captive certification capabilities.
For Market Incumbents: Deepen backward integration into cold-formed steel roll-forming and CLT panel production to insulate margins from commodity volatility and timber supply disruptions. Acquire distressed rental fleet operators in Western Australia and Texas to consolidate procurement relationships with mining operators and school districts. Defend against emerging pure-play sustainability specialists by accelerating CE marking for structural systems beyond country-by-country certification burdens. For New Entrants and Emerging Players: The price-point gap between premium CE-marked healthcare modules and economy-tier portable classrooms creates entry space for mid-market fabricators with rapid-deployment capabilities. Target Indonesian disaster relief stockpiling programs and Indonesian national disaster management agency procurement channels, where certification requirements remain less stringent than EU markets. Pursue lease-to-own financing partnerships with regional mining contractors to bypass capital budget approval cycles. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated construction conglomerates seeking captive fabrication capacity. Five-to-ten year viability hinges on carbon accounting infrastructure maturation and EU Green Deal procurement rule expansion beyond healthcare into education and military segments. Monitor CE marking acceleration timelines and skilled welder training program graduation rates as inflection indicators for supply constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Environmental Product Declaration Investment | Hospital construction teams in France and Germany reject modules lacking verified EPDs under EU Green Deal rules. |
| Cross-Laminated Timber Panelization Scale-Up | Student housing developers in the United Kingdom and Netherlands specify engineered wood for fire-rated vertical stacking. |
| Battery Energy Storage Integration | Western Australian mining camps pair modular dormitories with containerized BESS units from clean power developers. |
| Disaster Relief Stockpiling Contracts | Indonesian national disaster management agencies pre-position flat-packed emergency housing units for recurring procurement. |
| Lease-to-Own Financing Structure Deployment | Texas and Florida school districts contract for temporary classroom capacity with embedded purchase options transferring residual value risk. |
Research Methodology
Multi-period observation of steel price volatility indices, CE marking approval timelines, and modular construction permit filings anchored the trend analysis, supplemented by interviews with fabrication plant managers, hospital procurement directors, mining camp logistics coordinators, and CLT panel suppliers. Secondary validation drew from EU Green Deal implementation progress reports, OSHA factory inspection data, Australian Bureau of Statistics mining workforce housing expenditure series, and SEC filings from publicly traded construction conglomerates. Bottom-up module shipment tracking and top-down construction spending allocation models were triangulated to verify volume estimates.
Input-output matrices mapped cold-formed steel consumption, crane-assisted transport capacity, and certified welder labor hours to module output across product type and deployment segments over the projection horizon. Segmentation dimensions modeled included structural permanence classification, end-use vertical, site accessibility tier, and dimensional scale category. CAGRs were derived from regression analysis of historical shipment growth against infrastructure investment cycles and carbon disclosure mandate adoption curves. Forecast inputs incorporated EU Green Deal procurement rule phase-in schedules and cross-laminated timber manufacturing capacity expansion pipelines.
Inputs from hospital procurement databases, mining operator contract registries, and national building permit aggregators were available through the study window; gaps in real-time steel scrap pricing at mill gate and unreported private rental fleet transactions introduce uncertainty bands around portable office revenue estimates. Forecasts reflect assumptions regarding CE marking harmonization progress and REACH chemical restriction implementation timelines. Material deviation in EU Green Deal enforcement intensity, skilled welder immigration policy shifts, or cross-laminated timber insurance premium recalibration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Honduras Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Australia Construction Market
Building Construction
Kuwait Construction Market
Building Construction
United States Commercial Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Middle East Building Construction Market
Building Construction
Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Germany Commercial Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
UAE Transportation Infrastructure Construction Market