
 South Korea Data Center Construction Market | 2026-2036
South Korea Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Data Center Construction Market Insights
Hyperscale cloud operators is bifurcating demand away from traditional enterprise builds across the South Korean data center landscape. Samsung C&T Corporation leverages its integrated construction and technology supply chain to capture premium hyperscale contracts. Hyundai Engineering and Construction anchors its position through heavy civil expertise adapted to large-scale campus developments. DL E&C competes on specialized mechanical and electrical systems for high-density computing environments.
Data center construction encompasses the engineering, procurement, and construction of facilities designed to house computing infrastructure with power densities exceeding 15 kilowatts per rack and precision cooling systems maintaining temperatures within strict thresholds. The primary purpose centers on creating controlled environments that ensure continuous operation of servers, storage, and networking equipment for digital service delivery. New build construction dominates capital allocation as cloud service providers and colocation operators expand footprint, while modular approaches gain traction for speed-to-market in secondary locations. Cooling systems represent a critical technology segment where liquid immersion and free-air cooling methods are displacing traditional mechanical approaches amid energy cost pressures.
MFDS standards for equipment safety, KTL certifications for electrical infrastructure, and Ministry of Environment emissions regulations shape facility design and equipment selection across Korean data center projects. The National Strategic Smart Data Center initiative further directs public investment toward energy-efficient builds in designated zones. Stakeholders must monitor policy shifts around renewable energy procurement mandates and carbon intensity benchmarks that will determine site viability and long-term operating economics.
Market Dynamics
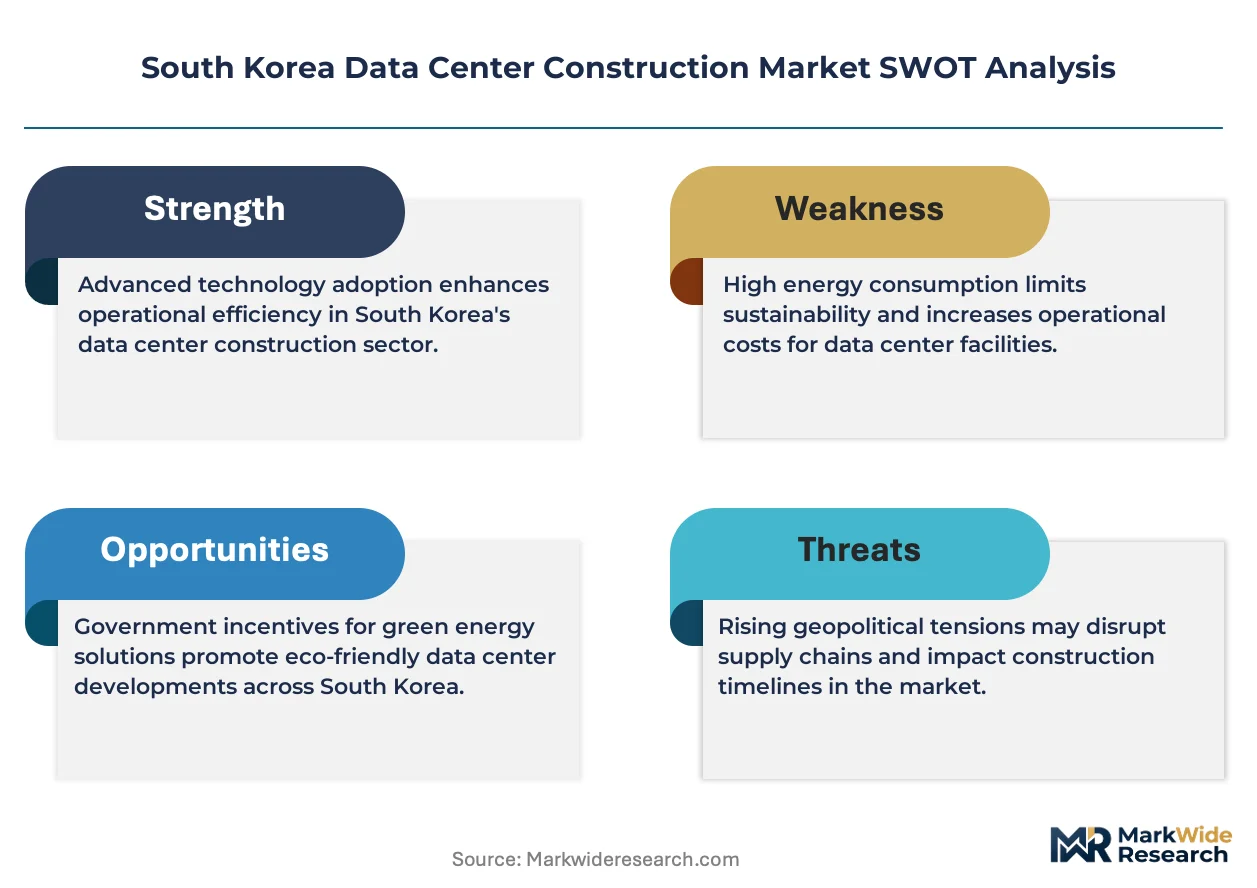
The Korean government's Green New Deal policy framework is forcing hyperscale cloud operators and colocation developers to redesign facility specifications around carbon intensity benchmarks and renewable energy procurement mandates before breaking ground on new campuses.
Growth Catalysts
- Cloud service provider expansion:Hyperscale operators are aggressively securing land and power allocations in the Seoul metropolitan area and Pangyo technology cluster to meet domestic digital service demand.
- MFDS equipment safety standards:Certification requirements for electrical infrastructure are accelerating professionalization of contractor capabilities and reducing post-construction commissioning delays.
- Liquid immersion cooling adoption:Energy efficiency pressures under the Green New Deal are pulling mechanical system upgrades into new build specifications ahead of traditional replacement cycles.
Market Restraints
- Land scarcity in Gyeonggi Province:The concentration of viable hyperscale sites around Pangyo is driving land cost inflation and extending site acquisition timelines.
- Specialized MEP contractor concentration:A limited pool of Korean firms capable of high-density power distribution and precision cooling installation creates bottleneck risk during construction surges.
- Grid interconnection queues:KEPCO infrastructure upgrade timelines often lag behind data center power demand schedules, delaying facility energization.
Strategic Opportunities
- Secondary city deployment:Busan and Gwangju offer underutilized power grid capacity and government incentive zones for disaster recovery and latency-sensitive edge facilities.
- Modular construction methods:Prefabricated mechanical and electrical modules are compressing speed-to-market for cloud providers facing competitive pressure to activate capacity.
- National Strategic Smart Data Center initiative:Public investment directed toward designated zones creates co-funding pathways for energy-efficient builds that exceed baseline Green New Deal requirements.
Industry Challenges
- Critical facility engineering talent:The shortage of professionals experienced in concurrent maintainability design and tier certification processes is extending design-review cycles.
- Legacy mechanical system integration:Retrofit projects in existing Seoul facilities face spatial constraints when upgrading to liquid cooling architectures compatible with high-density racks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Data Center Construction Market |
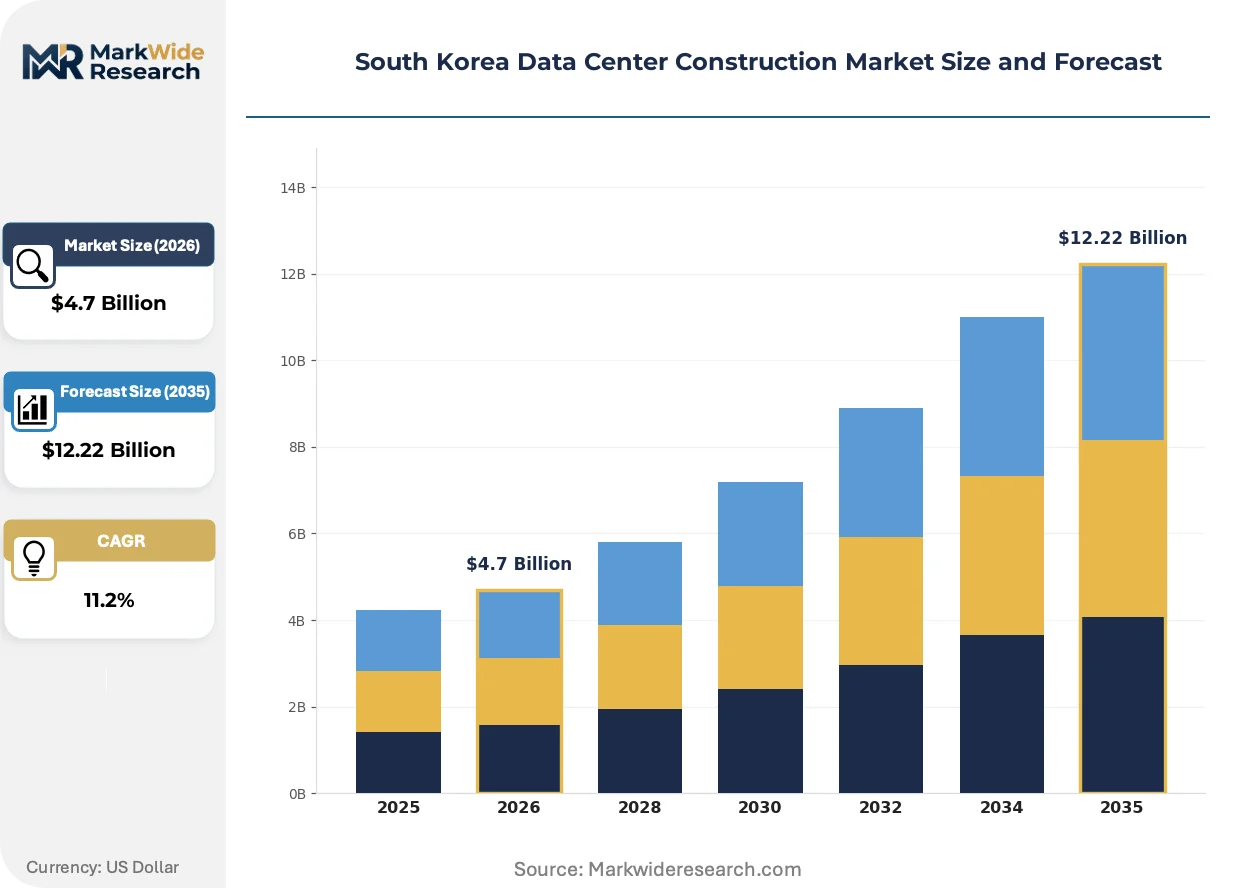
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.22 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: New Build, Expansion, Renovation, Modular Technology Used: Cooling Systems, Power Distribution, Server Hardware, Network Infrastructure End User: Cloud Service Providers, Enterprises, Colocation Providers, Government Size: Small, Medium, Large, Hyper-scale |
| Companies Covered | Samsung C&T Corporation, Hyundai Engineering and Construction, DL E&C, GS Engineering and Construction, SK ecoplant, POSCO E&C, HanmiGlobal, Lotte E&C, Fir Hills Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Data Center Construction Market Trends and Innovations
Cooling technology, regulatory compliance frameworks, and procurement structures are simultaneously transforming how Korean data center projects are engineered, financed, and delivered.
Direct-to-chip liquid cooling is miniaturizing heat removal infrastructure relative to traditional raised-floor air distribution. Hyperscale operators are specifying this architecture in new Pangyo campuses to achieve power usage effectiveness targets below 1.2. The technology is miniaturizing mechanical plant footprints and enabling higher rack densities within fixed building envelopes.
The Ministry of Environment emissions regulations are tightening refrigerant selection criteria for mechanical cooling systems. Facility designers must now specify low-global-warming-potential working fluids or alternative cooling methods to secure construction permits. Colocation operators in Seoul are responding by accelerating free-air cooling and evaporative system deployments to preempt compliance-driven retrofit costs.
Cloud service providers are consolidating construction procurement around design-build contracts with integrated MEP responsibility. This model displaces fragmented general contractor and specialist subcontractor arrangements that dominated earlier Korean data center waves. The shift is most visible in Gyeonggi Province hyperscale projects where single-source accountability compresses commissioning schedules and reduces interface risk between civil and mechanical workstreams.
South Korea Data Center Construction Market Segmentation
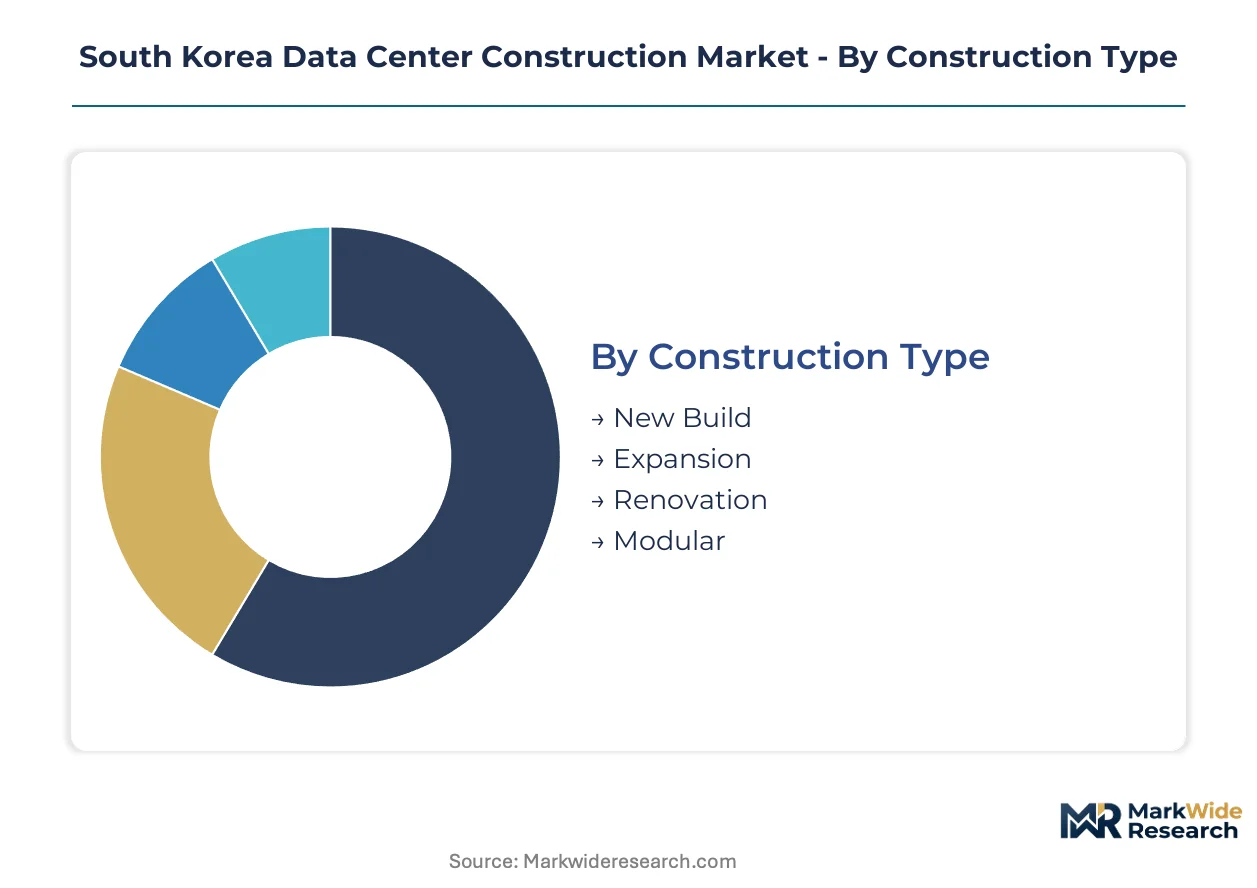
Segmentation in South Korea's data center construction market reveals how capital allocation splits across facility lifecycles, technology layers, and customer scale tiers. Understanding these divisions exposes where procurement power concentrates and which specifications dominate contract negotiations.
Construction Type:
New build contracts flow through design-build channels with integrated MEP accountability, while modular and renovation work often routes through specialized subcontractors serving speed-sensitive or constrained-site requirements.
- New Build:Greenfield campus developments with concurrent maintainability design and tier certification requirements anchor capital deployment. Cloud service providers in Pangyo and Seoul metropolitan area drive demand for these ground-up facilities with dedicated substations and liquid cooling infrastructure.
- Expansion:Phased capacity additions to existing hyperscale campuses leverage pre-approved power allocations and established grid interconnections. KEPCO infrastructure upgrade timelines often dictate construction sequencing for these projects.
- Renovation:Mechanical system upgrades in legacy Seoul facilities address spatial constraints when retrofitting for high-density racks. The Ministry of Environment emissions regulations accelerate refrigerant replacement schedules in these retrofit environments.
- Modular:Prefabricated mechanical and electrical modules compress speed-to-market for secondary city deployments. Busan and Gwangju incentive zones pull modular approaches for disaster recovery facilities requiring rapid activation.
New build dominates installed base. Modular is where expansion concentrates.
Technology Used:
Cost tier stratification separates premium liquid cooling specifications from standard mechanical approaches, with power distribution commanding margin premiums across all facility scales.
- Cooling Systems:Direct-to-chip liquid cooling architectures achieve power usage effectiveness below 1.2 in Pangyo hyperscale campuses. Free-air cooling and evaporative systems gain share in Seoul colocation facilities preempting compliance-driven retrofit costs under tightening refrigerant regulations.
- Power Distribution:High-density busway and switchgear installations serving racks exceeding 15 kilowatts require specialized Korean MEP contractor capabilities. KEPCO grid interconnection queues create bottleneck risk during construction surges for these electrical systems.
- Server Hardware:Rack integration and containment specifications vary by customer tier, with cloud providers dictating custom form factors. KTL certifications for electrical infrastructure shape equipment selection timelines.
- Network Infrastructure:Structured cabling and fiber distribution systems support latency requirements for edge and core facilities. Secondary city deployments in Gwangju prioritize network redundancy for disaster recovery applications.
Cooling systems command highest specification intensity. Power distribution is where contractor scarcity creates margin pressure.
End User:
Customer type determines procurement structure, with hyperscale cloud operators consolidating around single-source design-build contracts while enterprises and government retain fragmented general contractor arrangements.
- Cloud Service Providers:Hyperscale operators specify integrated MEP responsibility and compress commissioning schedules through consolidated procurement. Samsung C&T Corporation and DL E&C compete for these premium contracts with tier certification capabilities.
- Enterprises:Corporate IT facilities prioritize business continuity over density optimization, sustaining demand for traditional raised-floor air distribution. Financial services firms in Seoul drive renovation activity for legacy mechanical upgrades.
- Colocation Providers:Multi-tenant facilities balance standardization against customization flexibility, accelerating free-air cooling deployments to preempt compliance costs. Ministry of Environment regulations tighten refrigerant selection criteria for their mechanical systems.
- Government:National Strategic Smart Data Center initiative directs public investment toward energy-efficient builds in designated zones. MFDS equipment safety standards and KTL certifications shape facility design for these projects.
Cloud service providers dominate new capital commitment. Government is where co-funding pathways accelerate beyond baseline requirements.
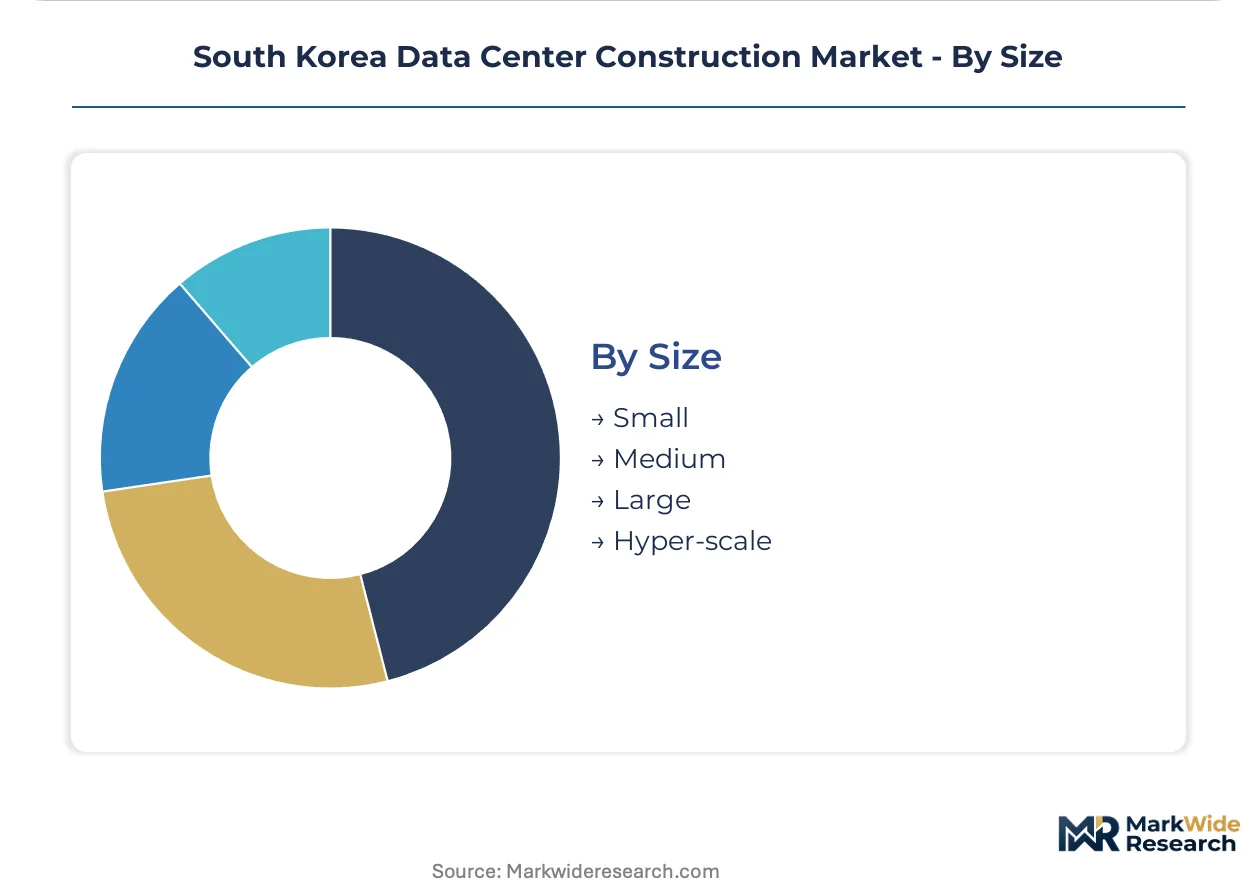
Size:
Volume concentration in large and hyper-scale facilities contrasts with geographic dispersion of small and medium deployments across secondary cities.
- Hyper-scale:Campus developments exceeding 50 megawatts concentrate in Pangyo technology cluster and Seoul metropolitan area with dedicated substations. Land scarcity in Gyeonggi Province drives cost inflation for these power-intensive sites.
- Large:Enterprise and colocation facilities in the 10-50 megawatt range anchor regional digital infrastructure. Hyundai Engineering and Construction leverages heavy civil expertise for these large-scale campus developments.
- Medium:Secondary city deployments in Busan and Gwangju utilize underutilized grid capacity for latency-sensitive edge facilities. Modular construction methods compress speed-to-market for this scale tier.
- Small:Enterprise branch and edge computing facilities distribute across provincial markets with standardized specifications. Critical facility engineering talent shortages extend design-review cycles for these smaller projects.
Hyper-scale dominates land and power allocation. Medium is where secondary city incentive zones pull geographic diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gyeonggi Province power grid interconnect underwrites South Korea's data center concentration, with Pangyo technology cluster and Seoul metropolitan area anchoring national capacity expansion through dedicated substation infrastructure.
Seoul Capital Area
Hyperscale cloud operators secure land and power allocations in Seoul metropolitan area to meet domestic digital service demand. MFDS equipment safety standards and KTL certifications for electrical infrastructure shape facility design and equipment selection timelines. Gangnam and Yeongdeungpo districts concentrate colocation facilities where free-air cooling deployments accelerate to preempt compliance-driven retrofit costs.
Gyeonggi Province
Pangyo technology cluster attracts campus developments exceeding 50 megawatts with dedicated substations and liquid cooling infrastructure. The National Strategic Smart Data Center initiative directs public investment toward energy-efficient builds in designated zones. Land scarcity around Pangyo drives cost inflation and extends site acquisition timelines for power-intensive hyperscale sites.
Busan-Ulsan
Underutilized power grid capacity in Busan pulls disaster recovery and latency-sensitive edge facility deployment. Modular construction methods compress speed-to-market for cloud providers facing competitive pressure to activate capacity. The city's port infrastructure supports submarine cable landing stations that anchor regional network redundancy.
Daejeon-Sejong
Government research institutions and public data center investment concentrate in this administrative capital region. KEPCO infrastructure upgrade timelines often lag behind facility power demand schedules, delaying energization. Sejong City's planned administrative functions create demand for tier-certified facilities serving public sector cloud migration.
Gwangju-Honam
Secondary city incentive zones in Gwangju utilize available grid capacity for edge computing and disaster recovery applications. The region's lower land costs attract modular deployment approaches for rapid facility activation. Network infrastructure investments prioritize redundancy for latency-sensitive workloads serving southwestern provincial markets.
South Korea Data Center Construction Market Competitive Landscape
Listed construction conglomerates compete with private specialists across integrated design-build contracts, with market structure consolidating around firms possessing concurrent maintainability design capabilities and tier certification credentials. Three strategic archetypes dominate: diversified chaebol-affiliated builders leveraging supply chain integration, specialized mechanical and electrical contractors focused on high-density power distribution, and heavy civil specialists adapted to large-scale campus developments. Competitive moves center on consolidating procurement accountability through single-source contracts and compressing commissioning schedules to match cloud provider speed-to-market requirements.
Within the chaebol-affiliated tier, Samsung C&T Corporation and Hyundai Engineering and Construction occupy positions defined by integrated construction and technology supply chains. DL E&C represents the specialized mechanical and electrical archetype, sitting within the contractor pool where high-density power distribution capabilities create scarcity premiums. These three firms exemplify how Korean market leaders anchor hyperscale contract capture through distinct capability configurations rather than undifferentiated scale competition.
| Leading Market Players |
|---|
| Samsung C&T Corporation |
| Hyundai Engineering and Construction |
| DL E&C |
| GS Engineering and Construction |
| SK ecoplant |
| POSCO E&C |
| HanmiGlobal |
| Lotte E&C |
| Fir Hills Company |
| Others |
Pricing and Supply Chain Analysis
Design-build contracts with integrated MEP responsibility anchor procurement structures in South Korea's data center construction market, locking in supply access to specialized Korean contractors and compressing price visibility for cloud service providers facing speed-to-market pressures. This contract pattern concentrates pricing power with tier-certified builders while exposing buyers to scarcity premiums during construction surges.
Pricing Analysis
Three-tier pricing structure across premium hyperscale, standard enterprise, and economy modular levels stratifies the market. Premium tier commands margins through concurrent maintainability design and tier certification credentials held by Samsung C&T Corporation and DL E&C. Price differentiation centers on certification level and volume scale, with hyperscale campus developments securing favorable terms through multi-year commitments. Cost compression in the standard tier intensifies as general contractors compete for fragmented enterprise builds. Colocation providers exhibit highest price sensitivity due to multi-tenant cost recovery constraints, while cloud service providers prioritize schedule certainty over unit cost minimization.
Supply Chain Analysis
Extended lead times for high-density busway and switchgear from South Korean and Japanese electrical component manufacturers compress project scheduling flexibility. Supply draws from domestic steel fabrication, Taiwanese precision cooling equipment, and German automation systems for mechanical plant integration. Single-source vulnerability concentrates in specialized MEP contractor capabilities for power distribution exceeding 15 kilowatts per rack. Distribution runs through direct procurement channels from cloud service providers to integrated design-build firms, displacing traditional general contractor-subcontractor hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's data center construction market sits in a cyclical upswing driven by hyperscale cloud provider expansion under Green New Deal compliance deadlines, creating temporary scarcity premiums for tier-certified contractors.
For Market Incumbents: Secure long-term capacity reservations with KEPCO for grid interconnection allocations before queue congestion worsens. Deepen backward integration into liquid cooling component manufacturing to capture margin pools currently flowing to Taiwanese suppliers. MFDS certification acceleration timelines present a defensive moat against emerging specialized contractors.
For New Entrants and Emerging Players: KTL certification fast-track programs offer entry pathways into secondary city modular deployments where incumbent concentration remains lowest. Target Busan and Gwangju incentive zones for disaster recovery facilities requiring rapid activation. Partner with regional electrical subcontractors to bridge capability gaps in high-density power distribution.
For Investors and Strategic Acquirers: The market sits at an expansion phase that favors specialized MEP contractors with tier certification credentials over diversified construction conglomerates. Long-term viability hinges on exposure to liquid cooling technology transitions and renewable energy procurement capabilities. Monitor KEPCO infrastructure upgrade announcements as the primary inflection indicator for construction surge timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Direct-to-chip systems enable PUE below 1.2 for Pangyo hyperscale campuses under Green New Deal mandates. |
| Design-Build Contract Consolidation | Single-source accountability reduces interface risk between civil and mechanical workstreams for cloud providers. |
| Secondary City Modular Expansion | Busan and Gwangju incentive zones pull geographic diversification away from land-scarce Gyeonggi Province. |
| Renewable Energy Procurement Integration | On-site solar and green power purchase agreements secure construction permits under tightening carbon intensity benchmarks. |
| Specialized MEP Contractor Acquisition | Scarcity premiums for high-density power distribution capabilities create consolidation opportunities in the Korean contractor pool. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center developers, EPC contractors, KEPCO grid planning officers, and MFDS regulatory leads; and secondary validation through KEPCO infrastructure disclosure filings, Ministry of Environment emissions permits, National Strategic Smart Data Center initiative documents, and hyperscaler capital expenditure announcements. Bottom-up project pipeline aggregation triangulated against top-down construction spending estimates.
Across the analysis window, the forecasting framework modeled construction value flows by facility scale tier, cooling technology type, and procurement structure. Segmentation dimensions included construction type, technology layer, end-user category, and geographic cluster. CAGRs derived from project-level capacity activation schedules and contractor backlog analysis, with sensitivity testing around KEPCO interconnection timelines and land availability constraints in Gyeonggi Province.
Decision-makers should treat outputs as directional under assumptions of sustained cloud provider expansion and stable Green New Deal enforcement; material deviation in renewable energy procurement mandates or grid infrastructure investment would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Global Dry Construction Market
Building Construction
Egypt Construction Market
Building Construction
Ireland Data Center Construction Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Middle East Building Construction Market
Building Construction
Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Prefabricated Buildings Market
Building Construction
US Prefabricated Buildings Market
Building Construction
Australia Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
France Prefab Homes Market
Building Construction
India Construction Market