
 Transportation Infrastructure Construction Market | 2026-2036
Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Infrastructure Construction Market Insights
Multi-source procurement is rebalancing toward consolidated design-build partnerships across major transportation programs. China Communications Construction Company leverages its integrated port-highway-rail capabilities across Belt and Road corridors. Vinci SA anchors European concession-backed infrastructure through long-term operating contracts. Bechtel Corporation sustains competitive position in large-scale tunnel and bridge megaprojects through in-house engineering depth.
Transportation infrastructure construction encompasses the engineering, assembly, and commissioning of civil works enabling the movement of passengers and freight, typically involving concrete compressive strengths of 30-60 MPa for bridge decks and continuous welded rail for high-speed track beds. Roads and railways occupy the largest share of project value, while tunnels command premium margins due to geotechnical complexity and specialized equipment requirements. Modular and prefabricated methods are gaining share as contractors seek to compress construction schedules and reduce lane-closure impacts on active corridors.
The US Federal Highway Administration, the EU F-Gas Regulation on embodied carbon in materials, and India's Ministry of Road Transport and Highways each impose distinct compliance layers on cross-border contractors. FHWA mandates Buy America provisions for steel and iron, while EU CSRD disclosures now require scope-3 emissions reporting on cement and asphalt sourcing. Stakeholders must monitor how carbon-border adjustments and local-content rules reshape supplier qualification and bidding strategies.
Market Dynamics
Federal procurement rules and embodied-carbon mandates are compressing contractor margins while forcing rapid recalibration of material sourcing and qualification protocols across project portfolios.
Growth Catalysts
- US Bipartisan Infrastructure Law:Direct federal funding toward bridge rehabilitation and corridor modernization creates sustained project pipelines for design-build consortia.
- Dedicated freight corridors:India's National Infrastructure Pipeline prioritizes rail freight separation from passenger networks, opening multi-year construction awards.
- Continuous welded rail:High-speed track specifications across Asian and Middle Eastern networks drive specialized civil works demand.
Market Restraints
- Steel and iron input costs:FHWA Buy America provisions restrict qualified supplier pools, amplifying price volatility exposure on federally funded projects.
- Specialized tunneling equipment:Concentrated manufacturing in Germany and Japan creates procurement bottlenecks for complex underground segments.
- EU F-Gas Regulation:Embodied carbon thresholds on cement and asphalt disqualify traditional supply sources, forcing costly material substitution.
Strategic Opportunities
- Modular prefabrication:Offsite bridge deck and tunnel segment production compresses lane-closure windows on active urban corridors.
- EU CSRD disclosures:Mandatory scope-3 emissions reporting creates first-mover advantage for contractors with verified low-carbon supply chains.
- Urban metro expansion:Indian metropolitan authorities are tendering underground and elevated rail packages with 25-year maintenance attachments.
Industry Challenges
- Geotechnical engineering talent:Scarcity of tunnel and foundation specialists delays project mobilization and inflates specialist subcontractor rates.
- Cross-border certification:Divergent national standards for concrete compressive testing and rail welding protocols fragment quality assurance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Infrastructure Construction Market |
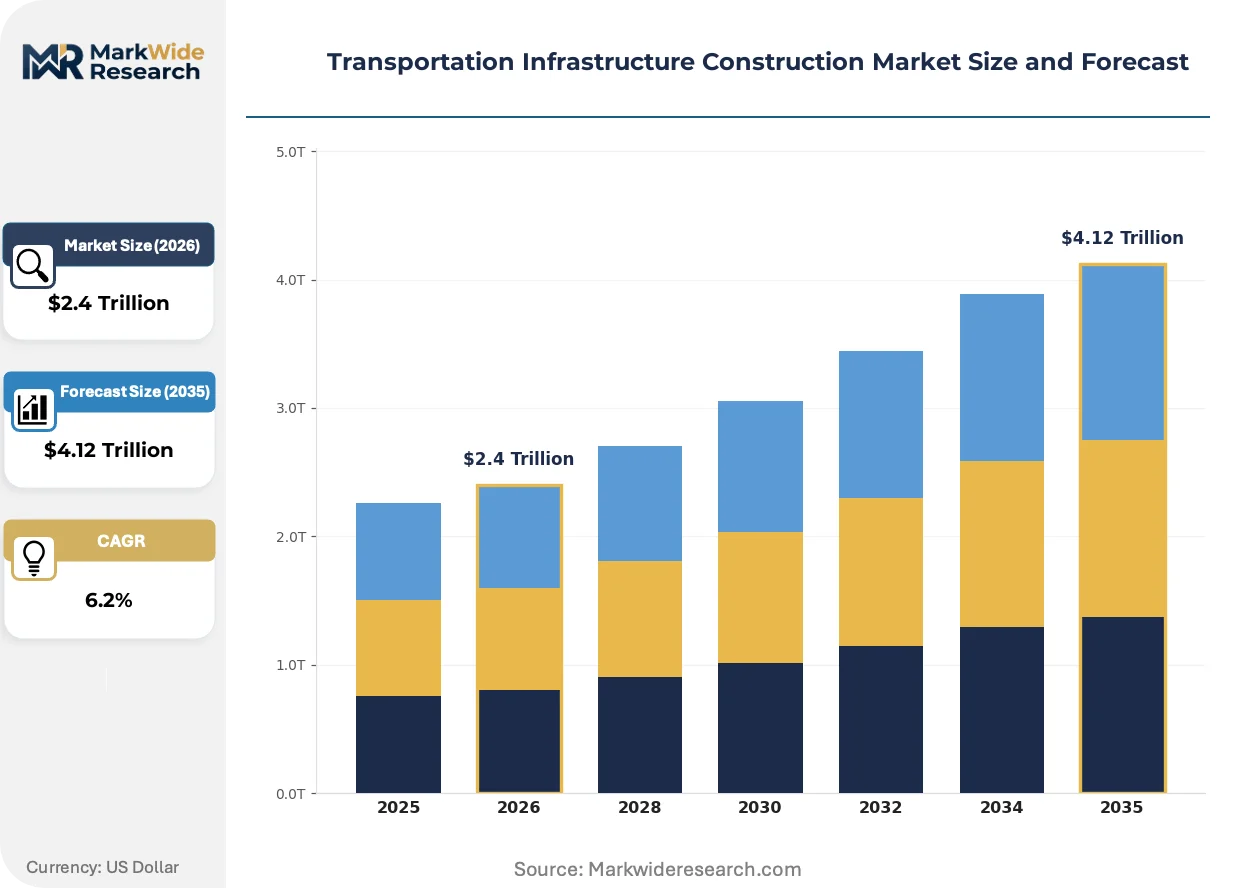
| Market Size in 2026 | $2.4 Trillion |
| Market Size in 2035 | $4.12 Trillion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Bridges, Roads, Tunnels, Railways Construction Method: Traditional, Modular, Prefabricated, In-situ Material Used: Concrete, Steel, Asphalt, Composite End User: Government, Private Sector, Contractors, Consultants |
| Companies Covered | China Communications Construction Company, Vinci SA, Bechtel Corporation, Fluor Corporation, AECOM, Kiewit Corporation, Hochtief AG, CRH plc, Larsen & Toubro Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Infrastructure Construction Market Trends and Innovations
Digital fabrication and low-carbon material specifications are converging to compress construction schedules while elevating compliance complexity for contractors operating across multiple regulatory jurisdictions.
Building Information Modeling is integrating geotechnical survey data, structural load simulations, and construction sequencing into unified project control platforms. European and Asian rail authorities now mandate BIM deliverables as contract conditions. This convergence is integrating design and construction phases that previously operated on sequential handoffs, collapsing traditional schedule buffers.
The EU CSRD and F-Gas Regulation jointly impose scope-3 emissions disclosure on cement, steel, and asphalt sourcing. Contractors must now document embodied carbon across tier-2 and tier-3 suppliers to qualify for public tenders. German and French infrastructure agencies have tightened material qualification timelines, forcing early-stage supplier engagement.
Design-build contracting is displacing traditional design-bid-award sequences on large corridor projects. State transportation departments in the US and provincial authorities in Canada now bundle engineering and construction risk with single-source accountability. This model concentrates procurement decision-making with fewer, larger consortia and compresses overall project delivery timelines.
Transportation Infrastructure Construction Market Segmentation
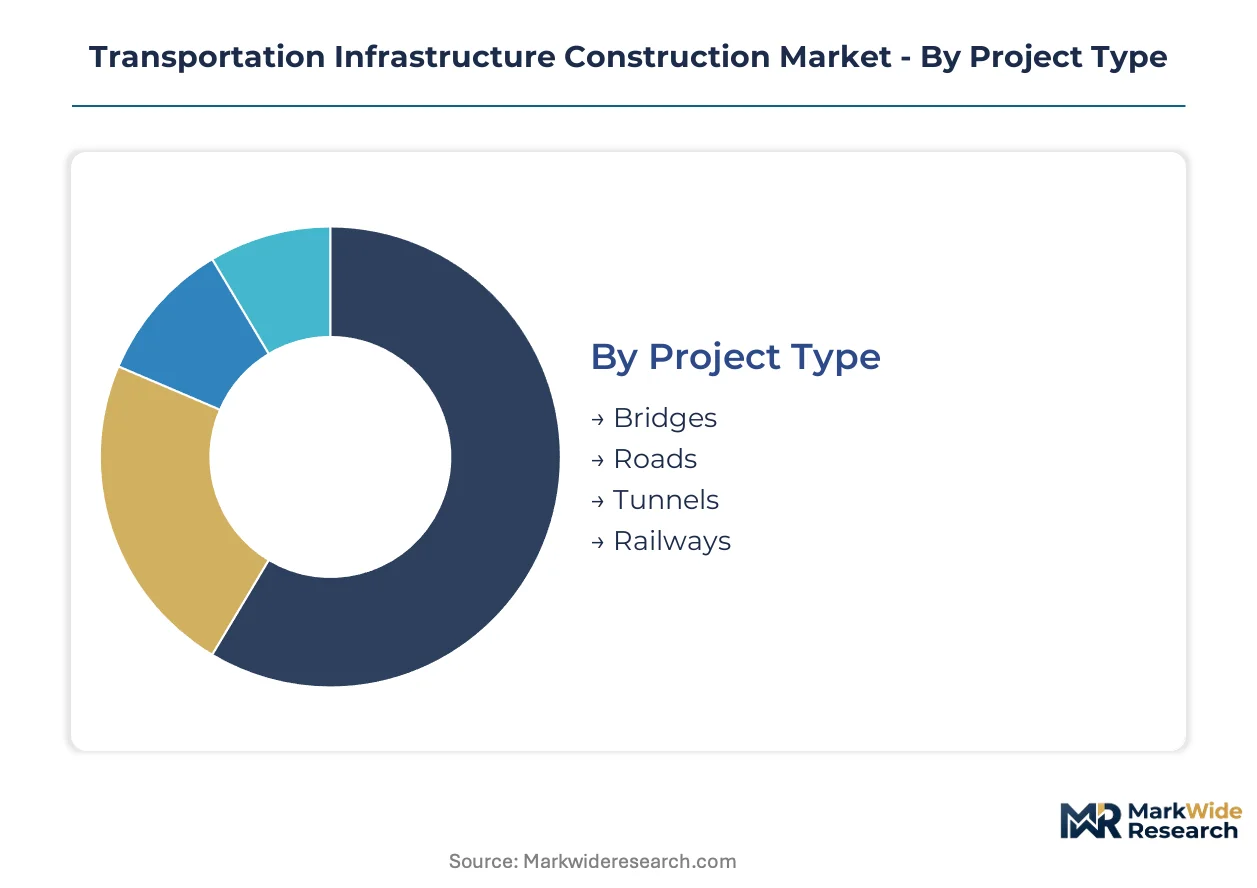
Transportation infrastructure construction segments reflect distinct regulatory burdens, material qualification protocols, and project delivery risk profiles. Contractors configure bidding strategies around segment-specific compliance layers rather than treating the market as uniform.
Project Type:
FHWA Buy America provisions apply differentially across bridge and rail projects, while tunnel works trigger specialized OSHA confined-space protocols and EPA stormwater discharge permits.
- Bridges:Deck construction employs concrete compressive strengths of 30-60 MPa with continuous welded rail attachments for transit integration. Federal bridge rehabilitation funding under the US Bipartisan Infrastructure Law concentrates awards in structurally deficient corridor segments across the Midwest and Northeast.
- Roads:Highway and arterial corridor works dominate procurement volume, involving asphalt paving and concrete pavement rehabilitation. India's Ministry of Road Transport and Highways tenders national highway widening through hybrid annuity models that transfer maintenance risk to contractors for 15-year periods.
- Tunnels:Underground segments command premium margins due to geotechnical complexity and specialized TBM equipment requirements.
- Railways:Dedicated freight corridors and high-speed track beds require continuous welded rail specifications.
Leading the category by volume: Roads. Growing fastest: Railways.
Construction Method:
Method selection determines lane-closure windows, labor intensity, and equipment capital requirements on active transportation corridors.
- Traditional:Cast-in-place concrete and sequential steel erection on project sites. India's urban metro authorities still specify traditional methods for complex foundation works where geotechnical uncertainty precludes prefabrication.
- Modular:Offsite production of bridge decks and tunnel segments compresses construction schedules. European rail agencies now mandate modular methods for elevated viaducts to minimize traffic disruption on dense corridor networks.
- Prefabricated:Factory-controlled quality reduces on-site welding and curing time.
- In-situ:Site-formed concrete for foundations and retaining walls where transport access limits prefabricated component delivery.
Dominating procurement awards: Traditional. Expanding most quickly: Modular.
Material Used:
EU F-Gas Regulation and CSRD scope-3 disclosure requirements are reshaping material qualification timelines and supplier verification protocols.
- Concrete:Standard construction material for bridge decks, foundations, and tunnel linings. German and French infrastructure agencies have tightened embodied carbon thresholds on cement sourcing, forcing early-stage engagement with low-carbon concrete suppliers.
- Steel:Structural framing and reinforcement with strict FHWA Buy America origin requirements. US federally funded projects face restricted qualified supplier pools, amplifying price volatility exposure on bridge and rail megaprojects.
- Asphalt:Pavement surfacing for roads and highways.
- Composite:Fiber-reinforced polymers for bridge deck overlays and corrosion-resistant applications.
Highest procurement volume: Concrete. Steepest compliance cost escalation: Steel.
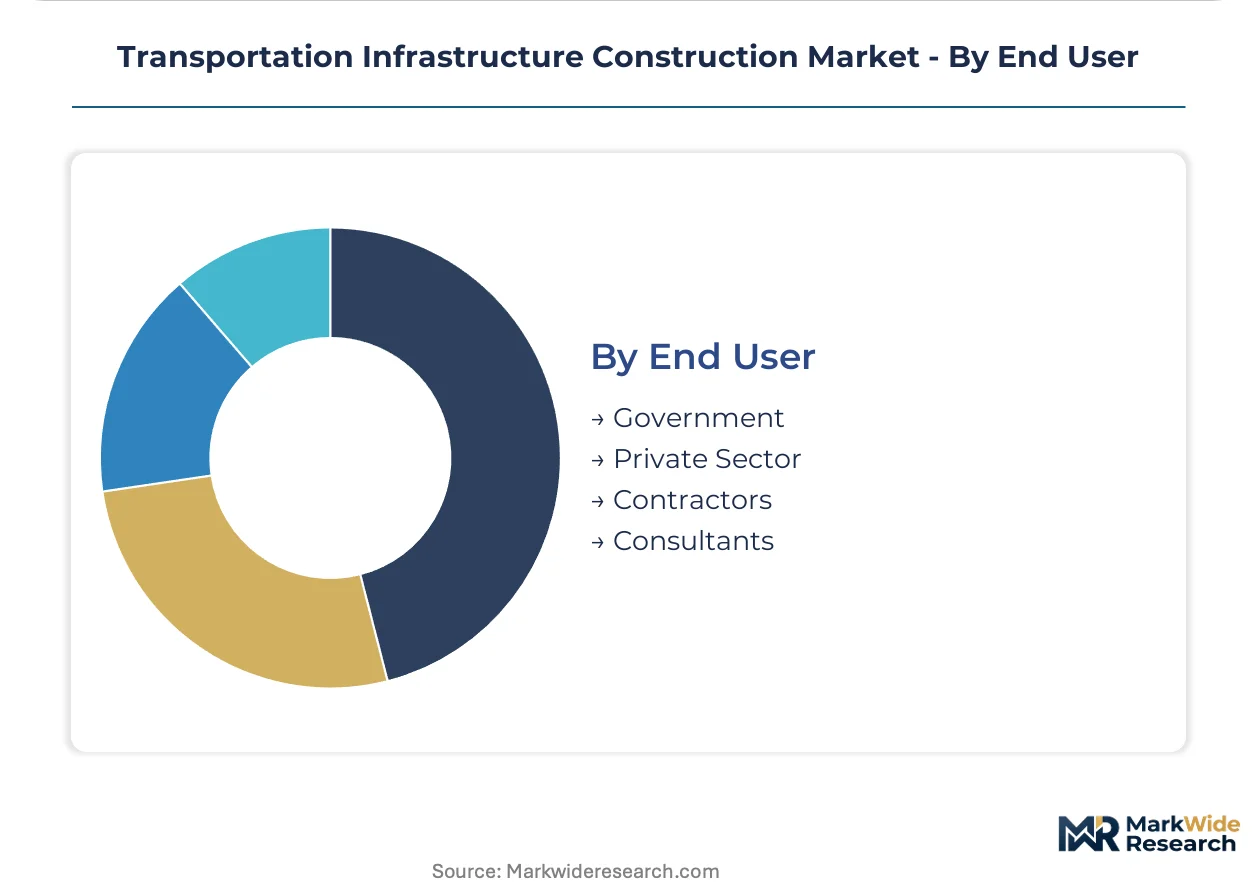
End User:
Contractor-customer relationships vary by procurement rules, payment security, and long-term maintenance attachment structures.
- Government:Federal, state, and municipal transportation departments with design-build and public-private partnership models. The US Federal Highway Administration channels infrastructure law funding through state DOTs with bundled engineering-construction risk.
- Private Sector:Industrial facility owners and logistics operators building captive rail spurs and access roads. Indian dedicated freight corridor projects attract private investment through availability-based payment structures.
- Contractors:Tier-1 construction firms self-performing or subcontracting specialized segments.
- Consultants:Engineering advisory firms providing geotechnical, structural, and environmental design services.
Controlling capital deployment: Government. Gaining procurement flexibility: Private Sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and cement production corridors in China, Germany, and India anchor regional supply chains for transportation megaprojects. Federal procurement programs and carbon-border mechanisms now reshape contractor qualification requirements across these manufacturing hubs.
United States
The Federal Highway Administration channels Bipartisan Infrastructure Law funding through state DOTs for bridge rehabilitation and corridor modernization. FHWA Buy America provisions restrict steel and iron sourcing to domestic mills, compressing qualified supplier pools. Midwest and Northeast corridor segments concentrate structurally deficient bridge awards where design-build consortia mobilize.
China
Belt and Road port-highway-rail integration drives cross-border construction awards across Central and Southeast Asian corridors. MIIT and MEE impose dual carbon goals on cement and steel sourcing for state-funded infrastructure. Yangtze River Delta manufacturing clusters supply continuous welded rail and prefabricated bridge segments for high-speed network expansion.
India
The National Infrastructure Pipeline prioritizes dedicated freight corridors and urban metro expansion across Delhi-Mumbai and Chennai-Bengaluru industrial belts. Ministry of Road Transport and Highways tenders national highway widening through hybrid annuity models transferring 15-year maintenance risk. Mumbai, Delhi-NCR, and Bangalore metropolitan authorities tender underground rail packages with long-term maintenance attachments.
Germany
EU F-Gas Regulation and CSRD scope-3 disclosure requirements force early-stage engagement with low-carbon concrete and steel suppliers. KBA and federal transport authorities mandate BIM deliverables as contract conditions for rail corridor projects. Rhine-Ruhr and Bavarian industrial clusters host specialized tunneling equipment manufacturing and geotechnical engineering services.
Saudi Arabia
NEOM and Red Sea coastal corridor developments attract international design-build consortia for integrated rail and highway networks. The country's national infrastructure regulator imposes local-content requirements on steel and cement sourcing for giga-project awards. Riyadh and Eastern Province construction hubs concentrate tunneling and bridge specialists for desert geotechnical conditions.
Transportation Infrastructure Construction Market Competitive Landscape
Strategic partnerships dominate the current landscape as contractors consolidate design-build capabilities to meet bundled procurement requirements. The vendor base organizes around three tiers: integrated infrastructure conglomerates with port-rail-highway capabilities, European concession specialists with long-term operating contracts, and North American engineering-heavy firms focused on tunnel and bridge megaprojects. M&A activity and capacity expansion in modular prefabrication represent the two principal competitive vectors reshaping market position.
Among integrated infrastructure conglomerates, China Communications Construction Company and Vinci SA exemplify archetypes spanning Belt and Road corridors and European concession-backed networks respectively. Bechtel Corporation occupies a position within the North American engineering-intensive tier, anchoring competitive positioning in large-scale tunnel and bridge projects through in-house technical depth. These three entities represent distinct strategic postures: state-linked vertical integration, concession-financed long-term asset operation, and privately held engineering excellence on complex geotechnical segments.
| Leading Market Players |
|---|
| China Communications Construction Company |
| Vinci SA |
| Bechtel Corporation |
| Fluor Corporation |
| AECOM |
| Kiewit Corporation |
| Hochtief AG |
| CRH plc |
| Larsen & Toubro Limited |
| Others |
Pricing and Supply Chain Analysis
Captive steel and cement production across Yangtze River Delta manufacturing clusters anchors both supply security and pricing leverage for contractors bidding on Belt and Road corridor awards. FHWA Buy America provisions and EU carbon-border mechanisms reshape how procurement teams qualify suppliers and negotiate long-term offtake terms.
Pricing Analysis
Maintenance-bundling in design-build contracts separates premium-tier consortia from unbundled competitors on Indian hybrid annuity highways. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, BIM capability, and local-content compliance. Cost compression in standard-tier road rehabilitation intensifies because FHWA domestic-content rules restrict qualified steel mills. State transportation departments show highest price sensitivity on routine highway widening, while NEOM giga-projects tolerate premium engineering fees for geotechnical complexity.
Supply Chain Analysis
Domestic-content mandates from India's Ministry of Road Transport and Highways and Saudi Arabia's national infrastructure regulator force early-stage supplier localization on megaproject awards. Steel production concentrates in China, Germany, and India; continuous welded rail manufacturing centers on Japanese and German specialized mills. TBM equipment draws from concentrated German and Japanese fabrication facilities, creating single-source vulnerability for tunnel segments. Distribution runs through state transportation department procurement portals and concession authority tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular prefabrication is displacing cast-in-place methods across European and Asian rail corridors, compressing project timelines while elevating capital requirements for offsite production facilities.
For Market Incumbents: Hedge against margin compression from EU F-Gas embodied-carbon thresholds by securing low-carbon concrete supply agreements before qualification deadlines. Acquire specialized tunneling equipment operators to reduce subcontractor dependence on geotechnically complex segments. BIM capability investment protects against disqualification from rail authority tender requirements.
For New Entrants and Emerging Players: Regional engineering consultancies with geotechnical specialization offer partnership pathways into Indian urban metro underground packages. Target Indian metropolitan authorities tendering 25-year maintenance-attachment rail contracts where incumbent capacity is constrained. Lead with modular fabrication joint ventures to bypass traditional equipment capital barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in concession-backed infrastructure funds seeking operational assets with long-term revenue visibility. Five-to-ten-year viability favors contractors with verified scope-3 emissions documentation and captive low-carbon material supply. Watch EU carbon-border adjustment implementation timing as inflection indicator for supplier qualification cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Capacity Buildout | Compresses lane-closure windows on FHWA-funded urban corridor rehabilitation. |
| Low-Carbon Concrete Supply Agreement | Secures EU CSRD qualification ahead of tightened French and German agency thresholds. |
| Geotechnical Engineering Firm Acquisition | Addresses talent scarcity inflating specialist subcontractor rates on tunnel segments. |
| BIM Platform Integration Partnership | Meets mandated deliverable conditions for European and Asian rail authority tenders. |
| Design-Build Consortium Formation | Bundles engineering-construction risk for state DOT procurement preference. |
Research Methodology
Independent corroboration across project procurement databases, regulatory filing repositories, and materials qualification registries underwrites the qualitative findings. Primary interviews with state DOT procurement officers, tunnel engineering specialists, concession authority contract managers, and prefabrication facility operators combined with secondary validation from FHWA funding announcements, EU CSRD disclosure filings, and Indian Ministry tender records. Bottom-up project pipeline aggregation and top-down infrastructure budget allocation analysis triangulate market sizing.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price effects in segment-level modeling. Segmentation dimensions include project type, construction method, material compliance tier, and end-user procurement model. CAGRs derive from weighted project award flows and maintenance-attachment revenue recognition patterns. Continuous welded rail specifications and TBM deployment rates feed corridor-specific capacity expansion assumptions.
Caveats apply where carbon-border adjustment implementation schedules or Buy America waiver decisions could materially shift the outlook. Forecasts reflect assumptions on federal funding continuity, embodied-carbon threshold stringency, and geotechnical labor market tightness. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
North America Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Asia-Pacific Transportation Infrastructure Construction Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Brazil Data Center Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Japan Transportation Infrastructure Construction Market
Infrastructure Construction
Brazil Infrastructure Sector Market
Infrastructure Construction
Bahrain Construction Market
Infrastructure Construction
Infrastructure Sector in Asia Pacific Market
Infrastructure Construction
South America Data Center Construction Market
Infrastructure Construction
Docks Market
Infrastructure Construction
Global Port Infrastructure Market