
 India Transportation Infrastructure Market | 2026-2036
India Transportation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
India Transportation Infrastructure Market Insights
Geopolymer concrete is recalibrating pavement economics across India's highway expansion programs by reducing clinker dependency and lowering thermal curing costs. Larsen & Toubro Limited leverages its integrated cement-to-construction workflow to dominate large-scale expressway tenders in western India. Tata Projects sustains competitive positioning through specialized bridge-deck engineering capabilities that anchor its presence in Himalayan rail corridors.
India transportation infrastructure encompasses the physical systems enabling passenger and freight movement across road, rail, air, and maritime networks, requiring load-bearing designs exceeding IRC axle-load specifications and seismic Zone-V compliance for structural resilience. Concrete and steel materials command the dominant procurement volumes, with composite segments gaining traction in airport runway resurfacing where fatigue resistance under tropical thermal cycling creates premium margin pools. Government grants and public-private partnerships structure the primary funding architecture, though private investment channels are deepening in operational asset classes such as toll roads and container terminals.
BIS certification mandates for construction materials, CEA electrical clearance protocols for rail electrification, and the Ministry of Environment Forest and Climate Change environmental impact assessment framework collectively shape project timelines and technology selection across states. The National Highway Authority of India asset monetization pipeline and PM Gati Shakti master plan are restructuring how contractors qualify for bundled multimodal contracts. Stakeholders must monitor whether proposed infrastructure investment trust reforms unlock sufficient institutional capital to absorb the project pipeline beyond current fiscal capacity.
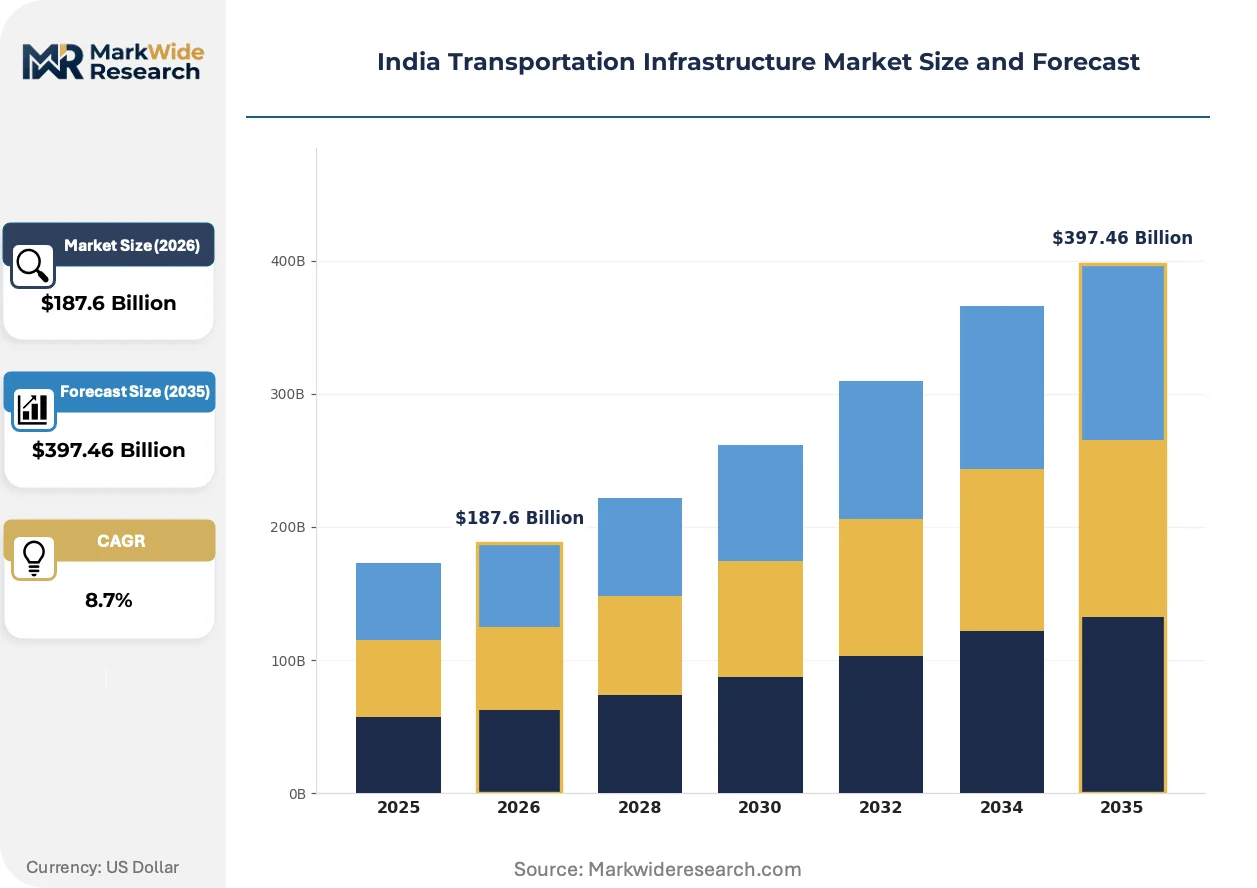
Market Dynamics
Geopolymer concrete formulations are compressing clinker procurement cycles across India's highway expansion programs, forcing contractors to requalify supply chains around BIS-certified blended mixes rather than traditional Portland cement.
Growth Catalysts
- Bharatmala Pariyojana Phase-II:The Ministry of Road Transport and Highways corridor bundling is aggregating demand for multi-lane expressways across Maharashtra and Karnataka, consolidating contractor qualification pools.
- Metro rail electrification:CEA clearance protocols for 25kV AC traction systems are standardizing rail infrastructure specifications across Tier-2 urban networks including Kochi and Lucknow.
- Port modernization incentives:Sagarmala-linked viability gap funding is redirecting private capital toward container terminal automation and deep-draft berth construction at Chennai and Visakhapatnam.
Market Restraints
- Clinker supply concentration:Domestic limestone reserves face quality degradation in Rajasthan and Madhya Pradesh, forcing reliance on imported clinker subject to DGFT duty volatility.
- Steel rebar price instability:Input cost swings for thermo-mechanically treated bars compress EPC contractor margins on fixed-price National Highway Authority of India tenders.
- Seismic Zone-V compliance:Himalayan rail corridors require specialized bridge piling techniques that extend project timelines beyond standard DPR estimates.
Strategic Opportunities
- Logistics parks under PM Gati Shakti:Multi-modal cargo hubs near Nagpur and Varanasi offer greenfield development scope for integrated warehousing and last-mile connectivity.
- Green hydrogen blending:Pilot mandates for H2-fuelled heavy trucking on Delhi-Mumbai Expressway corridors are creating demand for refueling infrastructure.
- Asset monetization pipeline:Infrastructure investment trust structures for operational toll roads unlock institutional capital absorption beyond current fiscal deficits.
Industry Challenges
- Bridge-deck welding certification:Qualified structural steel fabricators for railway viaducts remain concentrated in western India, creating deployment bottlenecks for eastern corridor projects.
- Environmental clearance timelines:Ministry of Environment Forest and Climate Change forest diversion approvals for linear projects average 18-24 months, compressing construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Transportation Infrastructure Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $397.46 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Highways, Railways, Airports, Ports Material: Concrete, Steel, Asphalt, Composite Funding Source: Government Grants, Private Investment, PPP, International Loans End User: Transport Operators, Logistics Providers, Government Agencies, Commuters |
| Companies Covered | Larsen & Toubro Limited, Tata Projects, Megha Engineering & Infrastructures Limited, IRB Infrastructure Developers Ltd, Shapoorji Pallonji, Dilip Buildcon Limited, Adani Ports and Special Economic Zone, KEC International Limited, Reliance Infrastructure Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Transportation Infrastructure Market Trends and Innovations
Digital twin modeling is compressing design-validation cycles across India's transportation infrastructure pipeline, enabling real-time stress simulation before physical ground-breaking.
Self-healing concrete embedded with bacterial spores is unifying durability and maintenance economics for coastal highway segments. State public works departments in Gujarat and Tamil Nadu are piloting formulations on marine-exposed viaducts. The technology is unifying 50-year lifecycle cost projections with upfront capital allocation frameworks previously treated as separate budget lines.
CEA technical standards for 50kV AC railway electrification are mandating upgraded insulation coordination across Himalayan corridors. Equipment suppliers must requalify switchgear for altitude-derated performance. Northeastern rail projects including the Jiribam-Imphal line face extended commissioning schedules as foreign OEMs adapt designs to Indian altitude and monsoon specifications.
Consortium-based bidding is displacing solo EPC contracts on bundled multimodal projects. Contractors now form specialized joint ventures combining road, rail, and port expertise to qualify for PM Gati Shakti-integrated tenders. This pattern concentrates most visibly in Maharashtra where Mumbai-Nagpur Expressway logistics nodes require simultaneous highway, freight rail, and dry port coordination.
India Transportation Infrastructure Market Segmentation
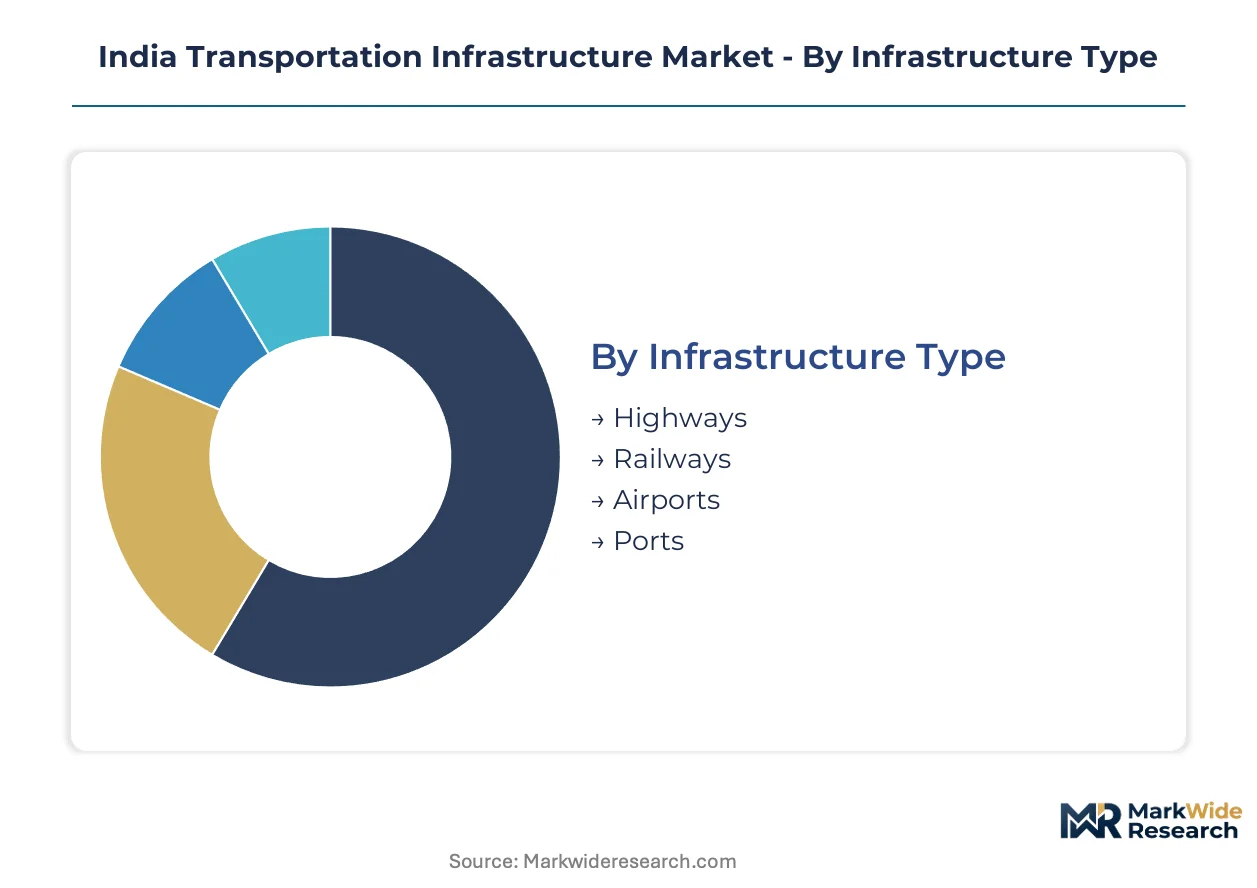
Segmentation across India's transportation infrastructure reveals how regulatory certification pathways, material procurement cycles, and funding architectures create divergent margin profiles for contractors and suppliers. Each dimension carries distinct BIS, CEA, and MoEFCC compliance burdens that reshape project qualification timelines.
Infrastructure Type:
BIS certification for IRC axle-load specifications applies universally, yet CEA electrical clearance protocols and MoEFCC environmental impact assessments vary sharply across these four segments.
- Highways:Multi-lane expressways and access-controlled corridors require IRC:SP:73 load-bearing designs with geopolymer concrete gaining traction for pavement durability. Demand concentrates in Maharashtra and Karnataka where Bharatmala Pariyojana Phase-II corridor bundling aggregates contractor pools.
- Railways:25kV AC traction systems and 50kV AC Himalayan corridors mandate CEA insulation coordination standards. Bridge-deck welding certification bottlenecks concentrate qualified fabricators in western India, extending timelines for eastern corridor deployment.
- Airports:Runway resurfacing specifications prioritize fatigue resistance under tropical thermal cycling, creating premium margin pools for composite material applications.
- Ports:Deep-draft berth construction and container terminal automation attract Sagarmala-linked viability gap funding at Chennai and Visakhapatnam.
Volume leader: Highways. Steepest expansion trajectory: Railways.
Material:
Cost tier differentiation separates clinker-dependent formulations from advanced composites, with procurement cycles compressing fastest for certified blended mixes.
- Concrete:Portland cement faces displacement by BIS-certified geopolymer blends that reduce thermal curing costs. Rajasthan and Madhya Pradesh limestone quality degradation is forcing imported clinker reliance subject to DGFT duty volatility.
- Steel:Thermo-mechanically treated rebar price instability compresses EPC margins on fixed-price NHAI tenders. Self-healing concrete with bacterial spores is unifying lifecycle cost projections for coastal Gujarat and Tamil Nadu viaducts.
- Asphalt:Conventional bituminous paving dominates secondary road networks with lower certification overhead than structural concrete specifications.
- Composite:Carbon-fiber and glass-reinforced polymers command airport runway segments where fatigue resistance under thermal cycling justifies premium positioning.
Procurement volume concentrates in concrete. Margin expansion favors composites.
Funding Source:
Application-based segmentation distinguishes operational asset classes with revenue certainty from greenfield development requiring construction risk absorption.
- Government Grants:Central budgetary allocation through Ministry of Road Transport and Highways dominates Bharatmala and Sagarmala program execution with sovereign credit backing.
- Private Investment:Toll road operations and container terminals attract institutional capital through operational yield profiles rather than construction-phase exposure.
- PPP:Bundled multimodal contracts under PM Gati Shakti mandate consortium-based bidding combining road, rail, and port expertise, visible in Maharashtra's Mumbai-Nagpur Expressway logistics nodes.
- International Loans:Multilateral development bank financing attaches environmental and social safeguard conditions that extend MoEFCC clearance timelines.
Dominant channel: Government grants. Deeening fastest: Private investment through infrastructure investment trust structures.
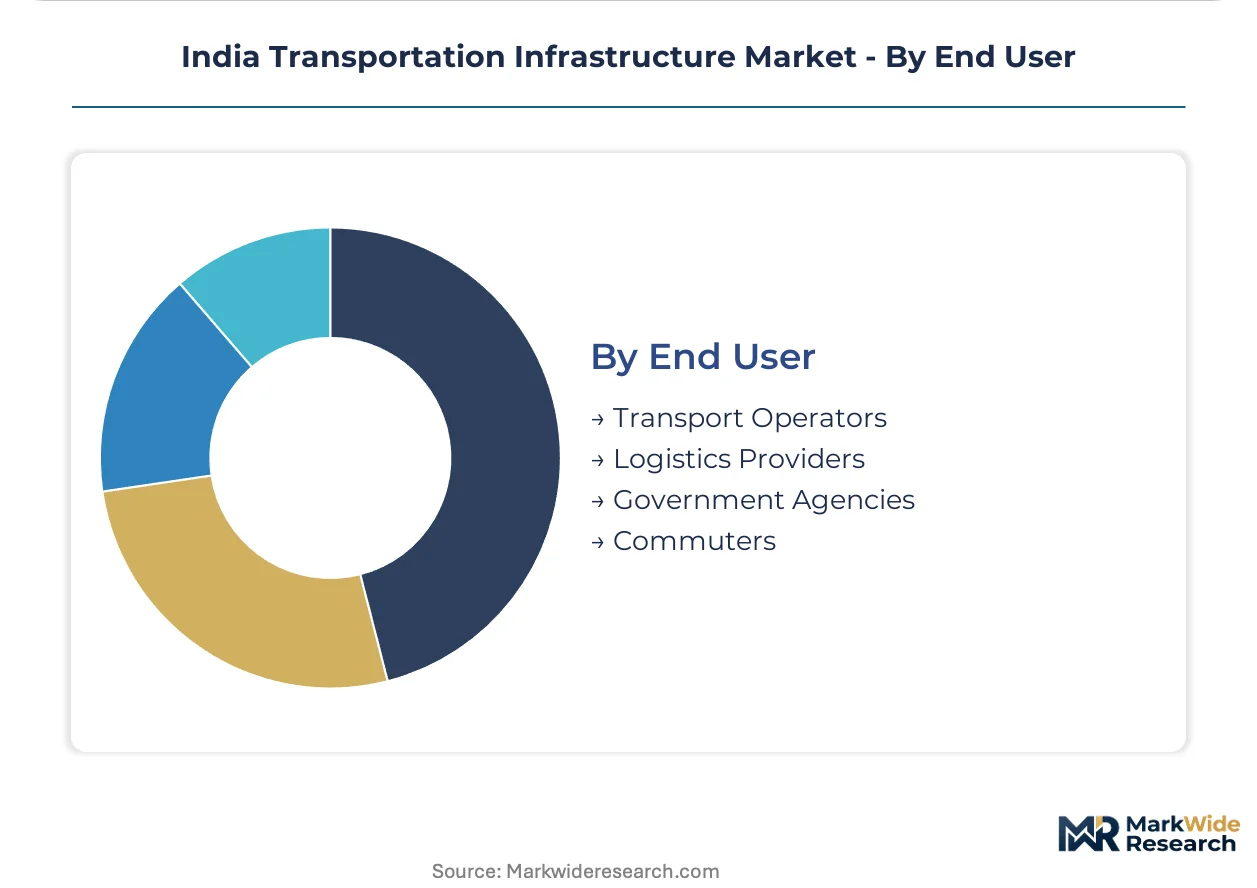
End User:
Customer type segmentation aligns procurement specifications with operational performance requirements across freight and passenger movement.
- Transport Operators:State road transport corporations and railway zones prioritize asset durability specifications that minimize maintenance frequency.
- Logistics Providers:Third-party logistics and e-commerce fulfillment networks drive demand for multimodal cargo hubs near Nagpur and Varanasi under PM Gati Shakti.
- Government Agencies:NHAI, state public works departments, and port authorities structure tender specifications around BIS certification mandates and CEA electrical protocols.
- Commuters:Urban metro rail networks across Tier-2 cities including Kochi and Lucknow accelerate adoption among passenger movement providers.
Primary demand anchor: Government agencies. Fastest specification evolution: Logistics providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration clusters around western and southern industrial corridors where Bharatmala Pariyojana Phase-II corridor bundling aggregates expressway construction. State-level procurement specifications diverge sharply based on limestone reserve quality and port modernization priorities.
Maharashtra
Mumbai-Nagpur Expressway logistics nodes drive multimodal cargo hub development. BIS certification mandates for IRC:SP:73 load-bearing designs govern all pavement specifications. The Pune-Nashik industrial belt concentrates geopolymer concrete pilot projects for highway durability testing.
Karnataka
Bengaluru-Chennai industrial corridor expansion accelerates demand for access-controlled expressways. CEA electrical clearance protocols for 25kV AC traction systems standardize metro rail specifications in Bengaluru's peripheral networks. The Tumakuru-Chitradurga mining belt anchors steel rebar procurement for bridge-deck construction.
Tamil Nadu
Chennai port modernization under Sagarmala viability gap funding attracts deep-draft berth automation investment. MoEFCC environmental impact assessments for coastal highway segments average 18-24 months. The Ennore-Kattupalli port cluster commands composite material applications for marine-exposed viaducts.
Gujarat
Self-healing concrete with bacterial spores undergoes state public works department piloting on marine-exposed coastal segments. DGFT duty volatility on imported clinker forces reliance on domestic limestone blending. The Hazira-Vadodara industrial corridor dominates thermo-mechanically treated rebar consumption for fixed-price NHAI tenders.
West Bengal
Haldia dock complex modernization and Kolkata metro rail extensions compete for CEA electrical protocol compliance resources. Bridge-deck welding certification bottlenecks concentrate qualified fabricators elsewhere, extending eastern corridor deployment timelines. The Durgapur-Asansol steel belt supplies structural materials for Himalayan rail corridor feeder networks.
India Transportation Infrastructure Market Competitive Landscape
Consortium-based bidding dominates the current landscape as bundled multimodal contracts displace solo EPC arrangements. The vendor base organizes around three strategic archetypes: integrated cement-to-construction conglomerates, specialized bridge-deck engineering firms, and port-centric infrastructure developers. Capacity expansion and strategic partnerships represent the primary competitive vectors, with qualification pool consolidation accelerating in western and southern states.
Among diversified construction conglomerates, Larsen & Toubro Limited and Tata Projects exemplify contrasting positioning archetypes. Larsen & Toubro Limited anchors the integrated workflow tier through captive cement supply chains and expressway tender dominance in western India. Tata Projects occupies the specialized engineering tier, with bridge-deck fabrication capabilities that align with Himalayan rail corridor specifications. Megha Engineering & Infrastructures Limited represents the emerging challenger archetype, securing position through consortium participation in PM Gati Shakti-integrated logistics node development.
| Leading Market Players |
|---|
| Larsen & Toubro Limited |
| Tata Projects |
| Megha Engineering & Infrastructures Limited |
| IRB Infrastructure Developers Ltd |
| Shapoorji Pallonji |
| Dilip Buildcon Limited |
| Adani Ports and Special Economic Zone |
| KEC International Limited |
| Reliance Infrastructure Limited |
| Others |
Pricing and Supply Chain Analysis
NHAI fixed-price tender concentration anchors project-based contract economics across India's transportation infrastructure sector, compressing EPC margins when steel rebar and clinker input costs swing. Contractors absorb cost volatility through qualification pool consolidation, where BIS-certified blended concrete mixes command premium positioning over commodity Portland cement.
Pricing Analysis
High-volume highway construction runs on thin margins while specialized rail electrification and airport composite applications sustain premium returns. Price differentiation rests on certification grade—BIS-certified geopolymer blends and CEA-cleared electrical systems separate qualified contractors from commodity bidders. Cost compression in fixed-price NHAI tenders is intensifying because steel rebar price instability transfers risk to EPC balance sheets. State public works departments show highest price sensitivity on standard pavement contracts; private port operators and airport authorities demonstrate lowest sensitivity for fatigue-resistant composite specifications.
Supply Chain Analysis
BIS certification and CEA electrical clearance protocols gate qualified supplier participation, filtering domestic limestone processors and switchgear OEMs from project eligibility. Raw material procurement draws from Rajasthan and Madhya Pradesh limestone reserves, Karnataka and Tamil Nadu steel rebar fabrication, and imported clinker subject to DGFT duty volatility. Single-source vulnerability concentrates in qualified bridge-deck welding fabricators clustered in western India, extending eastern corridor timelines. Distribution runs through Ministry of Road Transport and Highways tender aggregations, state public works department specifications, and Sagarmala-linked port authority procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
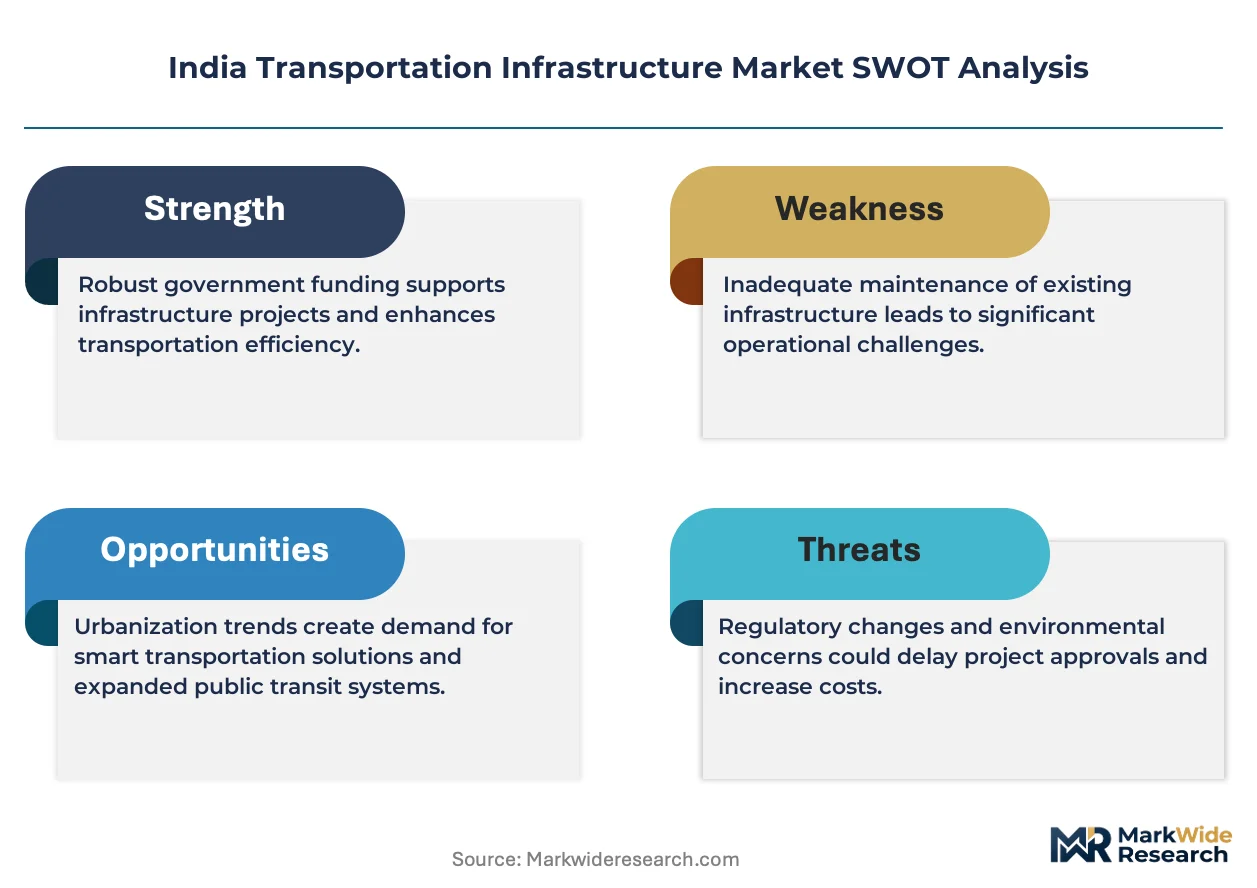
India's transportation infrastructure operates as a cost-of-compliance market where BIS certification mandates for IRC axle-load specifications create durable moats for pre-qualified contractors. Regulatory burden accumulation favors incumbents with established certification workflows over capital-rich but unqualified entrants.
For Market Incumbents: To counter steel rebar price volatility on fixed-price NHAI tenders, deepen captive cement supply chain control through Rajasthan limestone lease consolidation and geopolymer blend R&D investment. Anchor position further by acquiring distressed EPC portfolios from margin-compressed mid-tier competitors unable to absorb input cost swings.
For New Entrants and Emerging Players: Digital twin modeling capabilities for real-time stress simulation offer technology-first entry into design-validation subcontracts bypassing full EPC qualification requirements. Target Tier-2 urban metro rail networks in Kochi and Lucknow where CEA 25kV AC clearance protocols standardize specifications and reduce incumbent certification advantages. Pursue consortium participation with established rail electrification specialists rather than solo bidding.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated construction conglomerates with captive material supply and BIS-certified production workflows. Monitor infrastructure investment trust regulatory reform as the signal indicating institutional capital absorption capacity for operational toll road and container terminal assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Captive clinker supply insulates Rajasthan-based contractors from DGFT import duty volatility. |
| CEA Electrical Clearance Investment | 25kV and 50kV AC certification unlocks Himalayan and Tier-2 metro rail electrification contracts. |
| Geopolymer Concrete R&D Scale-Up | BIS-certified blended mix development reduces thermal curing costs for Bharatmala Phase-II expressways. |
| Consortium-Based Bidding Formation | PM Gati Shakti multimodal logistics node qualification requires combined road-rail-port expertise. |
| Infrastructure Investment Trust Structuring | Operational toll road yield profiles attract institutional capital beyond fiscal deficit constraints. |
Research Methodology
Document review covered Ministry of Road Transport and Highways tender records, NHAI asset monetization disclosures, and CEA technical standards, complemented by interviews with EPC contractor procurement directors, state public works department engineers, port authority project managers, and BIS certification auditors. Secondary validation drew from Sagarmala and Bharatmala program progress reports, DGFT trade data on clinker imports, and MoEFCC environmental clearance timelines. Bottom-up project pipeline aggregation and top-down fiscal allocation analysis were cross-referenced for triangulation.
Historical execution rates on NHAI and Sagarmala contracts were cross-referenced against panel input from contractor bid teams and multilateral development bank infrastructure officers. Segmentation modeling spanned infrastructure type, material certification tier, funding source architecture, and end-user procurement specifications across the projection horizon. CAGRs were derived from project commissioning schedules, limestone reserve quality trajectories, and steel rebar price elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MoEFCC forest diversion approval delays and DGFT duty regime shifts. Forecasts reflect documented assumptions on contractor qualification pool consolidation and institutional capital absorption through infrastructure investment trust structures. A model refresh is warranted upon material change in BIS certification mandate timing or CEA electrical protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Cofferdam Market
Infrastructure Construction
Ship Port Infrastructure Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
Israel Data Center Construction Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Rebar Tier Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
Conventional Overhead Conductor Market