
 Eastern Europe Construction Market | 2026-2036
Eastern Europe Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Eastern Europe Construction Market Foresight
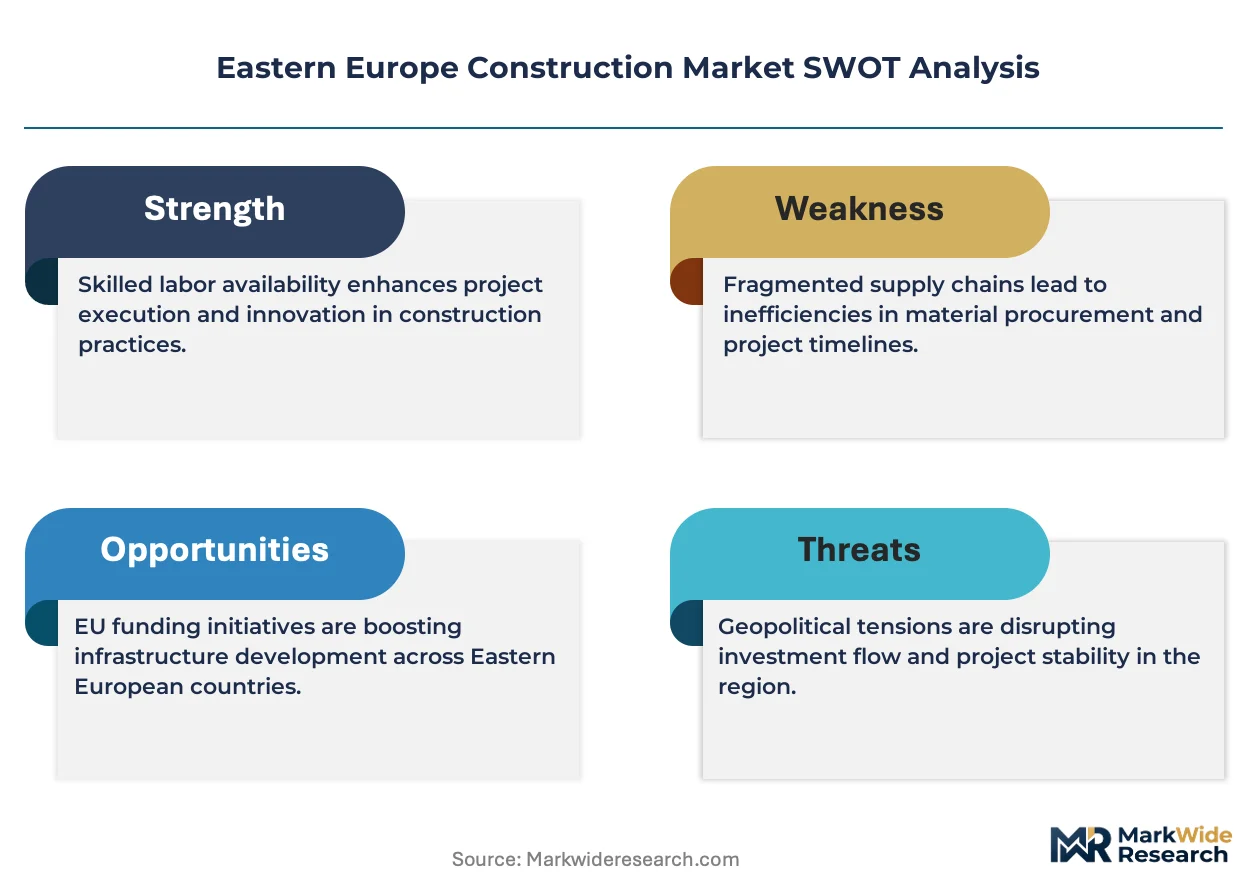
CE marking under the Construction Products Regulation is redrawing competitive access across the region. Budimex leverages its Polish manufacturing base to control domestic supply chains for concrete and steel frameworks. Strabag anchors Central European rail and highway portfolios through integrated civil engineering capabilities. Skanska differentiates via modular construction methods that compress project timelines for commercial clients.
Eastern Europe construction encompasses the planning, assembly, and commissioning of built structures using reinforced concrete, structural steel, timber framing, and curtain-wall glazing systems with specified load-bearing capacities and thermal performance ratings. The sector delivers residential housing, logistics facilities, transport nodes, and public buildings that underpin economic connectivity and urban density. Residential building types command the largest volume share as housing deficits in Poland, Romania, and the Czech Republic sustain multi-year development pipelines. Green building methods expand fastest as EU energy performance directives mandate near-zero energy standards for new stock and deep retrofits of existing assets. Mega projects concentrate margin pools through bundled design-build-finance contracts that lock in multi-year revenue visibility.
EU Green Deal implementation through the Energy Performance of Buildings Directive shapes product standards and retrofit demand timelines across member states. Poland's General Directorate for National Roads and Motorways and Romania's Ministry of Transport set procurement rules that favor contractors with certified quality management and local content thresholds. Stakeholders must monitor regulatory divergence between EU-aligned and non-EU Eastern European jurisdictions as compliance costs fragment competitive positioning across the region.
Market Dynamics
EU Green Deal building performance standards are compressing project timelines and retrofit obligations across Eastern Europe, forcing contractors to reconfigure material sourcing and certification workflows before 2030 deadlines lock in.
Growth Catalysts
- Transport infrastructure allocation:Poland's General Directorate for National Roads and Motorways and Romania's Ministry of Transport are channeling capital into highway and rail corridors, sustaining multi-year civil engineering demand.
- EU Energy Performance of Buildings Directive:Near-zero energy mandates for new stock and deep retrofit requirements are expanding contract volumes for thermal envelope upgrades across member states.
- Cross-laminated timber adoption:Engineered wood products are penetrating mid-rise residential and commercial frames as carbon accounting favors biogenic material substitution.
Market Restraints
- Reinforcing steel price volatility:Scrap metal and energy input costs for electric arc furnace production fluctuate with regional electricity pricing, compressing fixed-price contract margins.
- Cement supply concentration:Clinker production clusters in Poland and the Czech Republic create logistics bottlenecks for Romanian and Bulgarian projects distant from kiln capacity.
- CE marking compliance friction:Construction Products Regulation testing and factory production control certification delays market entry for non-EU material suppliers.
Strategic Opportunities
- Modular construction penetration:Off-site manufacturing of volumetric units is gaining traction in Warsaw and Krakow commercial developments, compressing on-site labor exposure.
- EU Green Deal retrofit wave:Deep renovation mandates for existing building stock are opening multi-decade service contracts for energy performance contracting firms.
- Balkan corridor expansion:North Macedonia and Serbia transport links to EU networks are generating greenfield infrastructure demand outside saturated Polish and Romanian markets.
Industry Challenges
- Certified trades scarcity:Passive house and nearly zero-energy building construction skills lag project pipeline expansion in secondary Polish and Romanian cities.
- Design-build-finance integration complexity:Bundled contract structures demand capital deployment capabilities and risk management disciplines unfamiliar to traditional general contractors.
- Legacy building stock heterogeneity:Pre-1990 panel construction and masonry structures complicate standardized retrofit approaches across Warsaw, Bucharest, and Prague housing estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eastern Europe Construction Market |
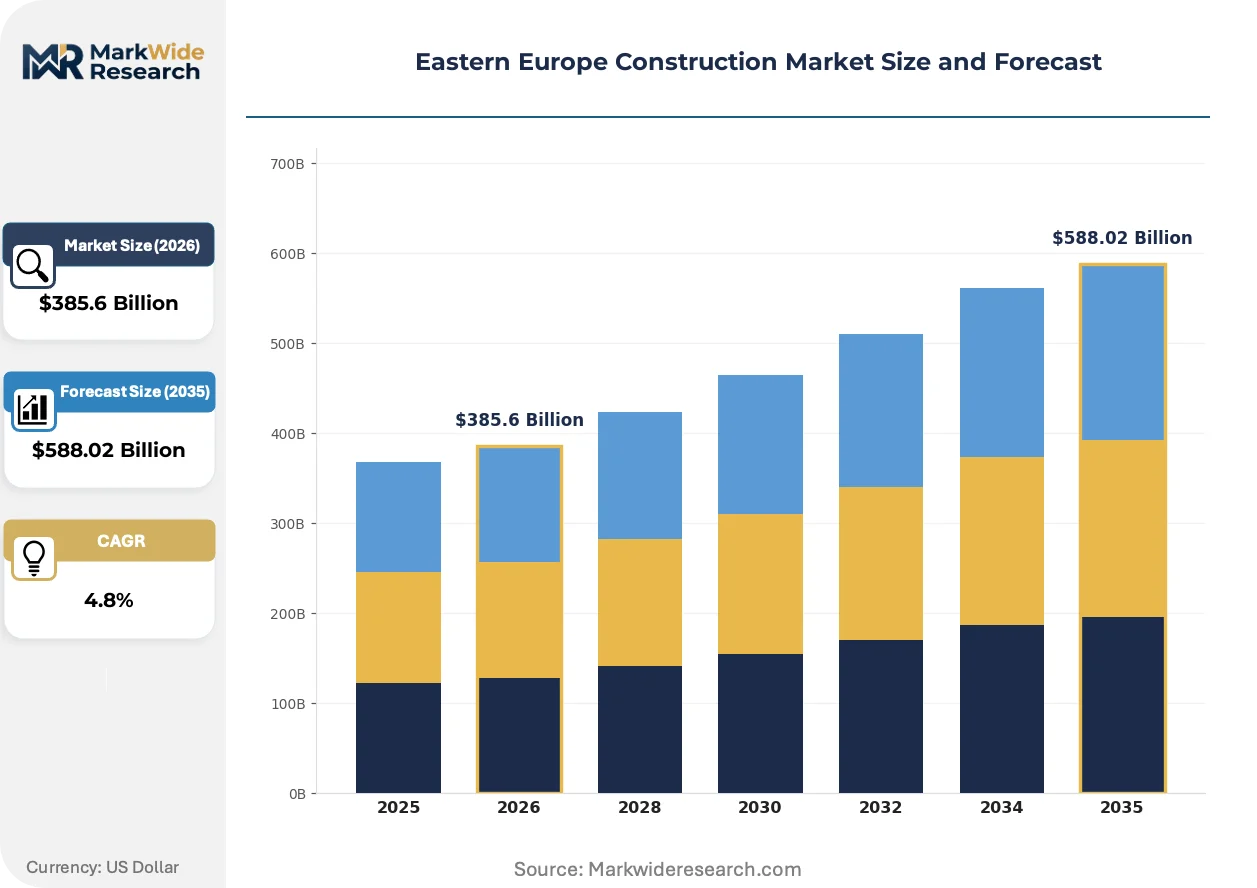
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $588.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential, Commercial, Industrial, Institutional Material Type: Concrete, Steel, Wood, Glass Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Construction Method: Traditional, Modular, Prefabricated, Green Building |
| Companies Covered | Budimex, Vinci, Strabag, Bouygues, BESIX, Skanska, Metinvest, Eiffage, PORR, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eastern Europe Construction Market Shifts & Advancements
Digital fabrication and performance-based material specifications are reconfiguring how Eastern European contractors bid, source, and deliver projects. Three developments dominate the transformation arc.
Cross-laminated timber and glulam systems are penetrating structural applications previously reserved for reinforced concrete and steel. Polish and Czech developers of mid-rise residential and office buildings are specifying engineered wood for its carbon sequestration credentials and construction speed. Factory-controlled precision is supplanting on-site formwork and curing delays, compressing weather-dependent schedules.
Energy Performance of Buildings Directive recasts are tightening thermal bridge requirements and mandating building automation integration. Member state transposition deadlines are forcing national building codes toward nearly zero-energy standards. Deep retrofit obligations for public and residential stock are redirecting contractor specialization toward envelope diagnostics and integrated HVAC replacement.
Public procurement authorities are consolidating design-build-finance awards into multi-year framework agreements. Poland's road agency and Romanian transport ministry are bundling highway segments into decade-long concession structures. Traditional unit-price bidding is yielding to availability-payment models that transfer demand risk to contractor consortia with balance-sheet capacity.
Eastern Europe Construction Market Segmentation
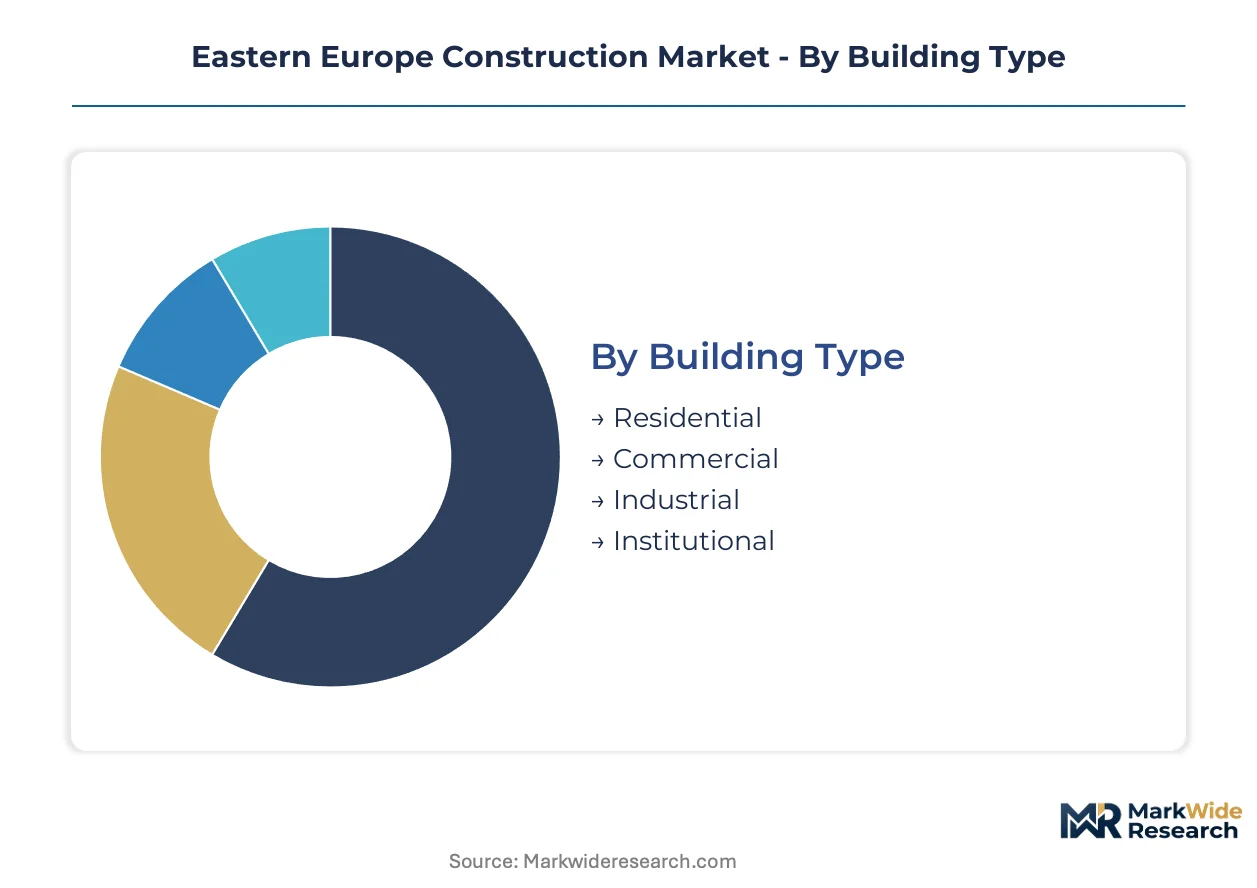
Construction demand across Eastern Europe fragments along building typology, material specifications, and procurement scale. Each segmentation axis carries distinct regulatory exposure and margin profiles that reshape contractor specialization and capital deployment strategies.
Building Type:
EU Energy Performance of Buildings Directive mandates diverge sharply across residential versus non-residential asset classes, creating compliance cost asymmetries that redirect contractor focus toward specific building categories.
- Residential:Multi-family housing estates and single-family units dominate contract volumes across Poland, Romania, and the Czech Republic. Persistent housing deficits in Warsaw, Krakow, and Bucharest sustain multi-year development pipelines, while deep retrofit obligations for pre-1990 panel construction open service contract opportunities.
- Commercial:Office complexes, retail centers, and logistics facilities command premium pricing for thermal envelope performance. Warsaw and Krakow urban corridors concentrate speculative development, with EU Green Deal standards forcing integrated building automation and near-zero energy specifications.
- Industrial:Manufacturing plants and warehousing infrastructure absorb steel-intensive framing systems. Automotive and e-commerce fulfillment demand concentrates in Polish Special Economic Zones near border crossings.
- Institutional:Hospitals, schools, and public administration buildings face public procurement rules favoring design-build-finance bundling. Romanian Ministry of Transport and Polish road agency frameworks lock in multi-year revenue visibility for qualified consortia.
Residential handles the majority of throughput; Commercial is the fastest mover on share.
Material Type:
Cost tier differentiation separates commodity bulk materials from certified low-carbon alternatives that command procurement premiums.
- Concrete:Reinforced and precast concrete systems anchor foundation and structural work. Clinker production concentrates in Poland and the Czech Republic, creating logistics cost penalties for Romanian and Bulgarian projects distant from kiln capacity.
- Steel:Structural steel and reinforcing bar demand tracks transport infrastructure allocation. Scrap metal and energy input costs for electric arc furnace production fluctuate with regional electricity pricing, compressing fixed-price contract margins.
- Wood:Cross-laminated timber and glulam systems penetrate mid-rise residential frames. Polish and Czech developers specify engineered wood for carbon sequestration credentials and construction speed advantages.
- Glass:Curtain-wall and high-performance glazing systems satisfy thermal bridge requirements under tightening Energy Performance of Buildings Directive recasts. Building automation integration mandates expand specification complexity.
Concrete maintains volume dominance; Wood is climbing the fastest as biogenic substitution accelerates.
Project Size:
Procurement authority and risk allocation structures vary systematically with project scale, from municipal permitting to national framework agreements.
- Small Scale:Single-family homes and minor renovations operate through local contractor networks. CE marking compliance friction delays material sourcing for non-EU suppliers at this tier.
- Medium Scale:Multi-family residential and light commercial projects balance standardization with customization. Secondary Polish and Romanian cities face certified trades scarcity for passive house construction skills.
- Large Scale:Office complexes and industrial facilities demand integrated project delivery. Design-build-finance integration complexity favors contractors with capital deployment capabilities.
- Mega Projects:Highway corridors, rail nodes, and urban regeneration schemes bundle decade-long concession structures. Poland's General Directorate for National Roads and Motorways and Romania's Ministry of Transport consolidate awards into availability-payment models.
Mega Projects concentrate margin pools; Medium Scale projects face the steepest capability constraints.
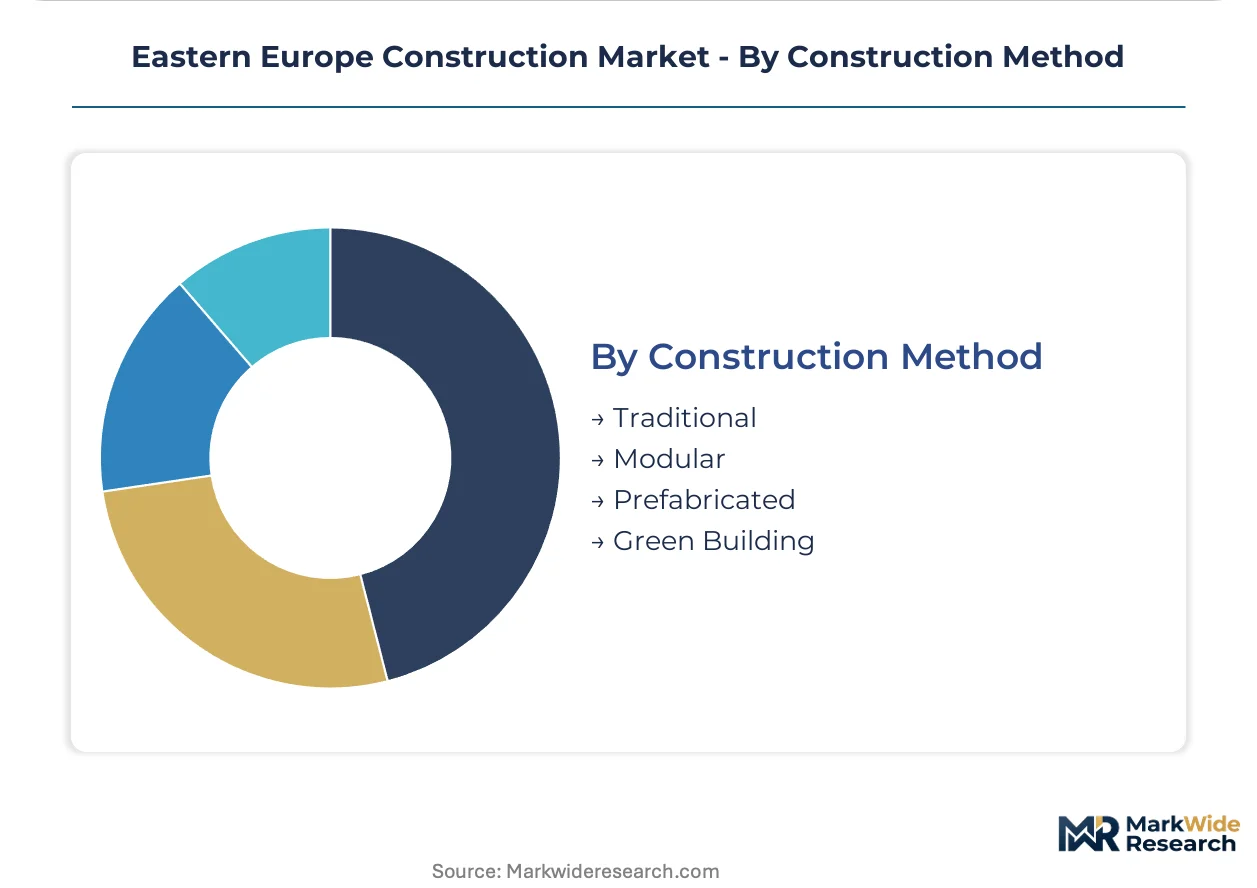
Construction Method:
Maturity gradients separate established on-site practices from emerging off-site and performance-based delivery models.
- Traditional:Cast-in-place concrete and steel erection on project sites retains cost advantages for one-off structures. Weather exposure and labor dependency compress scheduling reliability.
- Modular:Volumetric unit manufacturing gains traction in Warsaw and Krakow commercial developments. Factory-controlled precision reduces on-site labor exposure and accelerates commissioning timelines.
- Prefabricated:Panelized wall and floor systems balance customization with manufacturing efficiency. Logistics coordination demands favor contractors with captive supply chain control.
- Green Building:Near-zero energy and passive house standards mandate integrated envelope and HVAC design. EU Green Deal retrofit wave opens multi-decade service contracts for energy performance contracting firms.
Traditional methods retain volume leadership; Green Building specifications are expanding most quickly on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public procurement authorities and private developers across Eastern Europe concentrate capital deployment in transport corridors and urban regeneration zones. EU Green Deal compliance timelines are compressing project schedules in member states while non-EU neighbors face diverging regulatory pressures.
Poland
Transport infrastructure absorbs the dominant share of public capital through the General Directorate for National Roads and Motorways framework agreements. EU Energy Performance of Buildings Directive transposition mandates near-zero energy standards for new residential stock from 2030. The Warsaw-Krakow urban corridor concentrates logistics facility development and commercial office construction.
Romania
Rail and highway modernization programs channel multi-year civil engineering demand through Ministry of Transport procurement. CE marking compliance under the Construction Products Regulation gates material sourcing for public building retrofits. Bucharest and secondary cities Cluj-Napoca and Timișoara cluster residential development and thermal envelope upgrade contracts.
Czech Republic
Industrial manufacturing and warehousing construction tracks automotive supplier investments in Special Economic Zones. REACH and RoHS chemical regulations constrain material specifications for commercial building finishes. Prague and Brno anchor office development pipelines while Ostrava hosts brownfield regeneration schemes.
Hungary
Battery plant and electric vehicle supplier facilities drive steel-intensive industrial construction near Győr and Debrecen. EU Green Deal building performance standards apply to public procurement above defined thresholds. Budapest concentrates residential high-rise development and historic district retrofit obligations.
Bulgaria
Logistics corridor positioning along EU-Turkey transit routes sustains warehousing and cold storage construction. Non-EU regulatory divergence creates compliance cost asymmetries versus member state competitors. Sofia and Plovdiv cluster commercial development while Black Sea tourism zones drive seasonal hospitality construction.
Eastern Europe Construction Market Competitive Landscape
Player mix skews toward integrated civil engineering specialists with captive concrete and steel supply chains. Market structure concentrates around three tiers: pan-European infrastructure conglomerates with balance-sheet capacity for design-build-finance contracts, mid-scale national contractors dominating residential and light commercial segments, and specialized envelope and MEP firms capturing retrofit service contracts. Dominant competitive moves include backward integration into precast concrete manufacturing and strategic partnerships with modular construction technology licensors.
Among Poland-based integrated contractors, Budimex anchors domestic supply chain control for transport infrastructure frameworks. Strabag exemplifies the pan-European infrastructure archetype with multi-country rail and highway portfolios. Skanska occupies a position in modular and green building delivery methods for commercial clients seeking compressed project timelines.
| Leading Market Players |
|---|
| Budimex |
| Vinci |
| Strabag |
| Bouygues |
| BESIX |
| Skanska |
| Metinvest |
| Eiffage |
| PORR |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day steel reinforcement lead times in Polish transport infrastructure frameworks concentrate pricing power with domestic electric arc furnace operators and amplify margin sensitivity to regional electricity tariffs. This inventory compression forces contractors into cost-plus indexation clauses that transfer scrap metal and energy input volatility to public procurement authorities.
Pricing Analysis
Cost-plus contracts with steel scrap and cement clinker indexation dominate Polish and Romanian public infrastructure awards. Price differentiation rests on CE marking certification tier and captive precast concrete production. Cost compression in standard-grade reinforced concrete intensifies as Romanian projects absorb logistics premiums from distant Polish kiln capacity. State road agencies exhibit lowest price sensitivity; speculative Warsaw commercial developers face acute margin pressure.
Supply Chain Analysis
Poland and the Czech Republic anchor clinker and precast concrete production for the regional market. Romanian and Bulgarian project demand draws from these northern kilns, creating freight cost asymmetries. Single-source vulnerability concentrates in electric arc furnace steel output tied to regional power pricing. Distribution runs through captive precast yards controlled by integrated civil engineering conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contractor differentiation increasingly hinges on certified nearly zero-energy building skills and balance-sheet capacity for design-build-finance structures—assets that remain scarce outside Warsaw and Krakow. This capability gap fragments competitive positioning across secondary Romanian and Polish cities.
For Market Incumbents: Shield margin pools by deepening backward integration into cross-laminated timber manufacturing and precast concrete production. Bid consolidation threatens smaller Polish residential contractors lacking captive supply chain control. Certification investment in passive house construction skills anchors defensible positioning for EU Green Deal retrofit mandates. For New Entrants and Emerging Players: Anchor in Cluj-Napoca and Timișoara residential thermal envelope upgrades, where certified trades scarcity outpaces project pipeline expansion. Modular construction technology licensing offers the most penetrable entry vector for Warsaw commercial developers seeking compressed commissioning timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because design-build-finance bundling favors balance-sheet-heavy infrastructure conglomerates over traditional general contractors. Acquisition targets cluster around mid-scale envelope specialists with energy performance contracting capabilities. Watch Romanian Ministry of Transport framework award concentration as inflection signal for regional competitive restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precast Concrete | Captive supply chain control neutralizes cement logistics penalties for Romanian highway contractors. |
| Passive House Certification Investment | EU Energy Performance of Buildings Directive mandates create contractor scarcity premiums in secondary cities. |
| Modular Construction Technology Licensing | Factory-controlled precision compresses Warsaw commercial project timelines and labor exposure. |
| Cross-Laminated Timber Manufacturing Scale-Up | Carbon accounting favors biogenic substitution in Polish mid-rise residential frames. |
| Design-Build-Finance Consortium Formation | Poland's road agency availability-payment models demand capital deployment capabilities. |
Research Methodology
Initial hypotheses were tested against primary input from project directors at integrated civil engineering firms, procurement officers at Poland's General Directorate for National Roads and Motorways, envelope specialists at energy performance contracting firms, and plant managers at precast concrete manufacturing sites, then refined against secondary validation from EU Construction Products Regulation implementation reports, national building code transposition documents, and customs data on steel and cement trade flows. Bottom-up project pipeline assessments and top-down macro construction spend estimates were triangulated to anchor volume and value outputs.
Variance decomposition across the projection horizon isolates transport infrastructure allocation, EU Green Deal regulatory compliance timelines, and material input cost volatility as primary forecast drivers. Segmentation modeling spans building typology, material specification grade, project procurement scale, and construction method maturity. CAGRs were derived from regression analysis linking public capital commitment schedules to contractor capacity expansion patterns, with cross-laminated timber penetration curves and retrofit obligation enforcement intensity as industry-specific inputs.
Material uncertainties — reinforcing steel price volatility, CE marking compliance delays for non-EU suppliers, and divergence in national Energy Performance of Buildings Directive transposition — sit outside the modeled envelope. Forecasts reflect assumptions on procurement rule stability and clinker production capacity expansion. Recalibration cycles align with material shifts in EU Green Deal enforcement intensity and transport ministry framework award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Australia Construction Market
Building Construction
Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Prefabricated Construction Market
Building Construction
India Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Europe Modular Construction Market
Building Construction
India Commercial Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Egypt Residential Construction Market
Building Construction
Sweden New Construction Market
Building Construction
China Construction Market
Building Construction
China Building Construction Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Latin America Construction Market
Building Construction
Spain Prefab Wood Buildings Market