
 Cold Storage Construction Market | 2026-2036
Cold Storage Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Storage Construction Market Intelligence
Subscription-based energy management and automation software is shifting the value proposition from a one-time build cost to ongoing operational efficiency contracts. Americold Realty Trust leverages its extensive network to offer integrated logistics and construction consulting. Lineage Logistics Holdings, LLC differentiates through its focus on automated warehouse technologies and sustainable building practices. Tippmann Group specializes in designing and building facilities specifically for the food processing industry.
Cold storage construction involves the design, engineering, and erection of temperature-controlled buildings using insulated metal panels and specialized refrigeration systems. These facilities are engineered to maintain specific temperature ranges, from chilled above 0°C to frozen down to -40°C, essential for preserving perishable goods. New build projects for large-scale facilities constitute the largest share of construction activity, driven by major logistics providers. Within end-user industries, the pharmaceutical segment shows significant momentum, requiring advanced controlled atmosphere and blast freezing technologies.
Compliance with food safety and pharmaceutical standards, such as those from the US FDA and the European EMA, dictates facility design and material choice. Building codes and environmental regulations, including the EU's F-Gas Regulation and EPA rules in the United States, govern the types of refrigerants and insulation materials used. Stakeholders must now decide whether to invest in highly automated, energy-efficient new builds or focus on retrofitting existing assets to meet new standards.
Market Dynamics
The market's trajectory is defined by the convergence of stringent food safety and pharmaceutical regulations with the technological demands of advanced logistics. This dynamic forces a choice between high-cost, automated new builds and complex retrofits of existing infrastructure to maintain compliance and competitiveness.
Growth Catalysts
- Regulatory Mandates:The EU's F-Gas Regulation and similar EPA rules in the US are compelling the adoption of natural refrigerants like CO2 and ammonia, driving demand for new refrigeration systems and facility designs.
- Pharmaceutical Expansion:The biologics and vaccine supply chain requires facilities with precise temperature control, controlled atmospheres, and blast freezing capabilities, fueling construction of specialized GMP-compliant cold storage.
- Logistics Infrastructure Investment:Governments in major food-exporting nations like India and Brazil are promoting investment in cold chain infrastructure to reduce post-harvest losses and boost international trade competitiveness.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for automated systems, specialized insulated panels, and advanced refrigeration units acts as a major barrier to entry, particularly for smaller operators.
- Material Price Volatility:Fluctuations in the cost of steel and polyurethane for insulated metal panels create budget uncertainty and can delay project timelines, impacting contractor profitability.
- Complex Permitting Processes:Navigating a web of local building codes, environmental regulations, and food safety certifications from bodies like the FDA or EMA can significantly extend project lead times.
Strategic Opportunities
- Emerging Asian Markets:Southeast Asian nations present a significant opportunity for cold storage development, driven by a rising middle class, dietary shifts, and underdeveloped cold chain networks.
- Integrated Energy Management:Offering subscription-based energy management software bundled with construction creates long-term revenue streams and shifts the value proposition to total cost of ownership.
- Retrofitting and Modernization:Upgrading existing facilities with energy-efficient refrigeration systems and automation to meet new standards like the F-Gas Regulation offers a substantial service-based revenue stream.
Industry Challenges
- Skilled Labor Scarcity:A shortage of technicians trained in installing and maintaining advanced ammonia and CO2 refrigeration systems, alongside automation controls, constrains construction capacity and increases labor costs.
- Legacy System Integration:Integrating new automated storage and retrieval systems and warehouse management software with clients' existing IT infrastructure poses significant technical and operational hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Storage Construction Market |
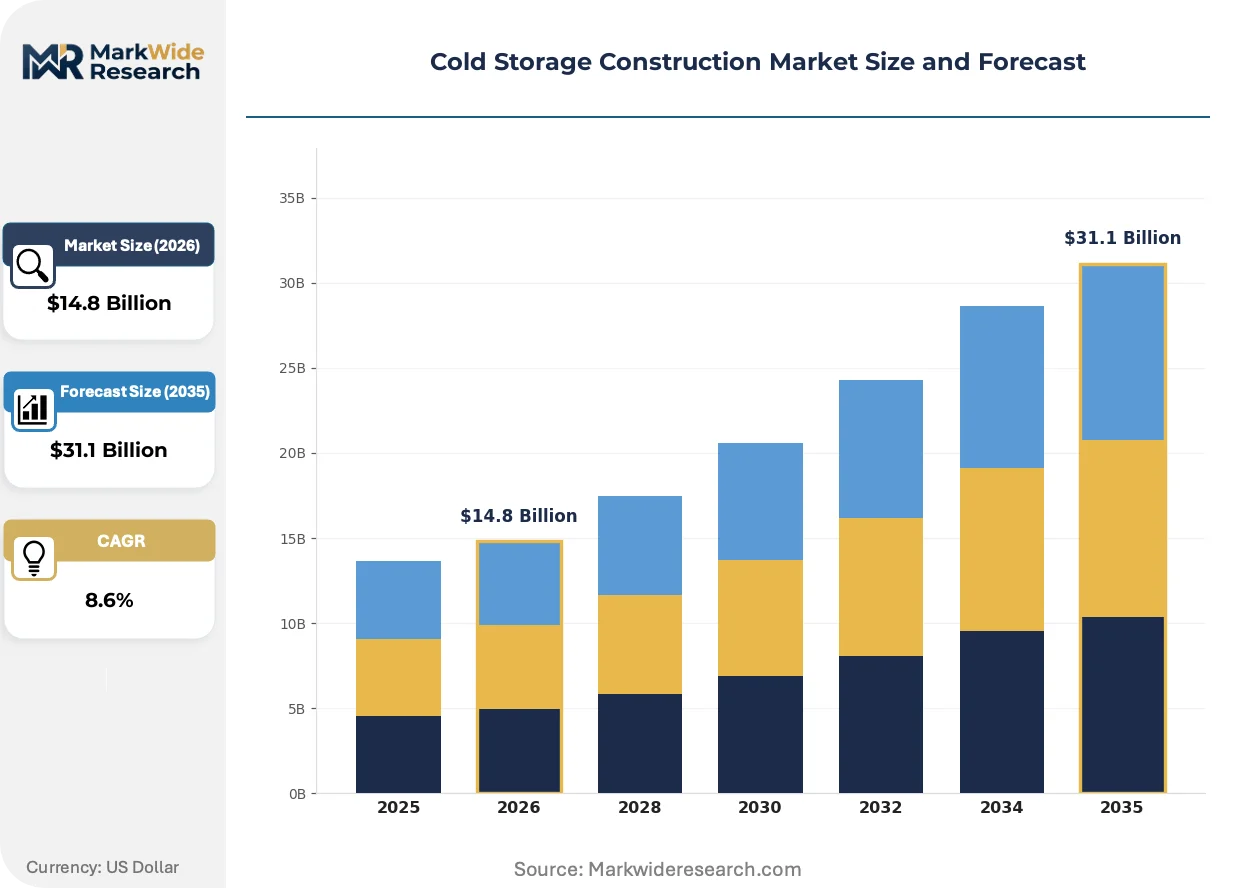
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: New Build, Expansion, Renovation, Retrofit Storage Technology: Blast Freezing, Refrigerated Warehousing, Controlled Atmosphere, Cryogenic Storage, Ice Storage End User Industry: Food Processing, Pharmaceutical, Chemical Manufacturing, Logistics Providers, Biotechnology Facility Capacity: Small Scale, Medium Scale, Large Scale, Bulk Storage |
| Companies Covered | Americold Realty Trust, Lineage Logistics Holdings, LLC, United States Cold Storage, Inc., Tippmann Group, Hansen Cold Storage Construction, Burris Logistics, Primus Builders, Inc., Preferred Freezer Services, AGRO Merchants Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Storage Construction Market Strategic Shifts & Innovations
Automation and sustainability are altering facility design and operational economics. The market is pivoting from static buildings toward adaptable, energy-efficient assets managed by software, driven by regulatory pressures and cost imperatives.
Prefabricated insulated metal panel (IMP) systems provide the core building envelope for modern cold storage. Logistics providers and food processors adopt these systems to accelerate construction. This technology is modularizing the construction process, allowing for faster deployment, design flexibility, and predictable thermal performance compared to traditional methods.
The United States EPA's regulations under the AIM Act mandate a phase-down of high-GWP hydrofluorocarbons (HFCs). This policy accelerates the transition toward natural refrigerants like ammonia and CO2 in new builds and major retrofits. Consequently, facility owners in the food sector must invest in new system designs to ensure long-term compliance.
A notable shift is occurring from one-time construction contracts to long-term service agreements focused on operational outcomes. This model disrupts traditional builders by bundling construction with ongoing energy management and automation support. The trend is most prominent within the pharmaceutical supply chain in North America and Europe, where uptime is paramount.
Cold Storage Construction Market Segmentation
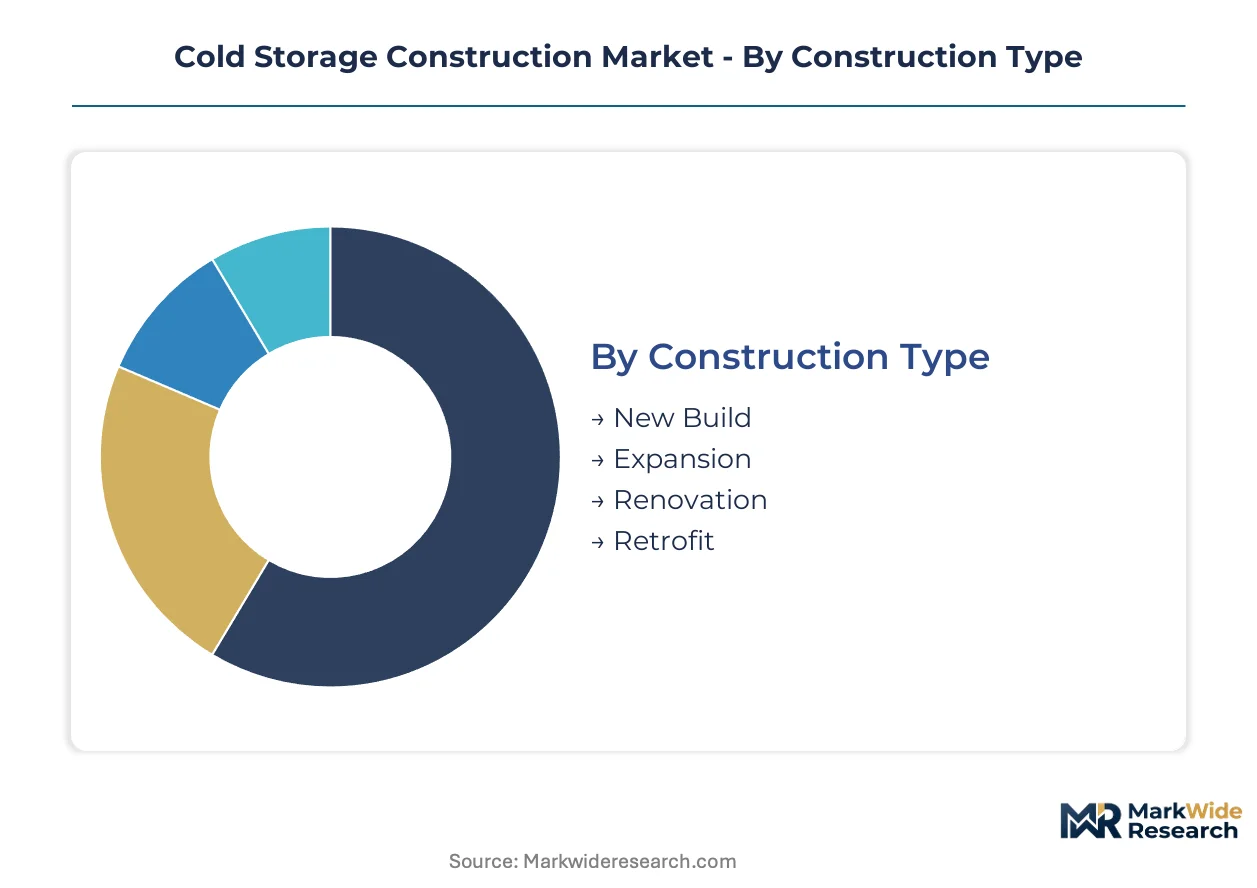
The cold storage construction market is segmented to reflect the diverse operational requirements and strategic investments across the industry. Understanding these segments clarifies the varying demands for specialized infrastructure, technological integration, and regulatory compliance that shape project execution.
Construction Type:
The cold storage construction market exhibits distinct segments based on the nature of the project, reflecting the industry's ongoing upgrade and replacement cycles.
- New Build:These projects involve the construction of entirely new temperature-controlled facilities on undeveloped sites, often incorporating advanced automation and energy-efficient designs. Major logistics providers and expanding food processing companies in nations like India and Brazil drive demand for new capacity.
- Retrofit:Retrofit projects involve upgrading existing cold storage facilities with new refrigeration systems, insulation, or automation technologies to meet modern standards or improve efficiency. European and North American facilities frequently undergo retrofits to comply with environmental regulations like the EU's F-Gas Regulation.
- Expansion:Expansion projects add capacity to existing operational cold storage facilities, often by extending current structures or building adjacent units. Logistics hubs frequently undertake expansions to handle increased throughput.
- Renovation:Renovation focuses on modernizing internal components, such as racking, lighting, or controlled atmosphere systems, within an existing cold storage structure. Pharmaceutical facilities often require renovations to update cleanroom specifications.
Volume placements concentrate in New Build projects; the faster expansion belongs to Retrofit initiatives.
Storage Technology:
Different storage technologies define the specific environmental controls and capabilities required within cold storage facilities.
- Refrigerated Warehousing:This segment includes facilities designed to maintain specific temperature ranges, typically from chilled (above 0°C) to frozen (down to -40°C), essential for preserving perishable goods. Food processing and general logistics providers form the primary demand base for these foundational storage solutions.
- Blast Freezing:Blast freezing technology involves rapidly lowering the temperature of products to deep-freeze levels, crucial for maintaining product quality and extending shelf life. The pharmaceutical segment, particularly for biologics and vaccines, relies heavily on blast freezing for product integrity.
- Controlled Atmosphere:Facilities with controlled atmosphere technology manage not only temperature but also oxygen, carbon dioxide, and nitrogen levels to slow ripening or spoilage. Fresh produce and specialized pharmaceutical storage utilize these advanced systems.
- Cryogenic Storage:Cryogenic storage maintains ultra-low temperatures, often below -150°C, typically achieved using liquid nitrogen or specialized mechanical freezers. Biotechnology companies and research institutions require cryogenic solutions for sensitive biological samples.
- Ice Storage:Ice storage systems generate and store ice during off-peak hours to provide cooling capacity during peak demand, offering energy management benefits. Large-scale food processing plants sometimes integrate ice storage for process cooling.
The foundational requirement for Refrigerated Warehousing underpins market activity, while Blast Freezing exhibits significant growth due to specialized needs.
End User Industry:
The diverse requirements of various end-user industries shape the design and technological integration within cold storage construction.
- Pharmaceutical:This segment demands highly specialized, GMP-compliant facilities with precise temperature control, controlled atmospheres, and blast freezing capabilities to protect sensitive biologics and vaccines. Regulatory bodies like the US FDA and European EMA dictate stringent design and operational standards for these facilities.
- Logistics Providers:Major logistics providers drive the construction of large-scale, often highly automated, cold storage facilities that serve as critical nodes in global supply chains. Investment in these facilities is prominent in emerging food-exporting nations like India and Brazil, enhancing international trade competitiveness.
- Food Processing:This industry requires cold storage facilities designed to preserve raw materials, work-in-progress, and finished food products, adhering to strict food safety and hygiene standards. Facilities range from chilled storage for dairy to deep-freeze for meats.
- Chemical Manufacturing:Cold storage for chemical manufacturing involves maintaining specific temperature ranges for temperature-sensitive chemicals, often with additional safety and containment protocols. Specialized facilities handle volatile or hazardous materials.
- Biotechnology:Biotechnology companies require ultra-low temperature storage for cell lines, genetic material, and other biological assets, often necessitating cryogenic solutions. Research and development activities within the sector drive this demand.
The largest volume of construction serves Logistics Providers, with Pharmaceutical demonstrating the steepest expansion trajectory.
Facility Capacity:
Facility capacity segments reflect the scale of operations and the volume of goods requiring temperature-controlled storage.
- Large Scale:Large-scale facilities are extensive, often multi-temperature warehouses designed for high-volume throughput and centralized distribution, serving regional or national markets. Major logistics providers invest in these facilities to support complex supply chains and e-commerce fulfillment.
- Bulk Storage:Bulk storage facilities are designed to hold massive quantities of a single or limited range of products, typically raw agricultural commodities or frozen ingredients, often for long durations. Food-exporting nations, such as India and Brazil, utilize bulk storage to reduce post-harvest losses.
- Small Scale:Small-scale cold storage units serve localized needs, such as urban distribution centers for last-mile delivery or specialized storage for niche products. These facilities prioritize accessibility and flexibility.
- Medium Scale:Medium-scale facilities typically serve regional distribution or specific processing needs, offering a balance between capacity and operational complexity. Food processors and regional logistics companies commonly utilize medium-scale cold storage.
While Bulk Storage projects often dominate in terms of individual project size, the collective demand for Large Scale facilities from logistics providers is substantial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bustling logistics hubs across Europe and North America drive significant cold storage construction activity. Investment in advanced facilities concentrates near major population centers and export routes. Developing nations like India and Brazil are rapidly expanding their cold chain infrastructure to support agricultural exports and reduce spoilage.
United States
The United States sees substantial cold storage demand from the pharmaceutical and food processing sectors. EPA regulations under the AIM Act accelerate the transition to natural refrigerants in new builds and major retrofits. California's Central Valley, a major agricultural region, continues to expand cold storage capacity for fresh produce distribution.
Germany
Germany's cold storage market is shaped by stringent pharmaceutical standards and food safety requirements. The EU's F-Gas Regulation compels the adoption of low-GWP refrigerants, influencing new facility designs. The Rhine-Main region, a key logistics and pharmaceutical hub, experiences continuous investment in highly automated cold storage facilities.
India
India is a critical market for cold storage infrastructure development, driven by efforts to reduce post-harvest losses and boost food exports. Government initiatives, including the FSSAI's food safety standards, guide facility construction. Major logistics corridors around Mumbai and Delhi-NCR are seeing significant investment in large-scale refrigerated warehouses.
Brazil
Brazil's agricultural export ambitions fuel considerable investment in cold storage construction, particularly for meat and produce. ANVISA regulations for pharmaceuticals and food safety standards influence facility design and operational protocols. The São Paulo state, with its extensive agricultural and industrial base, expands its cold chain network for both domestic and international markets.
Vietnam
Vietnam presents a strategic opportunity for cold storage development, supported by a rising middle class and evolving dietary patterns. The government promotes investment in modern logistics infrastructure to enhance trade competitiveness. Ho Chi Minh City, a major economic center, is experiencing growth in refrigerated warehousing to support fresh food distribution and exports.
Cold Storage Construction Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the cold storage construction market. The industry structure shows a mix of large, integrated logistics providers and specialized design-build firms. Strategic archetypes include those focused on comprehensive cold chain solutions, those specializing in specific end-user industries, and technology providers offering automation and energy management software. Capacity expansion and strategic partnerships for integrated service offerings represent dominant competitive moves.
Specialists in integrated cold chain solutions, such as Americold Realty Trust, leverage extensive networks to provide comprehensive logistics and construction consulting. Lineage Logistics Holdings, LLC exemplifies a focus on automated warehouse technologies and sustainable building practices. Tippmann Group represents firms specializing in designing and building facilities specifically for the food processing industry, catering to unique sector requirements.
| Leading Market Players |
|---|
| Americold Realty Trust |
| Lineage Logistics Holdings, LLC |
| United States Cold Storage, Inc. |
| Tippmann Group |
| Hansen Cold Storage Construction |
| Burris Logistics |
| Primus Builders, Inc. |
| Preferred Freezer Services |
| AGRO Merchants Group |
| Others |
Cost & Logistics Intelligence
Major Logistics Providers and pharmaceutical companies often drive project-based pricing, shifting towards value-based contracts for operational efficiency. This market structure balances high initial capital outlays with long-term service agreements for specialized cold storage facilities.
Pricing Analysis
Project-based pricing anchors construction contracts, increasingly shifting towards subscription-based or long-term service agreements for operational outcomes. Customization level for specialized facilities, such as GMP-compliant pharmaceutical cold storage, drives significant price differentiation. After-sales service, including energy management software and automation support, also influences pricing tiers. Pricing softness stems from material price volatility for steel and polyurethane, impacting contractor margins. Smaller operators exhibit higher price sensitivity compared to major logistics providers prioritizing uptime and specialized capabilities.
Supply Chain Analysis
Reverse logistics for refrigeration system components and insulated panels presents emerging challenges in the cold storage construction supply chain. Global supply of specialized refrigeration systems draws from manufacturers in Germany and the United States. Polyurethane and steel for insulated metal panels originate predominantly from Asian and European producers. Material price volatility, particularly for steel and polyurethane, creates a structural risk for project budgeting. Distribution runs through specialized engineering firms and general contractors directly to construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with natural refrigerants like CO2 and ammonia rapidly replacing legacy high-GWP hydrofluorocarbons.
For Market Incumbents: Deploy integrated service offerings by bundling construction with ongoing energy management and automation support. Invest in advanced automation R&D and natural refrigerant system expertise to mitigate threats from specialized technology providers. Expand long-term service agreements, particularly within the pharmaceutical supply chain, to ensure consistent uptime and operational efficiency. Consolidate market share through strategic partnerships for comprehensive cold chain solutions.
For New Entrants and Emerging Players: A price-point gap exists for cost-effective retrofit solutions addressing regulatory compliance in older facilities. Target the segment of small to medium-sized food processors seeking upgrades to meet new environmental standards. Focus on Southeast Asian nations where cold chain networks are underdeveloped, offering a penetrable geographic market. A go-to-market angle integrating subscription-based energy management software with retrofit services can attract new clients.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to capitalize on the market's long-term growth driven by pharmaceutical and food safety needs over the next decade. Identify specialist firms with deep expertise in automated cold chain technology or natural refrigerant system integration as prime acquisition targets. A signal to watch is increased M&A activity for automation software providers, indicating market consolidation around digital capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Emerging Markets | Logistics providers enhance global trade competitiveness for agricultural exports from India and Brazil. |
| Green Refrigerant Technology Adoption | Facility owners comply with regulations like the EU's F-Gas Regulation, reducing environmental impact. |
| Automated Warehouse Software Integration | Operators achieve higher throughput and operational efficiency for large-scale distribution centers. |
| Long-Term Service Contract Bundling | Construction firms secure recurring revenue streams, shifting focus to total cost of ownership. |
| GMP-Compliant Facility Certification | Pharmaceutical companies protect sensitive biologics, meeting stringent US FDA and European EMA standards. |
Research Approach
Document review covered EPA reports, F-Gas Regulation documents, FDA guidelines, and company annual reports, complemented by interviews with industry stakeholders. Primary interviews included cold storage facility managers, refrigeration engineers, logistics executives, and pharmaceutical supply chain leads. This approach utilized both bottom-up and top-down triangulation to ensure comprehensive data validation.
Cross-referencing historical market data with expert panel inputs formed the analytical framework across the analysis window. Segmentation dimensions modeled included construction type, storage technology, end-user industry, facility capacity, and regional regulatory frameworks. Compound annual growth rates were derived from regression analysis of historical trends and projected market drivers, with global trade volumes for perishables and pharmaceutical R&D spending serving as key forecast inputs.
Inputs from regulatory bodies and industry associations were available through the study window; gaps in specific regional investment data introduce uncertainty bands around localized forecasts. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates. Practitioners should monitor major policy announcements on refrigerants or new food safety mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Indonesia Infrastructure Market
Building Construction
China Modular Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Turkey Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
China Building Construction Market
Building Construction
Japan Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Vertical Garden Construction Market
Building Construction
Spain Construction Market
Building Construction
UK Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
US Modular Construction Market