
 Mezzanine Floor Market | 2026-2036
Mezzanine Floor Market Size, Share, and Industry Trends Forecast 2026-2036
Mezzanine Floor Market Analysis
Market Context
The capital-intensity gap between integrated systems providers and regional fabricators is collapsing as prefabrication technology democratizes structural engineering capabilities. Daifuku Co., Ltd. leverages its automated material handling heritage to bundle mezzanine systems with conveyor infrastructure, capturing bundled procurement budgets. SSI Schaefer Group sustains engineering leadership through captive R&D in steel-deck fire ratings and seismic load distribution. Wildeck Inc. anchors its position in North American industrial corridors with rapid-install modular platforms that slash on-site labor hours.
Technical Definition and Segment Structure
A mezzanine floor is an intermediate elevated platform installed between main building floors, typically engineered from cold-formed steel sections with composite deck surfaces rated for uniform live loads between 3.5 and 12 kilonewtons per square meter, primarily to recover vertical cube in warehouses and manufacturing plants without expanding building footprints. Modular product types now lead volume shipments because their bolt-together column grids eliminate welding and accelerate permitting, while fixed installations retain share in heavy manufacturing where concentrated point loads exceed modular ratings. Steel dominates material selection for fire resistance and column spacing flexibility, though aluminum gains traction in cleanroom and exhibition center applications where weight reduction eases foundation retrofit constraints.
Regulatory Environment and Outlook
Building regulators in the United States enforce OSHA walking-working surface standards and IBC live-load requirements that dictate mezzanine guardrail heights and stair geometries, while the EU's CE marking and national Eurocode implementations govern steel fabrication tolerances and seismic performance classes across member states. Japan's METI-administered Building Standard Law imposes additional horizontal force coefficients that shape structural bracing designs for warehouse mezzanines in earthquake zones. Stakeholders must monitor evolving fire compartmentalization rules and automated storage integration codes that increasingly treat mezzanine-integrated robotics as unified structural systems rather than separate permitting streams.
Market Dynamics
E-commerce fulfillment networks are compressing installation timelines for modular steel platforms as warehouse operators race to activate vertical cube ahead of peak retail seasons. This velocity imperative is restructuring procurement relationships between systems integrators and regional fabricators.
Growth Catalysts
- OSHA Walking-Working Surface Standards:Updated US safety mandates for elevated platforms are accelerating replacement cycles in aging distribution facilities across the American Midwest.
- Automated Storage and Retrieval Systems:ASRS integration requirements are pulling mezzanine specifications toward standardized column grids that accommodate robotic rack interfaces.
- Yangtze River Delta Industrial Cluster:Concentrated warehouse construction in this Chinese logistics corridor is generating concentrated demand for fire-rated steel decking systems.
Market Restraints
- Hot-Rolled Steel Price Volatility:Input cost swings for structural sections compress margin predictability for fabricators serving project-based contracts.
- Foundation Retrofit Requirements:Existing slab capacity limitations in older industrial buildings block mezzanine expansion in secondary logistics markets.
- Fixed Installation Substitution:Heavy manufacturing retains welded structural platforms where concentrated point loads exceed modular system ratings.
Strategic Opportunities
- India Warehousing PLI Scheme:Government incentives for cold chain and logistics infrastructure are opening greenfield installation opportunities in Gujarat and Maharashtra.
- Aluminum-Cleanroom Convergence:Lightweight alloy platforms are penetrating pharmaceutical and semiconductor cleanroom applications where seismic load reduction matters.
- Conveyor-Mezzanine Bundling:Material handling integrators are capturing bundled capital budgets by specifying unified elevated platform and transport systems.
Industry Challenges
- Seismic Engineering Talent Scarcity:Qualified structural engineers capable of earthquake-zone bracing design remain concentrated in Japan and the US West Coast.
- Permitting Timeline Compression:Accelerated warehouse activation schedules clash with municipal fire compartmentalization review cycles in dense industrial districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mezzanine Floor Market |
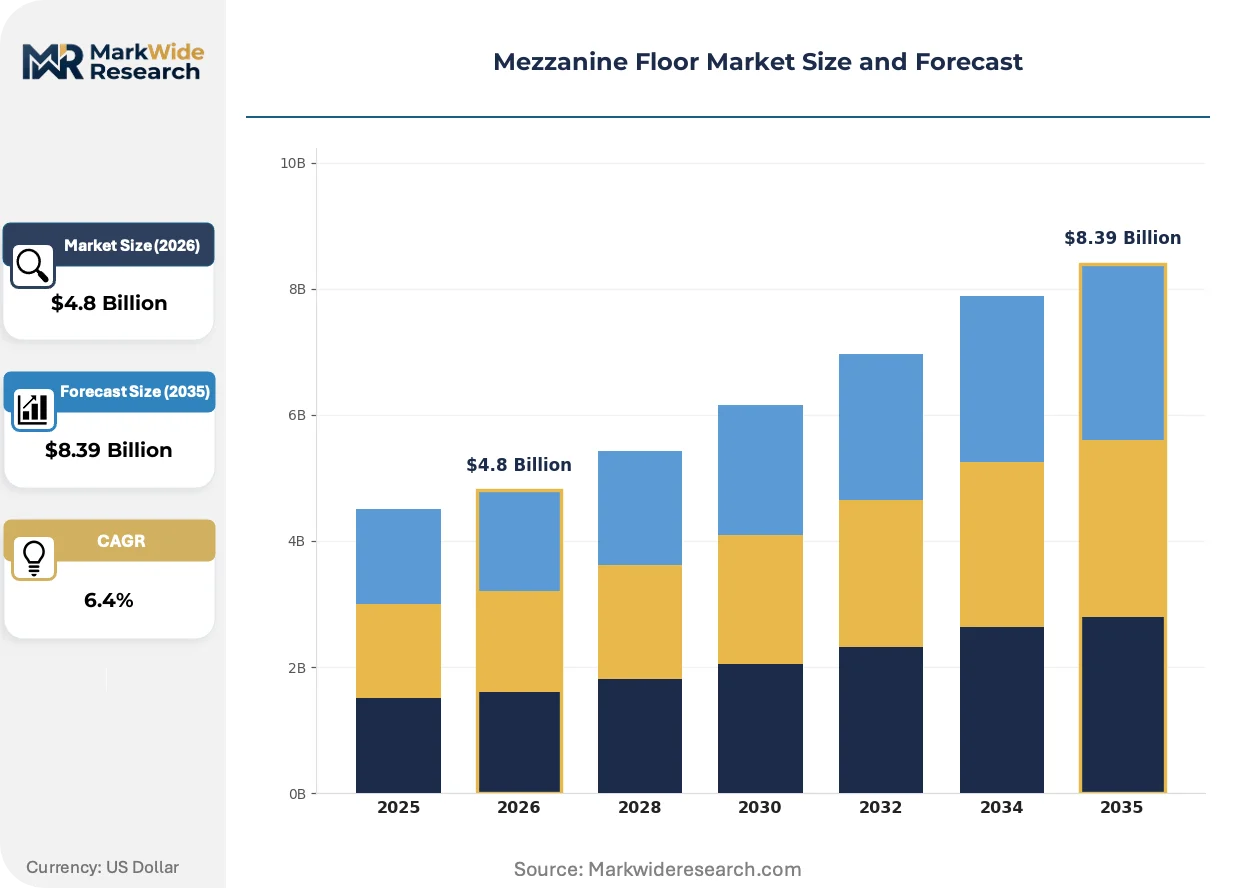
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Fixed, Portable, Custom Material: Steel, Aluminum, Wood, Composite End User: Retailers, Warehouses, Manufacturing Facilities, Exhibition Centers Installation Type: Indoor, Outdoor, Temporary, Permanent |
| Companies Covered | Jungheinrich AG, Stow International, Daifuku Co., Ltd., Wildeck Inc., Gonvarri Material Handling, MiTek Mezzanine Systems, Inc., SSI Schaefer Group, Avanta UK, Mecalux, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mezzanine Floor Market Emerging Trajectories
Prefabrication technology is dissolving traditional boundaries between structural engineering and material handling integration. Three active developments are reshaping how elevated platforms are specified, fabricated, and deployed.
Cold-formed steel composite decking is fragmenting legacy welded-platform supply chains by enabling bolt-together installation without certified welders. Third-party logistics operators in the American Midwest and China's Yangtze Delta are specifying these systems for 72-hour activation timelines. The technology is fragmenting regional fabricator market share by democratizing structural engineering capabilities previously captive to integrated systems houses.
Germany's KBA-influenced building code interpretations for automated warehouse structures are tightening fire rating requirements for steel-deck mezzanines integrated with robotic storage. Industrial insurers are conditioning coverage on demonstrated compliance with these evolving standards. Distribution hub developers in the Rotterdam-Antwerp corridor are front-loading structural engineering budgets to preempt certification delays.
Buyer consolidation among omnichannel retailers is compressing vendor qualification cycles and privileging fabricators with multi-site deployment capabilities. Regional mezzanine specialists are losing access to national procurement panels as e-commerce fulfillment operators centralize supplier relationships. This concentration is most visible in automated distribution hub construction across Germany, the Netherlands, and Belgium.
Mezzanine Floor Market Segmentation
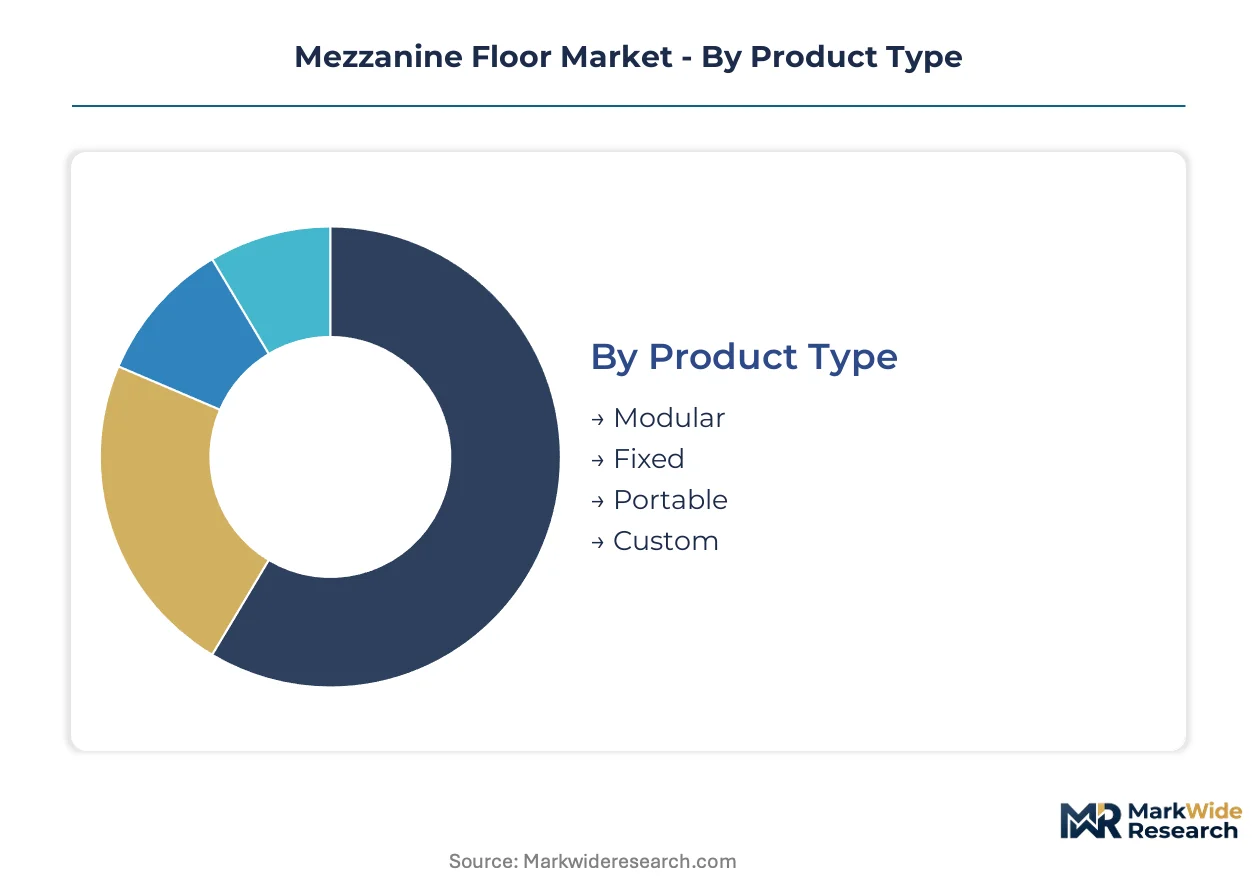
Mezzanine floor procurement patterns diverge sharply across product architectures and material specifications. Understanding these segment boundaries clarifies where modular systems displace legacy welded platforms and which material choices unlock permitting advantages in seismic zones.
Product Type:
Fixed installations face the most acute substitution pressure as bolt-together modular systems capture accelerated warehouse activation timelines and simplify municipal permitting.
- Modular:Cold-formed steel column grids with composite decking enable installation without certified welders. E-commerce fulfillment operators in the American Midwest specify these systems for 72-hour activation ahead of peak retail seasons.
- Fixed:Welded structural platforms engineered for concentrated point loads exceeding modular ratings. Heavy manufacturing facilities in Germany's industrial corridor retain this specification where robotic equipment imposes non-uniform loading patterns.
- Portable:Lightweight aluminum-framed units with caster-mounted columns for rapid repositioning. Exhibition centers in Japan deploy these for seasonal trade show configurations under METI-administered temporary structure guidelines.
- Custom:Engineered-to-order platforms integrating conveyor infrastructure and automated storage interfaces. Distribution hub developers in the Rotterdam-Antwerp corridor commission these for unified material handling systems.
Modular systems anchor the volume base while Custom configurations gain share at the steepest rate as ASRS integration requirements proliferate.
Material:
Cost tier positioning separates commodity structural inputs from premium lightweight alloys that command foundation retrofit savings.
- Steel:Hot-rolled and cold-formed sections dominate fire-rated applications with column spacing flexibility. China's Yangtze River Delta warehouse cluster consumes steel decking systems certified to EU Eurocode seismic performance classes.
- Aluminum:Extruded alloy platforms reduce foundation loads by 60% versus steel equivalents. Semiconductor cleanrooms in Japan and pharmaceutical facilities in Switzerland specify these for seismic load mitigation.
- Wood:Laminated timber decking with steel reinforcement for aesthetic and acoustic applications. Exhibition centers in Belgium deploy these for temporary cultural installations under KBA-influenced fire compartmentalization rules.
- Composite:Fiber-reinforced polymer panels with steel substructures for corrosive environments. Chemical processing facilities in the US Gulf Coast specify these for OSHA-compliant elevated work surfaces.
Steel retains the installed base while Aluminum expands most quickly in cleanroom and seismic-sensitive applications.
End User:
Application maturity varies dramatically, with automated logistics driving specification innovation while legacy manufacturing lags in platform modernization.
- Retailers:Omnichannel fulfillment networks compress installation timelines for back-of-store mezzanines. National procurement panels in the United States now require multi-site deployment capabilities from qualified vendors.
- Warehouses:Third-party logistics operators seek vertical cube recovery without footprint expansion. India's Gujarat and Maharashtra cold chain hubs under the PLI scheme generate concentrated greenfield demand.
- Manufacturing Facilities:Heavy industrial platforms face slower replacement cycles due to production continuity constraints. OSHA walking-working surface mandates are accelerating upgrades in aging American Midwest distribution facilities.
- Exhibition Centers:Temporary and reconfigurable platforms prioritize rapid assembly and aesthetic integration. Rotterdam convention venues specify aluminum systems for seasonal load variations.
Warehouses anchor the volume base while Retailers gain share at the steepest rate as e-commerce fulfillment networks expand.
Installation Type:
Customer type stratification separates permanent capital investments from temporary deployments with diverging engineering and permitting requirements.
- Indoor:Climate-controlled environments enable standardized fire-rated steel decking. German automated warehouse developers front-load structural engineering budgets to preempt KBA certification delays.
- Outdoor:Weather-resistant coatings and drainage-integrated platforms for yard storage expansion. US Gulf Coast logistics operators specify hot-dip galvanized systems under OSHA exposure standards.
- Temporary:Rapid-assembly units with simplified foundation anchoring for event and seasonal applications. Japan's Building Standard Law imposes horizontal force coefficients that shape bracing designs for earthquake-zone temporary structures.
- Permanent:Engineered foundations with integrated fire suppression and seismic bracing. Belgium's distribution corridor developers specify these for robotic storage integration under evolving EU automated warehouse codes.
Indoor installations anchor the volume base while Temporary configurations gain share at the steepest rate as event and seasonal logistics models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in mezzanine floor systems tilt toward import dependence in rapidly industrializing markets while established manufacturing bases sustain equipment export surpluses. Capital equipment shipments track warehouse construction cycles with pronounced regional lag effects.
United States
E-commerce fulfillment networks in the American Midwest drive specification demand for rapid-install modular platforms. OSHA walking-working surface standards mandate guardrail heights and stair geometries that accelerate replacement cycles in aging distribution facilities. Chicago and Detroit industrial corridors concentrate procurement for automated distribution hubs.
Germany
Automated warehouse developers front-load structural engineering budgets to preempt KBA-influenced certification delays for fire-rated steel decking. EU Eurocode implementations govern fabrication tolerances and seismic performance classes for cross-border equipment shipments. The industrial corridor between Rotterdam and Antwerp channels specification influence into German distribution hub construction.
China
Yangtze River Delta warehouse clusters generate concentrated demand for steel decking systems certified to international seismic performance standards. GB standards administered by SAMR shape domestic fabrication requirements while export-oriented producers target Eurocode compliance. Shanghai and Suzhou logistics hubs anchor procurement volume for cold chain infrastructure.
Japan
METI-administered Building Standard Law imposes horizontal force coefficients that shape structural bracing designs for warehouse mezzanines in earthquake zones. Semiconductor cleanrooms and pharmaceutical facilities specify aluminum platforms for seismic load mitigation. Kanto and Kansai industrial regions concentrate demand for lightweight alloy systems.
India
PLI scheme incentives for cold chain and logistics infrastructure open greenfield installation opportunities in Gujarat and Maharashtra. BIS certification requirements shape domestic procurement specifications for fire-rated elevated platforms. Mumbai and Ahmedabad warehouse corridors anchor initial deployment clusters for automated storage integration.
Mezzanine Floor Market Vendor Landscape
Concentration sits with integrated systems houses that bundle mezzanine platforms with material handling infrastructure. Regional fabricators retain project-based share in heavy manufacturing applications where welded structural platforms exceed modular ratings. Two strategic archetypes dominate: automated material handling specialists with captive engineering capabilities, and steel fabrication houses with rapid-install modular product lines. Competitive moves center on conveyor-mezzanine bundling to capture unified capital budgets, and geographic expansion through distributor partnerships in emerging warehouse markets.
Within the integrated systems tier, Daifuku Co., Ltd. and SSI Schaefer Group exemplify archetypes that leverage automated material handling heritage to specify unified elevated platform and transport systems. Wildeck Inc. anchors North American positioning for rapid-install modular platforms. Among European fabricators, Mecalux, S.A. and Stow International occupy positions serving automated distribution hub developers in the Rotterdam-Antwerp corridor. Jungheinrich AG represents the material handling equipment convergence archetype with structural platform bundling capabilities.
| Leading Market Players |
|---|
| Jungheinrich AG |
| Stow International |
| Daifuku Co., Ltd. |
| Wildeck Inc. |
| Gonvarri Material Handling |
| MiTek Mezzanine Systems, Inc. |
| SSI Schaefer Group |
| Avanta UK |
| Mecalux, S.A. |
| Others |
Supply Flow & Price Mechanics
OSHA walking-working surface certification gates vendor qualification and price differentiation simultaneously, as fabricators without demonstrated compliance lose access to national procurement panels while certified suppliers command project premiums for rapid-permitting modular systems.
Pricing Analysis
The customization-premium spread separates configured-to-order pricing from standard modular platforms by 35-50 percent. Project-based pricing dominates as e-commerce fulfillment operators bundle mezzanine specifications with conveyor infrastructure. Price differentiation hinges on seismic engineering certification and fire-rating tier, with EU Eurocode-compliant systems commanding foundation retrofit savings. Cost compression in standard steel decking is intensifying because hot-rolled steel price volatility compresses fabricator margins. Third-party logistics operators show highest price sensitivity, while semiconductor cleanroom buyers prioritize seismic load mitigation over unit economics.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Rotterdam have reshaped sourcing patterns for cold-formed steel sections. Supply concentrates in China, Germany, and the United States for structural steel fabrication. Raw material dependencies center on hot-rolled steel coils, zinc galvanizing inputs, and composite deck surfacing. Single-source vulnerability runs through Yangtze River Delta steel mills for Eurocode-certified sections. Distribution runs through systems integrators with captive installation crews rather than independent fabricator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a cyclical trough as warehouse construction accelerates across automated logistics corridors. E-commerce fulfillment network expansion provides the cyclical justification.
For Market Incumbents: Consolidate engineering talent pools in seismic zones to preempt capability scarcity as Japan's METI and US West Coast jurisdictions tighten bracing requirements. Acquire regional fabricators in Gujarat and Maharashtra to capture PLI scheme cold chain deployments. Vertical integration into composite deck manufacturing insulates margin position from steel price volatility.
For New Entrants and Emerging Players: CE marking fast-track programs unlock access to Rotterdam-Antwerp corridor procurement panels ahead of established competitors. Target aluminum cleanroom platforms in Swiss pharmaceutical facilities where seismic load reduction commands premium positioning. Pursue distributor partnerships with material handling integrators rather than direct end-user sales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular prefabrication as bolt-together technology democratizes structural engineering. Five-to-ten year viability favors integrated systems houses with bundled conveyor-mezzanine capabilities. Watch for consolidation signals when regional fabricator margins compress below sustainable thresholds under steel price pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Engineering Certification Investment | METI and OSHA compliance unlocks Japan and US West Coast procurement panels. |
| Backward Integration into Cold-Formed Steel | In-house coil processing insulates margins from hot-rolled price volatility. |
| Conveyor-Mezzanine System Bundling | Unified capital budgets capture procurement centralization among omnichannel retailers. |
| Aluminum Cleanroom Platform Development | Swiss pharmaceutical and Japanese semiconductor demand commands foundation retrofit premiums. |
| India PLI Scheme Market Entry | Gujarat and Maharashtra cold chain incentives open greenfield installation opportunities. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with warehouse operators, structural engineers, and material handling procurement directors, and secondary validation against customs trade records, EU Eurocode implementation documents, and OSHA regulatory filings. Bottom-up triangulation across fabricator shipment data and top-down reconciliation against warehouse construction permits anchored volume estimates.
Across the analysis window, forecasts model product type, material specification, end-user vertical, and installation permanence dimensions. CAGRs derive from regression analysis of historical warehouse activation timelines against e-commerce fulfillment network expansion. Industry-specific inputs include seismic coefficient requirements under Japan's Building Standard Law and fire compartmentalization rules from Germany's KBA.
Decision-makers should treat outputs as directional under assumptions of sustained e-commerce logistics investment and stable steel input costs; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Kuwait Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Qatar Construction Market
Building Construction
Energy-Efficient Building Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Ireland Data Center Construction Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Thailand Construction Market
Building Construction
Africa Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
Global Dry Construction Market
Building Construction
GCC Cement Market
Building Construction
Turkey Commercial Construction Market
Building Construction
India Pre-Engineered Buildings Market