
 China Building Construction Market | 2026-2036
China Building Construction Market Size, Share, and Industry Trends Forecast 2026-2036
China Building Construction Market Insights
The gap between premium certified structures and commodity-grade developments is recalibrating procurement patterns across China's building sector. China State Construction Engineering Corporation leverages its state-backed project pipeline to dominate mega-infrastructure bids. China Railway Construction Corporation anchors its position through vertical integration into rail-adjacent urban complexes. Shanghai Construction Group differentiates via specialization in high-rise commercial towers along the eastern seaboard.
Building construction encompasses the assembly of enclosed structures using concrete, steel, wood, or glass systems designed to provide habitable space with specified load-bearing capacity and environmental performance. The process spans foundation work, structural framing, envelope installation, and MEP integration to deliver functional real estate assets for occupancy or industrial operations. Residential buildings command the deepest volume pool, though green building methods attract the fastest policy tailwind from municipal sustainability mandates. Infrastructure projects sustain the most predictable government-funded workflow, while modular construction methods unlock labor-cost arbitrage in tier-two city expansions.
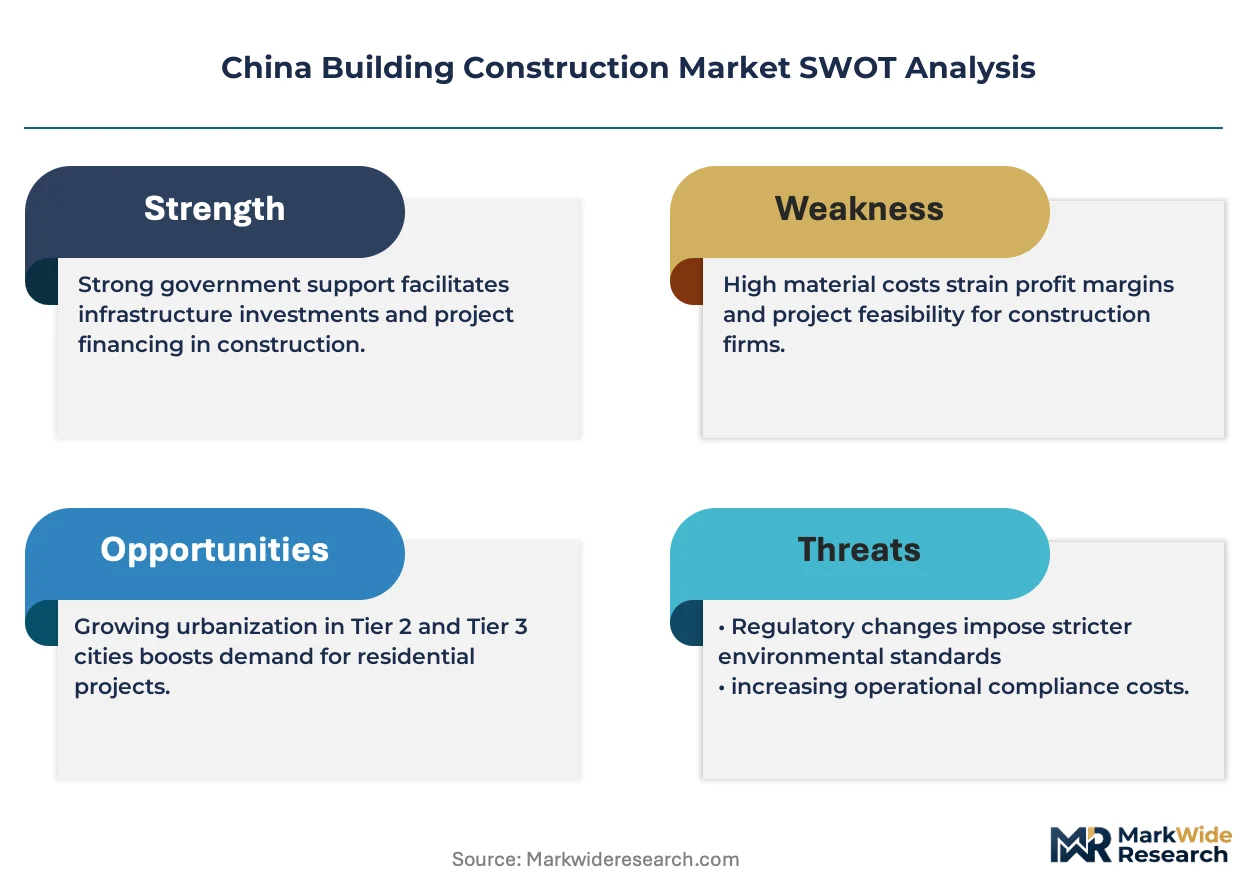
MIIT's GB standards framework and MEE's dual carbon enforcement reshape material specifications and energy-performance thresholds for new developments nationwide. The country's national construction regulator mandates seismic-grade compliance in western provinces, tightening technical barriers for unqualified contractors. Stakeholders must monitor how local government financing vehicles restructure debt exposure and redirect public project pipelines.
Market Dynamics
Beijing's dual carbon enforcement through MIIT's GB standards framework is compressing project timelines while elevating material certification requirements across all new developments.
Growth Catalysts
- Dual carbon goals:MEE enforcement tightens energy-performance thresholds, mandating low-carbon concrete and recycled steel in municipal projects.
- Smart city infrastructure:IoT-integrated transit hubs in the Greater Bay Area corridor drive demand for intelligent building management systems.
- Seismic-grade compliance:Western provinces face upgraded technical barriers that filter out unqualified contractors and concentrate contracts with certified builders.
Market Restraints
- Steel and cement price volatility:Input cost swings compress margins for fixed-price contractors locked into legacy municipal contracts.
- Local government financing vehicle debt:Restructuring of LGFV obligations delays public project pipelines and extends payment cycles.
- Labor substitution limits:Modular methods face site-integration bottlenecks that prevent full displacement of conventional on-site crews.
Strategic Opportunities
- Dongguan manufacturing belt:Industrial facility upgrades present captive demand for high-specification warehouse and R&D campus construction.
- Green building certification:Three-star ratings unlock preferential land auctions and subsidized financing in Shenzhen and Guangzhou.
- Prefabrication + BIM convergence:Factory-produced structural elements paired with digital twin modeling compress build cycles by 30-40% in tier-two city expansions.
Industry Challenges
- Skilled MEP integration specialists:Shortage of technicians qualified for smart building system commissioning creates project bottlenecks.
- Legacy concrete supply chains:Retooling batch plants for low-carbon mixes requires capital outlays that strain mid-tier contractors.
- Cross-provincial certification reciprocity:Non-uniform recognition of contractor licenses between Guangdong and inland provinces fragments bidding mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Building Construction Market |
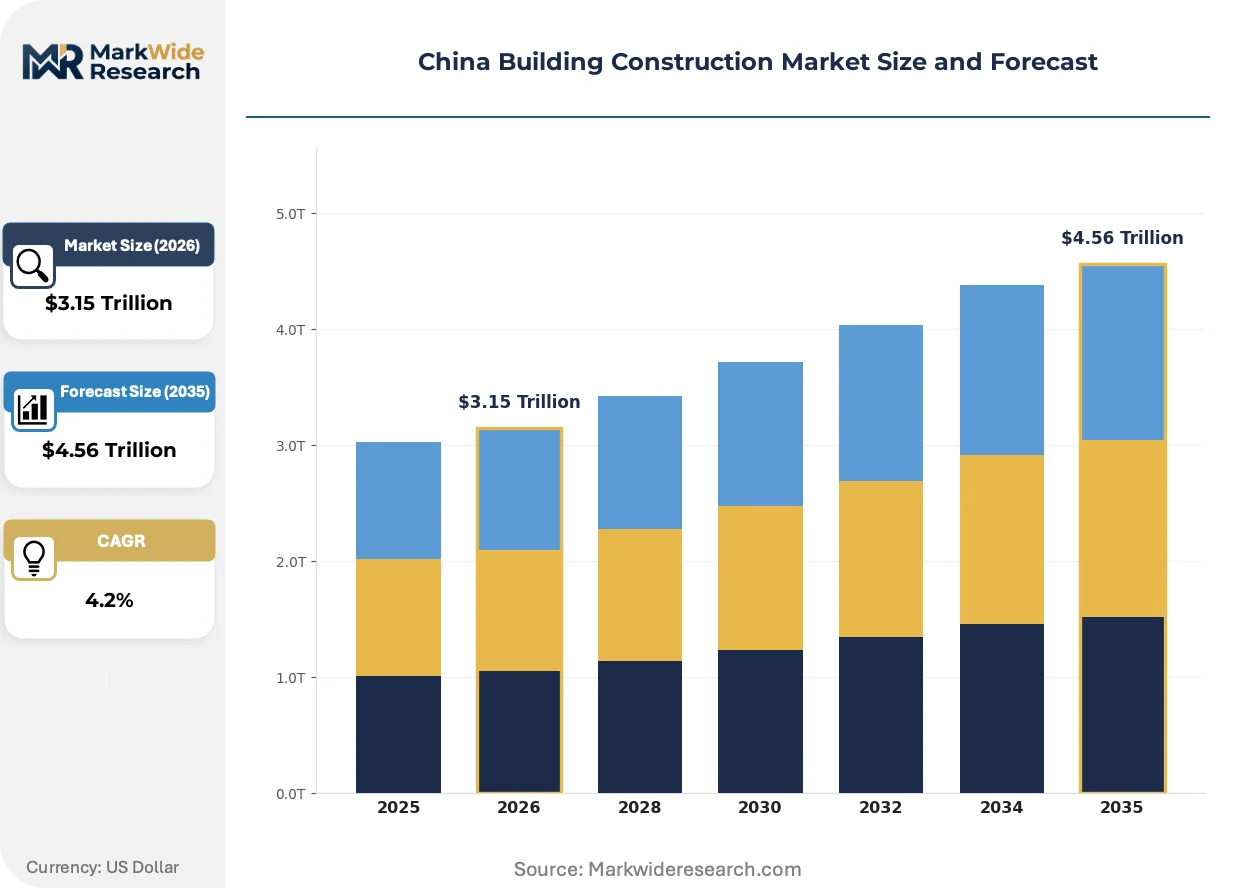
| Market Size in 2026 | $3.15 Trillion |
| Market Size in 2035 | $4.56 Trillion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Buildings, Commercial Buildings, Industrial Facilities, Infrastructure Projects Material: Concrete, Steel, Wood, Glass End User: Government, Private Developers, Corporations, Non-Profit Organizations Construction Method: Traditional, Modular, Precast, Green Building |
| Companies Covered | China State Construction Engineering Corporation, China Railway Group, China Railway Construction Corporation, China Communications Construction Company, Power Construction Corporation of China, China Metallurgical Group, Shanghai Construction Group, Shaanxi Construction Engineering Group Corporation, Beijing Urban Construction Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Building Construction Market Trends and Innovations
Digital fabrication methods and policy-mandated carbon accounting are converging to reshape how structures are designed, sourced, and delivered across China's eastern seaboard and inland corridors.
Modular prefabrication is decentralizing construction activity from centralized urban cores to factory hubs in tier-two cities. Real estate developers in the Greater Bay Area are adopting volumetric modules for residential towers to compress on-site labor requirements. This shift is decentralizing project risk profiles away from dense metropolitan labor pools toward controlled manufacturing environments with predictable output quality.
MIIT's updated GB standards for embodied carbon in building materials are forcing recalibration of procurement specifications nationwide. The framework mandates lifecycle carbon disclosure for structural steel and concrete, elevating certified low-carbon suppliers in municipal bid scoring. High-rise commercial towers in Shanghai and Beijing face the steepest compliance ramps, with developers accelerating partnerships with recycled-material suppliers to maintain bid competitiveness.
Buyers are consolidating vendor relationships around full-service design-build contracts that bundle architecture, engineering, and construction under single accountability. Municipal transit authorities in Guangzhou and Shenzhen are abandoning fragmented multi-contractor models in favor of integrated delivery for metro-adjacent mixed-use complexes. This concentration is most visible in the Pearl River Delta, where compressed project timelines favor contractors with captive design capabilities and in-house MEP engineering teams.
China Building Construction Market Segmentation
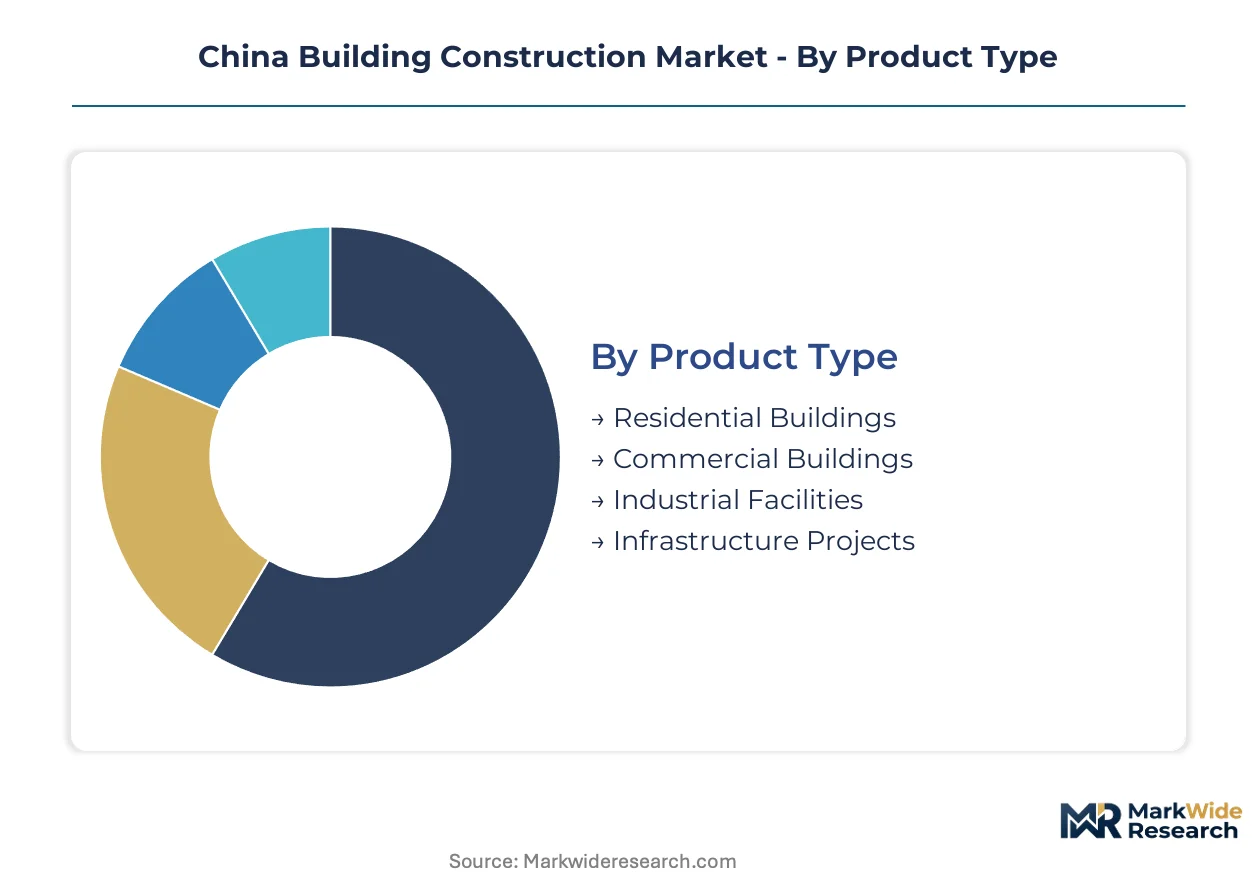
China's building construction market fragments across four critical dimensions that determine procurement patterns, regulatory exposure, and margin structures. Product type and construction method classifications increasingly overlap as MIIT's dual carbon mandates reshape material specifications and delivery models.
Product Type:
Structural purpose and occupancy classification define engineering standards, financing mechanisms, and municipal approval pathways across China's development pipeline.
- Residential Buildings:High-rise towers and mid-density compounds dominate volume, with prefabrication penetration accelerating in tier-two city expansions to offset labor shortages. Demand concentrates in the Greater Bay Area corridor where Guangzhou and Shenzhen municipal authorities fast-track permits for modular residential projects.
- Commercial Buildings:Office towers and retail complexes face the steepest embodied carbon compliance ramps under MIIT's updated GB standards, forcing developers toward recycled steel and low-carbon concrete specifications. Shanghai's Lujiazui financial district anchors premium-grade demand for intelligent building management integration.
- Industrial Facilities:Manufacturing plants and logistics warehouses in Dongguan's belt drive specification-grade concrete demand for heavy-load flooring systems.
- Infrastructure Projects:Rail-adjacent urban complexes and municipal transit hubs sustain predictable government-funded workflow through state-backed financing vehicles.
Residential buildings lead on scale; commercial buildings lead on momentum as green certification requirements intensify.
Material:
Supply chain configuration and embodied carbon accounting now dominate material selection criteria across all project categories.
- Concrete:The dominant structural medium faces forced retooling as MEE enforcement mandates low-carbon mix designs and lifecycle disclosure. Batch plant upgrades in Hebei and Shandong provinces concentrate supply for Beijing-Tianjin megaprojects.
- Steel:Structural framing and reinforcement applications pivot toward electric-arc furnace recycled content to meet municipal bid scoring preferences in Shenzhen and Guangzhou.
- Wood:Cross-laminated timber gains traction in low-rise commercial and institutional projects seeking carbon-sequestration credentials.
- Glass:High-performance curtain wall specifications expand in high-rise commercial towers across Shanghai's eastern seaboard corridor.
Concrete maintains volume dominance; steel commands the steepest specification upgrades as carbon accounting tightens.
End User:
Capital source and risk tolerance shape project timelines, contractor selection, and technology adoption rates.
- Government:Municipal transit authorities and provincial development agencies sustain infrastructure workflow through LGFV-financed pipelines, though debt restructuring delays payment cycles.
- Private Developers:Real estate firms in the Pearl River Delta accelerate design-build consolidation to compress timelines and transfer accountability.
- Corporations:Industrial facility owners in Dongguan's manufacturing belt drive captive demand for high-specification R&D campus construction.
- Non-Profit Organizations:Institutional and educational builders prioritize green building certification for subsidized financing access.
Government channels anchor predictable volume; private developers are expanding most quickly through integrated delivery models.
Construction Method:
Factory-based production and digital integration are displacing conventional on-site assembly across China's tier-two city expansion zones.
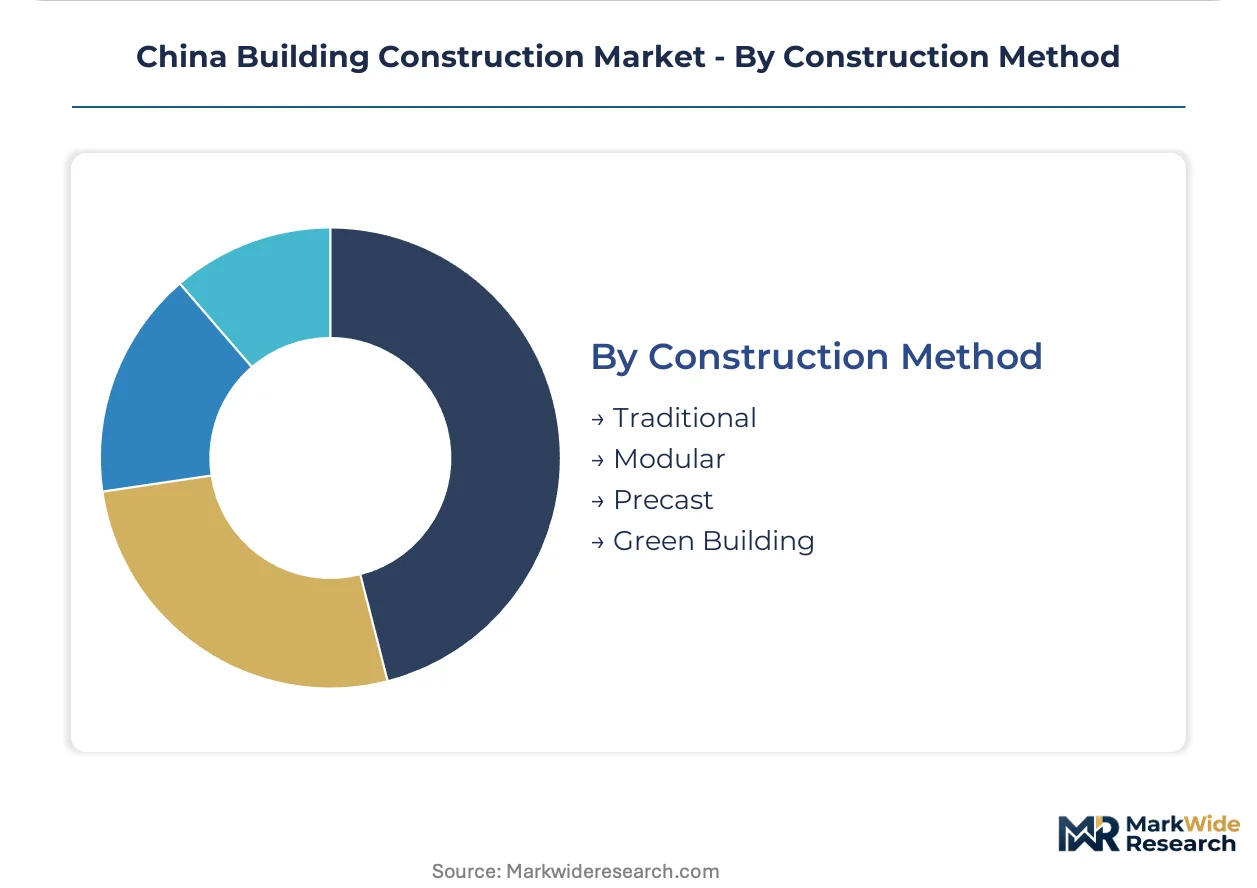
- Traditional:Cast-in-place concrete and stick-built framing retain dominance in western provinces where seismic-grade compliance requirements filter contractor pools. Sichuan and Yunnan markets sustain conventional methods due to transportation constraints on prefabricated modules.
- Modular:Volumetric construction decentralizes project risk from urban labor pools to controlled manufacturing environments in Foshan and Zhongshan factory hubs. Residential towers in Shenzhen adopt modular units to compress on-site crew requirements.
- Precast:Factory-produced structural elements paired with BIM modeling compress build cycles in Guangzhou's transit-adjacent developments.
- Green Building:Three-star certification unlocks preferential land auctions and subsidized financing across the Greater Bay Area corridor.
Traditional methods retain volume leadership; modular construction gains share fastest as labor costs rise and factory integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled construction labor concentrates in China's coastal megacities, anchoring the industry's geographic distribution. Provincial development strategies and municipal financing capacity determine project pipeline intensity across sub-regional markets.
Yangtze River Delta
Shanghai's high-rise commercial tower pipeline and Suzhou's advanced manufacturing campuses drive specification-grade demand. MIIT's GB standards enforcement elevates material certification requirements for new developments. The corridor's prefabrication hubs in Nantong and Changzhou supply modular components to compress build cycles.
Pearl River Delta
Guangzhou's transit-adjacent mixed-use complexes and Shenzhen's intelligent building mandates attract integrated design-build contractors. Green building certification unlocks preferential land auctions across municipal jurisdictions. Dongguan's manufacturing belt generates captive demand for high-specification industrial facilities.
Beijing-Tianjin-Hebei
Seismic-grade compliance requirements in Hebei province filter contractor pools toward certified builders. MEE's dual carbon enforcement tightens low-carbon concrete specifications for municipal projects. Xiong'an New Area's planned infrastructure sustains state-backed project pipelines.
Sichuan-Chongqing
Western province seismic codes sustain conventional cast-in-place methods due to transportation constraints on prefabricated modules. Chongqing's rail-adjacent urban complexes anchor infrastructure investment flows. Chengdu's technology campus expansions drive R&D facility construction demand.
Shandong Peninsula
Batch plant retooling for low-carbon mix designs concentrates supply capacity for northern megaprojects. Qingdao's port-adjacent logistics warehouses specification-grade concrete demand. Jinan's municipal transit authority pipelines sustain predictable government-funded workflow.
China Building Construction Market Competitive Landscape
Top-tier vendors anchor state-backed mega-infrastructure bids, while mid-tier specialists compete for municipal and commercial contracts. The market structure concentrates around state-owned enterprises with captive project pipelines and regional construction groups with specialized geographic footprints. Three archetypes dominate: nationwide infrastructure conglomerates, regional commercial tower specialists, and provincial contractors with seismic-grade certifications. Competitive positioning hinges on backward integration into material supply and design-build consolidation to compress accountability chains.
Within the state-owned enterprise tier, China State Construction Engineering Corporation and China Railway Construction Corporation exemplify scale-driven market presence. Shanghai Construction Group occupies a position among regional specialists concentrated along the eastern seaboard. These three entities represent the competitive spectrum from nationwide infrastructure dominance to geographic specialization.
| Leading Market Players |
|---|
| China State Construction Engineering Corporation |
| China Railway Group |
| China Railway Construction Corporation |
| China Communications Construction Company |
| Power Construction Corporation of China |
| China Metallurgical Group |
| Shanghai Construction Group |
| Shaanxi Construction Engineering Group Corporation |
| Beijing Urban Construction Group |
| Others |
Pricing and Supply Chain Analysis
MIIT's GB standards enforcement for embodied carbon disclosure is forcing procurement officers toward certified low-carbon concrete and recycled steel suppliers, compressing margins for uncertified batch plants while elevating bid premiums for compliant material streams.
Pricing Analysis
The bundled-vs-unbundled service split separates design-build integrators from fragmented multi-contractor arrangements. Pricing stratifies across premium three-star green certification, standard municipal compliance grade, and economy commodity-grade tiers. Cost compression in the economy tier is intensifying because legacy concrete suppliers face forced capital outlays for low-carbon retooling. Government transit authorities exhibit lowest price sensitivity due to state-backed financing, while mid-tier private developers in tier-two cities face acute margin pressure.
Supply Chain Analysis
Certification and qualification gating concentrates supply capacity among MIIT-registered batch plants in Hebei, Shandong, and Jiangsu provinces. The construction material network draws from limestone quarries in northern China, electric-arc furnace steel mills in eastern coastal zones, and timber plantations in southwestern provinces. Single-source vulnerability runs through the low-carbon concrete additive segment where qualified suppliers remain limited. Distribution runs through provincial construction material trading centers that aggregate certified product streams for municipal bid aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through prefabrication adoption that compresses on-site labor costs and unlocks premium-tier green certification pricing.
For Market Incumbents: Extend backward integration into modular component manufacturing in Foshan and Zhongshan factory hubs to capture value migrating from on-site assembly. Lock in long-term supply agreements with electric-arc furnace steel mills before recycled content bid scoring tightens further. Defend against emerging design-build specialists by consolidating architecture and MEP engineering capabilities under single accountability structures. For New Entrants and Emerging Players: Begin with seismic-grade certification acquisition in Sichuan and Yunnan provinces where transportation constraints filter prefabricated competition. Target the Dongguan manufacturing belt's industrial facility upgrade cycle for high-specification R&D campus construction. Pursue partnership entry with municipal transit authorities seeking integrated delivery for rail-adjacent mixed-use complexes. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier contractors possessing three-star green certification credentials and captive prefabrication capacity. Long-term viability hinges on positioning for sustained government infrastructure flows through LGFV restructuring cycles. Watch for inflection in provincial contractor license reciprocity agreements between Guangdong and inland provinces as signal of bidding mobility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Prefabrication Hub Expansion | Factory-produced structural elements paired with BIM modeling compress build cycles by 30-40% in tier-two city expansions. |
| Green Certification Investment | Three-star ratings unlock preferential land auctions and subsidized financing in Shenzhen and Guangzhou municipal jurisdictions. |
| Design-Build Consolidation | Integrated delivery bundles architecture, engineering, and construction under single accountability for compressed timelines. |
| Low-Carbon Material Partnership | Electric-arc furnace recycled steel and low-carbon concrete specifications meet MIIT's municipal bid scoring preferences. |
| Seismic-Grade Certification | Western province compliance requirements filter contractor pools toward certified builders in Sichuan and Chongqing markets. |
Research Methodology
Multiple input streams — primary interviews with construction project directors, procurement officers at municipal transit authorities, batch plant operations managers, and green building certification consultants — were reconciled against secondary validation from MIIT GB standards documentation, MEE enforcement circulars, provincial construction industry association reports, and municipal LGFV financing disclosures. Bottom-up project pipeline aggregation and top-down macroeconomic scenario triangulation anchored volume and value estimates.
Historical construction completion data was cross-referenced against panel input from industry stakeholders to calibrate segment-level trajectories across the projection horizon. The analytical framework modeled product type, material specification, end-user capital source, and construction method dimensions. CAGRs were derived from trend extrapolation adjusted for policy inflection points including dual carbon enforcement timelines and seismic code upgrade schedules.
Several conditions sit outside the modeled scope, including abrupt LGFV debt restructuring outcomes, steel and cement commodity price spikes, and cross-provincial license reciprocity breakthroughs. Forecasts reflect documented assumptions about policy enforcement continuity and infrastructure investment flows. A model refresh is warranted upon material change in MIIT's GB standards implementation pace or municipal financing vehicle liquidity conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
UAE Construction Market
Building Construction
Japan Construction Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Latin America Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Tanzania Construction Market
Building Construction
France Prefab Wood Building Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Guatemala Construction Market
Building Construction
France Prefab Homes Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Spain Prefabricated Buildings Market