
 Global Rail Infrastructure Market | 2026-2036
Global Rail Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rail Infrastructure Market Intelligence
The performance gap between advanced, digitally integrated signaling systems and conventional track materials is expanding. Siemens specializes in high-speed rail technologies and sophisticated Communication-Based Train Control systems for urban transit. CRRC Corporation leverages its manufacturing scale to dominate large infrastructure projects, particularly for national railways in emerging economies. In contrast, Wabtec Corporation focuses on freight modernization and Positive Train Control solutions that meet specific North American rail operator requirements.
Rail infrastructure encompasses the permanent, fixed assets required for railway operation, including track structures, electrification catenaries, and station facilities. These systems are engineered to precise specifications like standard track gauge (1,435 mm) and specific electrification voltages, such as 25 kV AC. High-margin opportunities are concentrating in advanced signaling systems and Communication-Based Train Control technology due to their software content. High-speed rail applications drive new construction, while freight carriers invest in upgrading existing tracks and bridges for higher axle loads.
The EU's Technical Specifications for Interoperability and the US Federal Railroad Administration's Positive Train Control mandate define critical safety and performance benchmarks. In parallel, China's national GB standards and India's PLI scheme for manufacturing influence component sourcing and network design. Future investment decisions for public transport authorities and freight operators hinge on balancing the capital cost of digital upgrades against the lifecycle maintenance of legacy assets.
Market Dynamics
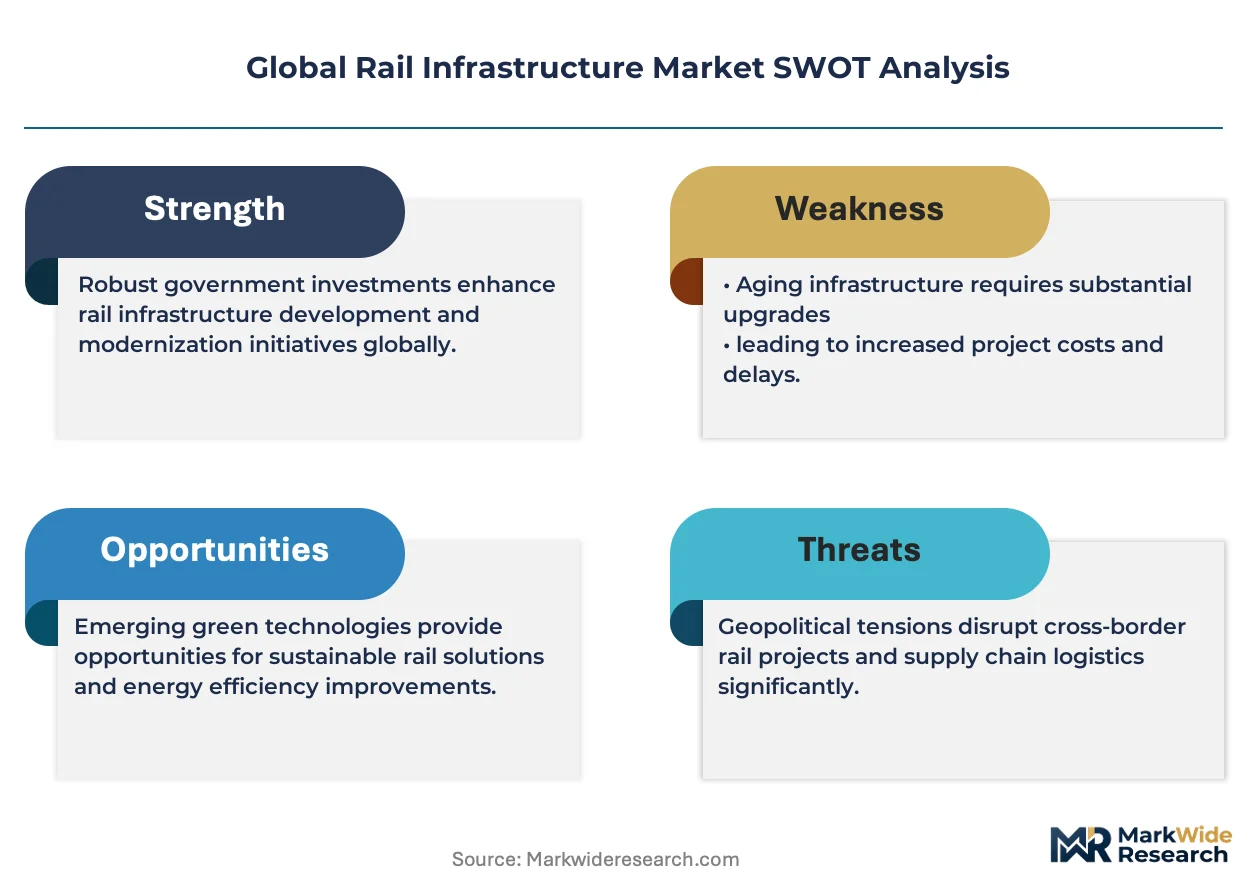
The central tension in the rail infrastructure market is the financial and operational conflict between deploying advanced digital control systems and managing the lifecycle costs of vast, aging physical track and civil structures. This defines investment priorities for both public and private operators.
Growth Catalysts
- High-Speed Rail Investment:National strategic initiatives, particularly in China and across the European Union, are driving new construction of dedicated high-speed lines, requiring advanced track, electrification, and signaling systems.
- Urban Transit Expansion:Rapid urbanization in India and Southeast Asian nations necessitates the development of new metro and light rail networks, creating sustained demand for urban-focused infrastructure like Communication-Based Train Control.
- Safety and Interoperability Mandates:Regulations such as the US Positive Train Control mandate and the EU's Technical Specifications for Interoperability compel operators to invest in modern signaling and control technologies to meet safety benchmarks.
Market Restraints
- High Capital Intensity:The substantial upfront investment required for new railway construction, including land acquisition, tunneling, and track laying, constrains the pace and scale of network expansion projects.
- Long Project Gestation Periods:Rail infrastructure projects are characterized by extended timelines for planning, regulatory approvals, and construction, which can span decades and expose projects to political and economic volatility.
- Legacy Asset Integration Costs:Integrating new digital signaling and control systems with existing, often decades-old, mechanical and electrical infrastructure presents significant technical challenges and financial burdens for operators.
Strategic Opportunities
- Predictive Maintenance Solutions:The deployment of sensor networks and software analytics to monitor asset health offers a high-margin opportunity to reduce lifecycle maintenance costs for track, bridges, and catenary systems.
- Brownfield Freight Modernization:Upgrading existing freight corridors in North America to support higher axle loads and double-stack container traffic presents a significant opportunity focused on structural reinforcement and track renewal.
- Component Manufacturing Incentives:Government policies, such as India's PLI scheme, create opportunities for establishing localized manufacturing of rail components, reducing supply chain dependency and improving cost-competitiveness.
Industry Challenges
- Digital Engineering Skills Gap:A shortage of technicians and engineers proficient in advanced software-based systems like CBTC and PTC hinders the effective deployment and maintenance of next-generation rail control networks.
- Divergent International Standards:Navigating conflicting technical requirements between the EU's TSIs, America's FRA regulations, and China's GB standards complicates global supply chain management and product design for component manufacturers.
- System Integration Complexity:Ensuring seamless interoperability between new digital signaling from one vendor and legacy electromechanical track components from another remains a primary operational hurdle for network operators during modernization projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rail Infrastructure Market |
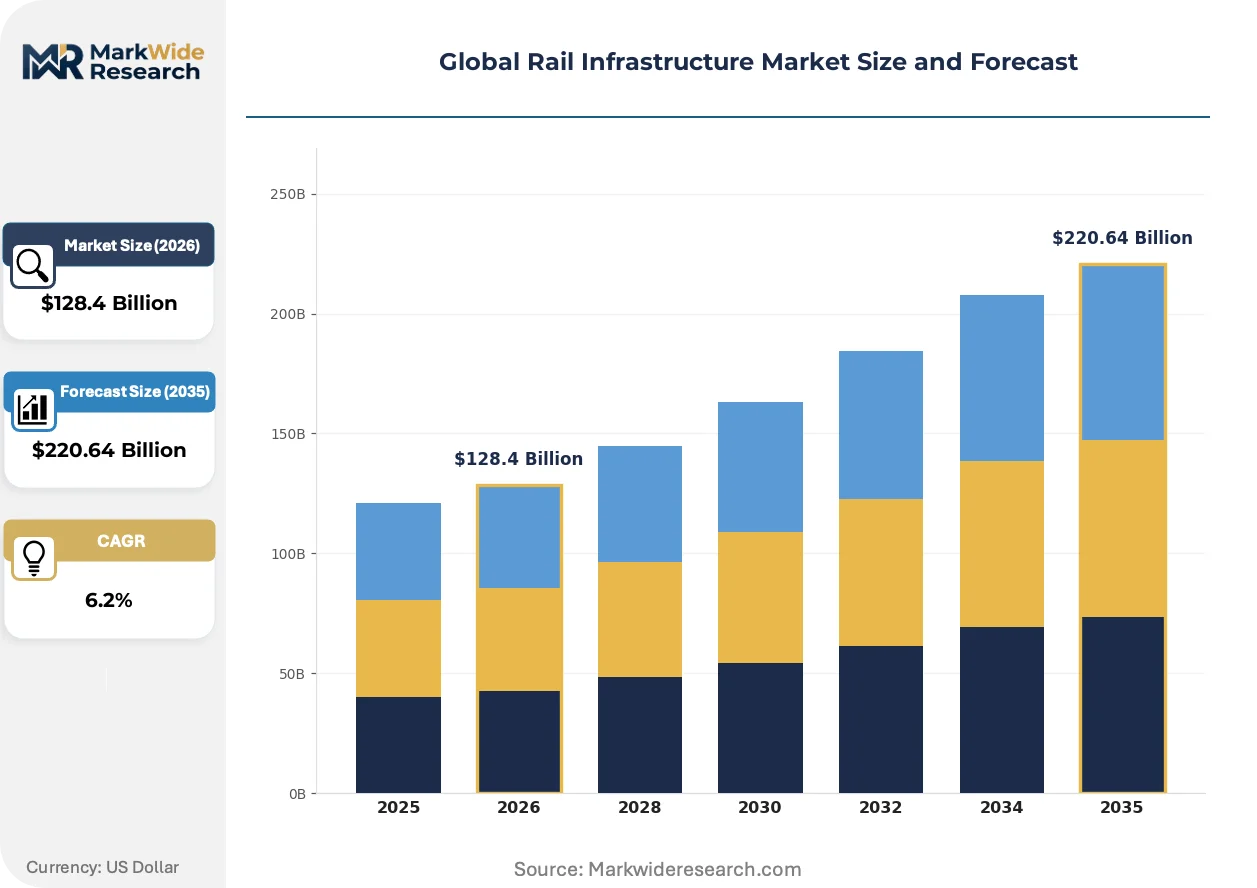
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $220.64 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tracks, Bridges, Signaling Systems, Stations, Electrification, Tunnels Technology: Automatic Train Control, Positive Train Control, Communication-Based Train Control, Wireless Sensor Networks, Fiber Optic Systems, SCADA Application: Passenger Transit, Freight Carriers, High-Speed Rail, Urban Transit Systems, Monorails, Light Rail End User: Public Transport Authorities, Freight Operators, Railway Contractors, Infrastructure Developers, Maintenance Companies, Leasing Firms |
| Companies Covered | Larsen & Toubro, Hyundai Rotem, Alstom, Wabtec Corporation, Bombardier Transportation, Siemens, Hitachi Rail, CAF (Construcciones y Auxiliar de Ferrocarriles), CRRC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rail Infrastructure Market Strategic Shifts & Innovations
Digitalization is transforming the market's focus from purely physical construction to software-defined operational efficiency. Investment is pivoting toward technologies that maximize the capacity, safety, and lifecycle value of both new and existing railway assets, creating new competitive dynamics among suppliers.
Communication-Based Train Control (CBTC) utilizes continuous, high-resolution wireless data exchange to manage train separation and speed, replacing traditional fixed-block trackside signals. Urban transit authorities are the primary adopters of CBTC to increase passenger throughput and operational flexibility on congested metro lines. This technology is rewriting the economics of network capacity, enabling operators to boost service frequency without the immense cost of laying new track.
The European Union's Technical Specifications for Interoperability (TSIs) create a standardized regulatory framework for all new and upgraded rail lines within the bloc. This policy compels manufacturers to design components, particularly for signaling and control systems, that are compatible across different national networks. The segment most affected is train control, where compliance with the European Rail Traffic Management System (ERTMS) is now a prerequisite for market access.
Public transport authorities and freight carriers are increasingly prioritizing total cost of ownership, which includes long-term maintenance, over the initial capital cost of infrastructure. This behavioral shift favors suppliers that bundle digital monitoring and predictive analytics services with the sale of physical components like track and switches. This trend is most visible in mature North American and European markets, where optimizing the performance of legacy assets is paramount.
Global Rail Infrastructure Market Segmentation
Understanding the Global Rail Infrastructure Market through segmentation reveals distinct investment patterns and technological priorities. This detailed analysis highlights where capital flows, which technologies are gaining traction, and the specific needs of various end-user groups, shaping competitive strategies across the industry.
Product Type:
Supply concentration for rail infrastructure product types primarily centers on core physical assets and advanced control systems.
- Tracks:These fundamental permanent way structures, including rails, sleepers, and ballast, form the backbone of all railway networks. Demand is concentrating in major national railway modernization programs in India and Southeast Asian nations for both new construction and heavy-haul upgrades.
- Signaling Systems:These complex systems manage train movements, ensuring safe operations and optimizing network capacity through technologies like interlockings and block systems. Demand is driven by safety mandates such as the US Positive Train Control and the EU's Technical Specifications for Interoperability, compelling technology upgrades.
- Bridges:Essential civil engineering structures facilitate railway passage over obstacles like rivers, valleys, and other transport routes.
- Stations:These facilities serve as passenger hubs, integrating ticketing, waiting areas, and platform access, particularly critical for urban transit expansion.
- Electrification:Infrastructure components like overhead catenary systems and third rails provide power to electric trains.
- Tunnels:Underground or through-mountain passages reduce travel distances and overcome geographical barriers, often for high-speed lines.
Today's leader: Tracks. Tomorrow's challenger: Signaling Systems.
Technology:
Application-focused technology segmentation highlights the specialized control and communication solutions deployed across rail networks.
- Communication-Based Train Control:This advanced signaling technology uses continuous, high-resolution wireless data exchange to manage train separation and speed. Urban transit authorities are the primary adopters of CBTC to increase passenger throughput and operational flexibility on congested metro lines.
- Positive Train Control:A processor-based system designed to prevent train-to-train collisions, overspeed derailments, and incursions into work zones. North American rail operators are mandated to deploy PTC systems, driving significant investment in technology upgrades across freight networks.
- Automatic Train Control:A general class of systems that automatically control train speed, ensuring safe operation and adherence to track conditions.
- Wireless Sensor Networks:These distributed sensor systems monitor various infrastructure parameters like track integrity, temperature, and vibration.
- Fiber Optic Systems:High-bandwidth communication networks support data transmission for signaling, control, and operational communications.
- SCADA:Supervisory Control and Data Acquisition systems monitor and control industrial processes, including railway power distribution and station operations.
Communication-Based Train Control is expanding most quickly.
Application:
Customer type influences the specific infrastructure requirements and technology choices for various rail applications.
- High-Speed Rail:Dedicated lines for trains operating at speeds exceeding 250 km/h, requiring specialized track, electrification, and signaling. National strategic initiatives in China and the European Union are driving new construction for passenger connectivity.
- Urban Transit Systems:Metro, light rail, and tram networks designed to serve dense metropolitan areas, prioritizing high frequency and passenger capacity. Rapid urbanization in India and Southeast Asian nations necessitates new network development for these systems.
- Passenger Transit:Broad category encompassing intercity and regional rail services focused on passenger movement.
- Freight Carriers:Rail networks dedicated to transporting goods, often requiring robust tracks for higher axle loads and efficient logistics.
- Monorails:Elevated railway systems where trains run on a single beam, often used for niche urban or airport connections.
- Light Rail:Tram-like systems with lighter vehicles and infrastructure, suitable for urban and suburban environments.
High-Speed Rail drives the largest volume of new construction projects.
End User:
Margin potential varies significantly across end-user segments, reflecting their operational models and investment priorities.
- Public Transport Authorities:Government or quasi-government bodies responsible for planning, operating, and maintaining urban and regional passenger rail services. These entities often prioritize lifecycle costs and operational efficiency for their extensive networks.
- Freight Operators:Companies that transport goods by rail, investing in infrastructure upgrades to enhance capacity, speed, and safety for cargo movement. These operators focus on return on investment for track modernizations and PTC deployments.
- Railway Contractors:Firms specializing in the construction, installation, and maintenance of rail infrastructure components.
- Infrastructure Developers:Entities responsible for the planning, financing, and construction of new railway lines and associated facilities.
- Maintenance Companies:Businesses providing specialized services for the upkeep and repair of tracks, signaling, and electrification systems.
- Leasing Firms:Companies that provide rolling stock, equipment, or even infrastructure components under lease agreements to operators.
Public Transport Authorities hold significant long-term value due to sustained infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A concentration of digital engineering talent in India drives advanced signaling system development for both domestic and international rail projects. This workforce supports the country's ambitious national railway modernization programs. Rapid urbanization further necessitates urban transit expansion across major Indian cities.
India
Demand for new high-speed rail lines and urban metro systems is significant across India. The country's PLI scheme for manufacturing incentives localized component sourcing. The Delhi-NCR region sees continuous expansion of its metro network, requiring advanced infrastructure.
China
Extensive high-speed rail construction and urban transit development define market activity in China. The nation's GB standards influence component design for domestic projects. The Yangtze River Delta region drives demand for advanced rail infrastructure, including new lines and upgrades.
United States
Freight modernization and safety mandates drive investment in existing networks across the United States. The US Federal Railroad Administration's Positive Train Control mandate compels technology upgrades. Major freight corridors across the Midwest are upgrading for higher axle loads and enhanced safety.
Germany
Advanced signaling systems and high-speed rail initiatives characterize European demand, particularly in Germany. The EU's Technical Specifications for Interoperability (TSIs) standardize cross-border rail components. The Munich metropolitan area focuses on urban transit system enhancements, including CBTC deployments.
Indonesia
Urban transit expansion and new light rail networks are critical for rapidly growing cities in Indonesia. The country's national infrastructure development plans support railway modernization. Jakarta's ongoing metro and LRT projects exemplify this growth, creating demand for modern systems.
Global Rail Infrastructure Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in rail infrastructure. The market exhibits a tiered structure, with a few global conglomerates dominating large-scale projects. Strategic archetypes include integrated system providers, specialized technology developers, and regional civil engineering firms. Companies pursue strategic partnerships and portfolio diversification to enhance their market position.
Integrated system providers such as Germany-based Siemens and China-based CRRC Corporation exemplify the scale and technological breadth required for national railway projects. These entities offer end-to-end solutions from high-speed rail technologies to sophisticated Communication-Based Train Control systems. Wabtec Corporation, a US-based entity, represents specialists focused on freight modernization and Positive Train Control solutions, meeting specific North American rail operator requirements.
| Leading Market Players |
|---|
| Larsen & Toubro |
| Hyundai Rotem |
| Alstom |
| Wabtec Corporation |
| Bombardier Transportation |
| Siemens |
| Hitachi Rail |
| CAF (Construcciones y Auxiliar de Ferrocarriles) |
| CRRC Corporation |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers like CRRC Corporation often dictate pricing benchmarks for large infrastructure projects, while specialized private entities such as Wabtec Corporation command premiums for advanced safety systems, influencing both component availability and market cost structures.
Pricing Analysis
Bundled solutions integrating advanced signaling with long-term maintenance contracts dominate pricing structures for complex rail infrastructure projects. Price differentiation stems from technology sophistication, such as Communication-Based Train Control capabilities, and the level of customization required to meet specific national standards. Intense competition from global conglomerates and government budget constraints generate pricing pressure across many segments. Public Transport Authorities, focused on total cost of ownership, exhibit high price sensitivity for new deployments, while freight operators prioritize return on investment for track upgrades.
Supply Chain Analysis
Direct-to-government procurement channels and large engineering, procurement, and construction (EPC) contractors handle the bulk of rail infrastructure distribution. Geographic supply concentration for core physical assets like tracks centers on China and India, while advanced signaling components draw from Germany and the United States. Key raw material dependencies include steel for tracks and copper for electrification systems. Single-source vulnerability for specialized digital components presents a structural supply chain risk. Downstream, distribution runs through localized civil engineering firms for installation and maintenance services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with mandates like the US Positive Train Control driving sustained investment and technological evolution across networks.
For Market Incumbents: Lock in long-term service and maintenance contracts for advanced signaling systems, leveraging existing network knowledge and installed base. Invest in R&D for digital integration platforms to seamlessly connect new control systems with legacy physical infrastructure, mitigating the threat from specialized software entrants. Optimize global supply chains for critical components to ensure project delivery timelines and cost efficiency. This approach reinforces market leadership against evolving technological landscapes.
For New Entrants and Emerging Players: Launch via specialized software solutions targeting predictive maintenance and asset health monitoring for existing rail infrastructure. Focus on brownfield freight modernization in North America, where operators seek higher axle load capacity and enhanced safety. The most penetrable segment lies in offering value-based analytics services that reduce lifecycle maintenance costs. Develop go-to-market strategies emphasizing operational efficiency gains and rapid return on investment for operators.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional civil engineering firms with strong local government ties and established track record in physical infrastructure. Prioritize acquisition targets specializing in advanced signaling software development or sensor network technologies, offering high-margin growth potential over a 5-10 year horizon. A key signal to watch for inflection is increased government allocation for digital upgrades in emerging markets like India and Southeast Asia, indicating broader technology adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Communication-Based Train Control (CBTC) R&D | Drives capacity expansion and operational flexibility for urban transit systems like the Delhi Metro. |
| Secure long-term contracts for Positive Train Control (PTC) deployment | Ensures compliance with US Federal Railroad Administration mandates for North American freight operators. |
| Form strategic partnerships with local civil engineering firms | Facilitates market access and project execution in regions undergoing national railway modernization programs. |
| Develop predictive maintenance software for track infrastructure | Reduces lifecycle maintenance costs and extends asset life for Public Transport Authorities and Freight Operators. |
| Expand localized component manufacturing capabilities in India | Leverages the PLI scheme, reduces supply chain dependency, and improves cost-competitiveness for national projects. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. This involved extensive discussions with railway engineers, public transport authority procurement heads, freight operations managers, and signaling system developers. Secondary data sources included national railway reports, government infrastructure spending plans, academic papers on rail technology, and company annual reports, triangulating findings from bottom-up market sizing and top-down industry analysis.
Historical data anchored the forecast framework, establishing a baseline for projections across the modeling period. The analytical framework integrated segmentation dimensions including product type, technology, application, end user, and regional regulatory compliance for the rail sector. Compound annual growth rates were derived through a comprehensive analysis of market drivers and restraints. Industry-specific forecast inputs included government infrastructure spending forecasts and urbanization rates for new network development.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant geopolitical shifts or unexpected technological breakthroughs impacting rail systems. Forecasts reflect assumptions regarding continued government investment in rail infrastructure and the steady adoption of advanced digital control systems. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Netherlands Transportation Infrastructure Construction Market
Infrastructure Construction
Switzerland Transportation Infrastructure Construction Market
Infrastructure Construction
South Korea Transportation Infrastructure Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Steel Utility Poles Market
Infrastructure Construction
South Korea Infrastructure Market
Infrastructure Construction
Europe Transportation Infrastructure Construction Market
Infrastructure Construction
Latin America Data Center Construction Market
Infrastructure Construction
Denmark Data Center Construction Market
Infrastructure Construction
Pipeline Construction Market
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Middle East Pipeline Construction Market
Infrastructure Construction
Rebar Tier Market