
 Oman Construction Market | 2026-2036
Oman Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Construction Market Outlook
Hospitality and tourism infrastructure is recalibrating project pipelines across Oman. Galfar Engineering & Contracting SAOG anchors large-scale civil works through its entrenched position in hydrocarbon-adjacent construction. Larsen & Toubro Oman competes on complex industrial and power infrastructure execution. Al Hassan Engineering specializes in marine and coastal works that serve port expansions along the Arabian Sea.
Oman construction encompasses the physical assembly of buildings, transport networks, and industrial facilities using reinforced concrete, structural steel, and composite materials to specified load-bearing and environmental performance standards. The sector delivers residential, commercial, infrastructure, and industrial assets that support economic diversification beyond oil. Infrastructure project types currently absorb the largest capital allocation as the government advances logistics corridors and utility backbones. Sustainable construction methods are gaining fastest traction as green building codes and energy efficiency mandates tighten material selection and waste protocols. Cement and steel material types dominate volume but face margin compression from import dependency and freight cost volatility.
Oman's Ministry of Housing and Urban Planning enforces building codes that shape structural design and safety compliance for all new developments. The Public Authority for Mining regulates aggregate and limestone extraction that feeds domestic cement production, constraining supply elasticity. Contractors must navigate permitting through multiple municipal authorities, with Muscat Municipality maintaining the most stringent environmental impact review protocols. Stakeholders should monitor how carbon intensity disclosure requirements evolve under Oman's net-zero commitments and whether domestic precast capacity expands to offset imported structural components.
Market Dynamics
Oman's construction sector is undergoing a fundamental recalibration as building energy efficiency codes tighten material specifications and compress allowable carbon intensity in structural assemblies. This regulatory compression is reshaping procurement protocols and contractor qualification requirements across Muscat and the Duqm Special Economic Zone corridor.
Growth Catalysts
- Tourism Infrastructure Mandates:Hospitality projects driven by Oman's tourism diversification strategy are expanding the buyer base for high-specification commercial builds. New resort developments in Salalah and Musandam require specialized marine-resistant concrete formulations.
- Duqm Special Economic Zone Authority Framework:SEZ incentives for logistics and industrial facilities are channeling capital into heavy civil works. Port expansion timelines are accelerating demand for precast structural components.
- Green Building Code Adoption:Oman's Ministry of Housing and Urban Planning energy efficiency standards are mandating thermal performance upgrades. Building envelope specifications now require insulated concrete forms and low-emissivity glazing systems.
Market Restraints
- Import-Dependent Steel Supply:Structural steel procurement relies on GCC and Asian mill supply subject to freight cost volatility. Currency fluctuations against the Omani rial compress contractor margins on fixed-price contracts.
- Limestone Extraction Licensing:The Public Authority for Mining constrains aggregate supply elasticity through controlled quarry permitting. Domestic cement production faces raw material bottlenecks during peak construction seasons.
- Skilled Labor Concentration:Specialized welding and marine construction expertise concentrates in Muscat and Sohar. Project sites in remote governorates face crew mobilization delays and accommodation cost premiums.
Strategic Opportunities
- Dhofar Governorate Underpenetration:Salalah's free zone and port expansion create greenfield demand for industrial warehousing and cold chain infrastructure. Logistics corridor development linking the port to interior population centers requires transport network investment.
- Precast-Modular Convergence:Factory-built structural elements combined with on-site assembly are compressing project timelines for repetitive building types. Hotel and residential developers in Muscat are piloting hybrid construction methods.
- Net-Zero Disclosure Requirements:Oman's carbon intensity reporting mandates for large developments are creating advisory and certification service demand. Engineering consultancies are building lifecycle assessment capabilities to capture compliance-driven revenue.
Industry Challenges
- Building Information Modeling Competency Gaps:Contractor adoption of 4D/5D BIM for clash detection and cost modeling lags client requirements on complex industrial projects. Training pipelines for VDC coordinators remain underdeveloped in Omani technical institutes.
- Multi-Authority Permitting Friction:Environmental impact reviews through Muscat Municipality operate on timelines misaligned with Ministry of Housing approvals. Project financing drawdown schedules face disruption from unpredictable clearance durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Construction Market |
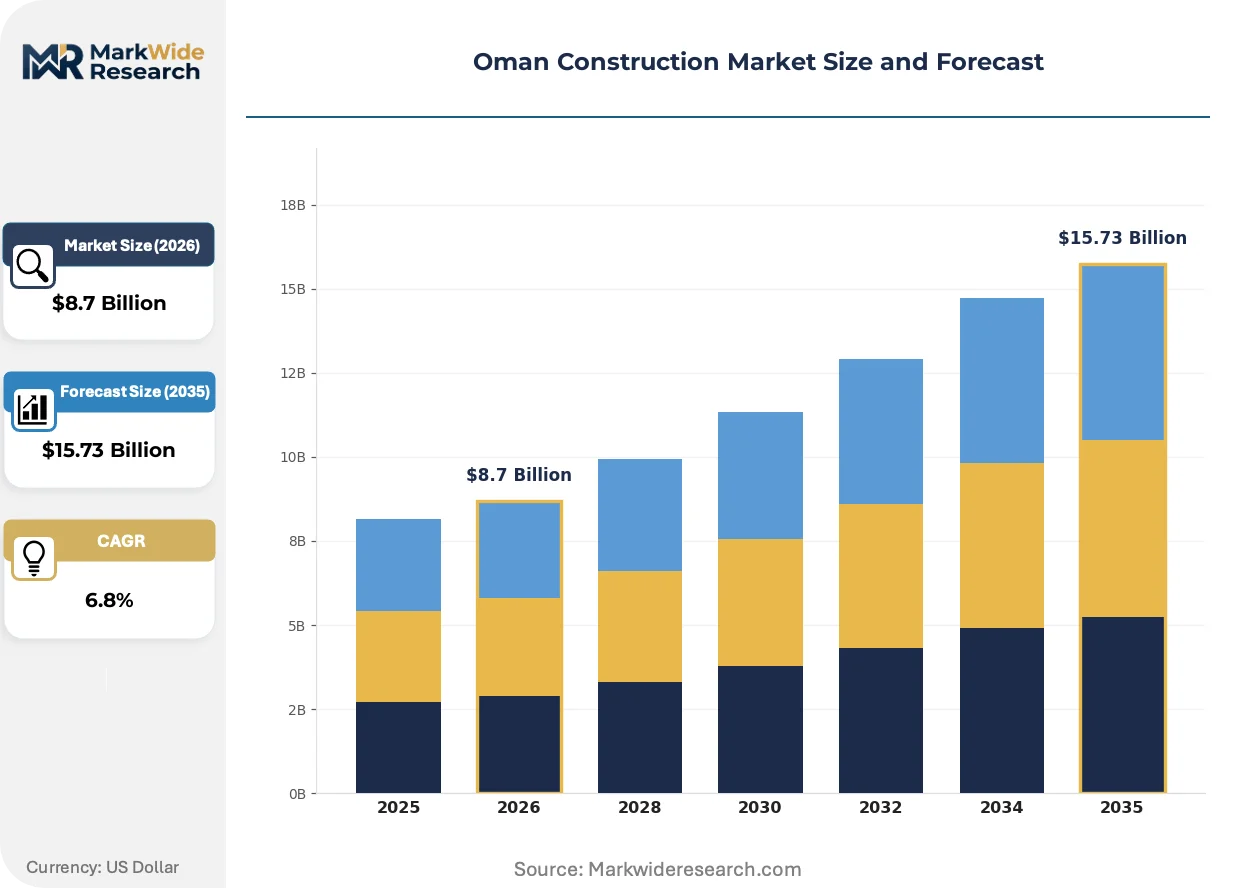
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Infrastructure, Industrial Material Type: Cement, Steel, Timber, Glass Construction Method: Traditional, Modular, Precast, Sustainable End User: Government, Private Sector, Contractors, Developers |
| Companies Covered | Al Turki Enterprises, The Oman Construction Company, Galfar Engineering & Contracting SAOG, Al Hassan Engineering, Bechtel, Consolidated Contractors Company, Bahwan Engineering Group, Douglas OHI, Larsen & Toubro Oman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Construction Market Strategic Shifts
Digital fabrication and regulatory carbon accounting are converging to reshape how Omani contractors source materials, sequence work, and document compliance. These shifts are compressing traditional procurement cycles while elevating technical qualification barriers.
Building Information Modeling integrated with carbon tracking software is unifying design, procurement, and compliance workflows into single-platform environments. Major infrastructure developers in the Duqm corridor are mandating BIM Level 2 delivery on contracts above specified thresholds. This unifying technology is compressing the traditional separation between engineering design and quantity surveying functions, forcing contractor organizational restructuring.
Oman's Ministry of Housing and Urban Planning is enforcing progressive energy efficiency tiers through its building code revision cycle. The 2024 thermal performance standards now require whole-building energy modeling prior to permit issuance. Commercial developments in Muscat Governorate are responding by specifying high-performance glazing and automated building management systems to demonstrate compliance.
Developer procurement patterns are fragmenting toward specialized trade contractors rather than consolidated general contracting. Industrial facility owners in Sohar and Duqm are directly engaging MEP specialists and façade subcontractors while retaining construction management oversight. This disintermediation is most visible in pharmaceutical and food processing verticals where process equipment integration demands discipline-specific expertise beyond traditional general contractor capabilities.
Oman Construction Market Segmentation
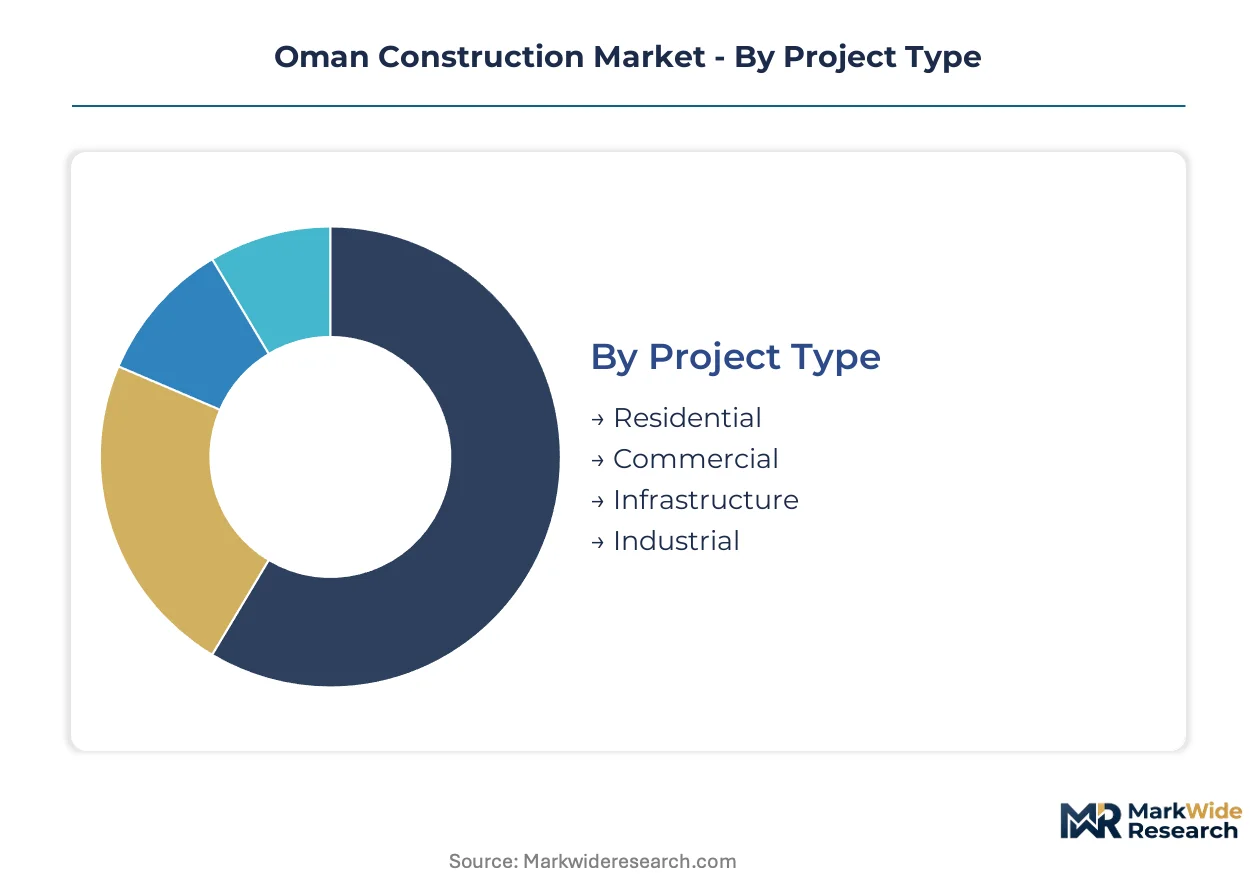
Construction segmentation in Oman reveals how procurement priorities diverge across project sponsors and delivery methodologies. Understanding these fault lines clarifies where capital allocation concentrates and where technical specifications are tightening fastest.
Project Type:
Buyer differentiation across project types reflects varying risk appetites and financing structures among government agencies, institutional investors, and private developers.
- Infrastructure:Roads, bridges, utilities, and logistics corridors absorb the largest capital deployment as Oman advances its transport backbone and utility networks. Demand concentrates in the Duqm Special Economic Zone corridor and Muscat periphery, driven by sovereign development mandates and logistics hub ambitions.
- Industrial:Manufacturing facilities, refineries, and processing plants require specialized heavy civil works and process-integrated construction. Project pipelines cluster around Sohar and Duqm industrial zones, propelled by economic diversification targets and hydrocarbon-adjacent manufacturing expansion.
- Residential:Housing developments span social housing programs and private master-planned communities. Muscat Governorate and interior urban centers anchor volume as population growth and mortgage accessibility programs stimulate developer activity.
- Commercial:Office towers, retail complexes, and mixed-use developments serve corporate and consumer demand. Hospitality-anchored commercial builds in Salalah and Musandam are expanding fastest under tourism infrastructure mandates.
Volume sits with Infrastructure; growth tilts toward Industrial.
Material Type:
Material selection in Omani construction tracks regulatory pressure on embodied carbon and import dependency exposure across different project risk profiles.
- Cement:Portland and blended cement formulations dominate structural concrete supply for foundations, columns, and slabs. Domestic production from limestone extraction in northern governorates serves Muscat and Sohar demand, though quarry licensing constraints tighten during peak construction seasons.
- Steel:Reinforcing bar and structural sections from GCC and Asian mills provide tensile strength for high-rise and industrial frames. Currency volatility against the Omani rial compresses contractor margins on fixed-price contracts when freight costs spike.
- Glass:Low-emissivity and laminated glazing systems satisfy thermal performance mandates in commercial envelopes. Building code revisions are accelerating specification upgrades across Muscat commercial developments.
- Timber:Engineered wood products and treated lumber serve interior finishes and select structural applications. Limited domestic supply and humidity degradation concerns restrict deployment to conditioned environments.
Supply security favors Cement; specification intensity climbs fastest for Glass.
Construction Method:
Delivery methodology fragmentation reflects timeline compression demands and workforce availability constraints across Oman's dispersed project geography.
- Traditional:Cast-in-place concrete and stick-built steel erection remain prevalent for bespoke designs and complex geometries. Remote governorate projects without precast yard proximity default to conventional methods despite longer schedules.
- Precast:Factory-cast structural elements accelerate repetitive building assembly and quality control. Duqm port expansion and Muscat hotel developments are driving demand for standardized precast components.
- Sustainable:Green building protocols, renewable material sourcing, and carbon accounting integration address Ministry of Housing energy efficiency mandates. Whole-building energy modeling requirements are elevating sustainable method adoption in commercial permitting.
- Modular:Volumetric units manufactured off-site and assembled on location compress project timelines for repetitive typologies. Workforce accommodation and temporary facility projects are piloting modular delivery in remote sites.
Deployment breadth stays with Traditional; adoption velocity favors Sustainable.
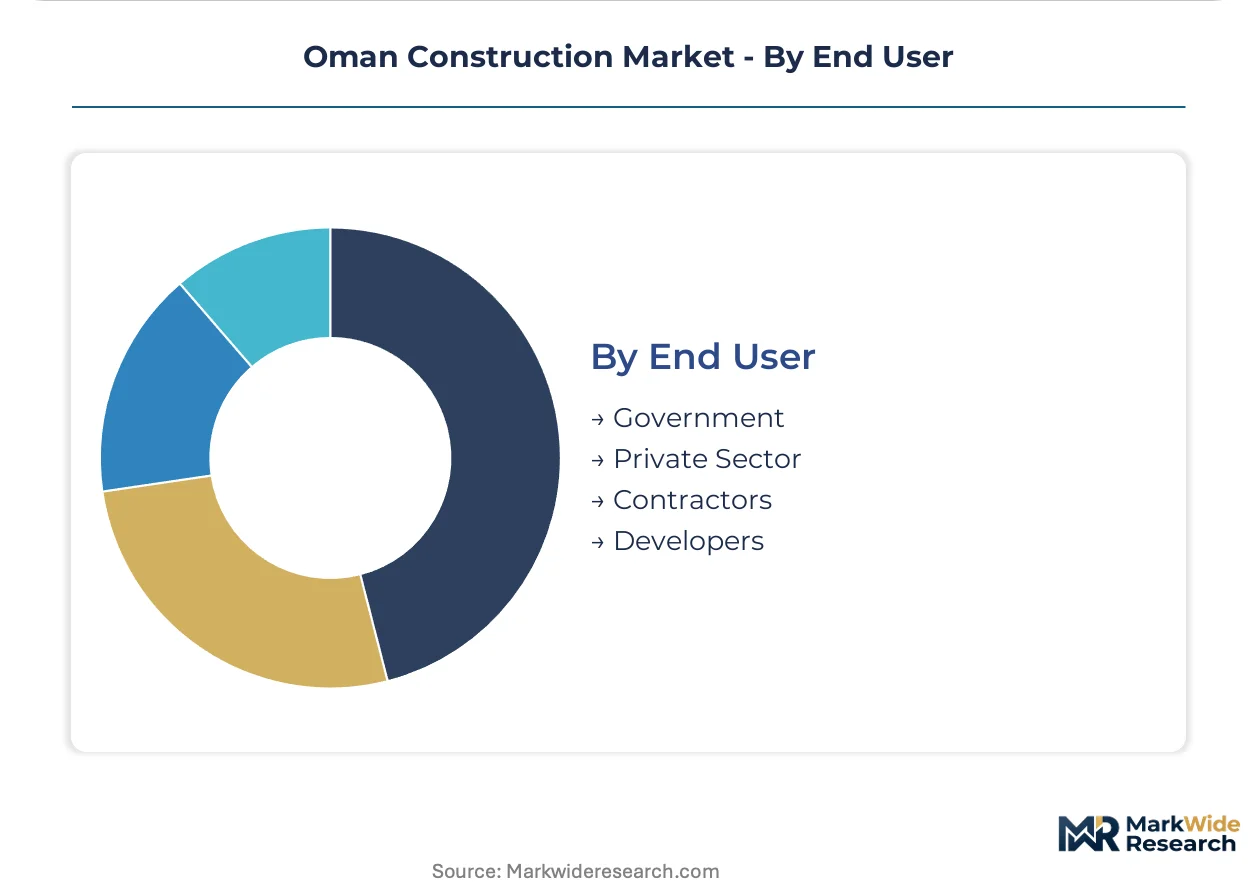
End User:
End user category delineates how procurement authority, risk allocation, and technical specification control distribute across Oman's construction value chain.
- Government:Ministries and public authorities commission infrastructure, social housing, and institutional facilities through tender processes. Ministry of Housing and Urban Planning building codes and Muscat Municipality environmental protocols shape technical requirements.
- Private Sector:Corporate occupiers and institutional investors direct commercial and industrial development specifications. Direct engagement of trade contractors for MEP and façade systems is fragmenting traditional general contracting relationships.
- Developers:Real estate development companies aggregate capital, secure entitlements, and monetize completed assets. Master-planned community developers in Muscat and Salalah are integrating lifecycle assessment capabilities for carbon disclosure compliance.
- Contractors:Construction firms execute works under design-bid-build or design-build arrangements. Galfar Engineering and Larsen & Toubro Oman anchor large-scale civil and industrial execution capacity.
Project flow concentrates with Government; specification control is shifting fastest toward Developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Duqm Special Economic Zone Authority framework concentrates capital deployment along Oman's central coastline. Government incentives for logistics and industrial facilities are channeling heavy civil works into this corridor. Muscat and Salalah anchor secondary demand poles through distinct sectoral specializations.
Muscat Governorate
Mixed-use commercial developments and hospitality projects dominate procurement pipelines in the capital region. The Ministry of Housing and Urban Planning enforces progressive energy efficiency tiers through building code revisions that mandate thermal performance upgrades. Developers in Al Seeb and Al Khoud are piloting hybrid precast-modular construction methods for hotel and residential assets.
Duqm Special Economic Zone
Port expansion timelines and refinery-adjacent industrial facilities are accelerating demand for heavy civil infrastructure and precast structural components. SEZ Authority incentives for logistics operators are compressing project approval cycles relative to standard municipal permitting. The port-industrial corridor is attracting contractors with marine construction capabilities for waterfront heavy civil works.
Dhofar Governorate
Salalah's free zone expansion and port modernization are creating greenfield demand for industrial warehousing and cold chain infrastructure. Logistics corridor development linking the port to interior population centers requires transport network investment and specialized marine-resistant concrete formulations. The governorate remains underpenetrated relative to northern construction intensity, offering first-mover positioning for contractors willing to absorb crew mobilization costs.
Al Batinah Region
Limestone extraction from northern quarries feeds domestic cement production serving Muscat and Sohar demand clusters. The Public Authority for Mining constrains aggregate supply elasticity through controlled permitting that tightens during peak construction seasons. Sohar's industrial zone anchors manufacturing facility construction for hydrocarbon-adjacent processing industries.
Musandam Governorate
Resort developments targeting tourism diversification require specialized marine-resistant materials and coastal engineering expertise. Remote geography limits contractor access and inflates accommodation cost premiums for project crews. The governorate's strategic location at the Strait of Hormuz is driving port and coastal defense infrastructure investment.
Oman Construction Market Competitive Environment
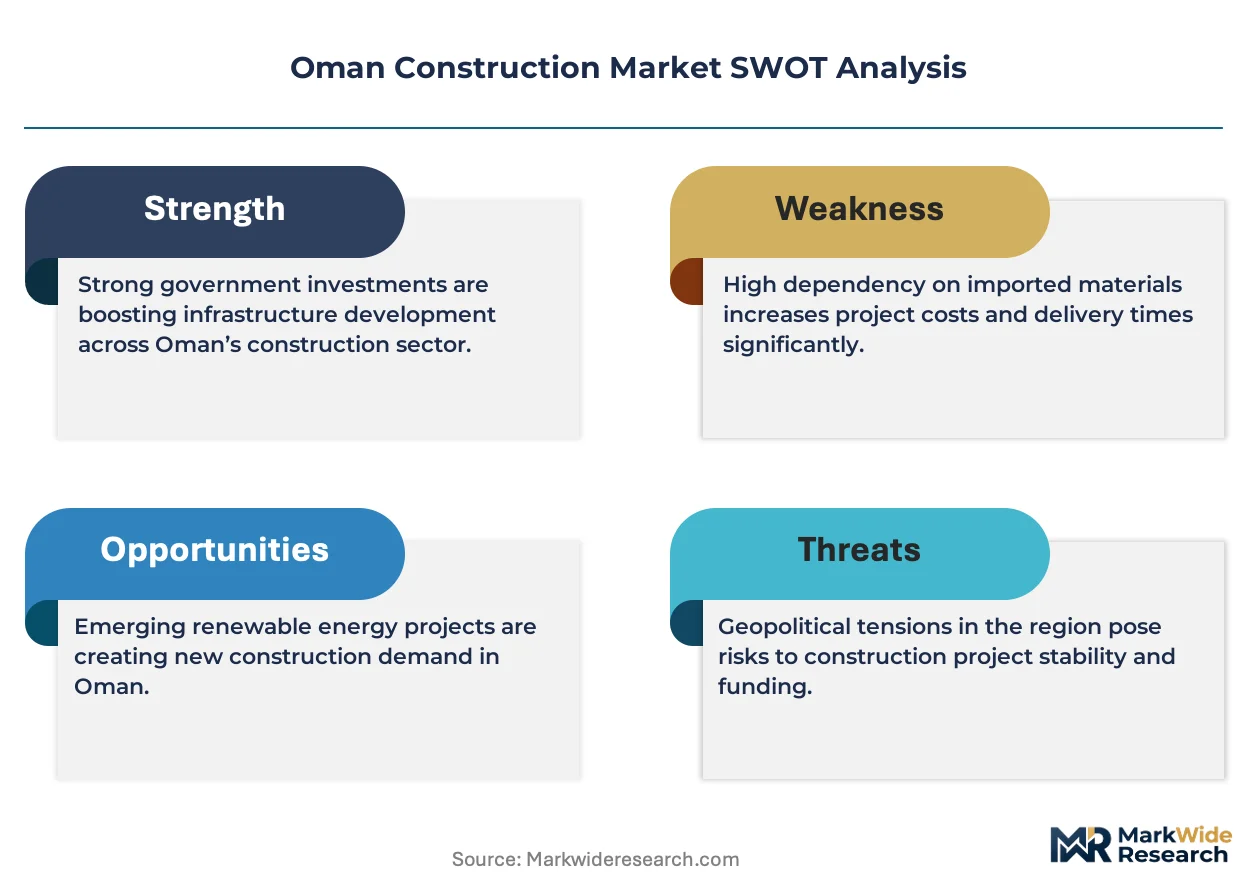
Branded specialists and contract manufacturers split share differently across segments, with government-tendered infrastructure favoring established civil works contractors while private developers fragment procurement toward trade specialists. Market structure tilts toward consolidated execution capacity at the heavy civil and industrial tier, with mid-scale residential and commercial contracting remaining more fragmented. Three archetypes dominate: hydrocarbon-adjacent engineering specialists, diversified regional conglomerates with construction divisions, and international EPC contractors targeting complex industrial facilities. Competitive moves center on precast yard capacity expansion and BIM competency acquisition to meet evolving client technical requirements.
Among Omani-anchored contractors, Galfar Engineering & Contracting SAOG occupies a position exemplifying the hydrocarbon-adjacent engineering specialist archetype through its entrenched role in large-scale civil works. Larsen & Toubro Oman represents the international EPC contractor model competing on complex industrial and power infrastructure execution. Al Hassan Engineering sits within the coastal and marine works specialization tier, serving port expansions along the Arabian Sea. These three companies illustrate how technical capability concentration in Muscat and Sohar shapes competitive positioning across Oman's project geography.
| Leading Market Players |
|---|
| Al Turki Enterprises |
| The Oman Construction Company |
| Galfar Engineering & Contracting SAOG |
| Al Hassan Engineering |
| Bechtel |
| Consolidated Contractors Company |
| Bahwan Engineering Group |
| Douglas OHI |
| Larsen & Toubro Oman |
| Others |
Value Chain & Pricing Dynamics
Government infrastructure procurement concentrated in Muscat and Duqm operates on fixed-price contract structures that transfer freight cost volatility risk to contractors. This buyer concentration compresses margins when currency fluctuations against the Omani rial spike landed steel costs from GCC and Asian mills.
Pricing Analysis
Short lead-time premiums dominate contractor bidding behavior as project owners accelerate Duqm port expansion timelines. Pricing stratifies across premium-certified, standard-compliant, and economy-tier material specifications tied to Ministry of Housing energy efficiency mandates. Cost compression in structural steel procurement is intensifying because import dependency exposes fixed-price contracts to freight rate spikes. Government tender participants show highest price sensitivity; private developers with direct trade contractor engagement absorb specification premiums more readily.
Supply Chain Analysis
Regional distribution centers in Sohar and Muscat operate hub-and-spoke patterns serving northern governorate demand clusters. Geographic supply concentrates in the UAE, India, and China for structural steel and precast components. Raw material dependencies include limestone aggregate from Al Batinah quarries, Portland cement clinker, and marine-resistant concrete admixtures. Single-source vulnerability runs through GCC mill supply for rebar and structural sections. Distribution runs through contractor-controlled precast yards and third-party logistics operators serving remote Dhofar and Musandam sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's construction sector sits in a technology-transition phase as Building Information Modeling displaces traditional design-bid-build workflows. BIM Level 2 mandates on major Duqm contracts are forcing contractor organizational restructuring.
For Market Incumbents: Acquire precast yard capacity in the Duqm corridor to defend against modular construction entrants. Build lifecycle assessment advisory capabilities to capture carbon disclosure compliance revenue. Anchor position through backward integration into limestone aggregate extraction as Public Authority for Mining licensing tightens. For New Entrants and Emerging Players: Dhofar Governorate logistics developers represent an underserved buyer archetype with greenfield warehousing and cold chain demand. Capture Salalah free zone industrial facility contracts before incumbent mobilization cost premiums deter competition. Lead with marine-resistant concrete formulation expertise as a differentiated entry wedge. For Investors and Strategic Acquirers: The window for entry favors BIM-capable mid-tier contractors ahead of Ministry of Housing digital delivery mandates. Long-term viability hinges on precast-modular convergence positioning across the analysis window. Watch for carbon intensity disclosure rule expansion as the inflection signal for lifecycle assessment service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Precast Yard Capacity Expansion | Compresses project timelines for Duqm port-industrial corridor repetitive builds. |
| BIM Competency Acquisition | Meets Ministry of Housing Level 2 delivery mandates on infrastructure contracts. |
| Backward Integration into Aggregate | Secures limestone supply against Public Authority for Mining permitting bottlenecks. |
| Lifecycle Assessment Capability Build | Captures advisory revenue from net-zero disclosure compliance requirements. |
| Marine Construction Specialization | Addresses Musandam and Salalah coastal resort and port infrastructure demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with project developers, EPC contractors, Ministry of Housing officials, and quarry operators combined with Public Authority for Mining permit databases and Oman Chamber of Commerce construction sector reports. Bottom-up project pipeline tracking triangulated against top-down macroeconomic indicators.
Data-stream reconciliation across material procurement databases and contractor bid archives shaped the analytical framework. Segmentation dimensions modeled include project type, material category, construction methodology, and regional demand cluster throughout the forecast period. CAGRs derived from trend extrapolation of capital allocation patterns and regulatory implementation timelines. Energy efficiency code adoption curves and precast capacity expansion plans served as construction-specific forecast inputs.
Revisions become necessary when Ministry of Housing building code enforcement intensity shifts or Duqm SEZ incentive structures materially change. Forecasts reflect assumptions about sovereign infrastructure spending continuity and limestone quarry licensing velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Mezzanine Floor Market
Building Construction
Europe Modular Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Turkey Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Brazil Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
UAE Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Latin America Construction Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Construction Market
Building Construction
South Korea Data Center Construction Market