
 UAE Mhealth Market | 2026-2036
UAE Mhealth Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Mhealth Market Intelligence
Buyer concentration among UAE hospital networks and government health authorities is repositioning procurement power toward integrated platform vendors. Apple Inc leverages its wearable ecosystem to anchor consumer-facing vitals tracking within the Emirates. Samsung Electronics competes through Galaxy Watch integrations with local telemedicine networks. Philips Healthcare sustains its installed base of clinical monitoring hardware now feeding into cloud-based dashboards.
Mhealth encompasses the delivery of healthcare services, patient monitoring, and wellness management through mobile devices, wireless infrastructure, and portable digital technologies operating on iOS and Android platforms with Bluetooth Low Energy and cellular connectivity standards. The primary commercial purpose centers on extending clinical reach beyond facility walls while reducing per-capita healthcare expenditure through automated triage and remote chronic disease surveillance. Telemedicine Solutions command the dominant revenue share as MOHAP-licensed virtual consultation platforms become embedded in mandatory insurance coverage frameworks. Wearable Devices represent the fastest-expanding technology segment as biometric sensors achieve medical-grade accuracy for glucose, ECG, and blood oxygen monitoring. Remote Monitoring services concentrate margin pools through recurring subscription models tied to hospital-at-home programs.
MOHAP and Dubai Health Authority jointly enforce licensing standards for virtual consultation platforms, mandating end-to-end encryption and clinician credential verification that elevates barriers for uncertified app entrants. The UAE's PLI scheme for health technology manufacturing and data localization requirements under federal cybersecurity frameworks shape where platform infrastructure must reside and how patient data traverses borders. Stakeholders must monitor whether upcoming AI-specific medical device classifications from MOHAP will force algorithm retraining on locally hosted datasets.
Market Dynamics
MOHAP's licensing mandate for virtual consultation platforms is compressing vendor qualification timelines while concentrating procurement authority among hospital networks that can absorb compliance costs. This regulatory pressure is redrawing competitive boundaries between integrated platform providers and point-solution developers.
Growth Catalysts
- MOHAP Licensing Framework:Mandatory credential verification and end-to-end encryption standards for virtual consultation platforms are embedding telemedicine into insurance coverage frameworks, creating institutional demand pull.
- Wearable Biometric Accuracy:Medical-grade glucose, ECG, and blood oxygen sensors are expanding reimbursable remote monitoring indications beyond basic fitness tracking into chronic disease surveillance.
- Dubai-Abu Dhabi Infrastructure Concentration:Health system digitization investments cluster in these two emirates, generating network effects that accelerate platform adoption among affiliated clinical networks.
Market Restraints
- Data Localization Requirements:Federal cybersecurity frameworks mandate patient data residency within UAE borders, elevating cloud infrastructure costs for foreign platform providers.
- Clinician Credential Bottleneck:MOHAP's verification pipeline for virtual consultation licenses creates supply constraints on qualified provider pools, throttling platform scaling velocity.
- Interoperability Fragmentation:Proprietary data formats across hospital information systems impede seamless integration of third-party mhealth applications into existing clinical workflows.
Strategic Opportunities
- Hospital-at-Home Expansion:Recurring subscription models for remote patient monitoring services are capturing margin pools as acute care shifts beyond facility walls into residential settings.
- AI Medical Device Classification:Anticipated MOHAP algorithm governance rules will create first-mover advantages for vendors that establish locally hosted training datasets.
- PLI Manufacturing Incentives:The UAE's production-linked incentive scheme for health technology manufacturing is attracting component assembly operations for wearable sensors and connectivity modules.
Industry Challenges
- Integration Complexity:Legacy hospital information systems in Abu Dhabi and Dubai health networks require costly middleware development to interface with cloud-based mhealth dashboards.
- Algorithm Retraining Burden:Pending MOHAP requirements for locally trained AI diagnostic tools will force vendors to rebuild model architectures on geographically restricted datasets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Mhealth Market |
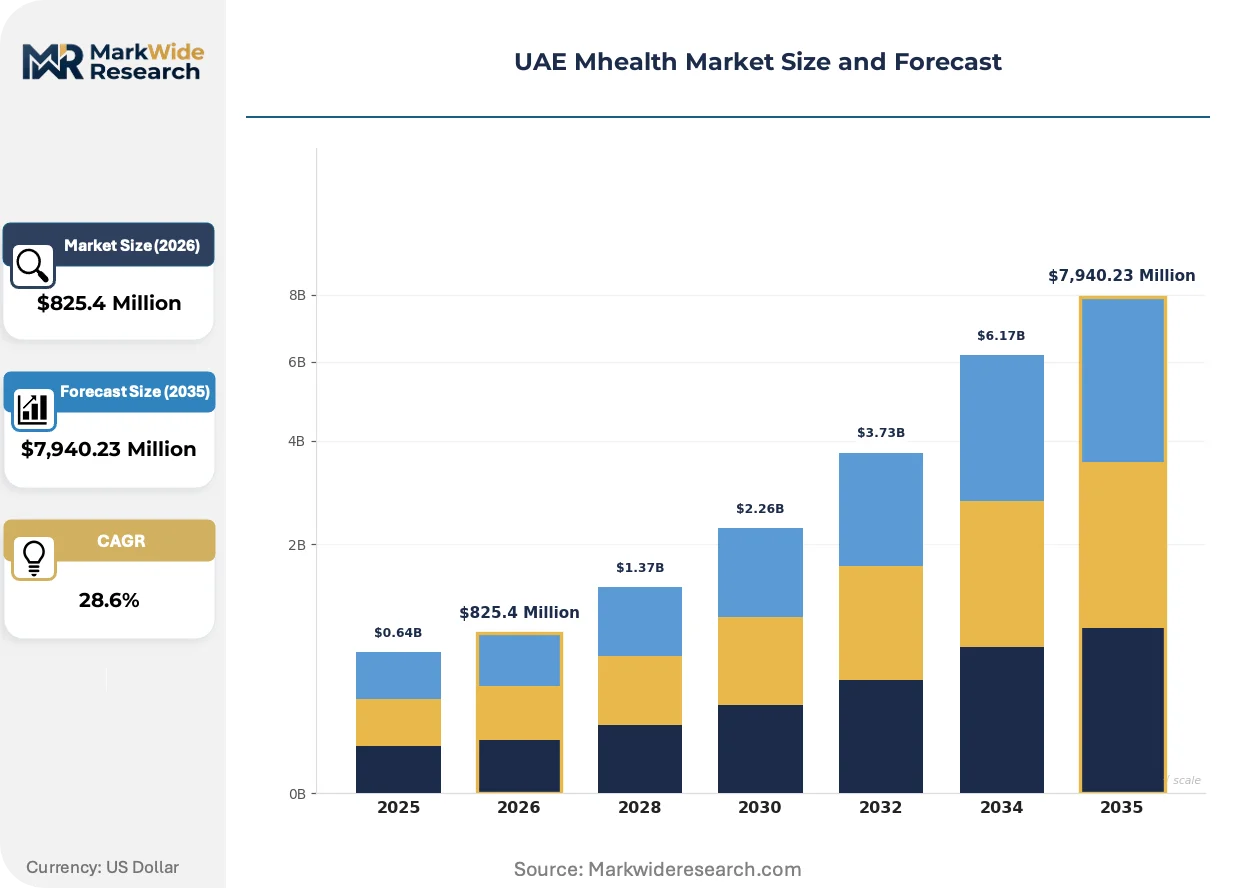
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $7,940.23 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Apps, Disease Management Apps, Medication Management Apps, Telemedicine Solutions Technology: Wearable Devices, Mobile Health Platforms, Cloud Computing, Artificial Intelligence End User: Healthcare Providers, Patients, Insurance Companies, Fitness Enthusiasts Service Type: Remote Monitoring, Consultation Services, Health Assessment, Wellness Programs |
| Companies Covered | Apple Inc, Samsung Electronics, Medcare, NextGen Healthcare, Philips Healthcare, Vodafone Group, Qualcomm, Alphabet Inc, Omron Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Mhealth Market Strategic Shifts & Innovations
Bluetooth Low Energy and cellular connectivity standards are enabling continuous physiological data streams that blur the boundary between consumer wellness and clinical-grade monitoring. Three developments are compressing product lifecycles and reshaping vendor competitive positioning.
Continuous glucose monitoring patches paired with smartphone analytics is integrating into endocrinology workflows at Dubai's flagship hospital networks. Specialist clinics are adopting these systems for real-time insulin dosing adjustments, displacing traditional finger-prick testing protocols. The technology is integrating patient-generated data directly into electronic health records, compressing diagnostic latency for diabetic complications.
MOHAP's forthcoming AI medical device classification framework will establish distinct approval pathways for diagnostic algorithms versus decision-support tools. This regulatory segmentation is forcing platform developers to rearchitect product modules for separate qualification tracks. Telemedicine vendors with embedded symptom-checker algorithms face the steepest compliance burden under the proposed rules.
Health authority procurement is consolidating around integrated platform vendors capable of delivering end-to-end virtual consultation, remote monitoring, and analytics dashboards. Single-point solution providers are losing access to hospital network tenders as buyers prioritize interoperability and unified data governance. Abu Dhabi's health system digitization contracts exemplify this concentration pattern, with awards favoring vendors offering bundled service stacks.
UAE Mhealth Market Segmentation
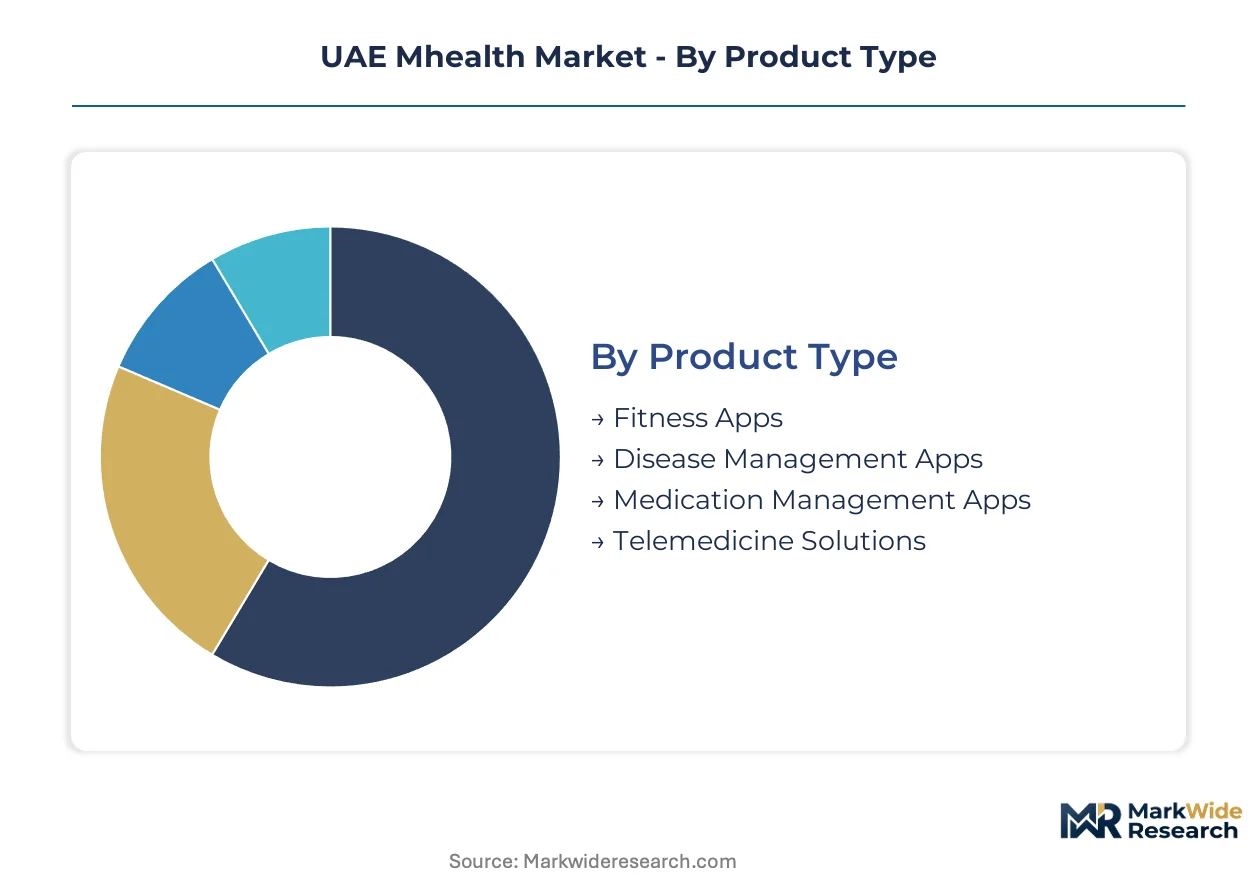
Mhealth segmentation in the UAE reflects divergent procurement logics across institutional buyers and consumer segments. Hospital networks prioritize integrated platform architectures while individual users drive volume through discrete wellness applications. Understanding these parallel demand curves is essential for vendor positioning.
Product Type:
Procurement authority concentrates with hospital network IT directors and MOHAP-licensed platform operators who evaluate clinical integration depth and compliance certification.
- Telemedicine Solutions:Virtual consultation platforms with end-to-end encryption and clinician credential verification anchor institutional procurement. Dubai and Abu Dhabi health networks embed these into mandatory insurance coverage frameworks, creating recurring revenue pools for qualified vendors.
- Disease Management Apps:Specialized applications for diabetes, cardiovascular, and respiratory conditions integrate continuous glucose monitors and blood pressure sensors into clinical workflows. Endocrinology departments at flagship Dubai hospital networks drive specialist adoption.
- Fitness Apps:Consumer-facing activity tracking and workout planning tools dominate download volumes through Apple App Store and Google Play distribution in the Emirates.
- Medication Management Apps:Pill reminders and adherence tracking tools serve polypharmacy patients and elderly populations managing multiple chronic prescriptions.
Volume sits with Fitness Apps; growth tilts toward Telemedicine Solutions.
Technology:
Technology selection follows a margin gradient: hardware sensors capture upfront revenue while cloud and AI layers extract recurring value through subscription analytics.
- Wearable Devices:Biometric sensors achieving medical-grade accuracy for glucose, ECG, and blood oxygen monitoring expand reimbursable indications. Samsung Galaxy Watch and Apple Watch ecosystems compete for integration with local telemedicine networks.
- Artificial Intelligence:Diagnostic algorithms and symptom-checker modules face impending MOHAP classification requirements that will force retraining on locally hosted datasets. First-mover advantages accrue to vendors establishing UAE-based training infrastructure.
- Mobile Health Platforms:Native iOS and Android applications with Bluetooth Low Energy connectivity serve as the primary consumer interface layer.
- Cloud Computing:Data localization mandates under federal cybersecurity frameworks require UAE-resident infrastructure, elevating operational costs for foreign platform providers.
Revenue concentrates in Wearable Devices; AI layers are climbing the fastest.
End User:
User type determines pricing architecture and regulatory exposure, with institutional buyers demanding enterprise-grade compliance and consumers prioritizing interface simplicity.
- Healthcare Providers:Hospital networks and clinic chains procure integrated platforms for virtual consultation and remote patient monitoring. MOHAP licensing requirements compress vendor qualification timelines toward established platform operators.
- Insurance Companies:Mandatory coverage frameworks for telemedicine create institutional demand pull as payers seek actuarial advantages from remote chronic disease surveillance.
- Patients:Chronic disease populations and elderly users generate recurring engagement through medication adherence and symptom tracking tools.
- Fitness Enthusiasts:Younger demographics in Dubai and Abu Dhabi drive consumer wearable volumes through wellness-oriented feature adoption.
Patient volumes dominate downloads; Healthcare Providers command contract values.
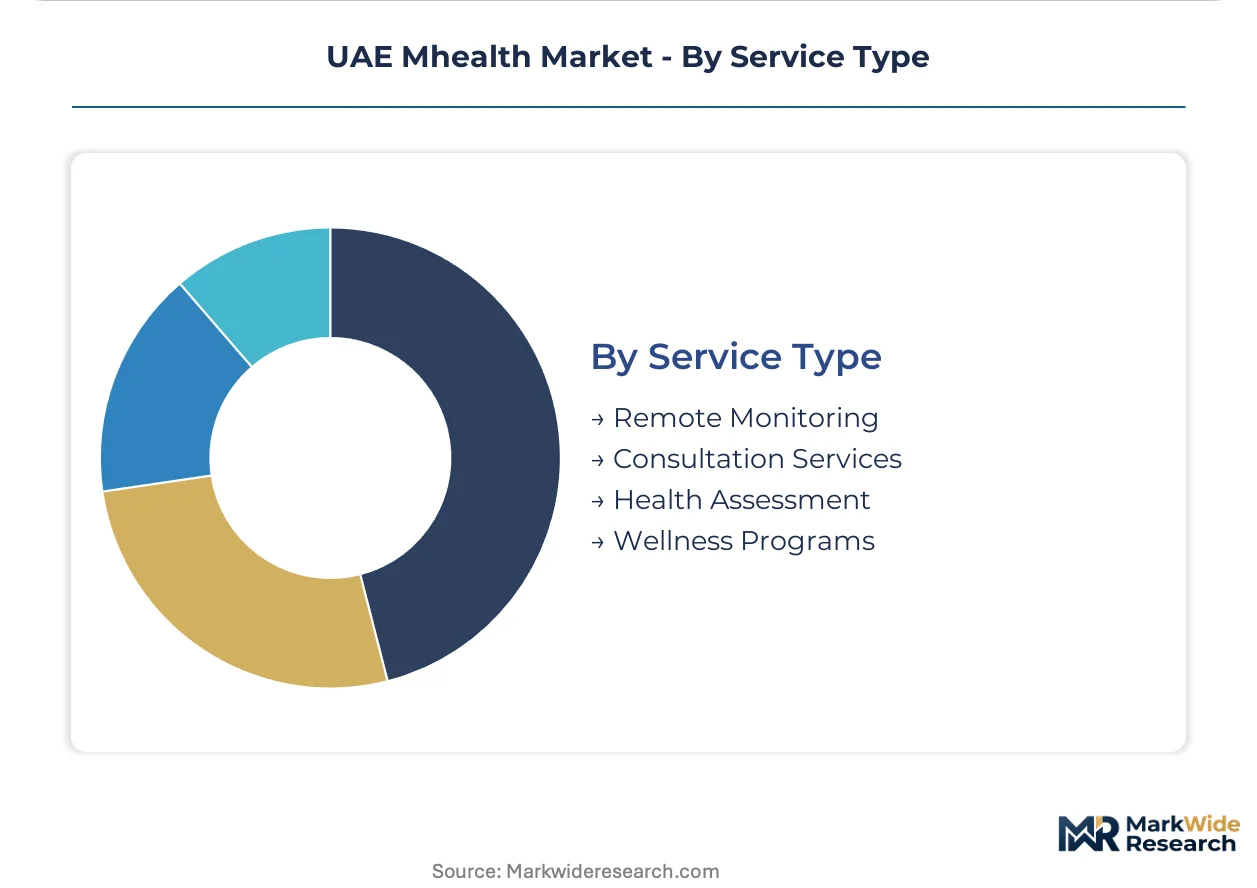
Service Type:
Service economics diverge between one-time consultation fees and recurring subscription models tied to longitudinal monitoring relationships.
- Remote Monitoring:Hospital-at-home programs and chronic disease surveillance generate recurring subscription revenue. Philips Healthcare sustains installed base advantages through clinical monitoring hardware feeding cloud-based dashboards.
- Consultation Services:MOHAP-licensed virtual consultations embed into standard care pathways with mandated encryption and credential verification protocols.
- Health Assessment:One-time diagnostic screenings and wellness checkups serve employer wellness programs and insurance risk stratification.
- Wellness Programs:Lifestyle coaching and preventive health modules target corporate wellness contracts and fitness enthusiast subscriptions.
Consultation Services capture transaction volume; Remote Monitoring holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived polymer feedstocks from Abu Dhabi's industrial zones anchor component manufacturing for wearable sensor housings and medical-grade device enclosures across the Emirates.
Dubai
Dubai Health Authority procurement concentrates on integrated telemedicine platforms for its flagship hospital networks. MOHAP licensing requirements for virtual consultations compress vendor qualification timelines toward established operators. Dubai Science Park clusters wearable device distributors and cloud infrastructure providers serving GCC markets.
Abu Dhabi
Abu Dhabi Health Services Company (SEHA) embeds remote patient monitoring into mandatory insurance coverage frameworks. The emirate's data localization mandates under federal cybersecurity frameworks require UAE-resident cloud infrastructure. Khalifa Industrial Zone attracts assembly operations for biometric sensors under PLI manufacturing incentives.
Sharjah
Sharjah's healthcare digitization lags Dubai and Abu Dhabi but accelerates through federal telemedicine coverage mandates. The emirate's university medical centers pilot AI diagnostic tools awaiting MOHAP classification rules. Sharjah Research Technology and Innovation Park hosts emerging mhealth software developers targeting price-sensitive clinical networks.
Northern Emirates
Ras Al Khaimah and Fujairah health authorities rely on federal MOHAP licensing standards without emirate-specific procurement frameworks. Rural clinic networks in these emirates adopt basic telemedicine consultations for specialist access. Infrastructure gaps concentrate deployment in coastal population centers rather than interior mountain settlements.
UAE Mhealth Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue AI diagnostic specializations and hospital-at-home service bundles. The vendor base stratifies between integrated platform operators capable of end-to-end compliance and point-solution developers facing procurement exclusion. Three archetypes dominate: consumer electronics ecosystems, clinical hardware incumbents, and telecom infrastructure providers. Competitive moves concentrate on strategic partnerships with hospital networks and geographic expansion into Saudi Arabia and Kuwait.
Within the consumer electronics archetype, Apple Inc and Samsung Electronics exemplify ecosystem-driven positioning. Apple leverages its wearable installed base to anchor consumer-facing vitals tracking. Samsung competes through Galaxy Watch integrations with local telemedicine networks. Philips Healthcare occupies a distinct tier as a clinical monitoring incumbent feeding cloud-based dashboards.
| Leading Market Players |
|---|
| Apple Inc |
| Samsung Electronics |
| Medcare |
| NextGen Healthcare |
| Philips Healthcare |
| Vodafone Group |
| Qualcomm |
| Alphabet Inc |
| Omron Healthcare |
| Others |
Cost & Logistics Intelligence
AI engineering talent clustering in Dubai Science Park and Abu Dhabi's Masdar City widens labor-cost spreads between premium algorithm development tiers and standardized platform maintenance operations, compressing mid-market vendor margins while elevating pricing power for integrated operators with captive technical workforces.
Pricing Analysis
Volume concentrates in consumer-facing fitness applications with thin margins; margin pools accrue to hospital-at-home remote monitoring subscriptions and MOHAP-licensed telemedicine platforms. Three-tier pricing structure across premium clinical-grade, standard enterprise, and economy wellness tiers separates vendors by certification depth and data localization compliance. Cost compression in the standard tier is intensifying because foreign platform providers absorb elevated cloud infrastructure expenses from federal cybersecurity mandates. Insurance companies and hospital networks exhibit lowest price sensitivity due to mandatory coverage frameworks; individual fitness enthusiasts drive volume but resist subscription premiums above basic tracking features.
Supply Chain Analysis
MOHAP's production-linked incentive scheme and data localization mandates are reshaping sourcing patterns toward UAE-based component assembly and domestic cloud infrastructure residency. Biometric sensor manufacturing draws from Taiwan, South Korea, and mainland China for MEMS fabrication and semiconductor packaging. Supply chain vulnerability centers on single-source dependencies for medical-grade glucose sensor membranes and ECG electrode materials. Distribution runs through Dubai Science Park logistics hubs for GCC re-export, with direct hospital network procurement bypassing traditional medical device distributors for integrated platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE Mhealth market is consolidating around integrated platform vendors as MOHAP licensing requirements and data localization costs force point-solution developers toward acquisition or exit.
For Market Incumbents: Acquire cloud infrastructure assets and UAE-resident data center capacity to satisfy federal cybersecurity mandates without recurring foreign hosting premiums. Philips Healthcare and Samsung Electronics should deepen backward integration into biometric sensor manufacturing through Khalifa Industrial Zone PLI incentives, insulating supply chains from Taiwan Strait logistics disruptions while capturing margin from hardware-to-software stack integration. For New Entrants and Emerging Players: MOHAP's forthcoming AI medical device classification framework opens a window for algorithm-specialist vendors that establish locally hosted training datasets ahead of compliance deadlines. Target Sharjah's university medical centers and Northern Emirates rural clinic networks where flagship hospital procurement concentration has left price-sensitive clinical networks underserved. Lead with discrete diagnostic modules rather than full-stack platforms to avoid direct competition with integrated incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with hospital-at-home service providers given the shift of acute care beyond facility walls into residential settings with recurring subscription economics. Acquisition candidates include remote monitoring specialists with existing SEHA or Dubai Health Authority contracts and AI diagnostic developers with UAE-based training infrastructure. Watch MOHAP's algorithm governance publication timeline as the inflection signal for first-mover compliance advantages crystallizing into contract wins.| Strategic Initiative | Industry Significance |
|---|---|
| MOHAP Licensing Compliance Investment | Mandatory credential verification and encryption standards embed vendors into insurance coverage frameworks at Dubai and Abu Dhabi health networks. |
| UAE Data Center Localization | Federal cybersecurity mandates require patient data residency, elevating operational costs for foreign platforms without domestic infrastructure. |
| Biometric Sensor Manufacturing Scale-Up | Khalifa Industrial Zone PLI incentives attract assembly operations for glucose and ECG sensors serving GCC telemedicine networks. |
| Hospital-at-Home Service Bundling | Remote patient monitoring subscriptions capture margin pools as SEHA embeds chronic disease surveillance into mandatory coverage. |
| AI Diagnostic Algorithm Retraining | Anticipated MOHAP classification rules force model rebuilding on geographically restricted datasets, favoring early UAE infrastructure investors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with hospital IT directors, MOHAP licensing officials, biomedical engineers, and telemedicine platform operators. Primary fieldwork combined with secondary validation from Dubai Health Authority procurement databases, SEHA contract disclosures, and federal cybersecurity framework documentation. Bottom-up sizing of wearable device shipments and telemedicine consultation volumes triangulated against top-down health expenditure allocations across the seven emirates.
Segment-level modeling captured product type splits between telemedicine solutions, disease management applications, and wearable devices; technology layers across hardware sensors, cloud infrastructure, and AI algorithms; and end-user differentiation between hospital networks, insurance payers, and individual consumers. Growth trajectories derived from policy mandate timelines, insurance coverage expansion schedules, and clinician credential pipeline capacity. Forecast inputs incorporated MOHAP licensing velocity, PLI manufacturing uptake rates, and hospital-at-home program enrollment curves.
The model assumes a particular technology adoption path; alternative pathways for AI diagnostic classification and data localization enforcement would alter the outlook. Forecasts reflect assumptions regarding regulatory implementation timing, interoperability standard adoption, and wearable biometric accuracy progression. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Cardiovascular Digital Solutions Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Global Surgical Preoperative Planning Software Market
Digital Health Solutions
Digiceuticals Market
Digital Health Solutions
Global Clinical Decision Support System Market
Digital Health Solutions
Digital Health Market
Digital Health Solutions
Global Urgent Care Apps Market
Digital Health Solutions
Artificial Intelligence in Precision Medicine Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Conversational AI in Healthcare Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
United Kingdom Digital Health Market