
 Electronic Data Capture Systems Market | 2026-2036
Electronic Data Capture Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Data Capture Systems Market Intelligence
Subscription-based software-defined feature layers is repositioning how Electronic Data Capture Systems vendors monetize platform access. Medidata Rave leverages cloud-native architecture to anchor enterprise-scale clinical trial workflows across North America and Europe. Oracle Clinical One sustains deep integration with broader clinical development suites, competing on ecosystem breadth rather than point-solution pricing. Castor EDC specializes in mid-market accessibility, differentiating through rapid deployment timelines for emerging biotech sponsors.
Electronic Data Capture Systems comprise software platforms, mobile applications, and web-based solutions that collect, manage, and validate clinical trial data through standardized electronic case report forms with audit trails and role-based access controls. These systems serve the primary purpose of replacing paper-based data collection to reduce transcription errors, accelerate database lock timelines, and enable real-time monitoring of patient safety signals. Cloud services and web-based solutions now lead deployment preferences among Contract Research Organizations seeking elastic infrastructure for multi-site global studies. On-premises systems retain residual demand in pharmaceutical companies with legacy validated environments and stringent internal IT governance protocols.
FDA 21 CFR Part 11 mandates electronic signature validation and audit trail integrity, directly shaping product development roadmaps and customer procurement criteria for US-facing deployments. EMA's ICH E6(R2) Good Clinical Practice guidelines reinforce risk-based monitoring requirements that EDC platforms must support through integrated data visualization and automated query management. CDSCO in India and PMDA in Japan impose parallel data integrity standards that vendors must navigate for market access across Asia-Pacific regulatory jurisdictions. Stakeholders should monitor how evolving FDA guidance on decentralized clinical trials reshapes platform requirements for direct-to-patient data capture and wearable device integration.
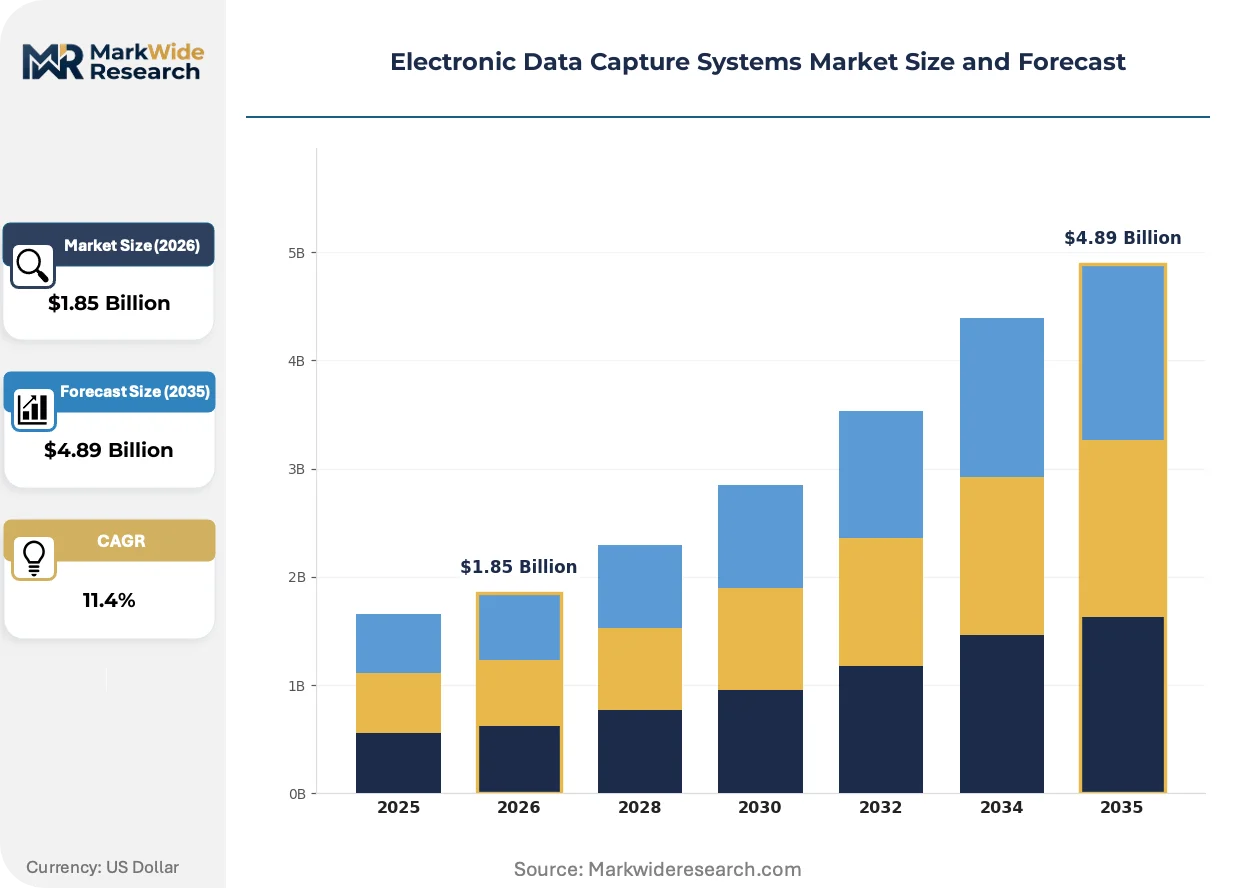
Market Dynamics
Decentralized clinical trial architectures are restructuring Electronic Data Capture Systems procurement, forcing vendors to reengineer platforms for direct-to-patient data flows and wearable device interoperability rather than site-centric workflows.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature validation mandates continue driving replacement cycles for legacy paper-dependent systems across US-based pharmaceutical sponsors.
- Contract Research Organizations:Elastic cloud infrastructure demand from multi-site global studies accelerates web-based deployment preferences over on-premises validated environments.
- Risk-based monitoring:EMA ICH E6(R2) Good Clinical Practice guidelines integrate automated query management and data visualization into core platform requirements.
Market Restraints
- Validation cost structure:Legacy pharmaceutical IT governance protocols perpetuate expensive on-premises maintenance for companies with entrenched validated environments.
- Asia-Pacific regulatory fragmentation:Parallel CDSCO India and PMDA Japan data integrity standards force redundant compliance investments for vendors seeking regional coverage.
- Technical debt in migration:Database lock timeline compression from modern platforms confronts sponsor hesitation over historical trial data format conversion risks.
Strategic Opportunities
- Direct-to-patient capture:FDA guidance evolution on decentralized trials opens white space for platforms integrating wearable biometrics and telemedicine endpoints.
- Mid-market accessibility:Rapid deployment timelines for emerging biotech sponsors remain underserved relative to enterprise-scale workflow complexity.
- NIH funding concentration:Academic medical centers and public health research networks present channel expansion potential outside commercial pharmaceutical procurement.
Industry Challenges
- Specialized talent scarcity:Clinical data management professionals with hybrid regulatory-technical expertise command premium compensation, constraining vendor scaling.
- Interoperability complexity:Integration friction between EDC platforms and existing clinical development suites delays implementation timelines for multi-system environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Data Capture Systems Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Platforms, Mobile Applications, Web-Based Solutions, Cloud Services, On-Premises Systems Deployment Mode: Centralized, Decentralized, Hybrid, Hosted, Managed Application: Clinical Trials, Patient Registries, Medical Device Studies, Real-World Evidence, Pharmacovigilance End User: Pharmaceutical Companies, Contract Research Organizations, Biotech Firms, Academic Research Institutions |
| Companies Covered | Viedoc, Medrio, Medidata Rave, ClinCapture, Clinion EDC, Oracle Clinical One, Castor EDC, OpenClinica, Veeva Vault EDC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Data Capture Systems Market Strategic Shifts & Innovations
Artificial intelligence and machine learning capabilities are embedding into core Electronic Data Capture Systems architectures, transforming manual query resolution and safety signal detection from retrospective batch processes into real-time automated workflows.
Natural language processing is automating adverse event narrative coding and medical history extraction from unstructured source documents. Mid-size Contract Research Organizations in the United States and Germany are piloting these capabilities for Phase II oncology studies. The technology is automating query generation cycles that previously required 48-72 hour human review turnaround, compressing database lock preparation timelines by eliminating transcription verification bottlenecks.
EMA's forthcoming guidance on computerized systems validation in cloud environments is reshaping vendor qualification protocols for European deployments. Pharmaceutical sponsors operating across multiple EU member states must now document data residency controls and subprocessor governance with greater granularity than FDA 21 CFR Part 11 requires. Contract Research Organizations with established EU Qualified Person networks are accelerating platform certification to capture sponsor procurement decisions ahead of formal guidance publication.
Subscription-based access models are displacing perpetual license structures among emerging biotech sponsors with variable pipeline velocity. These buyers now prioritize month-to-month scalability over multi-year enterprise commitments, forcing established vendors to unbundle feature tiers and introduce consumption-based pricing for storage and user seats. The shift is most visible in the San Diego and Boston biotech clusters where venture-funded sponsors dominate new system procurement decisions.
Electronic Data Capture Systems Market Segmentation
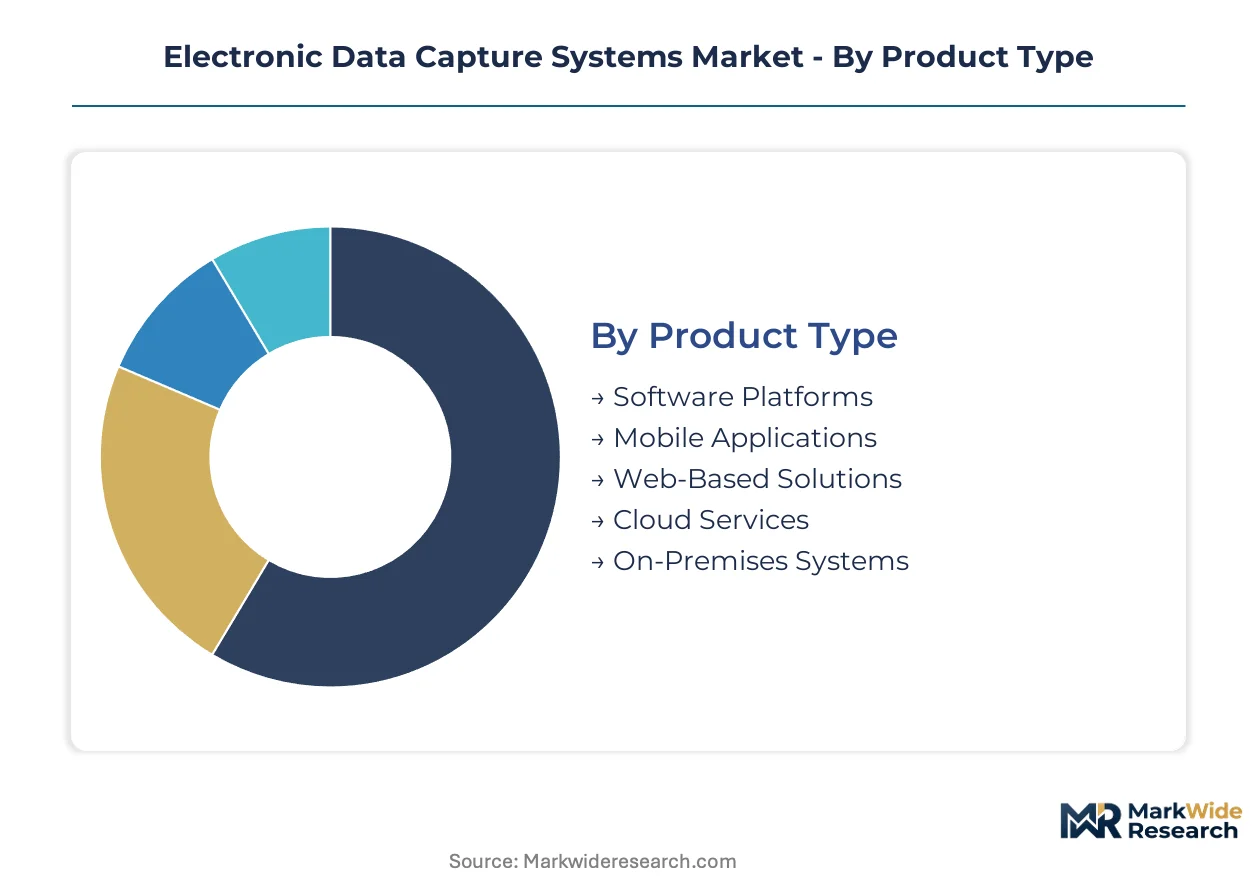
Electronic Data Capture Systems segment across four critical dimensions that shape procurement priorities and vendor positioning. Each axis reflects distinct technical requirements, regulatory constraints, and buyer budget cycles that determine competitive outcomes.
Product Type:
Cloud-native architectures now dominate platform roadmaps, displacing legacy validated environments through elastic infrastructure and reduced IT overhead.
- Software Platforms:Core enterprise-grade systems deliver configurable electronic case report forms, audit trails, and role-based access controls. Pharmaceutical sponsors in the United States and Germany anchor demand through multi-year enterprise agreements requiring 21 CFR Part 11 validation documentation.
- Cloud Services:Elastic compute and storage infrastructure enables Contract Research Organizations to scale trial capacity without capital expenditure. FDA guidance on computerized systems validation in cloud environments is accelerating procurement among mid-market biotech sponsors seeking rapid deployment.
- Mobile Applications:Native iOS and Android interfaces capture patient-reported outcomes and electronic diaries at the point of care.
- Web-Based Solutions:Browser-accessible platforms eliminate installation requirements for site coordinators across distributed trial networks.
- On-Premises Systems:Legacy validated environments persist in pharmaceutical companies with stringent internal IT governance protocols and historical trial data retention requirements.
Software Platforms lead on scale; Cloud Services lead on momentum.
Deployment Mode:
Study design complexity and patient access strategies are forcing sponsors to abandon rigid centralized models in favor of adaptive architectures.
- Decentralized:Direct-to-patient data flows integrate wearable biometrics, telemedicine endpoints, and home health nursing visits. EMA ICH E6(R2) risk-based monitoring guidelines and evolving FDA decentralized trial guidance are accelerating adoption among oncology and rare disease sponsors.
- Hybrid:Blended site-centric and remote capture models balance regulatory familiarity with patient convenience. Academic medical centers in the United States leverage hybrid deployments to maintain traditional principal investigator oversight while reducing patient travel burden.
- Centralized:Traditional site-based data capture through investigative sites remains prevalent in Phase III cardiovascular and metabolic studies requiring complex physical assessments.
- Hosted:Vendor-managed private cloud instances deliver isolated infrastructure for sponsors with data residency requirements.
- Managed:Full-service deployment including system administration, user support, and regulatory documentation outsourcing.
Centralized deployments retain installed base dominance; Decentralized architectures are climbing the fastest.
Application:
Regulatory pathway and data source diversity are fragmenting platform requirements across therapeutic development stages.
- Clinical Trials:Interventional studies across Phase I-III demand comprehensive adverse event capture, protocol deviation tracking, and statistical analysis dataset generation. Contract Research Organizations in the United States and United Kingdom concentrate procurement for global multi-site oncology and immunology programs.
- Real-World Evidence:Observational data capture from electronic health records, claims databases, and patient registries supports regulatory submissions and health technology assessments. EMA's evolving framework on real-world data quality is expanding platform requirements in France and Germany.
- Patient Registries:Longitudinal disease surveillance and natural history studies track treatment patterns and outcomes across extended follow-up periods.
- Medical Device Studies:Post-market surveillance and pre-market approval trials for implantable and diagnostic devices require specialized adverse event coding and device-specific endpoint capture.
- Pharmacovigilance:Post-marketing safety surveillance integrates individual case safety reports with aggregate data mining for signal detection.
Clinical Trials lead on scale; Real-World Evidence is gaining share fastest.
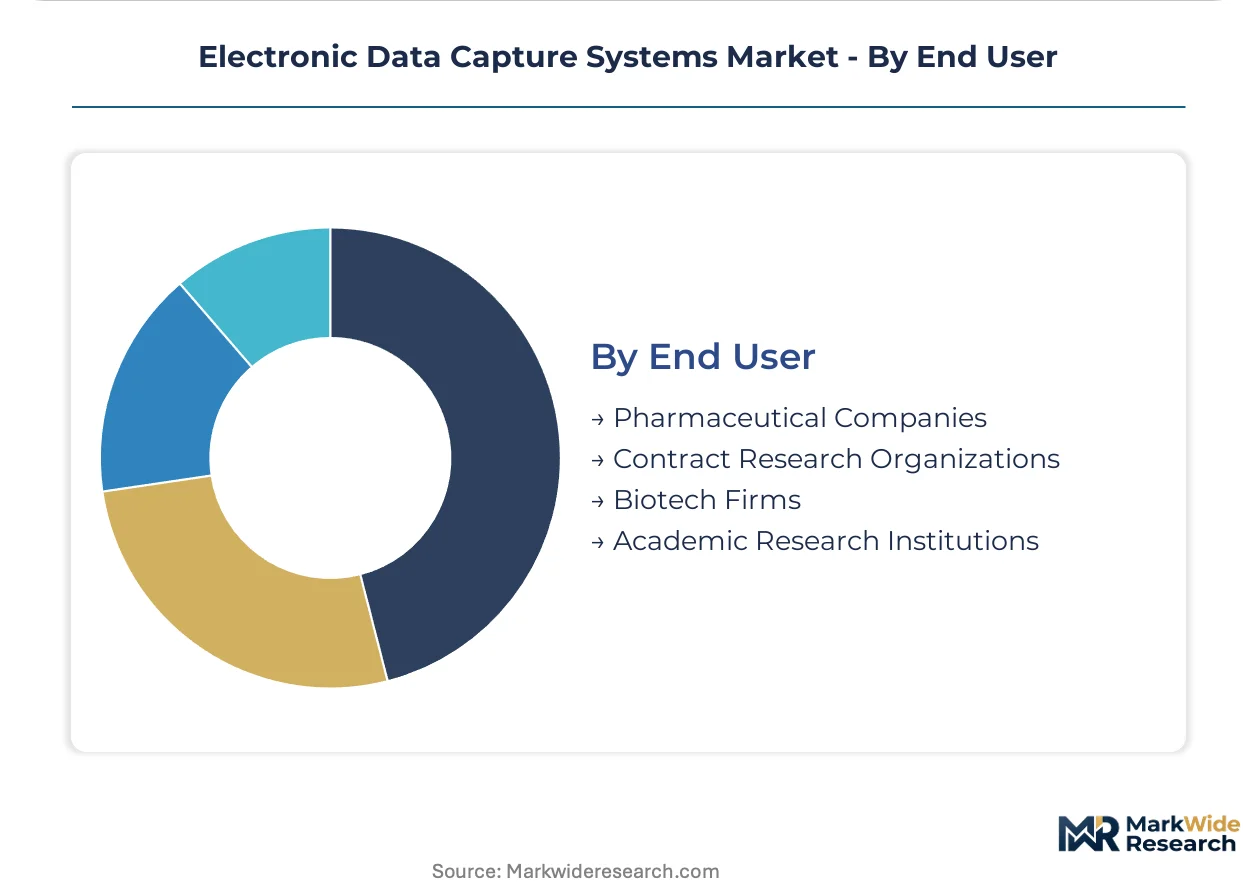
End User:
Buyer sophistication and procurement authority vary sharply across sponsor types, dictating sales cycle length and implementation complexity.
- Contract Research Organizations:Multi-sponsor service providers prioritize platform interoperability, rapid study build capabilities, and cross-sponsor data standardization. IQVIA, Parexel, and PRA Health Sciences drive volume through preferred vendor agreements with established EDC platforms.
- Biotech Firms:Venture-funded emerging sponsors with variable pipeline velocity favor subscription-based access and rapid deployment timelines. Boston and San Diego biotech clusters are displacing perpetual license structures with consumption-based pricing for storage and user seats.
- Pharmaceutical Companies:Large-cap sponsors maintain entrenched validated environments and multi-year enterprise agreements requiring extensive customization.
- Academic Research Institutions:NIH-funded investigators and public health research networks present channel expansion potential with distinct budget cycles and open-source preferences.
Pharmaceutical Companies lead on scale; Biotech Firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially higher EDC procurement volumes than Germany, though both markets now face converging pressure to validate cloud-native architectures under divergent regulatory timelines.
United States
FDA 21 CFR Part 11 mandates electronic signature validation and audit trail integrity, compelling pharmaceutical sponsors in Boston and San Diego to accelerate replacement cycles for legacy paper-dependent systems. NIH funding concentration at academic medical centers drives sustained demand from public health research networks. Contract Research Organizations with multi-site global studies anchor procurement decisions through preferred vendor agreements.
Germany
EMA ICH E6(R2) risk-based monitoring guidelines integrate automated query management into core platform requirements for mid-size Contract Research Organizations piloting AI-enabled capabilities. The country's national pharmaceutical regulator enforces computerized systems validation standards that exceed FDA granularity for data residency documentation. Bavaria-based clinical research units leverage hybrid deployment models to maintain principal investigator oversight while reducing patient travel burden.
United Kingdom
Contract Research Organizations in London and Cambridge concentrate procurement for global multi-site oncology programs requiring comprehensive adverse event capture. MHRA alignment with EMA guidelines simplifies cross-border trial execution for sponsors operating across EU member states. Academic research institutions with established EU Qualified Person networks accelerate platform certification to capture sponsor decisions.
India
CDSCO data integrity standards force redundant compliance investments for vendors seeking market access across Asia-Pacific regulatory jurisdictions. Hyderabad and Bangalore host emerging biotech sponsors favoring subscription-based access models over perpetual license structures. The country's national pharmaceutical regulator imposes parallel validation requirements that complicate migration from legacy validated environments.
Japan
PMDA electronic records standards shape product development roadmaps for vendors targeting Asia-Pacific expansion beyond China and India. Tokyo-based pharmaceutical sponsors maintain entrenched validated environments with stringent internal IT governance protocols. The regulator's emphasis on audit trail integrity drives replacement cycles for systems lacking real-time monitoring capabilities.
Electronic Data Capture Systems Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade platform providers commanding multi-year agreements while mid-market accessibility vendors capture emerging biotech procurement through rapid deployment timelines. The vendor base concentrates around three strategic archetypes: cloud-native architects competing on elastic infrastructure, ecosystem integrators leveraging broader clinical development suites, and deployment specialists optimizing for variable pipeline velocity. M&A activity targets complementary data visualization capabilities, while strategic partnerships with Contract Research Organizations lock in preferred vendor status for global multi-site studies.
Within the enterprise-scale tier, Medidata Rave and Oracle Clinical One exemplify divergent competitive strategies—one anchoring cloud-native architecture across North American and European deployments, the other sustaining deep integration with broader clinical development suites. Castor EDC occupies a position within the mid-market accessibility vector, representing vendors that differentiate through subscription-based pricing and rapid study build capabilities for emerging biotech sponsors in Boston and San Diego.
| Leading Market Players |
|---|
| Viedoc |
| Medrio |
| Medidata Rave |
| ClinCapture |
| Clinion EDC |
| Oracle Clinical One |
| Castor EDC |
| OpenClinica |
| Veeva Vault EDC |
| Others |
Cost & Logistics Intelligence
Backward integration into cloud infrastructure anchors supply positions for Electronic Data Capture Systems vendors while simultaneously determining pricing power across subscription tiers. Vendors with captive data center capacity in the United States and Germany command premium positioning against competitors sourcing compute through third-party hyperscalers.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for EDC platforms serving mid-market biotech sponsors. Three-tier pricing structure across premium, standard, and economy levels dominates procurement decisions, with FDA 21 CFR Part 11 certification tier and deployment velocity serving as primary differentiation drivers. Cost compression in the economy tier is intensifying because emerging sponsors prioritize month-to-month scalability over multi-year enterprise commitments. Biotech firms in Boston and San Diego exhibit highest price sensitivity, while large-cap pharmaceutical sponsors demonstrate lowest sensitivity due to entrenched validated environment requirements.
Supply Chain Analysis
Direct-to-sponsor channels handle enterprise-grade platform demand, while partner-mediated distribution serves emerging biotech procurement through Contract Research Organization preferred vendor networks. Software development concentrates in the United States, Germany, and India, with regulatory documentation and validation services anchored in the United States and United Kingdom. Platform architectures rest on cloud compute, cybersecurity frameworks, and specialized clinical data management talent pools. Single-source vulnerability in qualified regulatory affairs personnel creates bottlenecks for rapid deployment timelines. Distribution runs through vendor direct sales for enterprise agreements and CRO channel partnerships for mid-market accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic Data Capture Systems function as a stable compounder, with FDA 21 CFR Part 11 compliance mandates driving steady replacement cycles across pharmaceutical sponsor installed bases.
For Market Incumbents: Anchor cloud-native architecture investments against emerging AI-enabled entrants threatening query automation capabilities. Prioritize certification maintenance for EMA ICH E6(R2) guidelines to defend European market position. Capacity addition in Germany for EU data residency controls serves as the critical lever for sustaining premium pricing against mid-market challengers.
For New Entrants and Emerging Players: Enter via direct-to-patient capture modules for decentralized oncology trials, where FDA guidance evolution creates immediate white space. Target academic medical centers and NIH-funded research networks as the most penetrable buyer segment, given their distinct procurement cycles and under-served status relative to commercial pharmaceutical procurement. Position through rapid deployment timelines measured in days rather than months.
For Investors and Strategic Acquirers: Roll-up economics work for mid-market accessibility vendors because sponsor fragmentation across emerging biotech clusters prevents single-platform dominance. Long-term viability rests on recurring revenue depth rather than perpetual license conversion. Target acquisition archetype: cloud-native platforms with established CRO channel partnerships. Monitor FDA guidance publication timelines on decentralized trials as the signal to watch for inflection in direct-to-patient module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Query Automation | Medidata Rave and Oracle Clinical One embed machine learning to compress database lock timelines for Phase II oncology studies. |
| Cloud Infrastructure Expansion | Castor EDC leverages elastic compute to serve emerging biotech sponsors with consumption-based pricing in Boston and San Diego clusters. |
| Regulatory Certification Investment | Veeva Vault EDC maintains FDA 21 CFR Part 11 validation documentation to anchor enterprise pharmaceutical procurement decisions. |
| Strategic CRO Partnership | IQVIA and Parexel preferred vendor agreements lock in platform adoption for global multi-site immunology programs. |
| Wearable Device Integration | OpenClinica pilots biometric data capture modules for EMA ICH E6(R2) risk-based monitoring compliance in rare disease trials. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with clinical data management executives, regulatory affairs leads at pharmaceutical sponsors, Contract Research Organization procurement directors, and academic medical center IT governance officers. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA ICH E6(R2) guidelines, ClinicalTrials.gov protocol registries, and CDSCO data integrity standards. Bottom-up trial volume estimates and top-down platform spend analysis triangulated market sizing.
Comparable-period anchoring linked historical EDC adoption patterns to projected decentralized trial penetration rates across the analysis window. Segmentation dimensions modeled include deployment mode, end-user archetype, therapeutic area focus, and regional regulatory cluster. CAGRs derived from sponsor R&D budget elasticity and platform replacement cycle compression. Forecast inputs incorporated NIH funding allocation trends and EMA cloud validation guidance evolution.
Inputs from clinical trial registries and sponsor disclosure filings were available through the study window; gaps in real-time decentralized trial adoption metrics introduce uncertainty bands around direct-to-patient capture projections. Forecasts reflect documented assumptions regarding regulatory timeline acceleration and biotech venture funding velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Global Health Kiosk Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Healthcare Digital Signage Market
Digital Health Solutions
Digital Twins in Healthcare Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Global Behavioral/Mental Health Software Market
Digital Health Solutions
Vaccine Management Software Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Telepsychiatry Software Market
Digital Health Solutions
Smart Cards in Healthcare Market
Digital Health Solutions
Women Digital Health Solutions Market