
 Mhealth Market | 2026-2036
Mhealth Market Size, Share, and Industry Trends Forecast 2026-2036
Mhealth Market Analysis
Edge AI processing on smartphones and wearables is rewriting how mHealth applications deliver real-time diagnostics without cloud dependency. Apple Inc. leverages its silicon ecosystem to sustain tight integration between sensors and health algorithms. Samsung Electronics anchors its position through Galaxy Watch biometric accuracy and FDA-cleared ECG functionality. Teladoc Health, Inc. competes by dominating virtual care channel control across employer and payer networks.
mHealth encompasses portable digital health technologies that transmit, store, or analyze physiological data through wireless connectivity, typically operating on Bluetooth Low Energy protocols with cloud backend architectures to enable continuous patient monitoring outside clinical settings. Wearable Devices and Remote Patient Monitoring command the largest revenue pools due to recurring hardware replacement cycles and subscription-based data services, while Artificial Intelligence within the Technology segment is expanding fastest as predictive algorithms reduce false alerts in chronic disease management. Mobile Apps remain the most fragmented category with low barriers to entry, though FDA 510(k) clearance requirements are raising the threshold for clinical-grade offerings.
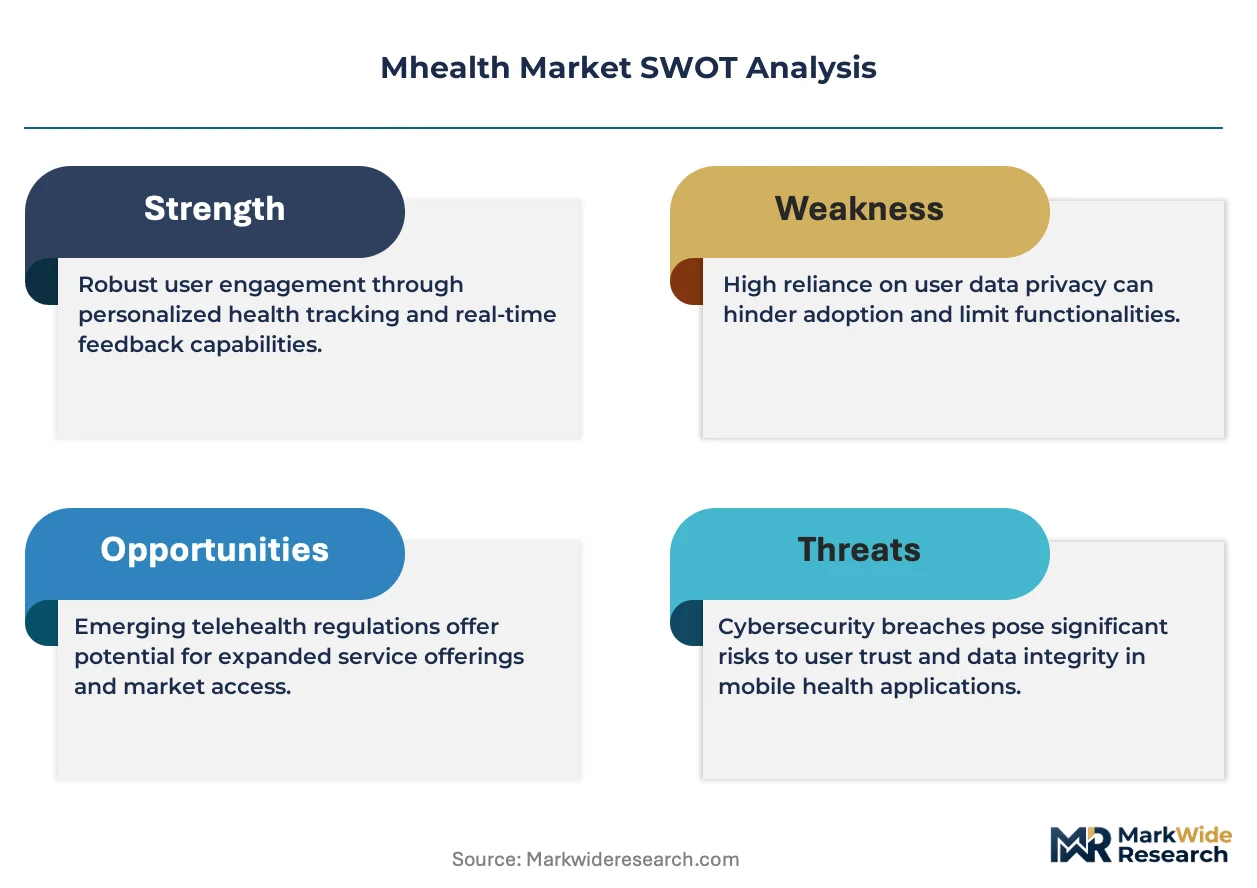
FDA premarket oversight and HIPAA privacy rules in the United States constrain how mHealth vendors collect and share patient data, directly shaping product architecture and liability exposure for cross-border data flows. The European Medicinal Agency's MDR framework and GDPR data localization mandates impose parallel compliance burdens on devices entering EU markets. Stakeholders must monitor evolving reimbursement codes from CMS and national health systems, as payment parity between telehealth and in-person visits will determine which mHealth business models achieve sustainable unit economics.
Market Dynamics
Edge AI processing is compressing diagnostic latency from cloud-dependent architectures to on-device inference, forcing vendors to redesign hardware-software stacks around smartphone and wearable silicon capabilities.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for software-as-a-medical-device products enable faster commercialization of algorithm-driven diagnostic tools in the United States.
- India PLI scheme incentives:Domestic manufacturing subsidies for wearable devices reduce import dependency and lower hardware costs for telehealth infrastructure deployment.
- Bluetooth Low Energy 5.3 protocols:Extended range and reduced power consumption enable continuous glucose monitoring and cardiac telemetry in ambulatory settings without patient behavior disruption.
Market Restraints
- HIPAA compliance architecture costs:End-to-end encryption requirements and business associate agreement overhead inflate operational expenditure for cross-border data flows.
- EU MDR technical documentation burdens:Clinical evidence requirements for Class IIa and above devices extend time-to-market by 18-24 months compared to previous directives.
- Lithium-polymer battery supply concentration:Cathode material processing dependence on East Asian refining capacity creates input cost volatility and forced stockpiling.
Strategic Opportunities
- Rural India connectivity gaps:Satellite-enabled telehealth kiosks and offline-first diagnostic apps address physician density below WHO thresholds in Bihar and Uttar Pradesh.
- AI-ECG convergence:Deep learning algorithms trained on photoplethysmography signals enable atrial fibrillation detection on consumer wearables without dedicated electrodes.
- Employer direct contracting channels:Self-insured corporations bypass traditional payer networks to purchase population health monitoring as a bundled per-employee-per-month service.
Industry Challenges
- Clinical validation talent scarcity:Biostatisticians with regulatory-grade trial design experience command premium compensation and extend recruitment cycles.
- EMR integration complexity:HL7 FHIR implementation gaps between proprietary hospital systems and consumer-facing apps require costly middleware development.
- Interoperability standard fragmentation:Competing frameworks between IEEE 11073, Continua, and proprietary protocols force multi-certification strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mhealth Market |
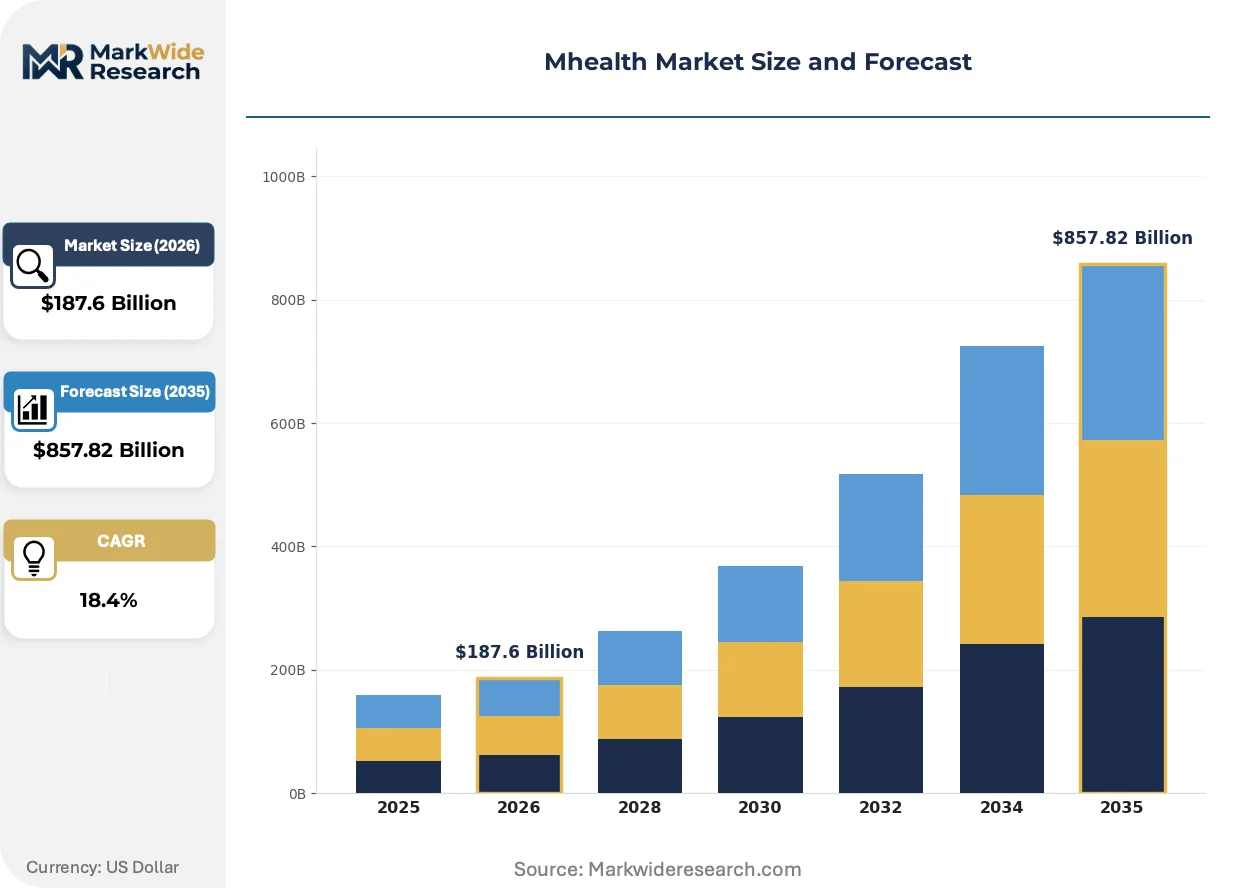
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Telemedicine Solutions, Remote Patient Monitoring Technology: Bluetooth, Cloud Computing, Artificial Intelligence, Big Data Analytics End User: Consumers, Healthcare Providers, Pharmaceutical Companies, Insurance Firms Application: Chronic Disease Management, Fitness Tracking, Mental Health Monitoring, Preventive Care |
| Companies Covered | Apple Inc., Samsung Electronics, Teladoc Health, Inc., Medtronic, Koninklijke Philips N.V., Abbott, AT&T, Qualcomm Technologies, Inc., Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mhealth Market Emerging Trajectories
Diagnostic workflows are migrating from centralized laboratory infrastructure to distributed point-of-care nodes, compressing the value chain between sensor capture and clinical decision.
Federated learning architectures are virtualizing model training across decentralized device populations without raw data centralization. Hospital systems and pharmaceutical sponsors adopt this approach to access diverse patient cohorts while respecting HIPAA and GDPR data residency constraints. The technique compresses regulatory exposure for multi-site trials and enables real-world evidence generation at population scale.
The European Medicinal Agency's MDR framework tightens post-market surveillance requirements for connected health devices, mandating periodic safety update reports and proactive incident reporting. Manufacturers must maintain clinical evidence throughout the product lifecycle, not just at premarket submission. Class IIa software devices face heightened scrutiny, pushing vendors toward notified body partnerships earlier in development cycles.
Self-insured employers now demand outcome guarantees from virtual care platforms, shifting payment from per-visit fees to condition-specific bundled arrangements. Chronic disease management vendors respond with risk-sharing contracts tied to hospitalization reduction metrics. This restructuring concentrates in the United States employer-sponsored insurance segment, where CFOs seek measurable ROI on wellness expenditures.
Mhealth Market Segmentation
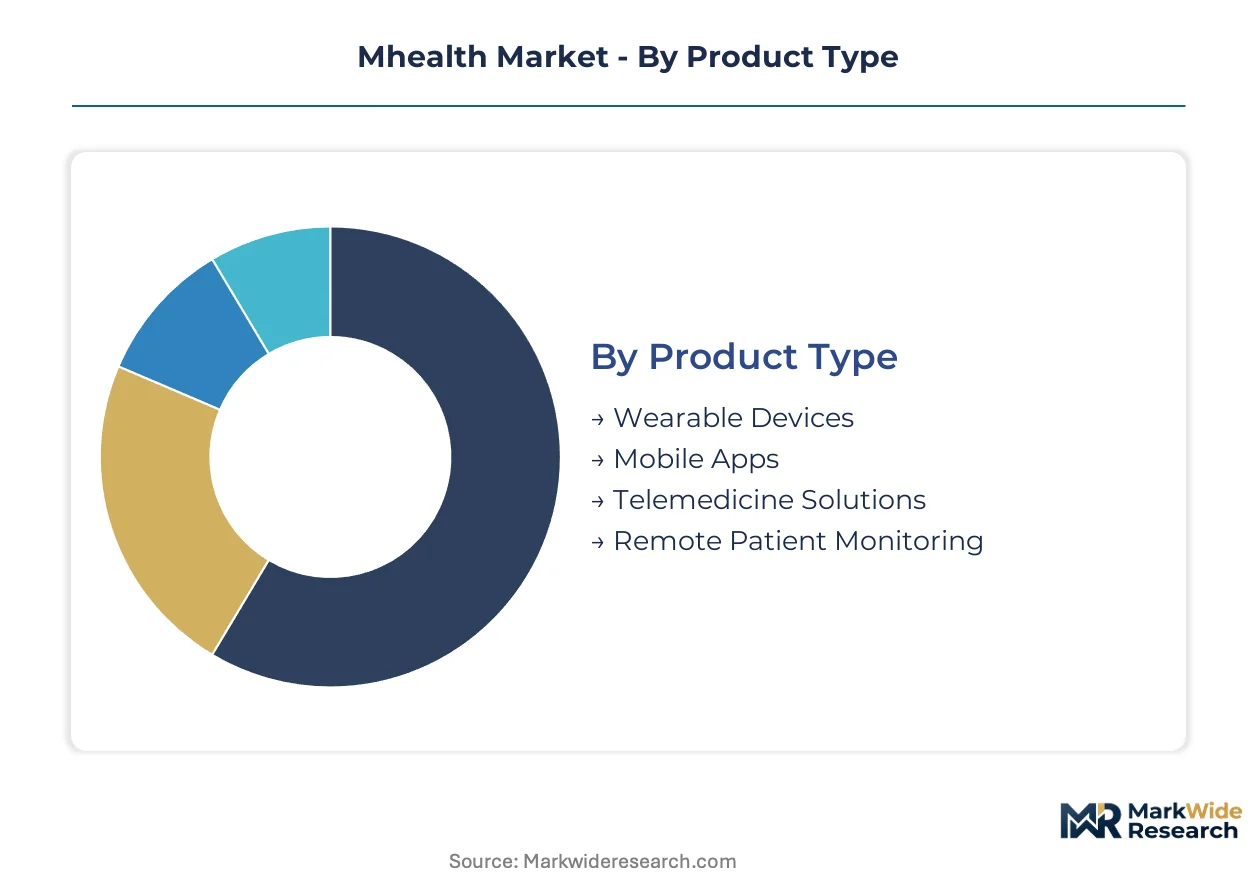
mHealth segmentation reveals divergent hardware replacement cycles, software monetization models, and regulatory pathways that shape vendor strategy. Product type determines capital intensity and margin structure, while technology choices dictate cloud infrastructure spend and FDA clearance complexity.
Product Type:
Use-case spectrum spans consumer wellness devices, clinical-grade diagnostics, and enterprise telehealth platforms with distinct reimbursement codes.
- Wearable Devices:Continuous physiological sensors operating on Bluetooth Low Energy 5.3 protocols capture ECG, SpO2, and glucose data for ambulatory monitoring. Hospital systems in the United States prioritize FDA-cleared units for remote patient monitoring programs reimbursed under CMS codes.
- Remote Patient Monitoring:Cloud-connected biometric hubs transmit data to clinical decision support systems, enabling chronic disease management outside facility walls. Indian healthcare providers deploy these devices through PLI-subsidized procurement to address physician density gaps in Bihar and Uttar Pradesh.
- Mobile Apps:Software interfaces for symptom tracking and medication adherence with lower hardware overhead.
- Telemedicine Solutions:Video consultation platforms integrating with hospital EMR systems via HL7 FHIR protocols.
The dominant share belongs to Wearable Devices, while Remote Patient Monitoring is closing the gap fastest.
Technology:
Cost tier separates commodity connectivity from premium inference capabilities requiring specialized silicon.
- Artificial Intelligence:Edge-deployed neural networks enable real-time arrhythmia detection and predictive glucose forecasting without cloud latency. Federated learning architectures train models across decentralized device populations while respecting HIPAA and GDPR data residency constraints.
- Cloud Computing:Scalable backend infrastructure processes multi-terabyte biometric streams from millions of concurrent devices. United States providers face HIPAA business associate agreement overhead that inflates operational expenditure for cross-border data flows.
- Bluetooth:Low-power wireless protocols enabling continuous sensor-to-smartphone transmission.
- Big Data Analytics:Population-level pattern recognition for epidemiological surveillance and clinical trial recruitment.
Artificial Intelligence commands premium pricing, whereas Bluetooth penetration is already saturating entry-level hardware.
End User:
Customer type determines procurement authority, budget cycle timing, and outcome accountability structures.
- Healthcare Providers:Hospital systems and physician practices purchasing FDA-cleared devices for billable remote monitoring services. United States providers navigate CMS reimbursement code evolution to achieve payment parity with in-person visits.
- Insurance Firms:Payers and self-insured employers demanding outcome guarantees from virtual care platforms. Risk-sharing contracts tied to hospitalization reduction metrics restructure payment from per-visit fees to bundled per-employee-per-month arrangements.
- Consumers:Individual purchasers of wellness trackers and direct-to-consumer telehealth subscriptions.
- Pharmaceutical Companies:Clinical trial sponsors deploying mHealth for decentralized real-world evidence generation.
Healthcare Providers account for the largest revenue pool, though Insurance Firms are expanding fastest through employer direct contracting channels.
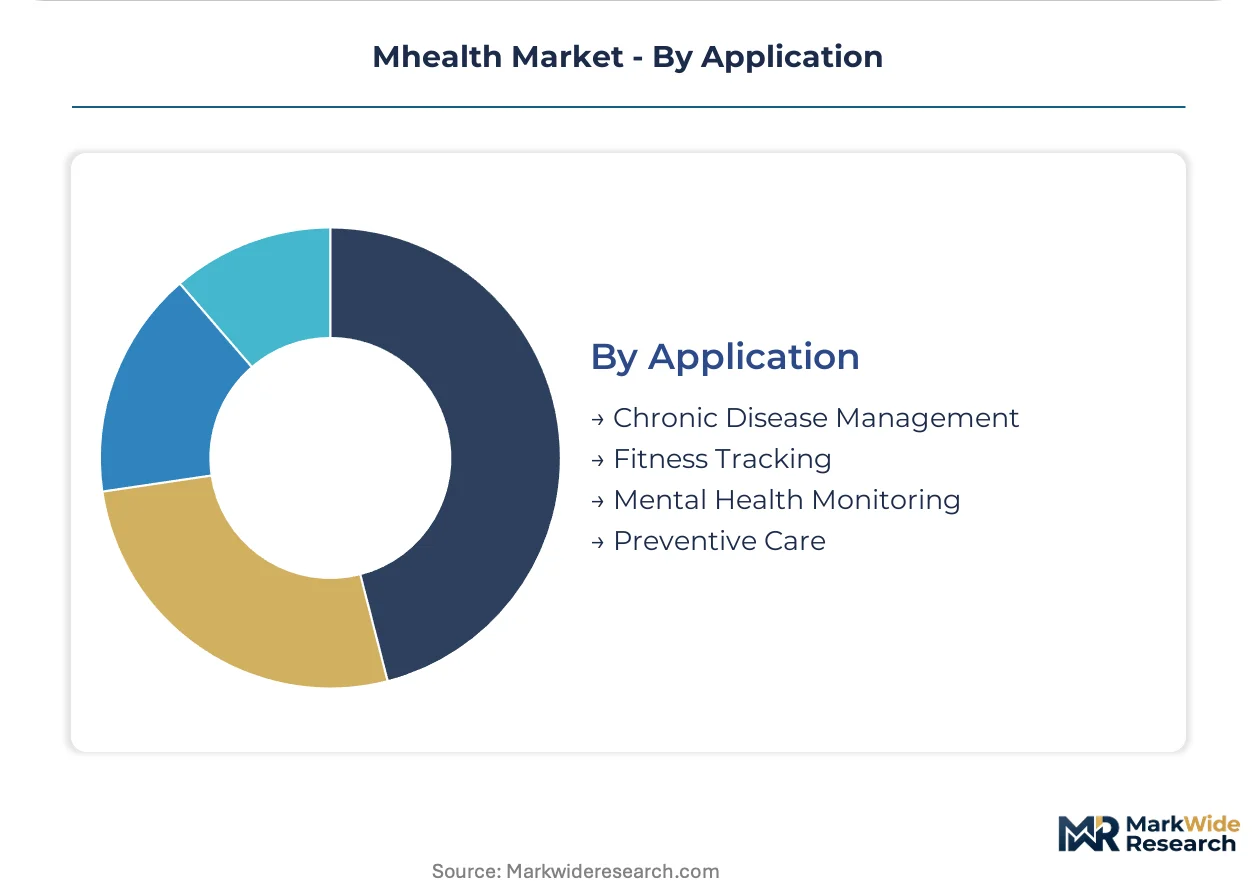
Application:
Volume concentration tracks chronic disease prevalence and reimbursement code availability across geographies.
- Chronic Disease Management:Diabetes, hypertension, and heart failure monitoring programs with established CPT codes in the United States. Predictive algorithms reduce false alerts and nurse triage burden, improving unit economics for value-based care contracts.
- Mental Health Monitoring:Digital phenotyping through smartphone sensor data and ecological momentary assessment tools. European deployments face GDPR technical documentation burdens that extend time-to-market compared to United States pathways.
- Fitness Tracking:Consumer wellness metrics with minimal regulatory oversight and hardware replacement cycles.
- Preventive Care:Population screening programs targeting early intervention before acute episodes.
Chronic Disease Management holds the installed base advantage, while Mental Health Monitoring is gaining share fastest through employer wellness mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports wearable devices and telehealth infrastructure components to healthcare systems across Southeast Asia and the Middle East, leveraging PLI scheme subsidies to undercut Chinese hardware pricing in price-sensitive procurement markets.
United States
Hospital systems in Texas and California deploy FDA-cleared remote patient monitoring devices under evolving CMS reimbursement codes. HIPAA business associate agreements constrain cross-border data architecture decisions for cloud backend providers. The Boston-Cambridge corridor concentrates digital health venture capital and clinical validation partnerships with academic medical centers.
Germany
Industrial employers in Bavaria and Baden-Württemberg purchase population health monitoring as bundled per-employee-per-month services from virtual care platforms. EMA MDR technical documentation requirements extend time-to-market for Class IIa software devices by 18-24 months compared to previous directives. The Berlin-Brandenburg region hosts federated learning research consortia linking university hospitals with wearable manufacturers.
India
Healthcare providers in Maharashtra and Karnataka deploy PLI-subsidized biometric hubs to address physician density gaps below WHO thresholds in Bihar and Uttar Pradesh. CDSCO medical device rules and state-level telemedicine guidelines shape product registration pathways for domestic and imported devices. The Delhi-NCR corridor concentrates telehealth platform development and satellite-enabled rural connectivity pilots.
China
Consumer electronics manufacturers in the Pearl River Delta integrate photoplethysmography sensors into wearables for domestic diabetes and hypertension management programs. NMPA medical device registration requirements and MIIT data localization rules constrain foreign cloud backend deployments. The Yangtze River Delta hosts AI-ECG algorithm development clusters serving both domestic hospital systems and export markets.
United Kingdom
NHS Integrated Care Systems in England pilot outcome-based contracts with virtual care platforms tied to hospitalization reduction metrics. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR frameworks while streamlining software-as-a-medical-device pathways. The Oxford-Cambridge arc concentrates digital biomarker startups and clinical AI validation partnerships with pharmaceutical sponsors.
Mhealth Market Vendor Landscape
On the supply side, the industry is bifurcated between integrated consumer electronics conglomerates and specialized healthcare technology vendors. Smartphone and semiconductor ecosystems dominate hardware-software stack control through captive silicon design. Three strategic archetypes prevail: sensor-integrated device manufacturers, virtual care platform operators, and clinical-grade diagnostic specialists. Competitive intensity manifests through FDA clearance racing and employer direct contracting channel capture.
Within the integrated technology tier, Apple Inc. and Samsung Electronics exemplify hardware-software ecosystem control through proprietary sensor-algorithm integration and consumer brand leverage. Teladoc Health, Inc. occupies a position representing virtual care channel dominance across employer and payer networks. These three entities anchor distinct competitive vectors—consumer wellness conversion, clinical-grade hardware certification, and population health contract scale—that structure rivalry across the mHealth value chain.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Teladoc Health, Inc. |
| Medtronic |
| Koninklijke Philips N.V. |
| Abbott |
| AT&T |
| Qualcomm Technologies, Inc. |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
Lithium-polymer cathode processing capacity in South Korea and China concentrates margin capture upstream, while FDA-cleared device manufacturers in the United States and Germany absorb certification premiums downstream. This geographic asymmetry between raw material refining and clinical-grade assembly shapes where pricing power accumulates across the mHealth value chain.
Pricing Analysis
Bluetooth Low Energy 5.3-enabled wearables command 40-60% premiums over prior-generation 4.2 protocol devices due to extended range and reduced power draw. Pricing stratifies across three tiers: FDA-cleared clinical units with CMS reimbursement codes, CE-marked wellness devices for European consumers, and uncertified economy hardware for price-sensitive emerging markets. Cost compression in the economy tier intensifies as Indian PLI-subsidized manufacturers expand capacity. Healthcare providers demonstrate lowest price sensitivity due to reimbursement pass-through mechanisms, while direct-to-consumer channels face acute elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for mHealth hardware vendors. Component sourcing concentrates in Taiwan for MEMS sensors, South Korea for advanced battery cells, and Malaysia for printed circuit board assembly. Lithium cobalt oxide cathodes and photoplethysmography optical modules represent critical single-source dependencies. Distribution runs through hospital GPO contracts in the United States, national health system tenders in Europe, and e-commerce direct-to-consumer channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mHealth market functions as a regulatory-moat arena where FDA 510(k) clearance histories and HIPAA-compliant cloud architectures create switching costs that entrench early movers. Network effects compound as hospital EMR integration depth increases patient data liquidity.
For Market Incumbents: Insulate installed base through exclusive hospital system partnerships that embed remote patient monitoring into standard care pathways. Deepen backward integration into sensor silicon design to reduce dependency on Taiwanese MEMS suppliers. Prioritize federated learning infrastructure investments that lock in pharmaceutical sponsor relationships for decentralized clinical trials.
For New Entrants and Emerging Players: Rural Indian states with physician density below WHO thresholds offer the most penetrable white-space for satellite-enabled telehealth kiosk deployment. Target employer direct contracting channels with bundled per-employee-per-month pricing that bypasses traditional payer network gatekeeping. Lead with offline-first diagnostic apps that function without continuous connectivity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed virtual care platforms that scaled during telehealth reimbursement expansion but now face outcome-guarantee contract restructuring. Five-to-ten year viability hinges on AI-ECG algorithm FDA clearance pipelines and chronic disease management risk-sharing contract performance. Monitor CMS reimbursement code evolution for remote patient monitoring as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined software-as-a-medical-device pathways compress time-to-revenue for algorithm-driven diagnostics. |
| Hospital System EMR Integration | HL7 FHIR protocol implementation locks in provider switching costs and secures recurring data subscription revenue. |
| Federated Learning Infrastructure | Decentralized model training respects HIPAA and GDPR constraints while accessing multi-site patient cohorts. |
| Employer Direct Contracting | Self-insured corporations purchase population health monitoring outside traditional payer network control. |
| PLI-Subsidized Manufacturing Scale | Indian domestic production incentives undercut Chinese hardware pricing in Southeast Asian export markets. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, GPO contracts managers, wearable device product managers, and telehealth platform executives. Secondary validation drew from FDA 510(k) clearance databases, CMS reimbursement code filings, CDSCO medical device registrations, and EU MDR notified body technical documentation. Bottom-up unit economics modeling triangulated against top-down market sizing from hospital procurement spend and employer wellness benefit allocations.
Calibration against historical adoption curves for remote patient monitoring and wearable device replacement cycles anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, technology tier, end-user procurement authority, and application reimbursement code availability. CAGRs were derived from fitted growth curves applied to installed base expansion and subscription pricing evolution. Forecast inputs incorporated Bluetooth protocol migration timelines and AI-ECG algorithm regulatory submission pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by consumer electronics conglomerates into clinical-grade diagnostics would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Pregnancy Tracking and Postpartum Care Apps Market
Digital Health Solutions
GCC E-Health Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Connected Health and Wellness Devices Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
Medically Prescribed Apps Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Europe Digital Health Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
US Advance Care Planning Solutions Market