
 Cardiovascular Digital Solutions Market | 2026-2036
Cardiovascular Digital Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Digital Solutions Market Analysis
The capital-intensity divergence between full-stack platform builders and point-solution developers is unwinding competitive dynamics across cardiovascular digital health. GE Healthcare leverages its installed base of imaging hardware to extend into AI-powered cardiac workflow integration. AliveCor, Inc. specializes in handheld ECG peripherals that anchor consumer-facing arrhythmia screening. Philips Healthcare competes through hospital-grade remote monitoring infrastructure that dominates enterprise procurement cycles.
Cardiovascular digital solutions encompass software, connected hardware, and analytics platforms designed to acquire, transmit, and interpret cardiac physiological data for clinical decision support. These systems integrate cloud architecture with algorithmic analysis to enable continuous or episodic monitoring of heart rhythm, hemodynamics, and structural function outside traditional catheterization or imaging suites. Wearable devices and remote monitoring systems currently occupy the largest addressable revenue pools, while AI analytics represents the fastest-expanding margin segment as payers increasingly reimburse predictive risk stratification. Mobile health platforms serve as the connectivity backbone, though their monetization remains concentrated in enterprise licensing rather than direct-to-patient subscription models.
FDA premarket notification pathways and the EU MDR framework impose distinct clinical validation requirements on algorithm-based diagnostic outputs, shaping R&D allocation and geographic launch sequencing for developers. HIPAA in the United States and GDPR across European jurisdictions create compliance cost differentials that favor vendors with established regulatory operations in both markets. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring and software-based interventions, as coverage determinations will dictate which technology configurations achieve sustainable unit economics.
Market Dynamics
Cloud-native AI architectures are compressing deployment timelines for cardiac diagnostic platforms, forcing incumbent hardware vendors to restructure R&D allocation toward software-centric delivery models.
Growth Catalysts
- EU MDR software-as-medical-device pathways:Streamlined conformity assessments for algorithm-based cardiac risk scoring accelerate European commercialization timelines.
- Remote therapeutic monitoring reimbursement codes:US CMS coverage determinations for continuous arrhythmia surveillance expand addressable patient populations beyond acute care settings.
- Edge computing integration:On-device inference capabilities reduce latency for real-time ECG analysis, enabling ambulatory monitoring without persistent cloud connectivity.
Market Restraints
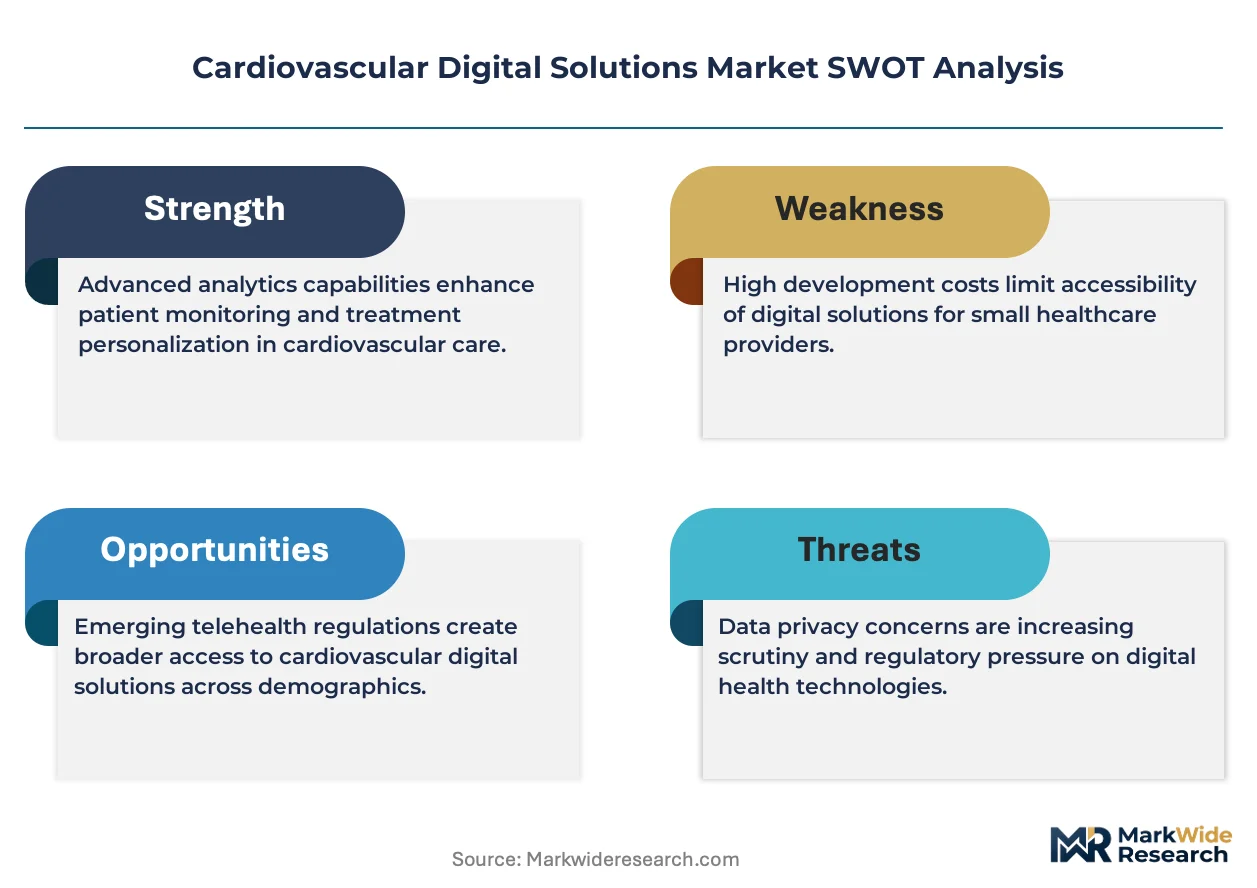
- GDPR-HIPAA compliance cost divergence:Dual-jurisdiction data governance requirements impose operational overhead that disadvantages mid-scale platform developers lacking established regulatory infrastructure.
- Cloud infrastructure concentration:Dependence on hyperscale providers for cardiac data storage creates vendor lock-in risks and pricing volatility for remote monitoring services.
- Interoperability fragmentation:Absence of unified data exchange standards between EHR systems and third-party cardiac analytics platforms limits workflow integration depth.
Strategic Opportunities
- Underpenetrated home-based heart failure monitoring:Japan's aging demographic and METI digital health subsidies create favorable reimbursement conditions for predictive decompensation alerts.
- AI-ECG multimodal fusion:Convergence of phonocardiography signals with electrical activity data enables structural-functional assessment without specialized imaging hardware.
- Direct-to-employer distribution channels:Self-insured corporations in Germany bypass traditional payer intermediaries to contract cardiovascular screening programs for workforce risk reduction.
Industry Challenges
- Clinical validation timeline compression:FDA 510(k) software modifications requiring new predicate device comparisons extend regulatory cycles for iterative algorithm updates.
- Embedded systems engineering scarcity:Shortage of firmware developers with FDA quality system regulation experience constrains wearable device pipeline velocity.
- Legacy EHR integration complexity:Proprietary data formats in established hospital information systems necessitate costly custom middleware development for seamless cardiac data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Digital Solutions Market |
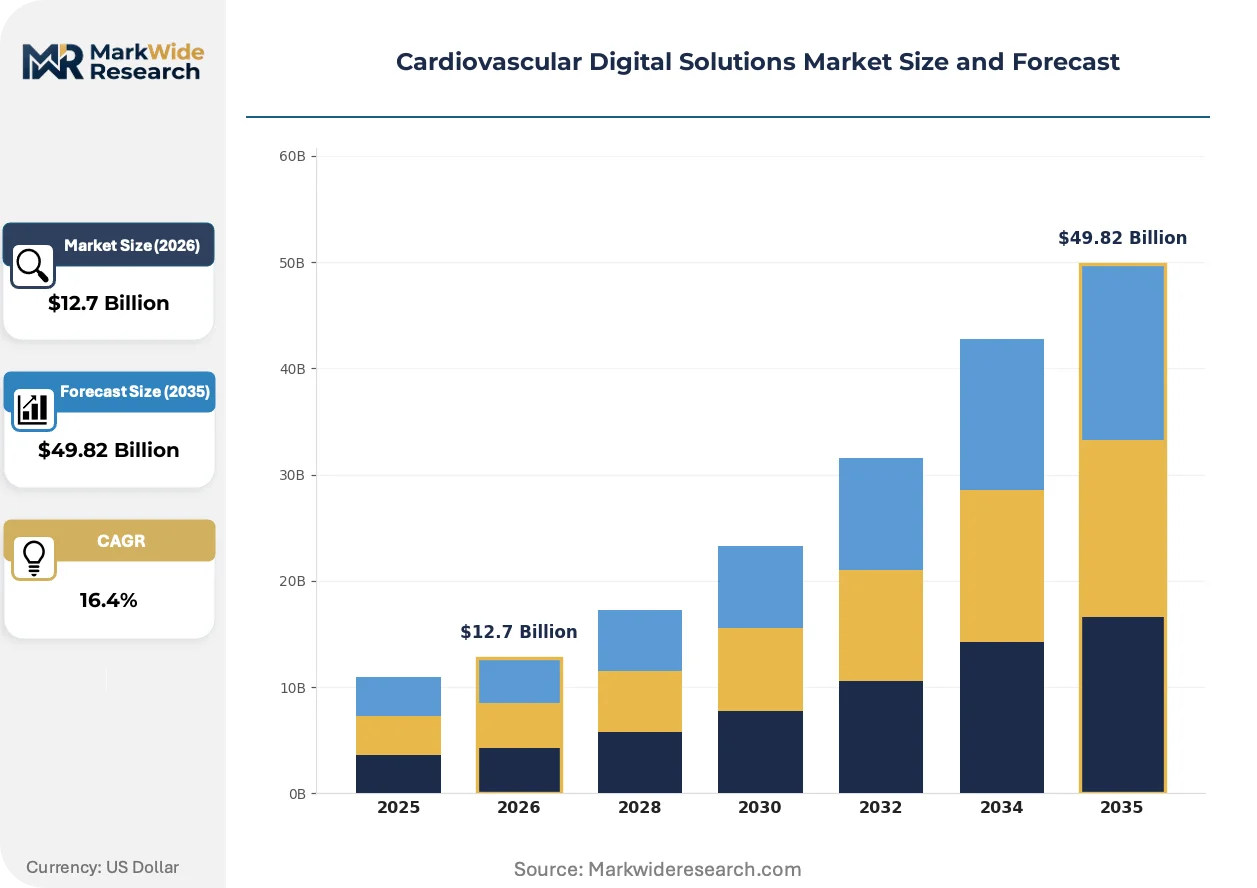
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $49.82 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Apps, Remote Monitoring Systems, Telehealth Solutions End User: Hospitals, Homecare Providers, Rehabilitation Centers, Patients Technology: Cloud-based Solutions, AI Analytics, Mobile Health Platforms, Big Data Integration Application: Disease Management, Patient Engagement, Health Monitoring, Data Analysis |
| Companies Covered | AliveCor, Inc., Apple Inc., iRhythm Technologies, Inc., GE Healthcare, Philips Healthcare, HeartFlow, Inc., Verily Life Sciences LLC, Medtronic, Baxter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Digital Solutions Market Emerging Trajectories
Algorithmic diagnostic modalities are fragmenting traditional cardiac care pathways, creating parallel tracks for hardware-anchored institutional deployment versus software-native distributed screening.
Photoplethysmography-based rhythm detection is bifurcating consumer wearables from clinical-grade monitoring. Apple Watch and Samsung Galaxy devices incorporate FDA-cleared irregular rhythm notifications for mass-market screening. Hospital procurement committees now distinguish between wellness-adjacent consumer devices and reimbursable diagnostic peripherals, compressing pricing power for mid-tier hardware vendors lacking clear regulatory differentiation.
MDR Article 10 clinical evidence requirements for software-as-medical-device classifications intensify post-market surveillance obligations across European Economic Area jurisdictions. Manufacturers must maintain systematic data collection on algorithm performance in real-world conditions. Cardiac risk prediction modules face heightened scrutiny under this framework, prompting developers to establish prospective registry partnerships before commercial launch.
Hospital procurement committees now bundle cardiovascular digital solutions into enterprise imaging contracts rather than standalone software licenses. GE Healthcare and Philips leverage installed modality bases to anchor AI analytics within multi-year equipment service agreements. This channel consolidation disadvantages point-solution vendors lacking hardware adjacencies, particularly in German and Japanese hospital systems with centralized procurement hierarchies.
Cardiovascular Digital Solutions Market Segmentation
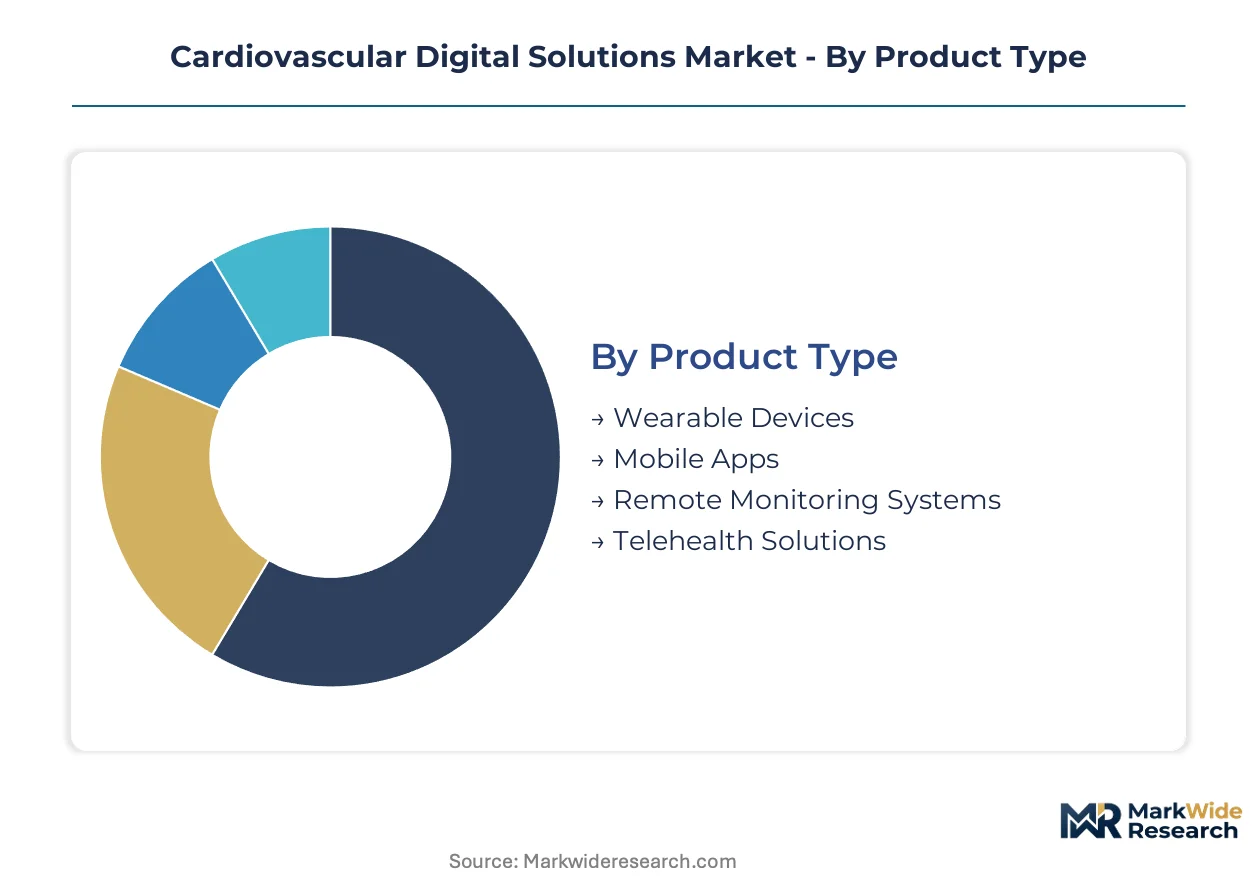
Segmentation in cardiovascular digital solutions reveals divergent commercialization pathways across hardware-centric and software-native deployment models. Product configuration dictates regulatory pathway complexity, while end-user concentration shapes pricing architecture and distribution economics.
Product Type:
Wearable Devices and Remote Monitoring Systems anchor domestic hospital procurement in Germany, Japan, and the United States, while Mobile Apps and Telehealth Solutions increasingly serve export-led distributed care models.
- Wearable Devices:Handheld ECG peripherals and photoplethysmography-enabled wristbands acquire cardiac electrical signals for episodic rhythm assessment. Hospital systems in the United States concentrate procurement through enterprise imaging contracts that bundle diagnostic hardware with AI analytics. FDA 510(k) clearance pathways impose clinical validation requirements that compress margin structures for iterative algorithm updates.
- Remote Monitoring Systems:Cloud-connected telemetry infrastructure enables continuous hemodynamic surveillance outside acute care settings. Japanese METI digital health subsidies accelerate adoption for home-based heart failure monitoring among aging demographics. Reimbursement codes for remote therapeutic monitoring in the United States expand addressable patient populations beyond traditional catheterization suites.
- Mobile Apps:Software interfaces serve as connectivity backbones between patients and clinical decision support systems.
- Telehealth Solutions:Synchronous and asynchronous consultation platforms integrate cardiac data streams into virtual care workflows.
Wearable Devices commands the established base. The steepest expansion runs through Remote Monitoring Systems.
End User:
Cost tier differentiation separates capital-intensive hospital deployments from subscription-based homecare and patient-direct models with lower upfront infrastructure requirements.
- Hospitals:Enterprise procurement committees bundle cardiovascular digital solutions into multi-year equipment service agreements with imaging modality vendors. German and Japanese hospital systems with centralized procurement hierarchies favor full-stack platform builders over point-solution developers. Cloud infrastructure concentration creates vendor lock-in risks for cardiac data storage.
- Homecare Providers:Distributed nursing services leverage remote monitoring infrastructure to manage post-acute cardiac patients outside institutional settings. GDPR-HIPAA compliance cost divergence disadvantages mid-scale platform developers lacking established regulatory operations in both jurisdictions. Predictive decompensation alerts for heart failure command premium pricing in reimbursed care pathways.
- Rehabilitation Centers:Cardiac recovery programs integrate wearable-derived telemetry into structured exercise protocols.
- Patients:Direct-to-consumer channels bypass traditional payer intermediaries for arrhythmia screening and wellness-adjacent monitoring.
Hospitals absorb the majority of current platform investment. Homecare Providers are gaining share fastest as reimbursement shifts toward ambulatory settings.
Technology:
Application maturity separates proven cloud architectures from emerging AI analytics segments where margin expansion outpaces revenue scale.
- Cloud-based Solutions:Scalable data infrastructure enables real-time cardiac telemetry ingestion across distributed patient populations. Dependence on hyperscale providers for storage and compute creates pricing volatility for remote monitoring services. EU MDR software-as-medical-device pathways streamline conformity assessments for algorithm-based platforms in European Economic Area jurisdictions.
- AI Analytics:Machine learning models interpret ECG signals, phonocardiography data, and multimodal physiological inputs for predictive risk stratification. Payers increasingly reimburse predictive cardiac risk scoring, expanding margin pools faster than hardware-centric segments. MDR Article 10 clinical evidence requirements intensify post-market surveillance obligations across deployed algorithms.
- Mobile Health Platforms:Connectivity middleware bridges wearable peripherals with clinical decision support systems.
- Big Data Integration:Population-scale cardiac registries enable algorithm training and real-world performance monitoring.
Cloud-based Solutions anchors current infrastructure deployment. AI Analytics climbs the fastest as reimbursement codes mature for software-based diagnostic outputs.
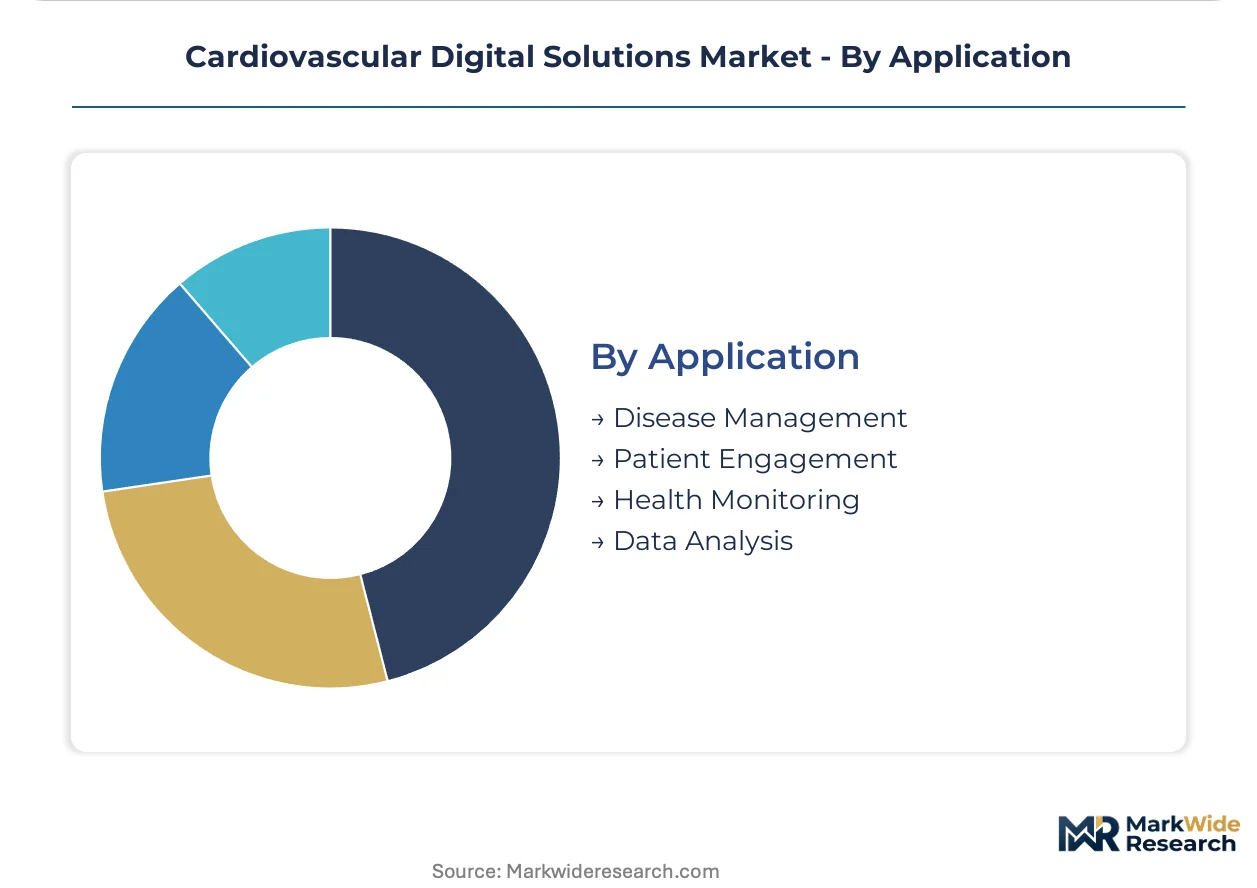
Application:
Customer workflow integration depth distinguishes institutional disease management platforms from patient-facing engagement tools with lighter EHR connectivity requirements.
- Disease Management:Structured protocols for heart failure, atrial fibrillation, and coronary artery disease integrate medication adherence, symptom tracking, and clinical escalation pathways. Proprietary data formats in legacy hospital information systems necessitate costly custom middleware development. Interoperability fragmentation limits workflow integration depth for third-party cardiac analytics platforms.
- Health Monitoring:Continuous or episodic physiological surveillance generates longitudinal cardiac data for trend analysis and early warning generation. Edge computing integration reduces latency for real-time ECG analysis without persistent cloud connectivity. Self-insured corporations in Germany bypass traditional payer intermediaries to contract cardiovascular screening programs for workforce risk reduction.
- Patient Engagement:Behavioral nudges and education modules improve medication compliance and lifestyle modification adherence.
- Data Analysis:Retrospective and prospective analytics support clinical research, quality improvement, and population health management.
Disease Management holds the deepest installed base. Health Monitoring shows the steepest trajectory as ambulatory reimbursement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany demonstrate the lowest price elasticity, bundling cardiovascular digital solutions into multi-year equipment service agreements. Japanese buyers exhibit intermediate sensitivity, responding to METI subsidy schedules for home-based monitoring. United States health systems show the highest elasticity, with standalone software vendors competing on per-patient pricing against integrated platform builders.
United States
CMS reimbursement codes for remote therapeutic monitoring drive hospital system procurement of continuous arrhythmia surveillance platforms. FDA 510(k) premarket notification pathways impose clinical validation requirements that compress margin structures for iterative algorithm updates. The Greater Boston cluster anchors health-tech venture formation, with digital health startups clustering around academic medical centers to access clinical validation partnerships.
Germany
Self-insured corporations bypass traditional payer intermediaries to contract cardiovascular screening programs for workforce risk reduction. EU MDR software-as-medical-device pathways streamline conformity assessments for algorithm-based cardiac risk scoring. Bavaria's medical technology corridor concentrates hospital procurement decision-making, with centralized procurement hierarchies favoring full-stack platform builders over point-solution developers.
Japan
METI digital health subsidies accelerate adoption of home-based heart failure monitoring among aging demographics. PMDA consultation pathways for software-as-medical-device classifications guide developers through clinical evidence requirements before market entry. The Kanto region around Tokyo hosts concentrated hospital system headquarters, where enterprise procurement committees bundle remote monitoring infrastructure into multi-year service agreements.
United Kingdom
NHS England integrated care systems pilot cardiovascular remote monitoring to reduce emergency department admissions for heart failure decompensation. MHRA software-as-medical-device guidance aligns with EU MDR clinical evidence requirements for algorithm-based diagnostic outputs. The London-Southeast corridor concentrates health-tech venture capital, with digital health startups positioning for procurement frameworks that favor cloud-native analytics platforms.
India
CDSCO medical device rules create regulatory pathways for software-based cardiac risk scoring that parallel FDA predicate device frameworks. The country's national pharmaceutical regulator has streamlined import licensing for wearable ECG peripherals. Maharashtra's Mumbai-Pune corridor concentrates hospital chain headquarters, where private providers pilot subscription-based remote monitoring for post-acute cardiac patients.
Cardiovascular Digital Solutions Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across cardiovascular digital solutions. Full-stack platform builders leverage installed imaging hardware bases to anchor AI analytics within enterprise procurement cycles. Point-solution developers compete on specialized algorithm performance but face pricing compression without hardware adjacencies. The market structure rewards vertical integration into cloud infrastructure and punishes standalone software licensing. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into adjacent diagnostic modalities.
Among imaging-hardware-anchored platform builders, GE Healthcare and Philips Healthcare occupy positions that exemplify enterprise procurement leverage. AliveCor, Inc. represents the handheld-peripheral specialist archetype, competing through consumer-facing arrhythmia screening channels. These three companies illustrate the competitive divergence between institutional deployment models and distributed screening approaches.
| Leading Market Players |
|---|
| AliveCor, Inc. |
| Apple Inc. |
| iRhythm Technologies, Inc. |
| GE Healthcare |
| Philips Healthcare |
| HeartFlow, Inc. |
| Verily Life Sciences LLC |
| Medtronic |
| Baxter |
| Others |
Supply Flow & Price Mechanics
Cloud-native AI architectures displacing on-premise server deployments simultaneously redistribute supply geography toward hyperscale data center regions and compress pricing premiums for traditional hardware-anchored cardiac monitoring platforms. This substitution dynamic concentrates margin capture among software-native vendors while forcing legacy device manufacturers to restructure pricing around recurring analytics subscriptions rather than capital equipment markups.
Pricing Analysis
Multi-year equipment service agreements drive lifetime value for full-stack platform builders like GE Healthcare and Philips, anchoring AI analytics within hospital procurement cycles. Pricing stratifies across FDA-cleared diagnostic tiers, CE-marked wellness-adjacent devices, and unregulated consumer peripherals, with certification level commanding the steepest premium differentials. Cost compression in mid-tier hardware segments intensifies as photoplethysmography-enabled consumer wearables encroach on clinical-grade monitoring indications. United States health systems exhibit the highest price elasticity, while German hospital procurement committees demonstrate the lowest sensitivity due to centralized bundling authority.
Supply Chain Analysis
Inventory cycles for semiconductor components and lithium-ion cells extend lead times for wearable device manufacturers sourcing from Taiwan, South Korea, and China. Firmware development for FDA quality system regulation compliance draws from scarce embedded systems engineering talent concentrated in the Greater Boston and Bavaria medical technology corridors. Single-source vulnerability in hyperscale cloud infrastructure creates vendor lock-in risks for cardiac data storage and compute. Distribution runs through enterprise imaging contracts in hospital systems, direct-to-consumer channels for handheld peripherals, and self-insured employer programs in Germany bypassing traditional payer intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across reimbursement pathways, regulatory jurisdictions, and deployment models creates specialized niches for point-solution developers alongside full-stack platform builders. Ambulatory care expansion and home-based monitoring subsidies in aging economies fragment demand into distinct purchasing archetypes.
For Market Incumbents: Shield installed base relationships by embedding AI analytics within multi-year equipment service agreements before point-solution vendors achieve standalone reimbursement codes. Deepen backward integration into cloud infrastructure to reduce hyperscale provider dependency and capture recurring revenue streams from predictive cardiac risk scoring. FDA 510(k) software modification requirements for iterative algorithm updates represent the primary regulatory threat to margin structures. For New Entrants and Emerging Players: Lead with AI-ECG multimodal fusion capabilities targeting underpenetrated home-based heart failure monitoring in Japan, where METI digital health subsidies reduce customer acquisition costs. Direct-to-employer distribution channels in Germany bypass traditional payer intermediaries and offer faster procurement cycles than hospital enterprise sales. White-space concentration in predictive decompensation alerts for reimbursed care pathways enables premium pricing before competitive commoditization. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors acquirers of specialized algorithm developers lacking hardware adjacencies. Long-term viability over the next decade hinges on regulatory infrastructure spanning FDA and EU MDR jurisdictions, with reimbursement code expansion serving as the critical inflection signal for software-based diagnostic outputs. Target acquisition archetypes include cloud-native AI analytics firms with established clinical validation partnerships and prospective registry data for post-market surveillance obligations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Software Modification Pathway | Accelerates iterative algorithm updates while compressing margin structures through predicate device comparison requirements. |
| EU MDR Software-as-Medical-Device Classification | Streamlines conformity assessments for algorithm-based cardiac risk scoring across European Economic Area jurisdictions. |
| Hospital System Partnership | GE Healthcare and Philips leverage installed imaging bases to anchor AI analytics within enterprise procurement cycles. |
| Reimbursement Strategy | CMS remote therapeutic monitoring codes expand addressable patient populations for continuous arrhythmia surveillance platforms. |
| Software Companion Development | Mobile health platforms bridge wearable peripherals with clinical decision support systems in distributed care models. |
Methodological Framework
A spread of perspectives from hospital procurement managers, biomedical engineers, regulatory affairs specialists, and GPO contracts administrators converged on the working assumptions underlying demand forecasts. Primary interviews across German, Japanese, and United States health systems combined with secondary validation from FDA 510(k) filings, EU MDR conformity assessment databases, CMS reimbursement code determinations, and hospital procurement contract registries. Bottom-up patient population sizing and top-down equipment vendor revenue analysis triangulated market boundaries.
Segmentation dimensions modeled encompass product configuration, end-user concentration, technology maturity, and application workflow integration depth across the projection horizon. CAGRs derive from installed base growth rates, replacement cycles for legacy telemetry infrastructure, and reimbursement expansion trajectories for predictive risk stratification. Algorithm performance metrics from real-world evidence registries and cloud infrastructure capex disclosures from hyperscale providers inform software-native segment expansion assumptions.
The analysis sits within stated boundaries; outcomes outside sustained CMS coverage determination expansion or EU MDR streamlined pathway continuity would require recalibration. Forecasts reflect documented assumptions on regulatory timeline compression and cloud infrastructure pricing volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Global Patient Engagement Solution Market
Digital Health Solutions
Mhealth Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Smart Healthcare Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Digital Assistants in Healthcare Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Europe Eclinical Solutions Market
Digital Health Solutions
Cardiac AI Monitoring and Diagnostic Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Digital Healthcare Solutions Market