
 US at-Home Testing Kits Market | 2026-2036
US at-Home Testing Kits Market Size, Share, and Industry Trends Forecast 2026-2036
US at-Home Testing Kits Market Analytics
FDA's expanded over-the-counter authorization framework is recalibrating the cost-of-entry calculus for molecular diagnostic startups. Abbott leverages its integrated manufacturing footprint to sustain price competitiveness in glucose monitoring strips. Quidel Corporation anchors its position through proprietary lateral-flow chemistry that dominates retail pharmacy shelf space.
At-home testing kits comprise self-administered diagnostic systems designed for specimen collection, assay processing, and result interpretation without clinical supervision, typically employing immunochromatographic, electrochemical, or nucleic acid amplification methodologies with sensitivity thresholds matching laboratory standards. Diagnostic Tests command the largest revenue pool due to recurring purchase patterns for chronic condition management, while Genetic Testing captures premium pricing through direct-to-consumer channel expansion. Sample Collection Kits represent the fastest-growing product type as telehealth platforms bundle them with remote consultation services.
FDA premarket notification requirements, CLIA waiver standards, and HIPAA privacy rules collectively shape product development roadmaps and channel economics for kit manufacturers. CMS reimbursement policies for remote patient monitoring create parallel demand pull from Medicare Advantage plans seeking to reduce acute episode frequency. Stakeholders must monitor evolving FDA guidance on software-as-a-medical-device to determine whether algorithm-interpreted results trigger additional regulatory thresholds.
Market Dynamics
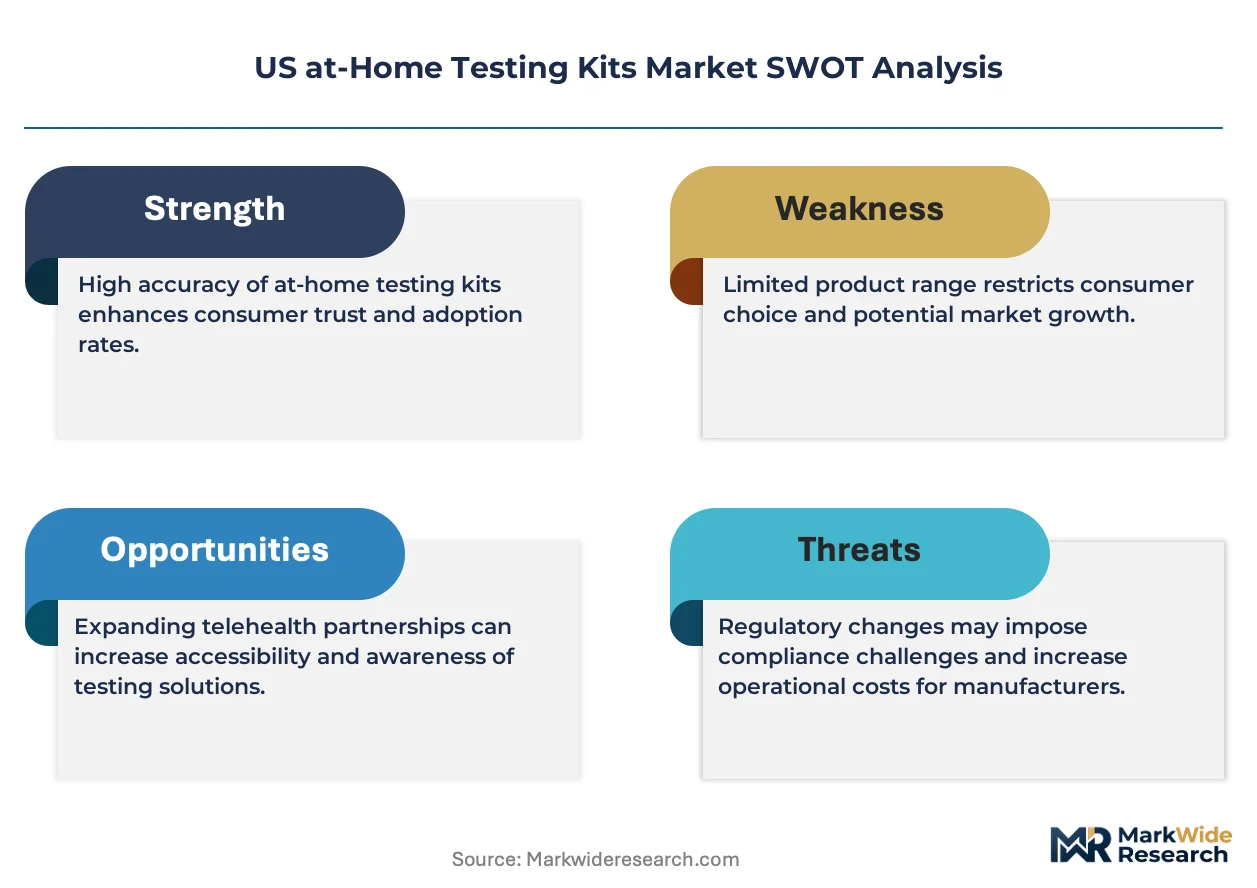
FDA's expanded over-the-counter authorization framework for molecular diagnostics is compressing commercialization timelines and lowering capital barriers for kit manufacturers entering chronic disease monitoring segments.
Growth Catalysts
- CLIA Waiver Expansion:Simplified regulatory pathways for waived-complexity tests accelerate point-of-care approvals and enable retail pharmacy distribution without laboratory infrastructure.
- Telehealth Integration:Remote consultation platforms bundle specimen collection kits with virtual physician visits, creating recurring revenue streams in suburban Texas and Florida markets.
- Chronic Disease Prevalence:Diabetes and cardiovascular condition management among Medicare Advantage enrollees sustains recurring glucose monitoring and lipid panel purchase patterns.
Market Restraints
- Reimbursement Uncertainty:CMS remote patient monitoring coding changes create payment volatility for manufacturers dependent on Medicare Advantage plan contracts.
- Input Concentration:Nitrocellulose membrane and antibody reagent supply chains concentrate among Asian specialty chemical producers, exposing lateral-flow assay makers to freight cost spikes.
- Technical Limitation:Self-collected specimen quality variability reduces sensitivity for low-viral-load infectious disease detection compared to clinical phlebotomy.
Strategic Opportunities
- Behavioral Health Screening:Underpenetrated cognitive function and pharmacogenomic testing in rural Midwest counties offers whitespace beyond infectious disease and diabetes.
- Software-as-Medical-Device:Algorithm-interpreted result platforms trigger FDA guidance evolution, creating first-mover advantage for integrated diagnostic-software developers.
- Retail Clinic Partnerships:CVS MinuteClinic and Walgreens Healthcare networks embed kit fulfillment into hybrid care models, expanding channel reach beyond direct-to-consumer shipping.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of computational biologists capable of validating machine-learning diagnostic algorithms delays product development cycles.
- HIPAA-Compliant Data Architecture:Cloud infrastructure costs for encrypted health record transmission consume disproportionate capital relative to hardware manufacturing.
- Interoperability Friction:Electronic health record integration with Epic and Cerner systems requires bespoke API development for each health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US at-Home Testing Kits Market |
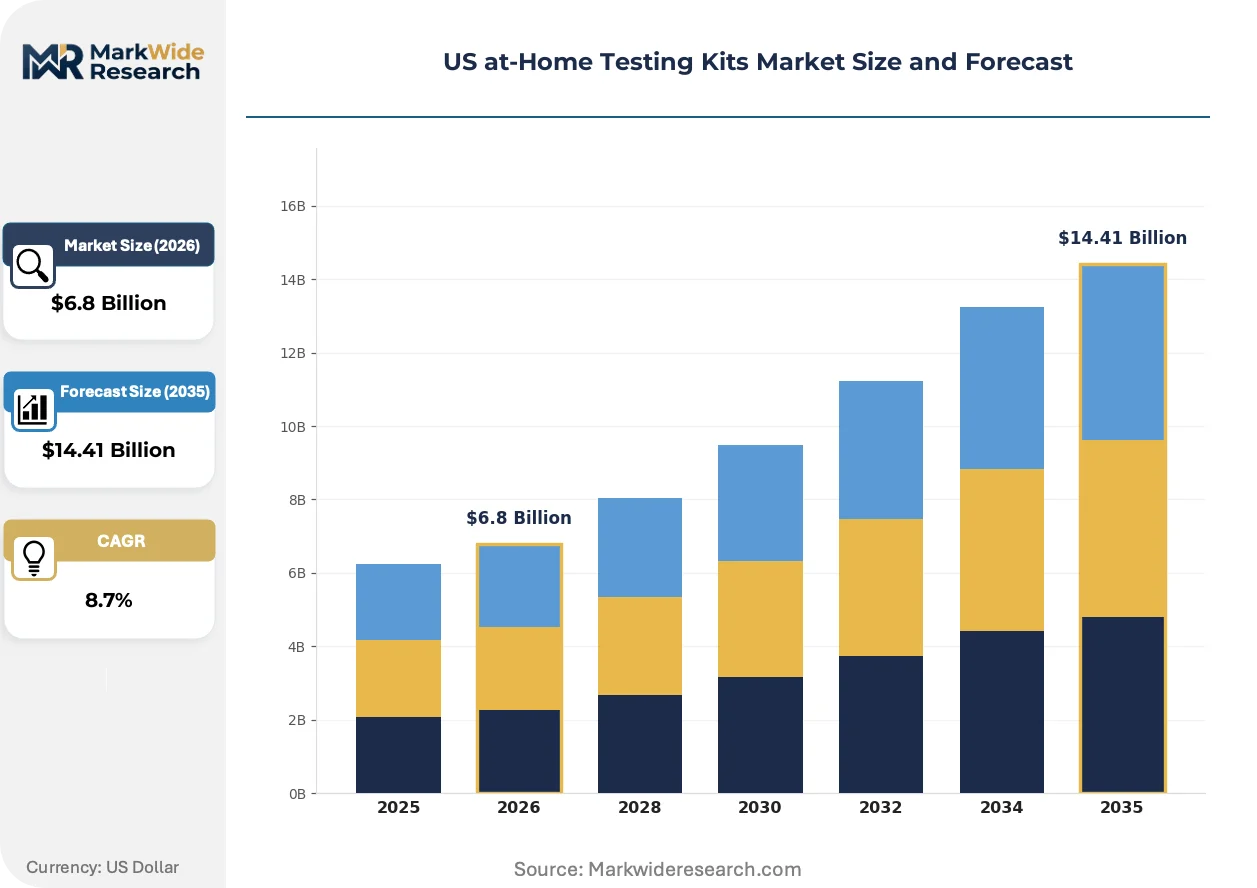
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Health Monitoring Devices, Sample Collection Kits, Infection Detection Kits Target Audience: Individuals, Families, Caregivers, Healthcare Professionals Testing Functionality: Blood Glucose Monitoring, Pregnancy Testing, Genetic Testing, Pathogen Detection Distribution Channel: Online Retail, Pharmacies, Hospitals, Direct Sales |
| Companies Covered | Abbott, ACON Laboratories, Inc., BD, Quidel Corporation, Cardinal Health, OraSure Technologies, Inc., Everlywell, Inc., Siemens Healthcare GmbH, F. Hoffmann-La Roche Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US at-Home Testing Kits Market Evolving Landscape
Isothermal nucleic acid amplification and smartphone-connected electrochemical sensors are collapsing the cost-performance gap between home-based and laboratory diagnostics. Three developments dominate current investment patterns.
Loop-mediated isothermal amplification chemistry is absorbing polymerase chain reaction workflows for infectious disease detection. Retail pharmacy chains in Florida and Texas deploy these platforms for respiratory panel screening without thermal cycler infrastructure. The technology is absorbing capital previously allocated to central laboratory equipment, redirecting instrument financing toward disposable cartridge manufacturing.
FDA's 2023 guidance on over-the-counter molecular diagnostics eliminated prescription requirements for influenza and COVID-19 combination assays. Manufacturers now optimize assay sensitivity thresholds for untrained user specimen collection rather than clinical technician handling. Suburban markets with limited laboratory access accelerate adoption fastest, particularly among Medicare Advantage plans seeking to reduce emergency department utilization.
Subscription-based replenishment models displace episodic pharmacy purchasing for chronic condition monitoring. Direct-to-consumer platforms auto-ship glucose strips and HbA1c kits on 90-day cycles, locking in patient adherence data. This pattern concentrates in Texas metro corridors where pharmacy deserts intersect with high diabetes prevalence, forcing traditional retailers to bundle remote physician consultation with kit fulfillment.
US at-Home Testing Kits Market Segmentation
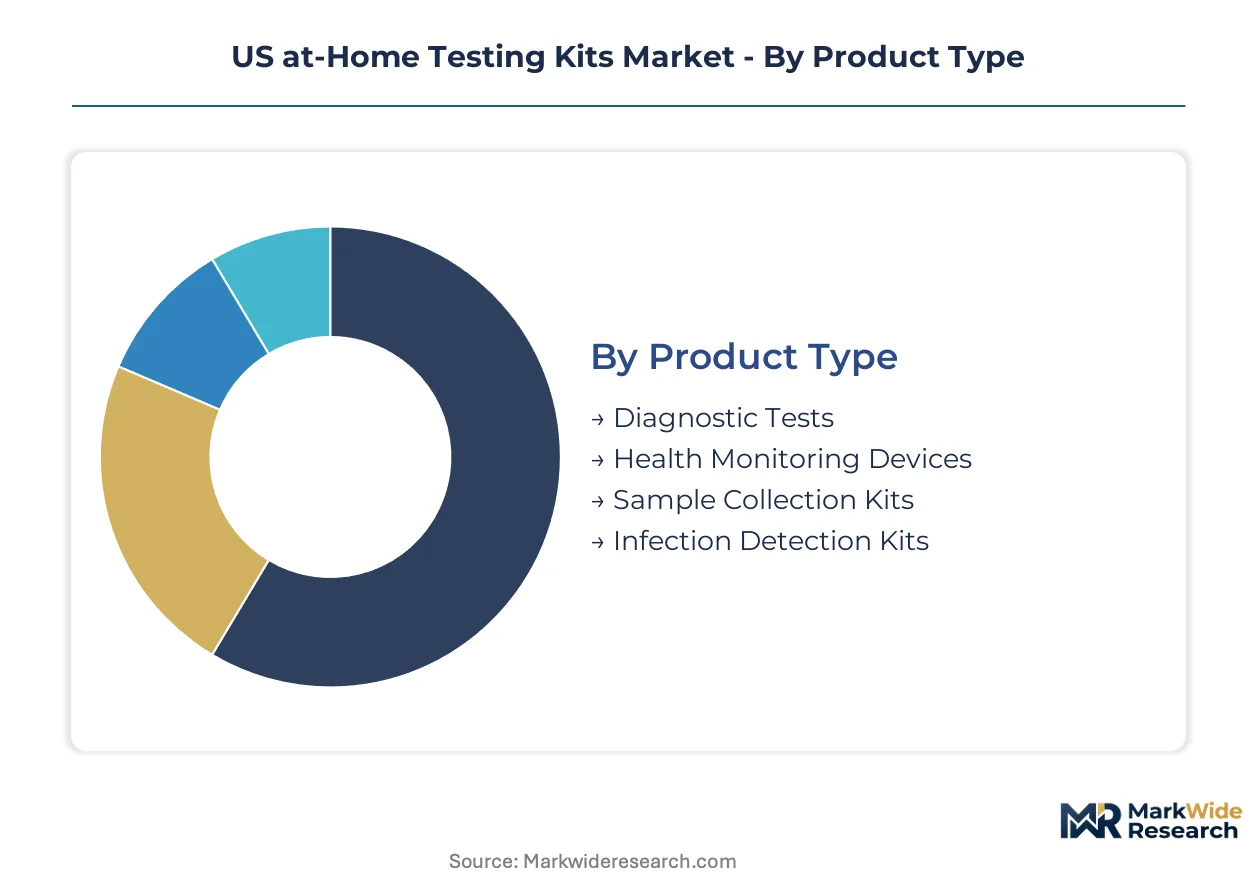
Kit manufacturers configure product portfolios around four intersecting dimensions: clinical utility, user capability, specimen type, and fulfillment pathway. Each segmentation axis reveals distinct margin structures and regulatory exposure.
Product Type:
Purchase frequency and reimbursement eligibility diverge sharply across product categories.
- Diagnostic Tests:Self-administered assays employing immunochromatographic or electrochemical detection for chronic condition markers. Recurring glucose monitoring and lipid panel purchases in Texas and Florida Medicare Advantage populations sustain revenue stability.
- Sample Collection Kits:Specimen gathering systems bundled with telehealth consultations for remote laboratory processing. Telehealth platforms in suburban markets auto-ship these on 90-day cycles, locking patient adherence data.
- Health Monitoring Devices:Wearable or handheld instruments with continuous sensing capabilities for biometric tracking.
- Infection Detection Kits:Single-use lateral-flow or molecular assays for respiratory and gastrointestinal pathogen identification.
Volume sits with Diagnostic Tests; growth tilts toward Sample Collection Kits.
Target Audience:
User sophistication determines packaging complexity, instruction clarity, and FDA clearance pathway selection.
- Individuals:Solo consumers managing personal health conditions through direct-to-consumer channels. Subscription replenishment models in pharmacy desert corridors concentrate demand here.
- Families:Multi-user households purchasing bundled testing for infectious disease screening and preventive health monitoring.
- Caregivers:Non-clinical attendants assisting elderly or disabled patients with specimen collection and result interpretation.
- Healthcare Professionals:Licensed providers deploying kits for remote patient monitoring under CMS reimbursement codes.
Revenue concentrates with Individuals; expansion tilts toward Healthcare Professionals.
Testing Functionality:
Technical complexity and sensitivity requirements shape manufacturing investment and CLIA waiver strategy.
- Blood Glucose Monitoring:Electrochemical strip-based systems with FDA-cleared accuracy thresholds matching laboratory reference methods. Abbott's integrated manufacturing sustains price competitiveness in this high-volume category.
- Pathogen Detection:Isothermal amplification and lateral-flow chemistry for infectious disease identification without thermal cycler infrastructure. Retail pharmacy chains in Florida deploy these for respiratory panel screening.
- Pregnancy Testing:Human chorionic gonadotropin detection via immunochromatographic strips with visual or digital readout.
- Genetic Testing:Direct-to-consumer nucleic acid analysis for ancestry, pharmacogenomics, and carrier screening.
Shipment volume clusters in Blood Glucose Monitoring; steepest expansion trajectory appears in Pathogen Detection.
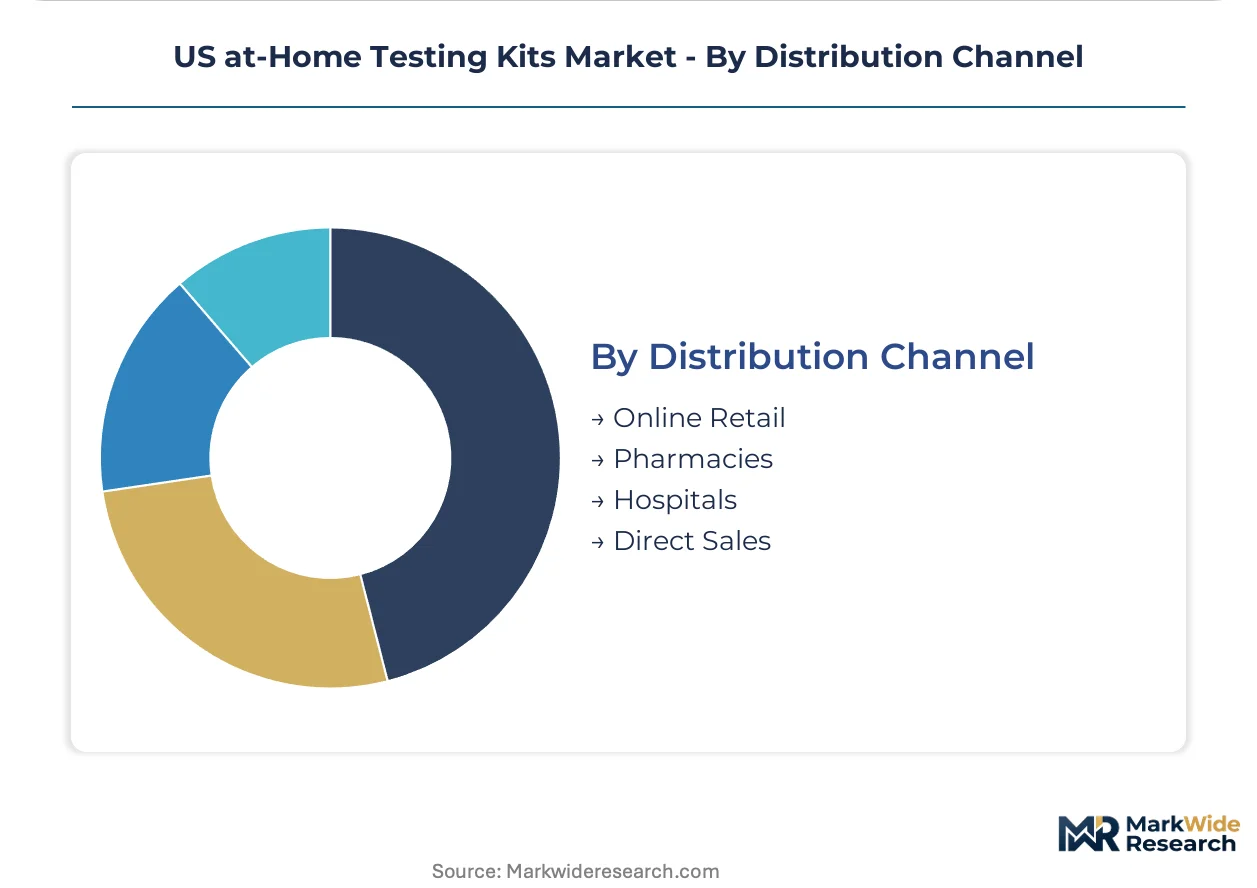
Distribution Channel:
Fulfillment economics and patient acquisition costs vary dramatically by channel structure.
- Online Retail:Direct-to-consumer platforms with subscription auto-ship and telehealth bundling. Texas metro corridors with pharmacy deserts drive disproportionate share here.
- Pharmacies:CVS MinuteClinic and Walgreens Healthcare networks embedding kit fulfillment into hybrid care models.
- Hospitals:Discharge planning and remote patient monitoring program kit provisioning.
- Direct Sales:Manufacturer-controlled channels bypassing retail markup for chronic disease management programs.
Transaction volume flows through Online Retail; margin expansion favors Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and Florida concentrate capital deployment for at-home testing manufacturing. FDA's 510(k) clearance acceleration for waived-complexity devices lowers entry barriers in these zones. State-level telehealth reimbursement parity laws in both states amplify demand pull from Medicare Advantage plans.
Texas
Houston's medical device corridor anchors glucose monitoring strip production for Medicare Advantage populations. The Texas Medical Board's expanded telehealth prescribing authority enables remote consultation bundling with specimen collection kits. Dallas-Fort Worth metroplex drives subscription auto-ship volume where pharmacy deserts intersect with high diabetes prevalence.
Florida
Retirement-age demographics in Tampa and Orlando sustain recurring infectious disease panel purchases. Florida's Department of Health emergency preparedness contracts prioritize point-of-care molecular diagnostics for respiratory screening. Miami-Dade County concentrates retail pharmacy chain deployment of isothermal amplification platforms.
California
Silicon Valley software developers dominate algorithm-interpreted diagnostic platforms awaiting FDA software-as-medical-device guidance. California's Department of Managed Health Care mandates coverage for remote patient monitoring in regulated health plans. San Diego's biotech cluster advances nucleic acid amplification chemistry for over-the-counter clearance pathways.
New York
Greater New York's health system consolidation creates procurement scale for hybrid care model kit fulfillment. New York State's telehealth parity law requires commercial insurers to reimburse virtual visits bundled with home specimen collection. Buffalo-Rochester corridor hosts specialty chemical production for lateral-flow nitrocellulose membranes.
Illinois
Chicago's logistics infrastructure supports distribution hub positioning for direct-to-consumer auto-ship programs. Illinois Department of Public Health CLIA waiver streamlining accelerates point-of-care test approvals for retail pharmacy deployment. Rockford manufacturing base produces electrochemical sensor components for blood glucose monitoring systems.
US at-Home Testing Kits Market Competitive Landscape
Massachusetts and California producers anchor the molecular diagnostics tier; Midwest manufacturers hold glucose monitoring and lateral-flow chemistry. The vendor base stratifies across integrated conglomerates, specialized assay developers, and telehealth-integrated platforms. Three archetypes dominate: diversified health technology conglomerates with captive distribution, pure-play diagnostic chemistry specialists, and direct-to-consumer subscription platforms. Competitive moves concentrate on retail clinic partnership expansion and CLIA waiver portfolio accumulation.
Within the integrated conglomerate tier, Abbott and Siemens Healthcare GmbH occupy positions spanning electrochemical sensing to molecular platforms. Among specialized assay developers, Quidel Corporation and ACON Laboratories, Inc. exemplify lateral-flow chemistry concentration. OraSure Technologies, Inc. and Everlywell, Inc. represent the telehealth-integrated subscription archetype with bundled specimen collection and virtual consultation services. BD and Cardinal Health anchor distribution infrastructure plays. F. Hoffmann-La Roche Ltd sits within the premium-tier diagnostic instrumentation segment.
| Leading Market Players |
|---|
| Abbott |
| ACON Laboratories, Inc. |
| BD |
| Quidel Corporation |
| Cardinal Health |
| OraSure Technologies, Inc. |
| Everlywell, Inc. |
| Siemens Healthcare GmbH |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Network & Pricing Analysis
CLIA waiver certification tiers bifurcate the market into premium molecular diagnostics and commodity lateral-flow strips, with each tier demanding distinct supply chain footprints and margin structures. Premium players absorb FDA pre-submission costs and captive antibody production to defend pricing power, while commodity manufacturers chase volume through Asian-sourced nitrocellulose membranes and contract electrochemical sensor assembly.
Pricing Analysis
Short lead-time premiums command 15-25% markups over spot inventory for glucose monitoring strips and respiratory panel cartridges. The dominant structure runs subscription-based auto-ship with 90-day replenishment cycles, where price differentiation rests on FDA clearance tier and telehealth bundling depth. Cost compression in lateral-flow infectious disease kits intensifies as retail pharmacy chains consolidate procurement under private-label programs. Medicare Advantage plans exhibit lowest price sensitivity for remote patient monitoring bundles, while uninsured direct-to-consumer buyers drive spot-market discounting.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean specialty chemical producers for nitrocellulose membranes and antibody reagents. Raw material dependencies center on electrochemical sensor substrates, isothermal amplification enzymes, and lateral-flow backing cards. Tariff exposure on imported reagents threatens margin stability for mid-tier assay developers. Distribution runs through three channels: direct-to-consumer auto-ship platforms, retail pharmacy chain DCs, and hospital system GPO warehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA's software-as-medical-device guidance trajectory elevates compliance costs into a structural moat, insulating CLIA-waiver-holding incumbents from undercapitalized entrants while rewarding algorithm-integrated platform investments.
For Market Incumbents: Anchor market position through backward integration into electrochemical sensor manufacturing and exclusive retail clinic partnerships with CVS MinuteClinic and Walgreens Healthcare networks. The threat of telehealth-native subscription platforms demands defensive CLIA waiver portfolio expansion into pharmacogenomic testing. Priority leverage rests on proprietary lateral-flow chemistry scale and algorithm-validated result interpretation platforms awaiting FDA clearance. For New Entrants and Emerging Players: Capture whitespace in behavioral health screening and rural Midwest cognitive function testing where penetration remains under 15% of addressable households. The most penetrable entry vector runs through telehealth-integrated specimen collection kits bundled with virtual psychiatric consultation. Go-to-market execution should prioritize direct-to-consumer subscription auto-ship in Texas pharmacy desert corridors before retail pharmacy shelf space competition intensifies. For Investors and Strategic Acquirers: Re-rating potential sits with telehealth-integrated diagnostic platforms given CMS remote patient monitoring reimbursement expansion and Medicare Advantage plan risk-contract growth. Long-term viability favors acquirers of algorithm-interpreted result developers with pending FDA software-as-medical-device submissions. The signal to watch is FDA guidance finalization on algorithm-validated diagnostics, which will trigger consolidation premiums for compliant first-movers.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Waiver Portfolio Expansion | Accelerates point-of-care approval timelines and unlocks retail pharmacy distribution without laboratory infrastructure investment. |
| Software-as-Medical-Device Development | Positions algorithm-interpreted platforms for FDA guidance compliance and premium pricing in telehealth-integrated channels. |
| Retail Clinic Partnership Embedding | Integrates kit fulfillment into CVS MinuteClinic and Walgreens Healthcare hybrid care models beyond direct-to-consumer shipping. |
| Backward Integration into Sensor Manufacturing | Captures electrochemical strip cost structure and insulates margin from Asian substrate price volatility. |
| Subscription Auto-Ship Infrastructure | Locks patient adherence data and recurring revenue in chronic disease monitoring segments with 90-day replenishment cycles. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning regulatory affairs directors at molecular diagnostic developers, GPO contracts managers at hospital systems, retail pharmacy category buyers, and telehealth platform executives. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare Advantage plan enrollment statistics, and CLIA waiver approval logs. Bottom-up demand modeling triangulated against top-down market sizing across product type, testing functionality, and distribution channel dimensions.
Granularity-level modeling segmented volume and value outputs by diagnostic test versus sample collection kit versus infection detection format, with further disaggregation by blood glucose monitoring, pathogen detection, and genetic testing functionality tiers. CAGRs derived from regression analysis of historical FDA clearance velocity, Medicare Advantage enrollment trajectories, and telehealth consultation volume correlations with kit shipment data. Industry-specific forecast inputs incorporated CMS remote patient monitoring coding changes and state-level telehealth parity law adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-as-medical-device guidance timing and CMS reimbursement code stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Coagulation Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Osmometer Market
Testing Services
Global Drug Abuse Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Global Metabolic Testing Market
Testing Services
ATP Assays Market
Testing Services
Ferritin Testing Market
Testing Services
Radiographic Testing Market
Testing Services
At-Home Testing Market
Testing Services
Warfarin Sensitivity Test Market
Testing Services
Friability Tester Market