
 Smart Healthcare Market | 2026-2036
Smart Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Healthcare Market Intelligence
The EU AI Act is expanding compliance obligations for algorithmic healthcare tools across European member states. GE Healthcare leverages its imaging hardware installed base to embed AI diagnostic layers directly into radiology workflows. Cognizant sustains large-scale digital transformation contracts with hospital networks seeking interoperable electronic health record systems. Zymr specializes in cloud-native healthcare platforms that navigate FDA software-as-a-medical-device validation pathways.
Smart healthcare encompasses connected medical devices, digital therapeutics, and AI-augmented clinical decision systems that transmit biometric data through encrypted IoT networks to centralized analytics engines. These systems integrate FDA 21 CFR Part 820 quality system requirements with real-time patient monitoring to reduce acute episode escalation and optimize resource allocation across care delivery organizations. Wearable devices and remote patient monitoring now capture the fastest-growing application segments as payors shift reimbursement toward outcomes-based models. Smart hospital solutions anchored in IoT technology and cloud computing occupy mature margin pools where infrastructure replacement cycles generate recurring revenue streams.
FDA software-as-a-medical-device guidance, EU AI Act risk classification frameworks, and HIPAA security rule enforcement collectively determine market access velocity and product development costs for platform vendors. The EU Green Deal's digital health infrastructure investments and CSRD reporting requirements further shape procurement criteria for European hospital systems. Stakeholders must monitor evolving reimbursement parity between remote and in-person care delivery to calibrate portfolio bets across telemedicine and connected device segments.
Market Dynamics
The Medicare reimbursement pivot toward remote patient monitoring codes is compressing hospital capital planning cycles and forcing rapid IoT infrastructure deployment across acute care networks.
Growth Catalysts
- FDA software-as-a-medical-device framework:The 2021 guidance clarifies algorithmic diagnostic validation pathways, reducing regulatory uncertainty for AI-augmented imaging tools and accelerating product-to-market timelines.
- Hospital-at-home reimbursement parity:United States payors now match inpatient rates for acute-level remote monitoring, pulling capital toward connected patient monitoring infrastructure and tele-ICU platforms.
- Edge computing architectures:Real-time biometric processing at the device layer reduces latency for critical alert generation, enabling predictive intervention models that cut emergency department transfers.
Market Restraints
- EU AI Act risk classification:High-risk algorithmic diagnostic tools face conformity assessment burdens that extend development timelines and inflate compliance costs for European market entry.
- Semiconductor supply concentration:Discrete analog components for wearable biosensors concentrate in Taiwan and South Korea foundries, exposing procurement to geopolitical disruption and allocation constraints.
- Interoperability fragmentation:Proprietary data formats across EHR vendors block seamless device-to-platform integration, forcing costly middleware development and delaying care coordination benefits.
Strategic Opportunities
- CSRD-aligned hospital procurement:European sustainability reporting mandates create preference for energy-efficient IoT infrastructure and circular device lifecycle programs in German and French health systems.
- Mental health digital therapeutics:FDA breakthrough device designation for prescription-grade cognitive behavioral apps opens reimbursement pathways for software-only interventions in anxiety and depression management.
- Direct-to-employer contracting:Self-insured corporations in the United States are bypassing traditional payors to purchase population health monitoring services, creating new channel economics for platform vendors.
Industry Challenges
- FDA 21 CFR Part 820 quality system implementation:Cloud-native startups face steep organizational learning curves in design controls and risk management documentation for connected device submissions.
- Cybersecurity validation timelines:HIPAA security rule enforcement and FDA premarket cybersecurity guidance require penetration testing and SBOM documentation that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Healthcare Market |
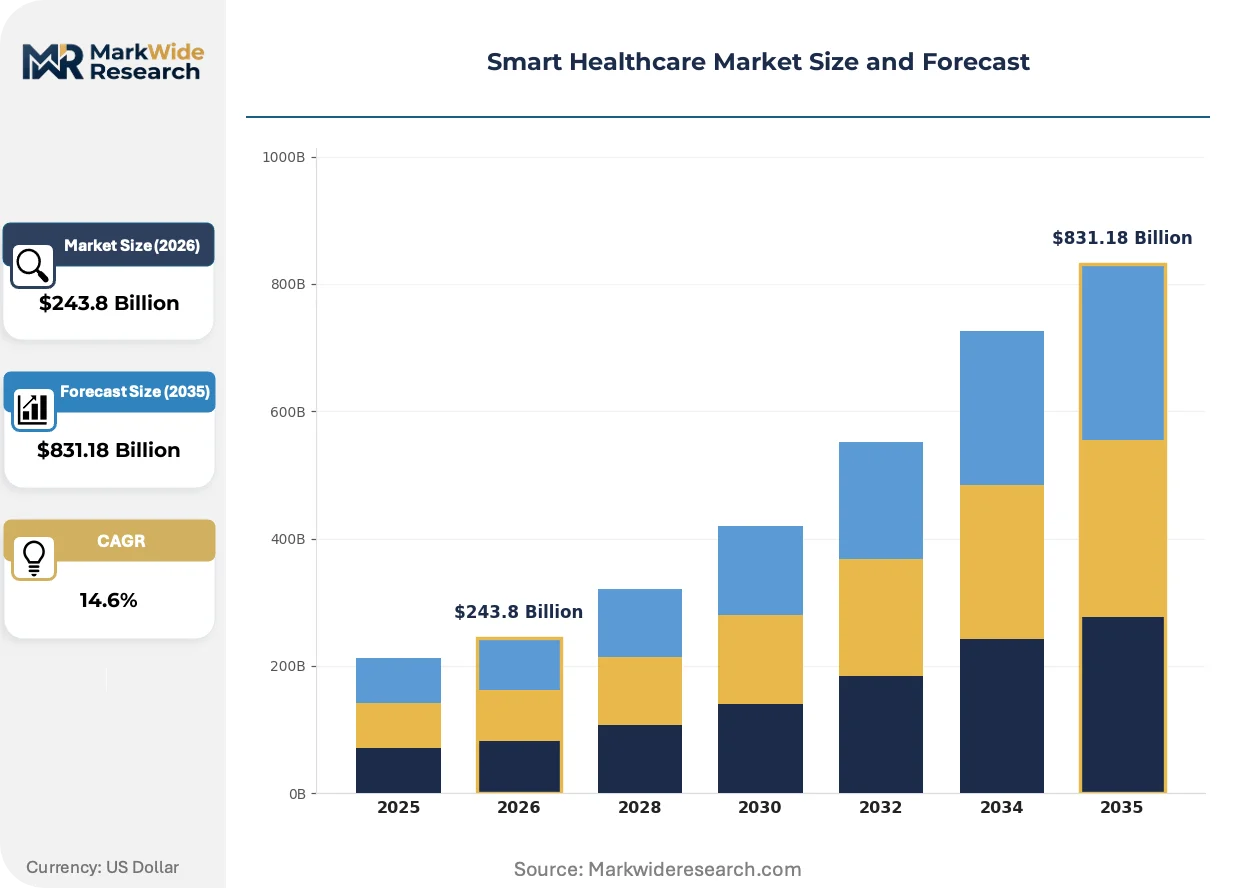
| Market Size in 2026 | $243.8 Billion |
| Market Size in 2035 | $831.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Telemedicine Solutions, Health Monitoring Systems, Smart Hospital Solutions End User: Clinics, Hospitals, Homecare Providers, Laboratories Technology: IoT Technology, AI Systems, Blockchain Solutions, Cloud Computing Application: Chronic Disease Management, Remote Patient Monitoring, Health Data Analytics, Smart Medication Management |
| Companies Covered | Merative, Innowise, Accenture, Zymr, UST, GE Healthcare, 7T, SOPHiA GENETICS, Cognizant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Healthcare Market Strategic Shifts & Innovations
Generative AI is rewriting clinical documentation workflows while ambient listening systems capture encounter data without keyboard burden. These shifts are compressing the gap between diagnostic insight and care delivery execution.
Multimodal AI is converging with continuous glucose monitoring and cardiac telemetry streams to generate predictive risk scores for acute decompensation. Hospital systems in the United States are deploying these platforms in step-down units within eighteen-month procurement cycles. The technology is converging with existing EHR infrastructure to close the loop between algorithmic alert and nursing intervention workflow.
The EU AI Act's high-risk system requirements are mandating human-in-the-loop oversight for diagnostic algorithms and imposing post-market monitoring obligations on deployed AI. Medical device manufacturers must maintain performance logs and incident reporting systems that track algorithmic drift. European radiology networks are responding by consolidating vendor relationships to reduce compliance fragmentation across their installed base.
Employer-sponsored health plans are unbundling traditional insurance to purchase standalone remote monitoring services for chronic condition management. Benefits administrators in the United States are contracting directly with digital health platforms, displacing broker-mediated payor relationships. This channel shift concentrates purchasing power among Fortune 500 benefits teams and compresses sales cycles for validated clinical outcomes.
Smart Healthcare Market Segmentation
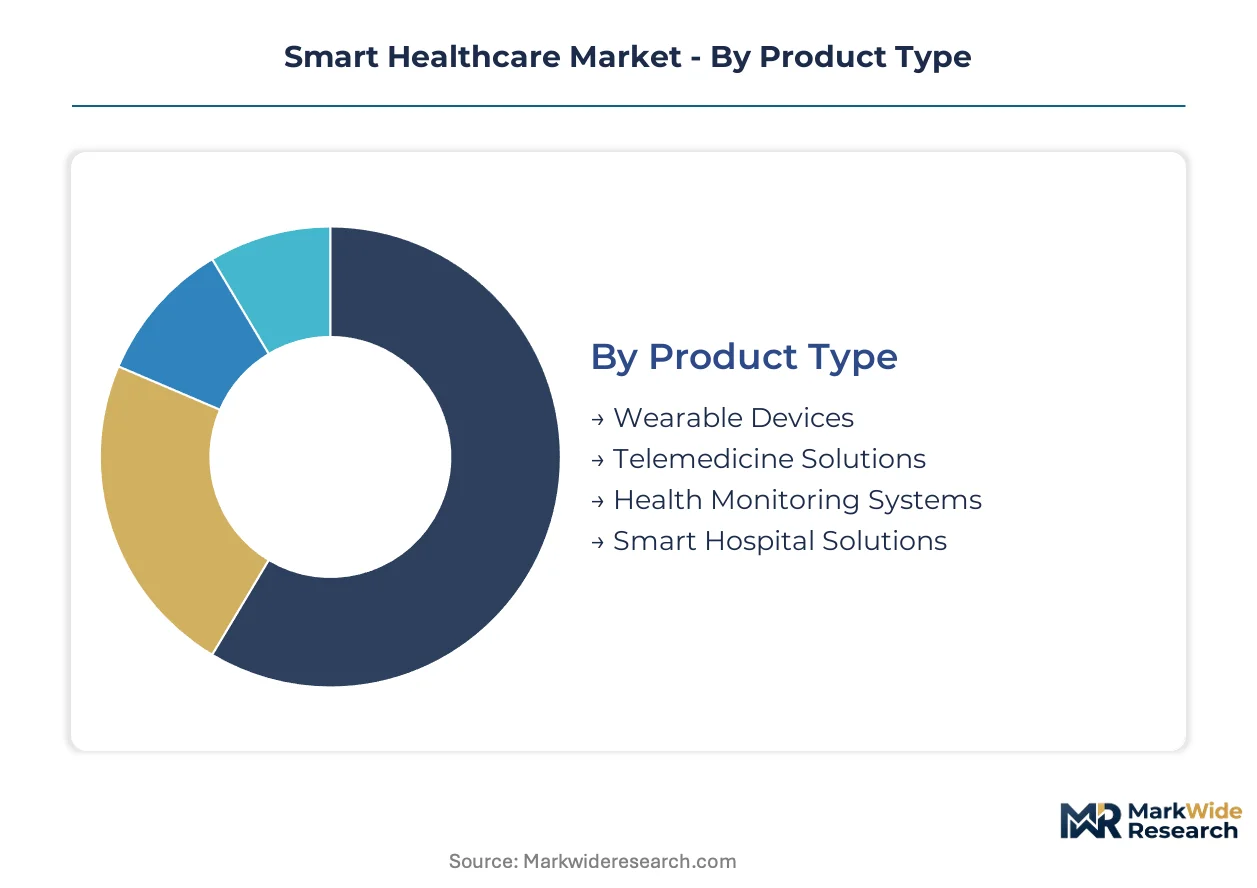
Segmentation in smart healthcare reveals how procurement power concentrates across infrastructure-heavy hospital systems versus distributed homecare networks. Vendors must calibrate product architectures to match divergent compliance burdens and reimbursement pathways across these divides.
Product Type:
Supply concentration in semiconductor foundries and medical-grade sensor manufacturing shapes which product categories achieve scale fastest.
- Smart Hospital Solutions:Integrated IoT infrastructure combining bedside monitors, asset tracking, and centralized command centers dominates capital expenditure in United States acute care networks. Hospital procurement committees prioritize FDA-validated platforms that interoperate with existing EHR systems, compressing vendor selection timelines.
- Wearable Devices:Continuous glucose monitors, cardiac patches, and pulse oximetry bands transmit encrypted biometric streams through Bluetooth Low Energy protocols. Medicare reimbursement codes for remote patient monitoring pull demand toward United States homecare settings where outcomes-based contracting accelerates deployment.
- Telemedicine Solutions:Video consultation platforms with integrated diagnostic peripherals serve rural health systems and employer-sponsored clinics seeking to bypass traditional payor networks.
- Health Monitoring Systems:Stationary connected devices for blood pressure, weight, and spirometry capture recurring revenue through cloud subscription models in chronic disease management programs.
Today's leader: Smart Hospital Solutions. Tomorrow's challenger: Wearable Devices.
End User:
Margin structures diverge sharply between capital-intensive hospital infrastructure and lean homecare service models.
- Hospitals:Multi-year digital transformation contracts with systems integrators lock in enterprise-wide platform deployments. United States health systems accelerate procurement cycles as CMS reimbursement shifts reward reduced readmission rates through predictive monitoring.
- Homecare Providers:Skilled nursing agencies and home health aides leverage lightweight remote monitoring kits to extend care beyond facility walls. Reimbursement parity for hospital-at-home models in the United States concentrates purchasing power among regional home health networks.
- Clinics:Federally qualified health centers and specialty practices adopt modular telemedicine suites to expand access without proportional staffing increases.
- Laboratories:Reference labs and pathology networks deploy AI-augmented diagnostic workflows to compress turnaround times for high-volume testing.
Revenue concentrates with Hospitals. Volume expansion favors Homecare Providers.
Technology:
Development cost tiers separate validated medical-grade platforms from consumer-adjacent wellness applications.
- AI Systems:Machine learning algorithms for radiology, pathology, and clinical decision support require FDA software-as-a-medical-device validation and continuous performance monitoring under EU AI Act high-risk system requirements. European radiology networks consolidate vendor relationships to reduce compliance fragmentation.
- IoT Technology:Connected medical devices with edge computing capabilities process biometric data locally before encrypted transmission to cloud analytics engines. Taiwan and South Korea foundry concentration for discrete analog components exposes supply chains to geopolitical disruption.
- Cloud Computing:HIPAA-compliant infrastructure hosts patient data lakes and enables real-time care coordination across distributed provider networks.
- Blockchain Solutions:Distributed ledger architectures for health record interoperability and pharmaceutical supply chain traceability remain in pilot phases with limited production deployment.
Investment flows to AI Systems. Regulatory headwinds constrain Blockchain Solutions.
Application:
Clinical utility and reimbursement clarity determine which applications achieve sustainable revenue streams.
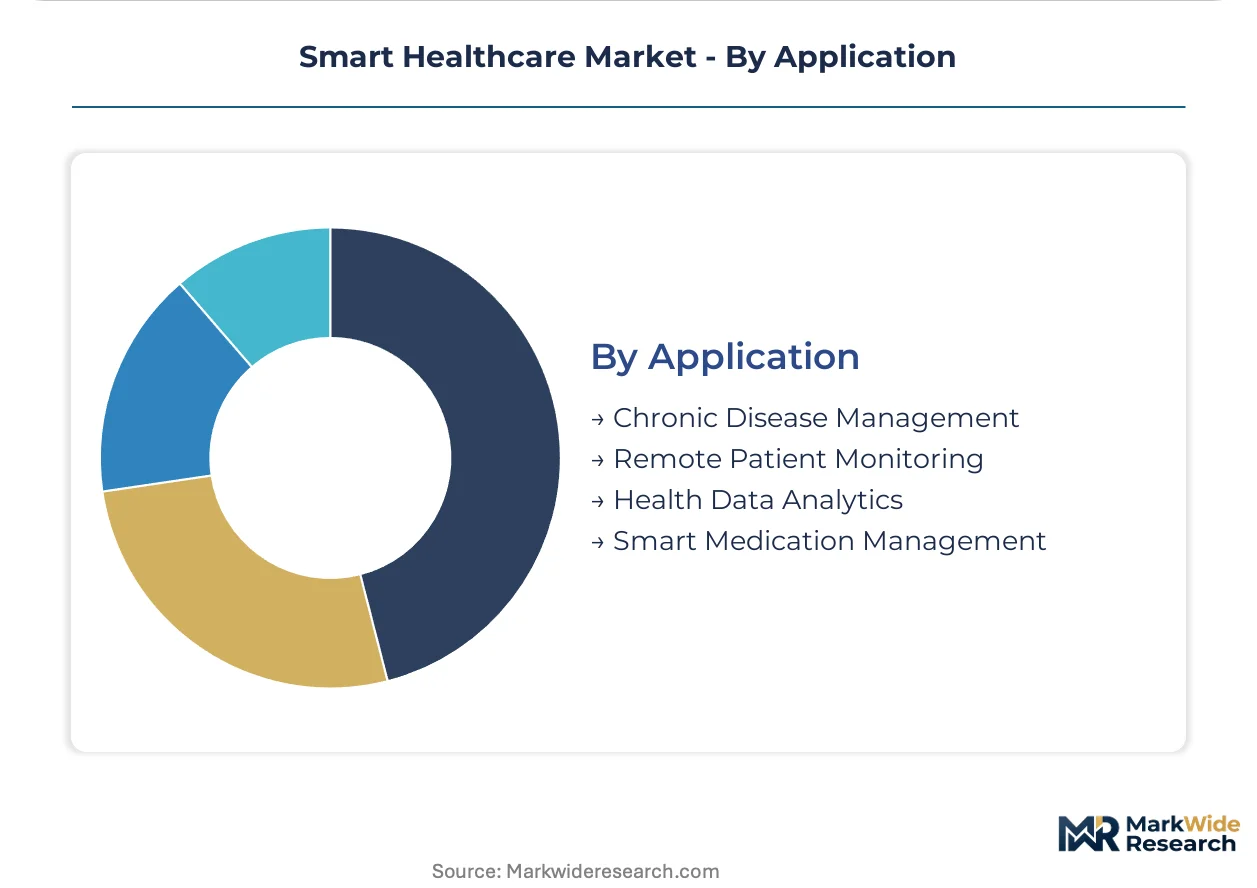
- Remote Patient Monitoring:Continuous vital sign surveillance with predictive alert generation reduces emergency department transfers and enables early intervention. United States payor reimbursement codes for RPM services create direct revenue lines for platform vendors and provider networks.
- Chronic Disease Management:Digital therapeutics and connected device programs for diabetes, heart failure, and COPD align with outcomes-based contracting models. Self-insured employers in the United States bypass traditional payors to purchase population health monitoring services directly.
- Health Data Analytics:Population-level risk stratification and operational optimization tools serve integrated delivery networks seeking to manage total cost of care.
- Smart Medication Management:Connected dispensers and adherence monitoring systems support polypharmacy patients in aging demographics.
Reimbursement clarity favors Remote Patient Monitoring. Chronic Disease Management climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered connected patient monitoring infrastructure through Medicare reimbursement reforms that scaled remote care models nationwide. European hospital systems later adopted similar frameworks under the EU AI Act's risk classification mandates. Asian markets now accelerate procurement of AI-augmented diagnostic platforms as regulatory pathways mature.
United States
Hospital-at-home reimbursement parity pulls capital toward tele-ICU platforms and connected monitoring infrastructure across acute care networks. FDA software-as-a-medical-device guidance clarifies algorithmic diagnostic validation pathways for AI-augmented imaging tools. The Boston-Cambridge corridor anchors digital health venture density, with Massachusetts General Brigham deploying predictive analytics at scale.
Germany
CSRD-aligned procurement criteria favor energy-efficient IoT infrastructure and circular device lifecycle programs across university hospital systems. The EU AI Act's high-risk system requirements impose conformity assessment burdens on algorithmic diagnostic tools entering European markets. Berlin and Munich concentrate health technology startups navigating MDR compliance for connected medical devices.
United Kingdom
NHS Long Term Plan commitments accelerate procurement of remote patient monitoring for chronic disease management across integrated care systems. MHRA recognition routes for software-as-a-medical-device reduce regulatory duplication with FDA pathways. The Golden Triangle of London-Oxford-Cambridge hosts AI diagnostic ventures partnering with Genomics England on population-scale screening.
Japan
Aging demographics drive demand for home-based monitoring systems and predictive fall detection among municipal care providers. PMDA streamlined review pathways for AI-enabled medical devices compress time-to-market for algorithmic diagnostic platforms. Tokyo and Osaka metropolitan areas concentrate hospital system procurement of cloud-native electronic health record infrastructure.
South Korea
MFDS digital health regulatory sandbox programs enable pilot deployments of AI diagnostic tools before full market authorization. National health insurance reimbursement expansion for remote patient monitoring pulls demand toward wearable biosensors and connected chronic care platforms. Seoul's Digital Healthcare Cluster hosts medical AI ventures partnering with Samsung Medical Center on radiology workflow integration.
Smart Healthcare Market Key Industry Players
Premium-margin players sit above commodity-margin players across regulatory validation depth and installed base leverage. The market structures around three tiers: imaging hardware incumbents embedding AI layers, systems integrators managing hospital digital transformation, and cloud-native specialists navigating FDA software-as-a-medical-device pathways. Consolidation pressures intensify as European radiology networks reduce vendor fragmentation to streamline EU AI Act compliance. Dominant competitive moves include strategic partnerships bridging hardware and algorithmic capabilities, plus geographic expansion into direct-to-employer contracting channels.
Within the imaging-anchored tier, GE Healthcare exemplifies hardware-installed-base leverage for AI diagnostic integration. Among systems integrators, Cognizant and Accenture occupy positions managing enterprise-scale electronic health record transformation for hospital networks. At the cloud-native validation specialist tier, Zymr represents the archetype of platform vendors architecting FDA-compliant software-as-a-medical-device infrastructure.
| Leading Market Players |
|---|
| Merative |
| Innowise |
| Accenture |
| Zymr |
| UST |
| GE Healthcare |
| 7T |
| SOPHiA GENETICS |
| Cognizant |
| Others |
Cost & Logistics Intelligence
CMS reimbursement parity for hospital-at-home models is pulling procurement toward connected monitoring infrastructure, forcing vendors to absorb FDA validation costs while competing on outcomes-based contracting terms that compress upfront hardware margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the smart healthcare landscape. Premium tiers command valuation through FDA 510(k) clearance and EU MDR certification, while standard offerings compete on interoperability with Epic and Cerner EHR systems. Pricing pressure stems from Medicare's bundled reimbursement codes that cap per-patient revenue. Home health agencies exhibit acute price sensitivity; academic medical centers prioritize validation depth over unit cost.
Supply Chain Analysis
Direct-to-hospital GPO channels handle enterprise-scale procurement for integrated IoT infrastructure. Discrete analog components for wearable biosensors concentrate in Taiwan and South Korea foundries, exposing procurement to geopolitical disruption. Medical-grade sensor manufacturing draws from specialized semiconductor fabs, lithium polymer cell production, and precision molding operations. Single-source vulnerability for edge computing chipsets represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in smart healthcare rests on cloud-native platform economics displacing capital-intensive hardware cycles, with SaaS recurring revenue models capturing premium multiples over device-centric businesses.
For Market Incumbents: To counter cloud-native entrants unbundling EHR workflows, GE Healthcare and imaging hardware leaders should deepen AI layer integration across radiology installed bases while consolidating vendor relationships to streamline EU AI Act compliance documentation. Channel control through exclusive GPO contracting remains essential. For New Entrants and Emerging Players: Direct-to-employer contracting routes bypass traditional payor gatekeepers and open white-space access to Fortune 500 benefits administrators seeking population health monitoring for diabetes and hypertension management. FDA breakthrough device designation accelerates reimbursement pathway establishment. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native validation specialists possessing FDA software-as-a-medical-device submission expertise and established hospital pilot programs. Long-term viability favors platforms with demonstrated interoperability across Epic, Cerner, and Meditech environments. Watch for CMS expansion of remote patient monitoring billing codes as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-a-Medical-Device Submission | Unlocks Medicare reimbursement pathways for AI diagnostic algorithms in radiology workflows. |
| Hospital System Partnership | Mass General Brigham-scale deployments validate predictive analytics platforms for enterprise procurement. |
| CE Marking Pathway | EU MDR compliance enables access to German university hospital systems under CSRD-aligned procurement. |
| Software Companion Development | Epic-integrated modules close the loop between algorithmic alert and nursing intervention workflow. |
| Reimbursement Strategy | CPT code capture for remote patient monitoring creates direct revenue lines for platform vendors. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down connected device shipment tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and FDA regulatory affairs specialists combined with secondary validation against CMS Medicare reimbursement databases, FDA 510(k) submission records, and hospital capital expenditure disclosures. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map algorithmic diagnostic adoption rates against reimbursement policy shifts across the projection horizon. Segmentation dimensions include product architecture, end-user facility type, technology validation tier, and clinical application intensity. CAGRs derive from regression analysis of historical procurement cycles correlated with regulatory milestone timing. Forecast inputs incorporate edge computing cost curves and semiconductor foundry capacity utilization.
The model assumes a particular technology adoption path; alternative pathways for generative AI clinical documentation would alter the outlook. Forecasts reflect documented assumptions about Medicare reimbursement parity sustainability and EU AI Act enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Behavioral Mental Health Care Software Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
US Real World Evidence Solutions Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
Global Clinical Workflow Solutions Market
Digital Health Solutions
Global Urgent Care Apps Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Mixed Reality in Healthcare Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market
Digital Health Solutions
Mhealth Services Market