
 Digiceuticals Market | 2026-2036
Digiceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Digiceuticals Market Analysis
Subscription-based access to software-defined therapeutic modules is broadening what pharmaceutical and technology companies actually sell in the digiceuticals space. Click Therapeutics leverages its prescription digital therapy platform to anchor behavioral health interventions with clinical trial backing. Akili Interactive Labs specializes in cognitive treatment software delivered through gaming interfaces for pediatric attention disorders. Biofourmis extends its reach through wearable-integrated algorithms that predict cardiac decompensation before hospitalization becomes necessary.
Digiceuticals comprise clinically validated software applications, sensor-integrated hardware, and algorithmic platforms designed to prevent, manage, or treat medical conditions through direct physiological or behavioral intervention, typically requiring regulatory clearance comparable to pharmaceutical products. The therapy area dimension shows mental health and diabetes management applications commanding established reimbursement frameworks, while cardiovascular disorder platforms capture premium pricing through remote monitoring integration. Mobile applications and wearable devices dominate product type volumes, though software solutions with embedded artificial intelligence command disproportionate margin pools due to scalability and lower incremental delivery costs.
The FDA breakthrough device designation and EMA health technology assessment frameworks shape market access timelines, with FDA 510(k) and de novo pathways determining commercial viability for US entrants while CE marking under the EU Medical Device Regulation governs European market entry. Payer reimbursement policies from CMS and national health technology assessment bodies in Germany and Japan determine which digital therapeutic modalities achieve sustainable prescription volumes. Stakeholders must monitor evolving evidentiary standards for real-world effectiveness data as regulators tighten requirements for software update protocols and algorithm change management.
Market Dynamics
Prescription digital therapeutics are restructuring pharmaceutical commercial models as software-based interventions secure parity reimbursement with small-molecule drugs through dedicated billing codes and regulatory clearance pathways.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway compresses development timelines for clinically validated software interventions targeting diabetes management and behavioral health conditions.
- Remote Patient Monitoring:Wearable-integrated algorithms predicting cardiac decompensation are expanding hospital-at-home programs and reducing acute care utilization.
- Germany's Digital Health Act:Fast-track reimbursement approval for prescription digital therapeutics creates sustainable revenue models for clinically validated applications.
Market Restraints
- Evidentiary Burden:Real-world effectiveness data requirements under tightening FDA software update protocols extend validation costs and timelines.
- Algorithm Change Management:Regulatory frameworks mandate pre-approval for machine learning model updates, constraining iterative improvement cycles.
- Physician Adoption Friction:Prescription workflows for software interventions require EHR integration investments that slow clinical uptake.
Strategic Opportunities
- Pediatric Cognitive Disorders:Gaming-interface therapeutic delivery addresses unmet attention-deficit treatment demand with measurable engagement metrics.
- EU MDR Convergence:Harmonized CE marking pathways under the Medical Device Regulation reduce fragmented national approval costs for software entrants.
- Japan's PMDA Sakigake:Priority review designation for innovative digital therapeutics accelerates market access for preventive cardiovascular platforms.
Industry Challenges
- Clinical Validation Talent:Scarce expertise in digital health trial design and health economics outcomes research constrains pipeline advancement.
- Legacy EHR Integration:Health system procurement cycles for software interoperability create deployment bottlenecks and implementation cost overruns.
- Algorithmic Bias Certification:Emerging requirements for demographic performance validation across patient populations complicate regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digiceuticals Market |
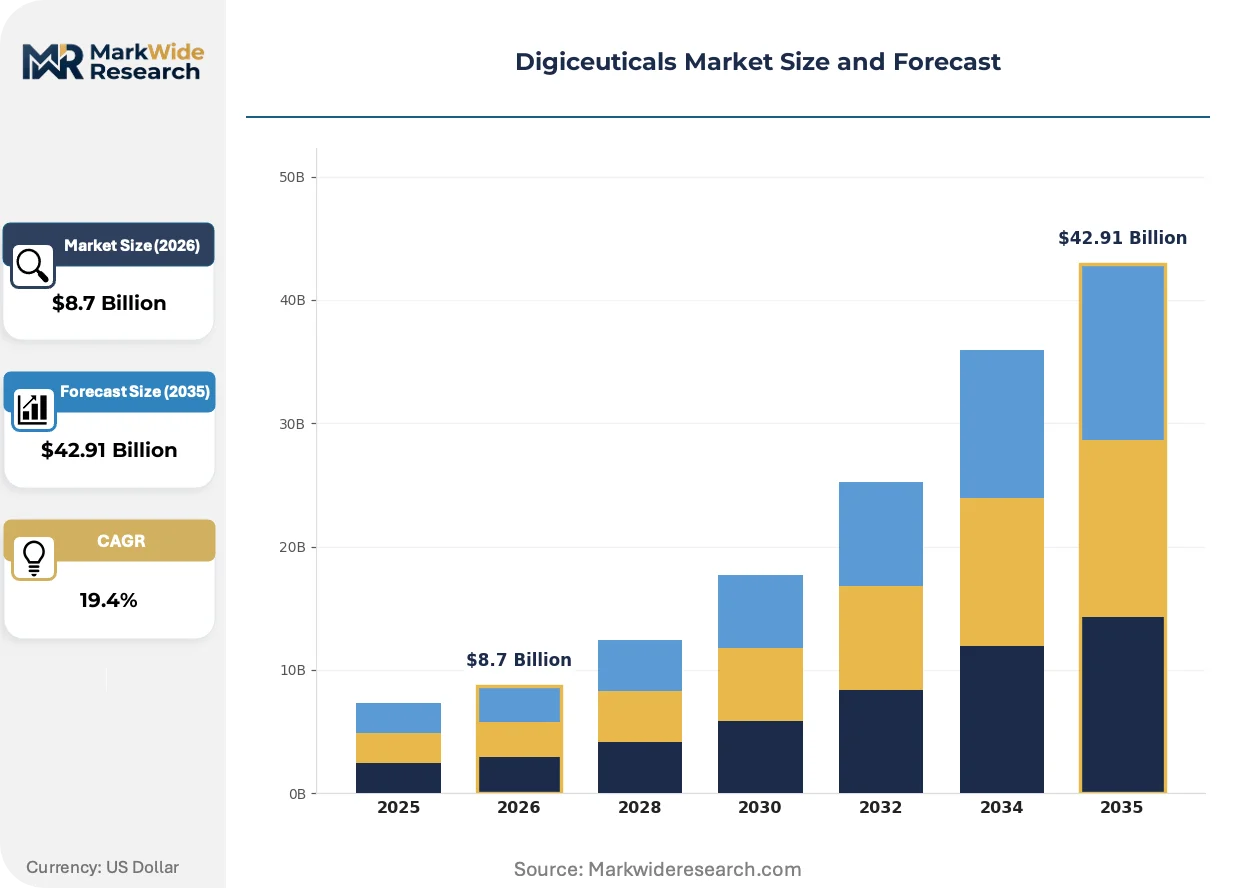
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Applications, Wearable Devices, Digital Therapeutics, Software Solutions Therapy Area: Mental Health, Chronic Pain, Cardiovascular Disorders, Diabetes Management End User: Patients, Healthcare Providers, Research Institutions, Payers Delivery Mode: Web-Based Platforms, Mobile-Based Platforms, Virtual Reality, Remote Monitoring |
| Companies Covered | Click Therapeutics Inc., Better Therapeutics Inc., Omada Health Inc., Noom Inc., Voluntis, Pear Therapeutics Inc., Akili Interactive Labs Inc., Biofourmis, Propeller Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digiceuticals Market Emerging Trajectories
Artificial intelligence is embedding into therapeutic software architectures, transforming static intervention protocols into adaptive systems that personalize dosing and behavioral nudges based on real-time physiological feedback.
Sensor-integrated prescription platforms is expanding into chronic disease management through continuous glucose monitors and blood pressure wearables that feed algorithmic treatment adjustments. Endocrinology practices in the United States are deploying these systems at accelerating velocity as CMS reimbursement codes stabilize. The technology is compressing traditional episodic care models into persistent therapeutic relationships with automated dose optimization.
EMA health technology assessment frameworks are tightening evidentiary standards for software-as-a-medical-device products across European markets. Manufacturers must now submit real-world performance data from post-market surveillance to maintain CE marking validity. Cardiovascular remote monitoring platforms face the steepest compliance burden as notified bodies scrutinize predictive algorithm accuracy claims.
Provider procurement preferences are gravitating toward bundled digital-physical therapeutic combinations that integrate software prescriptions with traditional pharmaceutical regimens. Hospital systems in Germany are restructuring formulary committees to evaluate total cost-of-care impact rather than standalone software pricing. This behavioral shift favors platforms demonstrating measurable hospitalization reduction through integrated disease management protocols.
Digiceuticals Market Segmentation
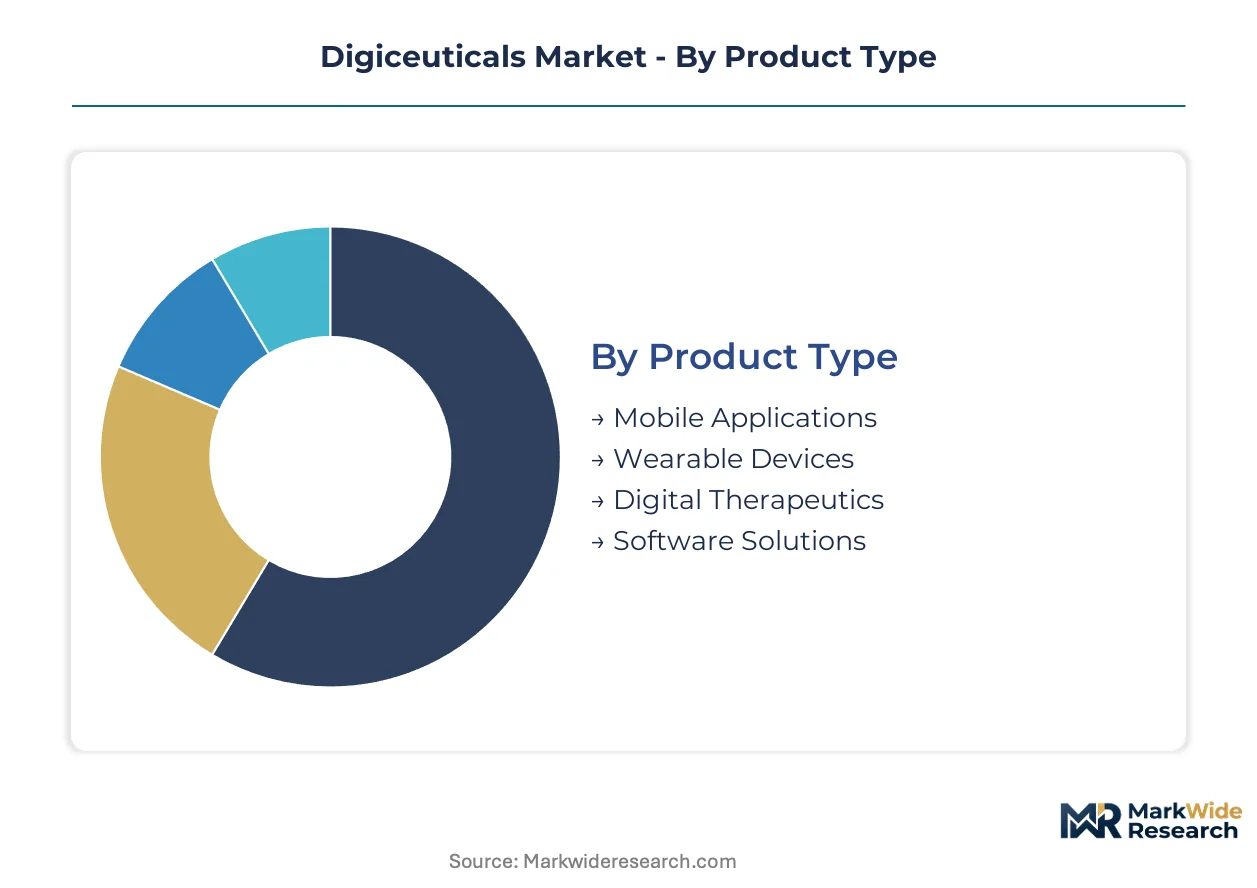
Digiceuticals require granular segmentation because software interventions, wearable hardware, and algorithmic platforms each navigate distinct regulatory pathways and reimbursement frameworks. Understanding where these categories overlap versus operate independently determines viable commercial strategies for developers and investors.
Product Type:
Standalone mobile applications operate at the surface layer of patient engagement, while embedded software solutions integrate deeply into clinical workflows and hospital information systems.
- Mobile Applications:Consumer-facing therapeutic software delivered through app stores requires prescription validation layers to achieve reimbursement parity. Demand clusters in the United States where CMS billing codes now recognize clinically validated mental health and diabetes management apps as reimbursable services.
- Wearable Devices:Sensor-integrated hardware platforms combine continuous physiological monitoring with algorithmic intervention protocols. Cardiovascular remote monitoring systems from Biofourmis and similar developers capture premium pricing through hospital-at-home program integrations in Germany and Japan.
- Digital Therapeutics:Prescription-grade software interventions requiring FDA 510(k) or de novo clearance demonstrate clinical outcomes equivalent to pharmaceutical comparators.
- Software Solutions:Enterprise-grade platforms embedding artificial intelligence for adaptive dosing and behavioral modification scale across health system deployments with lower incremental delivery costs.
Volume placements concentrate in mobile applications; the faster expansion belongs to software solutions with embedded AI architectures.
Therapy Area:
Mental health interventions command established reimbursement through dedicated billing codes, while cardiovascular platforms penetrate through remote monitoring integration and acute care avoidance metrics.
- Mental Health:Behavioral health software interventions address depression, anxiety, and substance use disorders through cognitive behavioral therapy protocols delivered via smartphone interfaces. Payers in the United States and Germany now reimburse these prescriptions at parity with traditional psychotherapy sessions.
- Diabetes Management:Continuous glucose monitor integration with insulin dosing algorithms compresses episodic endocrinology visits into persistent therapeutic relationships. CMS reimbursement stabilization has accelerated deployment velocity across American endocrinology practices.
- Chronic Pain:Non-opioid pain management applications reduce pharmaceutical dependency through neurostimulation and mindfulness-based protocols.
- Cardiovascular Disorders:Predictive algorithms analyzing heart rate variability and blood pressure trends enable pre-emptive intervention before decompensation events.
Revenue concentration sits with mental health applications; steepest expansion trajectory belongs to diabetes management through wearable-integrated dosing optimization.
End User:
Healthcare providers drive prescription volumes through EHR-integrated workflows, while payers increasingly demand real-world effectiveness data to justify formulary inclusion.
- Healthcare Providers:Physicians and health systems prescribe digiceuticals through integrated electronic health record interfaces that embed software prescriptions alongside pharmaceutical orders. Hospital systems in Germany restructure formulary committees to evaluate total cost-of-care impact.
- Payers:Insurance entities and national health services determine sustainable prescription volumes through coverage policies and health technology assessments. EMA frameworks now mandate post-market surveillance data for continued CE marking validity.
- Patients:Individual consumers access direct-to-consumer wellness applications falling outside prescription digital therapeutic definitions.
- Research Institutions:Academic medical centers generate clinical validation evidence supporting regulatory submissions and reimbursement negotiations.
Procurement authority concentrates with healthcare providers; the fastest-growing influence belongs to payers tightening evidentiary requirements for software update protocols.
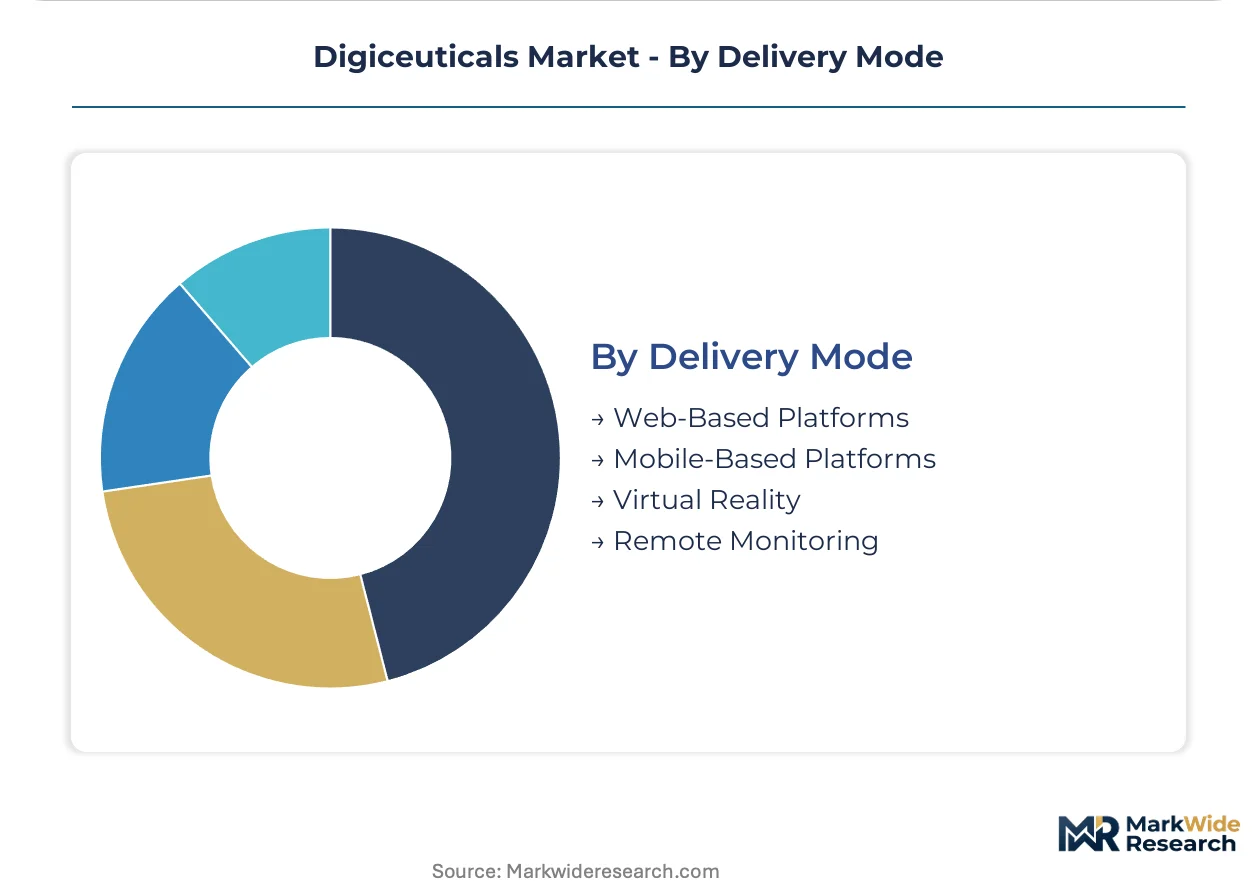
Delivery Mode:
Web-based platforms serve clinical environments requiring desktop workstation access, while mobile-based platforms dominate patient-facing engagement through smartphone ubiquity.
- Mobile-Based Platforms:Smartphone-native therapeutic delivery enables persistent patient engagement with push-notification behavioral nudges and real-time physiological feedback. Pediatric cognitive disorder treatments from Akili Interactive Labs leverage gaming interfaces on tablets to sustain attention-deficit therapy adherence.
- Remote Monitoring:Continuous data transmission from wearable sensors to cloud-based algorithms enables automated treatment adjustments without clinical intervention. Cardiovascular platforms face steepest EMA compliance burden as notified bodies scrutinize predictive accuracy claims.
- Web-Based Platforms:Browser-accessible therapeutic modules integrate with hospital information systems for clinician oversight and documentation.
- Virtual Reality:Immersive environments deliver exposure therapy and pain distraction protocols through head-mounted displays.
Patient engagement volumes concentrate in mobile-based platforms; the most rapid capability expansion belongs to remote monitoring through wearable-integrated predictive algorithms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American digiceutical development through its concentration of academic medical centers and FDA premarket review proximity. Venture funding for prescription digital therapeutic startups clusters along the Route 128 corridor. The metropolitan area hosts multiple clinical trial operations supporting 510(k) submissions for behavioral health and diabetes management platforms.
United States
CMS billing code expansions for clinically validated digital therapeutics drive prescription volumes through Medicare Advantage networks. FDA breakthrough device designations compress review timelines for diabetes management software seeking 510(k) clearance. The San Francisco Bay Area hosts venture-backed developers integrating continuous glucose monitors with insulin dosing algorithms for endocrinology practices.
Germany
Hospital-at-home program expansions create procurement demand for wearable-integrated cardiac monitoring platforms. The Digital Health Act fast-tracks reimbursement approval for prescription digital therapeutics through the Federal Institute for Drugs and Medical Devices. Berlin health systems restructure formulary committees to evaluate total cost-of-care impact from integrated disease management protocols.
Japan
Aging population demographics accelerate demand for remote patient monitoring in cardiovascular and diabetes management. PMDA Sakigake priority review designation expedites market access for preventive digital therapeutic platforms. Tokyo metropolitan hospitals deploy predictive algorithms analyzing heart rate variability to reduce acute care utilization among congestive heart failure patients.
United Kingdom
NHS England technology appraisal processes increasingly incorporate real-world effectiveness data requirements for software-as-a-medical-device products. MHRA guidance on machine learning medical devices shapes algorithm change management protocols for predictive cardiac platforms. London academic medical centers generate clinical validation evidence supporting EMA health technology assessment submissions for mental health interventions.
France
ANSM national reimbursement negotiations determine sustainable prescription volumes for cognitive behavioral therapy applications. HAS health technology assessment frameworks scrutinize pediatric attention disorder treatments delivered through gaming interfaces. Paris hospital systems pilot bundled digital-physical therapeutic combinations integrating software prescriptions with traditional pharmaceutical regimens for chronic pain management.
Digiceuticals Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as regulatory clearance requirements reshape competitive positioning. The vendor base stratifies across three tiers: venture-backed specialists pursuing FDA 510(k) pathways, pharmaceutical incumbents building digital therapeutic portfolios through acquisition, and health technology platforms extending into prescription-grade software. Market consolidation accelerates through strategic partnerships pairing behavioral health content developers with wearable hardware manufacturers. Portfolio diversification dominates competitive moves as single-condition platforms expand into adjacent therapy areas.
Within the venture-backed specialist tier, Click Therapeutics Inc., Akili Interactive Labs Inc., and Biofourmis occupy positions exemplifying distinct archetype strategies. Click Therapeutics Inc. represents the prescription digital therapy platform model anchoring behavioral health interventions with clinical trial infrastructure. Akili Interactive Labs Inc. exemplifies gaming-interface therapeutic delivery targeting pediatric cognitive disorders through engagement-optimized tablet applications. Biofourmis anchors the wearable-integrated algorithm segment through predictive cardiac decompensation platforms deployed in hospital-at-home programs. These three developers illustrate how regulatory clearance pathways and reimbursement code access determine sustainable commercial positioning across divergent product architectures.
| Leading Market Players |
|---|
| Click Therapeutics Inc. |
| Better Therapeutics Inc. |
| Omada Health Inc. |
| Noom Inc. |
| Voluntis |
| Pear Therapeutics Inc. |
| Akili Interactive Labs Inc. |
| Biofourmis |
| Propeller Health |
| Others |
Supply Flow & Price Mechanics
Hospital formulary committees demanding total cost-of-care evidence rather than standalone software pricing are forcing developers to restructure commercial models around bundled therapeutic combinations and value-based contracting.
Pricing Analysis
Margin tightening in prescription-grade software reflects CMS reimbursement code stabilization compressing premium capture for diabetes management platforms. Three-tier pricing structure across enterprise health system deployments, mid-size clinic networks, and individual physician practices separates volumes. Price differentiation hinges on FDA 510(k) clearance tier and embedded AI architecture sophistication. Payers exhibit highest price sensitivity; hospital systems with bundled procurement authority show lowest.
Supply Chain Analysis
Domestic-content mandates in Germany's Digital Health Act and Japan's PMDA Sakigake framework are reshaping clinical validation and regulatory submission sourcing toward local expertise clusters. Algorithm development concentrates in the United States, clinical trial operations in Germany, and wearable hardware manufacturing in Japan. Raw material dependencies span semiconductor chips for sensor integration, cloud computing infrastructure for algorithm hosting, and specialized clinical research organization services. Single-source vulnerability sits with FDA-designated contract research organizations. Distribution runs through health system procurement committees and national payer technology assessment pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digiceuticals occupy a technology-transition phase as adaptive AI architectures displace static intervention protocols across therapeutic software stacks.
For Market Incumbents: Lock in EHR integration partnerships with Epic and Cerner to defend prescription workflow positioning against emerging platform competitors. Deepen backward integration into clinical trial infrastructure to compress FDA 510(k) validation timelines and capture regulatory exclusivity windows. For New Entrants and Emerging Players: Enter via pediatric cognitive disorder applications where gaming-interface delivery commands measurable engagement premiums and reimbursement pathways remain underpenetrated. Target Germany's hospital-at-home program procurement as the fastest-accessible geography with established digital health reimbursement codes. For Investors and Strategic Acquirers: The window for entry favors venture-backed specialists with FDA breakthrough device designation and parallel EMA health technology assessment progress. Long-term viability centers on platforms demonstrating real-world effectiveness data generation capabilities. Watch CMS billing code expansion velocity as the inflection signal for sustainable prescription volume scaling.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses review timelines for diabetes management software seeking 510(k) clearance pathways. |
| CE Marking Pathway under EU MDR | Harmonizes software-as-a-medical-device access across fragmented European national markets. |
| Hospital System Partnership | Secures EHR-embedded prescription workflows through Epic and Cerner integration agreements. |
| Software Companion Development | Creates bundled digital-physical therapeutic combinations with traditional pharmaceutical regimens. |
| Reimbursement Strategy | Aligns CMS billing code submissions with Medicare Advantage network coverage policies. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with digital health executives, regulatory affairs specialists, hospital formulary directors, and payer access managers. FDA 510(k) databases, EMA health technology assessment submissions, ClinicalTrials.gov protocols, and CMS reimbursement code records provided validation layers. Bottom-up prescription volume modeling and top-down market sizing triangulated across analysis approaches.
Data-stream reconciliation across product type, therapy area, end user, and delivery mode segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from prescription volume trajectories, reimbursement code expansion rates, and health system procurement cycle timing. Real-world effectiveness data requirements and algorithm change management protocols served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA software update protocol tightening and EMA post-market surveillance mandate acceleration. Forecasts reflect documented assumptions regarding CMS billing code stability and health system EHR integration investment cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Mobile Health (Mhealth) Market
Digital Health Solutions
Healthcare Chatbots Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Patient Case Management Software Market
Digital Health Solutions
Digital Patient Engagement Solutions Market
Digital Health Solutions
Women Digital Health Solutions Market
Digital Health Solutions
Global Real World Evidence Solutions Market
Digital Health Solutions
Occupational Therapy Software Market
Digital Health Solutions
Long Term Care Software Market
Digital Health Solutions
North America Eclinical Solutions Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Mobile Tablets in Healthcare Market
Digital Health Solutions
Patient Engagement Technology Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Healthcare Mobile Application Market
Digital Health Solutions
Asia-Pacific Digital Therapeutic (Dtx) Market