
 Artificial Intelligence in Precision Medicine Market | 2026-2036
Artificial Intelligence in Precision Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Precision Medicine Market Intelligence
The FDA's Software as a Medical Device framework is broadening the cost-of-entry calculus for algorithm developers seeking clinical deployment. NVIDIA Corporation leverages its GPU architecture to dominate computational training workloads for genomic and imaging models. Tempus AI sustains vertical integration from wet-lab sequencing to predictive analytics, anchoring its position in oncology data networks. GE HealthCare navigates regulatory pathways across multiple jurisdictions while competing on diagnostic imaging AI embedded within existing hardware footprints.
Artificial Intelligence in Precision Medicine encompasses computational systems that analyze multi-omic, imaging, and electronic health record data to predict individual patient treatment responses, typically operating through deep learning architectures trained on curated clinical datasets with validation thresholds exceeding 85% concordance with expert pathologist diagnoses. Diagnostic Tools command the largest installed base due to regulatory familiarity and reimbursement clarity, though Personalized Treatment Solutions represent the fastest-expanding margin pool as pharmaceutical companies seek companion algorithm partnerships. Cloud-based Solutions lead delivery mode adoption among research institutions requiring elastic compute for population-scale genomic studies, while On-premise Solutions persist in hospital systems governed by stringent data residency requirements.
The FDA, EMA, and WHO collectively shape market access through divergent evidentiary standards for clinical AI validation, with the FDA's predetermined change control plans enabling iterative algorithm updates and the EMA's medical device regulation demanding static locked models post-certification. ISO 13485 quality management and IEC 62304 software lifecycle standards further constrain development economics for entrants lacking established regulatory infrastructure. Stakeholders must monitor evolving payer coverage determinations for algorithm-augmented diagnostics, as reimbursement parity with traditional testing modalities will determine commercial scalability regardless of technical performance benchmarks.
Market Dynamics
The FDA's predetermined change control plans for AI/ML-based Software as a Medical Device are compressing validation timelines while simultaneously elevating documentation burdens for algorithm developers seeking iterative deployment authority.
Growth Catalysts
- NIH Funding Concentration:United States federal research grants accelerate clinical validation cycles for multi-omic predictive models at academic medical centers.
- Oncology Protocol Standardization:AI-guided biomarker selection is becoming mandatory protocol at major cancer centers, creating installed base expansion.
- GPU Architecture Advances:Parallel processing hardware improvements reduce training costs for deep learning architectures on genomic and imaging datasets.
Market Restraints
- EMA Medical Device Regulation:Static locked-model requirements post-certification prevent iterative algorithm updates that FDA frameworks permit.
- High-Performance Computing Costs:Elastic cloud compute for population-scale genomic studies consumes substantial operating budgets at research institutions.
- Data Residency Requirements:Hospital systems in jurisdictions with stringent privacy laws face infrastructure duplication costs for on-premise deployment.
Strategic Opportunities
- Companion Algorithm Partnerships:Pharmaceutical companies seek predictive analytics partnerships for drug development and patient stratification.
- Integrated Payer-Provider Systems:United States healthcare consolidation creates centralized procurement channels for algorithm-augmented diagnostics.
- ISO 13485 Infrastructure Gap:Quality management certification scarcity among entrants creates acquisition targets for established regulatory players.
Industry Challenges
- Interoperability Friction:Electronic health record system fragmentation forces costly custom integration for each hospital deployment.
- Reimbursement Parity Delays:Payer coverage determinations for algorithm-augmented diagnostics lag behind traditional testing modality rates.
- Expert Pathologist Concordance Thresholds:Validation requirements exceeding 85% agreement create annotation bottleneck and quality control expenses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Precision Medicine Market |
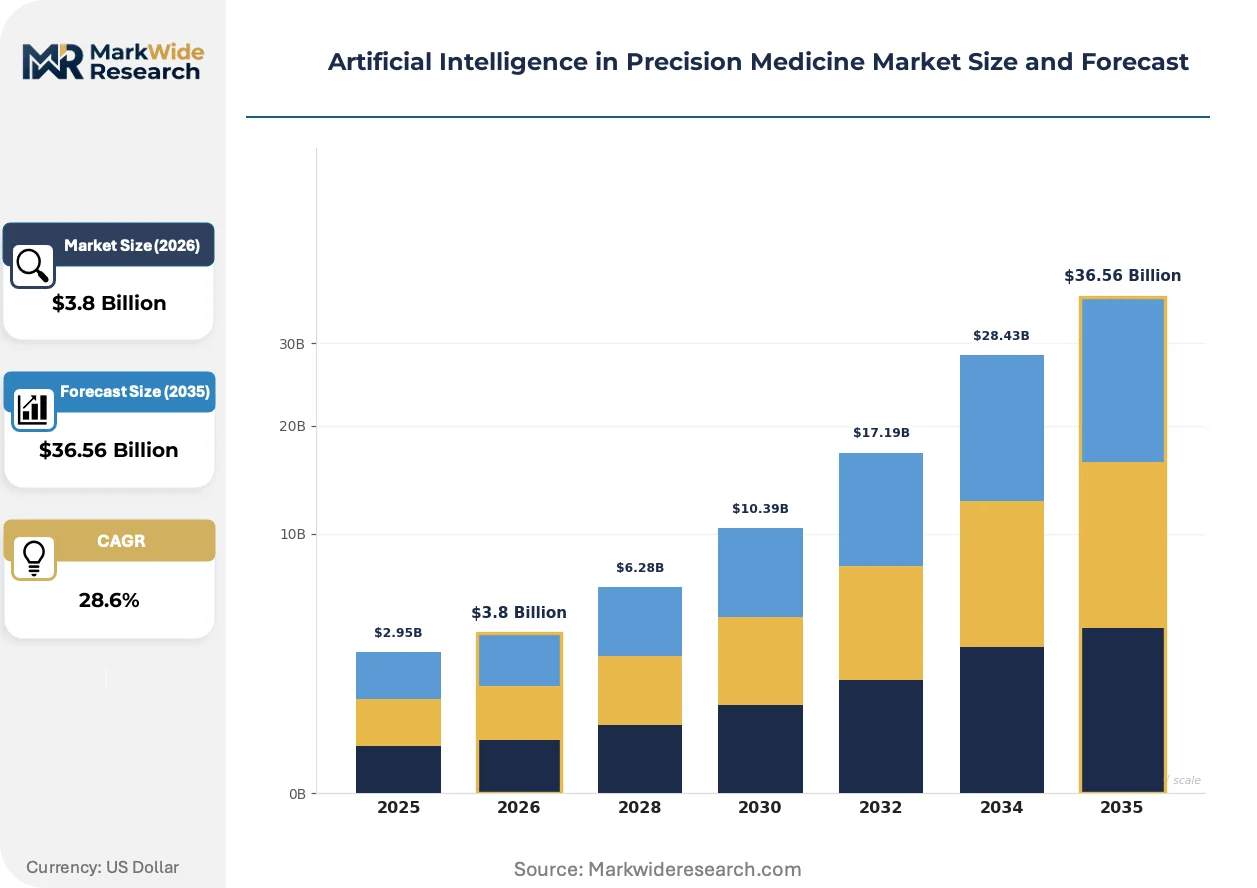
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Data Analytics Software, Clinical Decision Support Systems, Personalized Treatment Solutions Delivery Mode: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Software as a Service End User: Hospitals, Diagnostic Laboratories, Research Institutions, Pharmaceutical Companies Application: Genomics, Imaging, Drug Discovery, Patient Management |
| Companies Covered | NVIDIA Corporation, Tempus AI, GE HealthCare, Alphabet Inc., IBM, Microsoft, Illumina, PathAI, Proscia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Precision Medicine Market Strategic Shifts & Innovations
Deep learning architectures are integrating multi-modal data streams in ways that compress the gap between research-grade models and clinical deployment requirements.
Federated learning architectures are integrating patient data across institutional boundaries without centralizing protected health information. Academic medical centers in the United States and university hospitals in Germany are deploying these frameworks for multi-site genomic studies. This approach is integrating privacy-preserving computation with expanded training dataset scale, reducing the legal friction that previously fragmented research collaborations.
The EU AI Act's risk classification system for medical devices is forcing algorithm developers to restructure quality management documentation before market access. High-risk AI system requirements demand conformity assessments that exceed current ISO 13485 scope. European oncology diagnostics manufacturers are responding by segregating EU-specific model versions from iterative update pipelines serving FDA jurisdictions.
Hospital procurement committees are consolidating vendor relationships around platforms offering both diagnostic imaging and genomic prediction modules. Integrated delivery networks in the United States are displacing point-solution contracts with enterprise-wide algorithm licensing. This concentration is most visible at academic medical centers where oncology departments anchor purchasing decisions for system-wide AI infrastructure.
Artificial Intelligence in Precision Medicine Market Segmentation
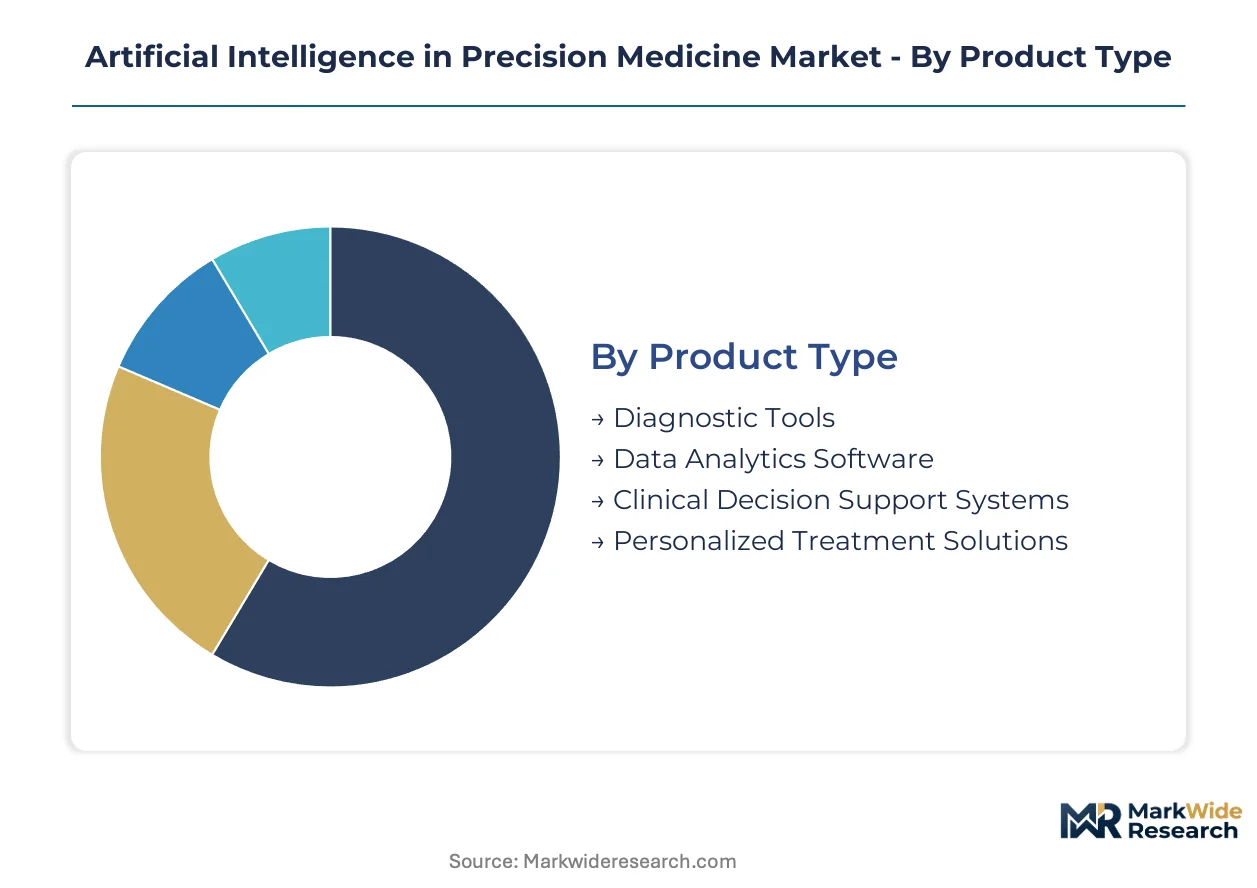
Segmentation in AI precision medicine reveals how computational capabilities align with distinct clinical workflows and infrastructure constraints. Each dimension exposes different buyer priorities, from regulatory risk tolerance to data sovereignty requirements.
Product Type:
Supply concentration clusters around diagnostic imaging modules where FDA 510(k) pathways offer predictable clearance timelines.
- Diagnostic Tools:Deep learning algorithms analyzing histopathology slides and radiological images with validation thresholds exceeding 85% concordance against expert pathologists. Demand concentrates at academic medical centers in the United States where NIH-funded validation studies accelerate procurement decisions.
- Personalized Treatment Solutions:Predictive models matching patients to targeted therapies based on multi-omic signatures and real-world evidence integration. Pharmaceutical companies in Boston and San Francisco anchor demand through companion algorithm partnerships for oncology drug development.
- Data Analytics Software:Population-scale genomic analysis platforms processing variant calling and pathway enrichment.
- Clinical Decision Support Systems:EHR-integrated recommendation engines flagging contraindications and dosing optimizations.
Today's leader: Diagnostic Tools. Tomorrow's challenger: Personalized Treatment Solutions.
Delivery Mode:
Cost tier stratification separates research institutions with elastic compute budgets from hospital systems facing capital expenditure constraints.
- Cloud-based Solutions:Scalable infrastructure for population-scale genomic studies with pay-per-compute pricing models. Research institutions in Germany and the United States dominate consumption, driven by federated learning architectures requiring distributed coordination without data centralization.
- On-premise Solutions:Air-gapped deployments satisfying HIPAA and EU GDPR data residency mandates for protected health information. Hospital systems in France and California absorb premium hardware costs to maintain jurisdictional compliance over patient records.
- Hybrid Solutions:Split architectures processing anonymized training data in cloud while retaining identifiable inference locally.
- Software as a Service:Subscription-based diagnostic modules with standardized API integrations for EHR connectivity.
Cloud-based Solutions hold current volume leadership. On-premise Solutions are gaining share fastest among integrated delivery networks with compliance-heavy oncology portfolios.
End User:
Application maturity varies sharply across customer types, with diagnostic laboratories demanding locked-model stability while research institutions pursue iterative updates.
- Hospitals:Enterprise-wide algorithm licensing for diagnostic imaging and clinical decision support. United States integrated delivery networks in Texas and Pennsylvania centralize procurement through oncology department anchor contracts.
- Pharmaceutical Companies:Patient stratification algorithms for clinical trial enrollment and biomarker-driven drug development. Demand clusters in Basel, Cambridge, and South San Francisco where R&D pipelines integrate predictive analytics from discovery through Phase III.
- Diagnostic Laboratories:High-throughput pathology screening with batch processing optimization.
- Research Institutions:Exploratory multi-omic modeling with less stringent validation requirements than clinical deployment.
Hospitals command the largest installed base. Pharmaceutical Companies represent the steepest expansion trajectory through companion algorithm partnerships.
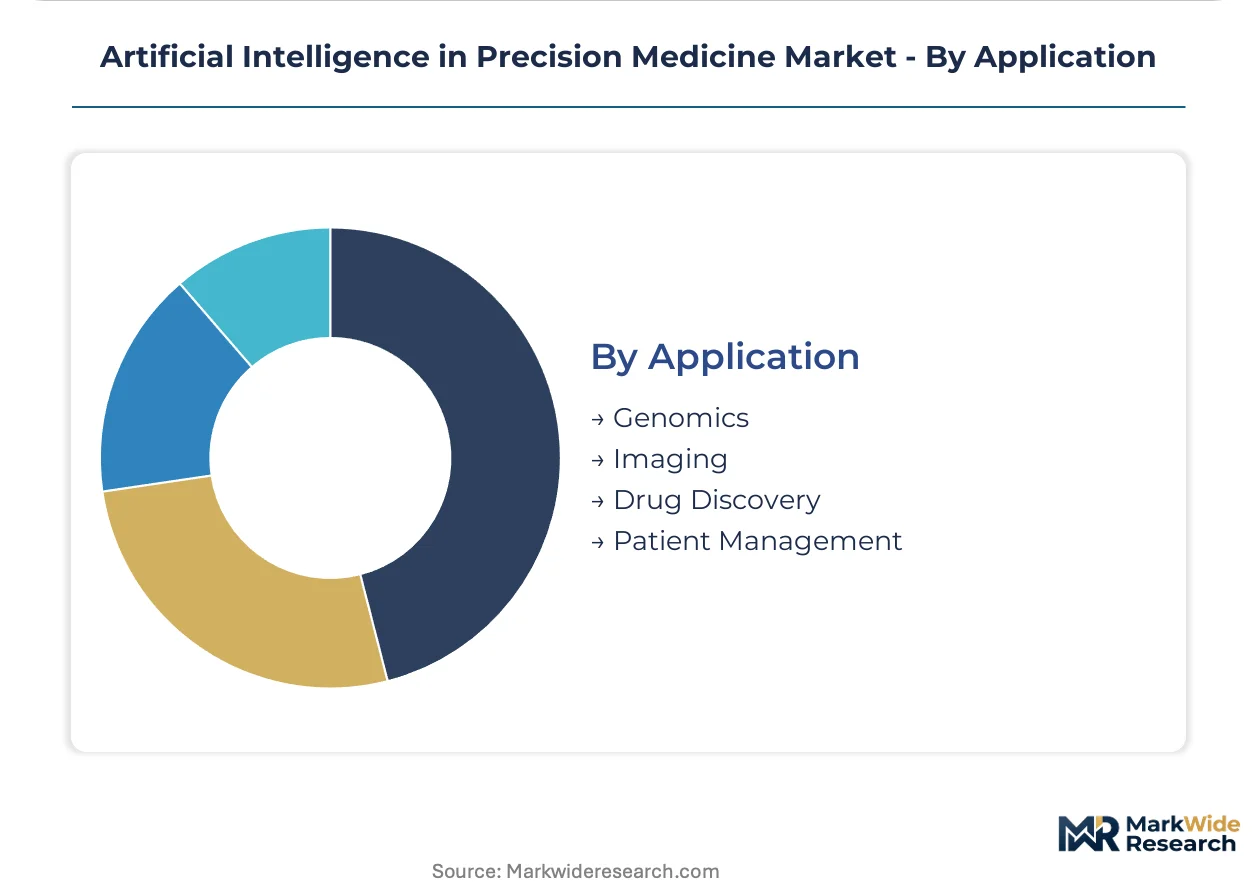
Application:
Volume concentration in genomics reflects plummeting sequencing costs, while imaging benefits from established reimbursement codes.
- Genomics:Variant interpretation pipelines and polygenic risk scoring across germline and somatic contexts. Research consortia in the United Kingdom and Netherlands deploy federated learning for multi-site cohort analysis without centralizing raw sequence data.
- Imaging:Radiomics feature extraction and automated lesion detection in CT, MRI, and digital pathology. Academic medical centers in New York and Heidelberg standardize AI-guided biomarker selection for oncology staging protocols.
- Drug Discovery:Molecular generative models and target identification through knowledge graph embeddings.
- Patient Management:Treatment response prediction and adverse event forecasting from longitudinal EHR trajectories.
Imaging leads current clinical deployment. Genomics is climbing the fastest as sequencing integration becomes mandatory at major cancer centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computational biology talent clusters in Boston and San Francisco anchor North American dominance, while regulatory divergence between FDA and EMA frameworks fragments deployment strategies across jurisdictions.
United States
NIH-funded academic medical centers in New York and Texas drive validation cycles for multi-omic predictive models. FDA predetermined change control plans enable iterative algorithm updates unavailable in European jurisdictions. Boston's Kendall Square biotech corridor concentrates pharmaceutical company R&D partnerships for companion algorithm development.
Germany
University hospitals in Heidelberg and Munich deploy federated learning architectures for multi-site genomic studies without centralizing patient data. EMA medical device regulation demands static locked models post-certification, preventing iterative updates. The country's national pharmaceutical regulator enforces conformity assessments exceeding ISO 13485 scope for high-risk AI diagnostics.
United Kingdom
Research consortia in Cambridge and London coordinate population-scale genomic analysis through cloud-based elastic compute infrastructure. National Health Service procurement centralization creates volume concentration for diagnostic imaging AI vendors. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit with FDA frameworks more closely than EMA static-model requirements.
China
NMPA regulatory pathways for AI-based Software as a Medical Device accelerate domestic algorithm commercialization timelines. Hospital systems in Beijing and Shanghai absorb premium on-premise hardware costs to satisfy data residency mandates. The national medical products administration prioritizes indigenous GPU architecture development to reduce training cost dependencies.
India
CDSCO regulatory harmonization efforts attract contract research organizations conducting clinical validation for Western market entry. Hospital chains in Mumbai and Bangalore pilot diagnostic imaging modules with 85% pathologist concordance thresholds. The national pharmaceutical regulator streamlines import licensing for cloud-based genomic analysis platforms serving research institutions.
Artificial Intelligence in Precision Medicine Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Semiconductor hardware manufacturers with GPU architectures anchor the infrastructure layer, while vertical-integrated sequencing-to-analytics platforms occupy the data layer. Diagnostic imaging incumbents embed algorithms within existing hardware footprints to defend installed base positions. Dominant competitive moves include strategic partnerships for companion algorithm development and regulatory infrastructure acquisitions to accelerate multi-jurisdiction clearance timelines.
Within the infrastructure-specialist tier, NVIDIA Corporation exemplifies compute-layer dominance through parallel processing hardware that reduces genomic model training costs. Tempus AI and GE HealthCare anchor distinct strategic positions—one representing wet-lab-to-algorithm vertical integration, the other exemplifying embedded diagnostic imaging AI within established hardware ecosystems. These three entities collectively illustrate how regulatory navigation capabilities, compute infrastructure control, and clinical data network scale constitute the primary vectors of competitive differentiation.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Tempus AI |
| GE HealthCare |
| Alphabet Inc. |
| IBM |
| Microsoft |
| Illumina |
| PathAI |
| Proscia |
| Others |
Cost & Logistics Intelligence
Computational biology PhD concentrations in Boston and San Francisco Bay Area create acute labor-cost differentials that widen pricing-tier spreads between premium algorithm developers and commodity analytics providers.
Pricing Analysis
Bundled end-to-end oncology platforms command substantial premiums over unbundled point-solution modules. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic tools from research-use-only analytics and open-source genomic pipelines. Price differentiation rests on ISO 13485 certification status and EHR integration depth. Pricing pressure stems from cloud compute commoditization eroding infrastructure margins. Pharmaceutical companies exhibit lowest price sensitivity due to companion algorithm partnership budgets, while community hospital systems face acute procurement constraints.
Supply Chain Analysis
China's NMPA domestic-content mandates for GPU architecture development are reshaping sourcing patterns for training hardware. Supply concentrates in Taiwan for advanced semiconductor fabrication, the United States for NVIDIA GPU design, and China for indigenous AI chip production. The chain draws from silicon wafers, high-bandwidth memory modules, and specialized cooling systems. Single-source vulnerability around TSMC's 4nm process node creates systemic concentration risk. Distribution runs through direct enterprise sales for hospital systems and cloud marketplace channels for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where pharmaceutical companion algorithm partnerships shift demand toward premium specifications with locked-model stability guarantees.
For Market Incumbents: Cement regulatory infrastructure advantages by acquiring ISO 13485-certified quality management systems from distressed entrants facing EMA compliance costs. Deepen backward integration into wet-lab sequencing capacity to defend data network effects against cloud-native challengers. Prioritize FDA predetermined change control plan investments to maintain iterative deployment authority unavailable under European static-model requirements.
For New Entrants and Emerging Players: Enter via federated learning infrastructure gaps at German university hospitals where EMA locked-model rules disadvantage iterative incumbents. Target India's CDSCO harmonization pathway for cost-efficient clinical validation serving Western market entry. Pursue white-label genomic analytics partnerships with diagnostic laboratories seeking batch processing optimization without captive algorithm development.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap sequencing-to-analytics platforms lacking pharmaceutical companion algorithm revenue streams. Long-term viability across the analysis window favors entities with locked hospital system contracts and NIH-funded validation study pipelines. Monitor NMPA domestic-GPU mandates as inflection signal for China market access restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Predetermined Change Control Plan Submission | Unlocks iterative algorithm updates prohibited under EMA static-model requirements. |
| Companion Algorithm Partnership with Pharma | Secures premium revenue streams from oncology drug development pipelines. |
| Federated Learning Architecture Deployment | Enables multi-site genomic studies without centralizing protected health information. |
| ISO 13485 Quality Management Acquisition | Accelerates multi-jurisdiction clearance timelines for regulatory-constrained entrants. |
| EHR Integration API Standardization | Reduces interoperability friction that fragments hospital procurement decisions. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down GPU infrastructure tracking forms the analytical core of this study. Primary interviews with oncology informaticists, hospital purchasing committee chairs, pharmaceutical R&D partnership leads, and regulatory affairs specialists at algorithm developers were cross-validated against FDA 510(k) clearance databases, NIH grant award records, EMA medical device registration filings, and cloud hyperscaler healthcare vertical revenue disclosures.
Historical trendline analysis of academic medical center AI adoption curves informed projection modeling across product type, delivery mode, end user, and application segmentation dimensions. CAGRs were derived from regression-weighted consensus of installed base expansion rates and pricing trajectory assumptions. Forecast inputs incorporated pharmaceutical companion algorithm partnership announcement velocity and federated learning consortium formation patterns.
Inputs from FDA predetermined change control plan documentation were available through the study window; gaps in real-time EMA conformity assessment timelines introduce uncertainty bands around European deployment forecasts. Forecasts reflect assumptions regarding NIH funding continuity and cloud compute cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Care Management Solutions Market
Digital Health Solutions
Mhealth Apps Market
Digital Health Solutions
AI-Powered Clinical Decision Support Market
Digital Health Solutions
Digital Therapeutics Market
Digital Health Solutions
Global Emergency Medical Services Billing Software Market
Digital Health Solutions
Advanced Clinical Decision Support Platforms Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
North America Virtual Reality (VR) Health Market
Digital Health Solutions
Artificial Intelligence in Medicine Market
Digital Health Solutions
Patient Engagement Platforms Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Global Preventive Healthcare Technologies and Services Market
Digital Health Solutions
Middle East and Africa Wireless Healthcare Market
Digital Health Solutions
Prescribed Health Apps Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Mixed Reality in Healthcare Market