
 Spain Diagnostic Imaging Equipment Market | 2026-2036
Spain Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Diagnostic Imaging Equipment Market Analytics
Consolidation among public hospital buyers is restructuring procurement dynamics across Spain's autonomous communities. Large regional health services now aggregate diagnostic imaging tenders, reducing vendor fragmentation. Siemens Healthineers leverages its installed base in magnetic resonance to sustain service contract renewals. GE Healthcare anchors its position through CT scanner placements in Madrid's major teaching hospitals. Esaote SpA specializes in ultrasound systems, competing on portability for outpatient clinic networks.
Diagnostic imaging equipment encompasses systems that generate visual representations of internal body structures for clinical diagnosis, with modalities ranging from X-ray tubes operating at 20-150 kVp to MRI scanners utilizing superconducting magnets at 1.5-3 Tesla. These systems serve primarily to detect disease, guide interventions, and monitor therapeutic response across hospital and ambulatory settings. X-ray and CT scanner segments dominate installed volume, though MRI commands premium pricing per unit. Ultrasound represents the fastest-growing modality in outpatient and point-of-care settings. Digital imaging technology leads conversion from analog film, while oncology applications drive advanced modality utilization across Spain's cancer referral networks.
Spain's national pharmaceutical and medical device regulator, the Spanish Agency for Medicines and Health Products, enforces EU MDR compliance timelines for legacy device recertification. BIS-equivalent standards alignment through EU harmonization ensures cross-border market access for manufacturers. The EU AI Act introduces conformity requirements for machine-learning diagnostic algorithms embedded in imaging software. Stakeholders must monitor autonomous community budget cycles and EU funding program allocations to anticipate capital replacement waves.
Market Dynamics
Consolidated tendering frameworks under Spain's National Health System are restructuring capital allocation patterns across autonomous communities. Regional health services now aggregate diagnostic imaging procurement, compressing vendor access windows and elevating service contract terms as competitive differentiators.
Growth Catalysts
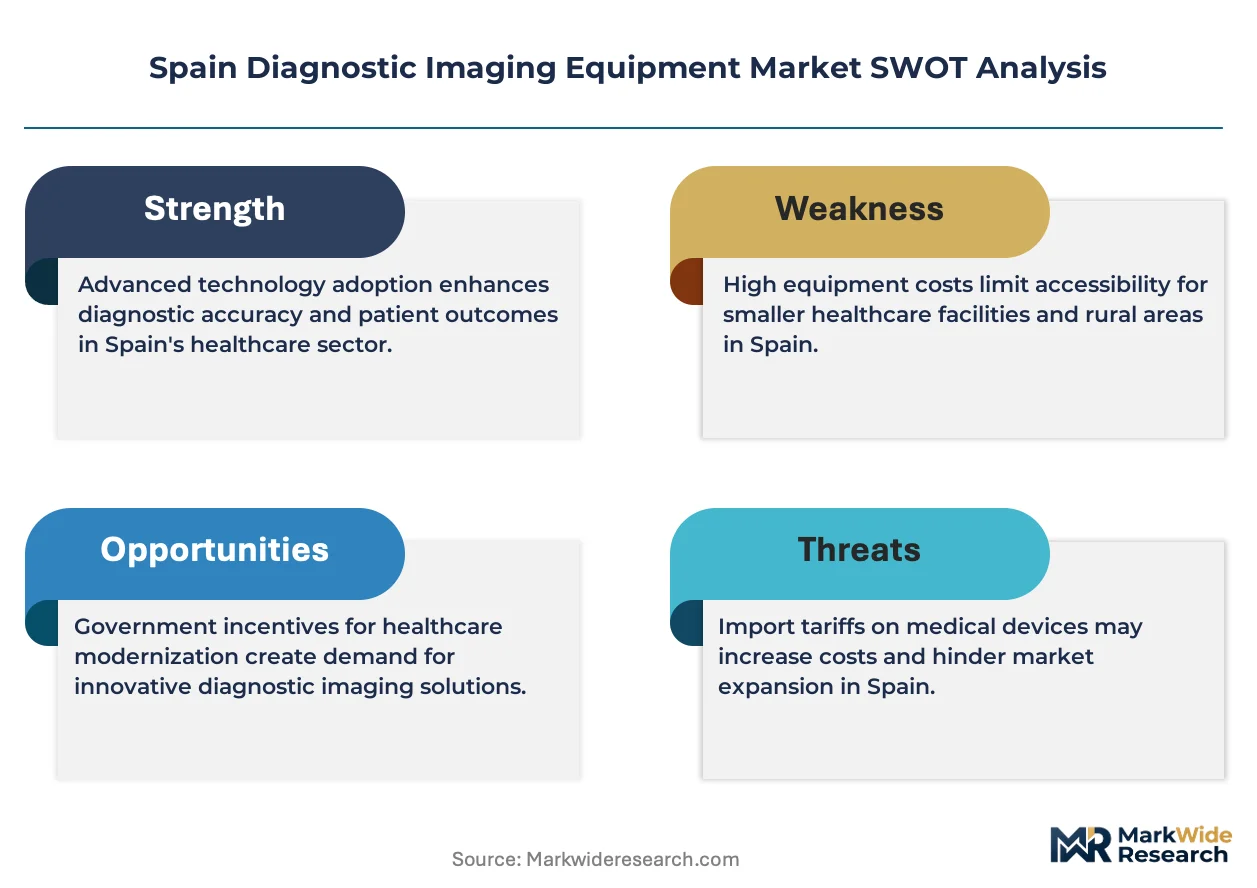
- EU Medical Device Regulation:Legacy device recertification timelines are accelerating replacement cycles for installed MRI and CT systems. Hospitals must upgrade or retire non-compliant equipment.
- Tertiary referral networks:Madrid and Catalonia anchor capital deployment through specialized oncology and cardiovascular centers requiring advanced modalities.
- Digital imaging conversion:Analog-to-digital transitions in outpatient clinics drive ultrasound and portable X-ray demand outside hospital networks.
Market Restraints
- Superconducting magnet supply concentration:MRI system production depends on niobium-titanium wire sources concentrated outside Europe, exposing Spanish buyers to input volatility.
- EU MDR conformity assessment backlog:Notified body capacity constraints extend certification timelines for software-enabled imaging devices.
- Computed radiography substitution:Direct digital radiography systems displace CR-based workflows, stranding intermediate-technology investments in smaller facilities.
Strategic Opportunities
- Point-of-care ultrasound expansion:Emergency departments and primary care centers in Andalusia and Valencia seek portable systems for triage acceleration.
- AI-embedded diagnostic software:Machine-learning algorithms for lesion detection create aftermarket revenue streams atop hardware placements.
- Autonomous community budget cycles:EU recovery fund allocations to regional health services concentrate capital releases in 2024-2026 windows.
Industry Challenges
- Clinical engineer shortage:Specialized biomedical technician training programs in Spain fail to match MRI and CT maintenance workforce requirements.
- Legacy PACS integration:New imaging systems must interface with heterogeneous picture archiving infrastructures across merged hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Diagnostic Imaging Equipment Market |
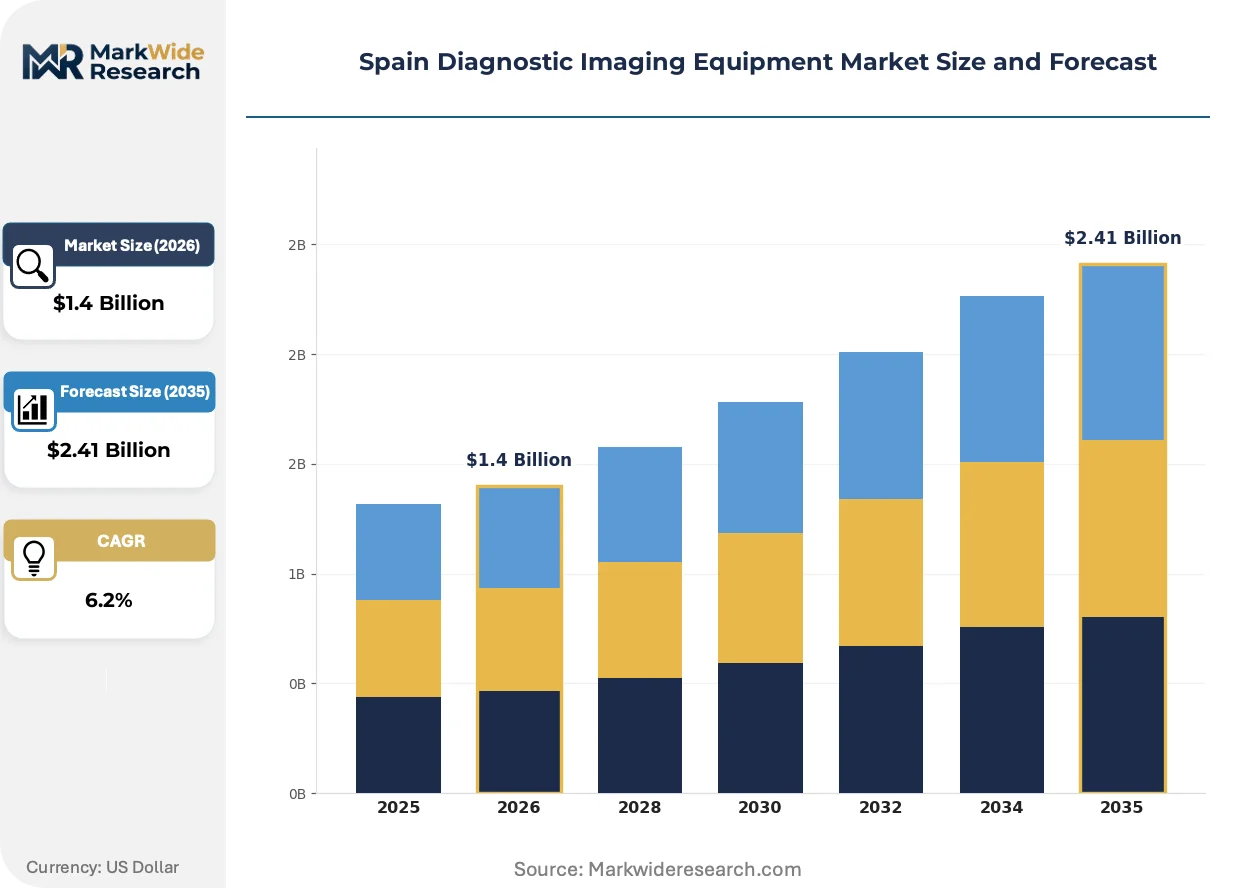
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, MRI, CT Scanners, Ultrasound End User: Hospitals, Clinics, Diagnostic Labs, Research Facilities Technology: Digital Imaging, Computed Tomography, Nuclear Medicine, Magnetic Resonance Application: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Fujifilm Holdings Corporation, Carestream Health, GE Healthcare, Hologic Inc, Esaote SpA, Siemens Healthineers, Canon, Shimadzu Corporation, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Diagnostic Imaging Equipment Market Evolving Landscape
Artificial intelligence integration and point-of-care modality expansion are compressing traditional radiology workflows. Spain's health system restructuring accelerates technology deployment decisions.
Portable ultrasound systems with AI-assisted image interpretation are decentralizing diagnostic capabilities from centralized radiology departments to emergency wards and outpatient clinics. Hospital networks in Catalonia deploy these units for rapid triage. The shift is compressing specialist radiologist consultation queues while elevating frontline clinical decision speed.
The EU AI Act introduces conformity requirements for machine-learning diagnostic algorithms embedded in imaging software. Spanish Agency for Medicines and Health Products enforcement timelines align with MDR recertification waves. Radiology software vendors must now submit algorithmic transparency documentation alongside traditional safety dossiers.
Regional health services are consolidating equipment tenders into multi-year framework agreements that bundle hardware, software, and maintenance. Large hospital trusts in Madrid negotiate directly with manufacturers, displacing traditional distributor intermediaries. The model concentrates purchasing power while extending vendor lock-in through integrated service terms.
Spain Diagnostic Imaging Equipment Market Segmentation
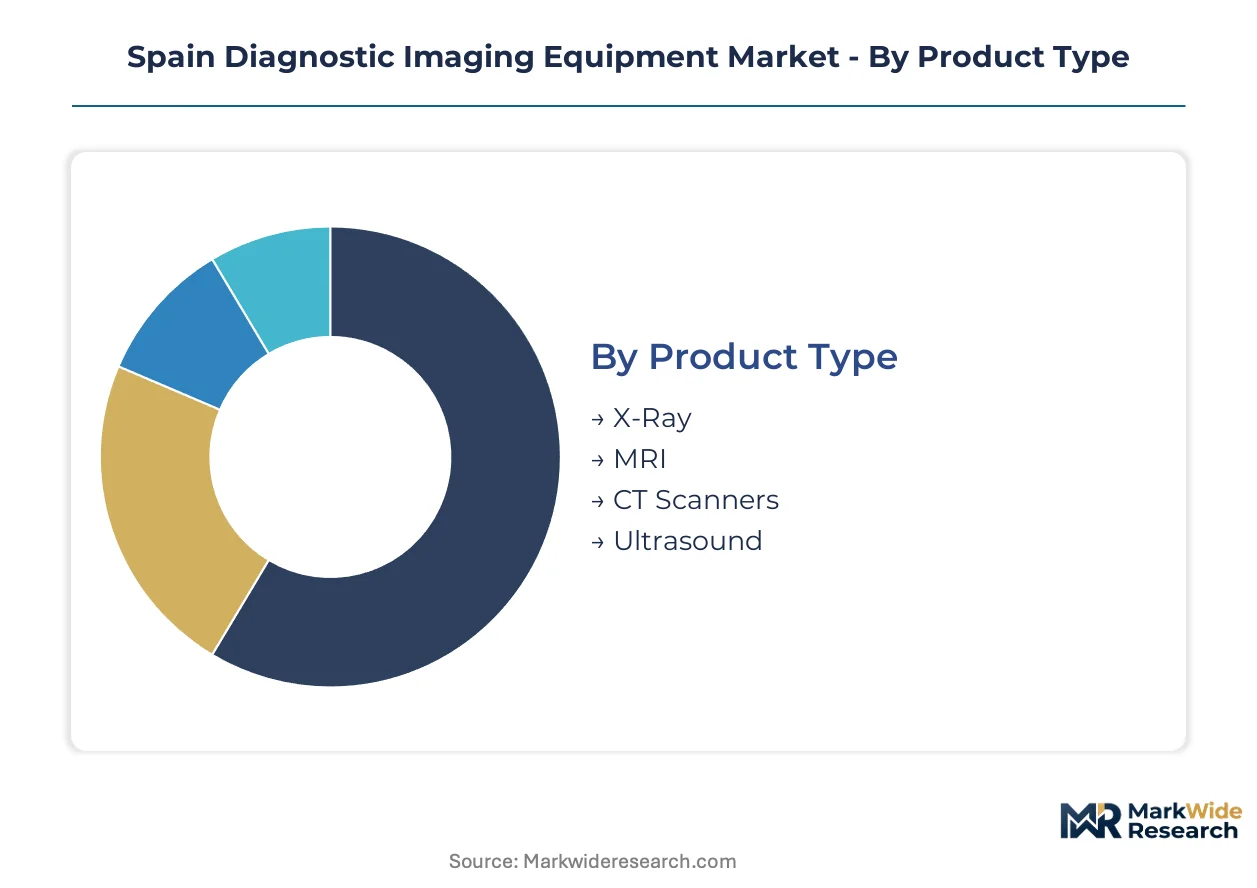
Diagnostic imaging equipment segments split sharply between high-volume workhorse modalities and premium systems commanding specialized clinical workflows. Understanding these tiered demand patterns enables vendors to align R&D investment with procurement cycles across Spain's autonomous communities.
Product Type:
X-Ray and CT scanner volumes dominate installed base counts while MRI systems extract premium pricing per unit through superconducting magnet technology.
- X-Ray:Conventional radiography systems operate at 20-150 kVp for skeletal and chest imaging. Demand concentrates in primary care networks across Andalusia and Valencia where digital detector retrofits replace aging analog units under EU recovery fund allocations.
- MRI:Superconducting systems utilizing 1.5-3 Tesla magnets enable soft-tissue visualization without ionizing radiation. Madrid's tertiary oncology centers anchor capital deployment as MDR recertification timelines force legacy system replacements.
- CT Scanners:Multi-detector arrays generate cross-sectional anatomical datasets through rotating X-ray sources. Emergency departments in Catalonia drive demand for rapid trauma assessment capabilities.
- Ultrasound:Piezoelectric transducer systems provide real-time imaging without radiation exposure. Portable configurations are gaining share fastest in outpatient clinic networks seeking point-of-care deployment flexibility.
Today's leader: X-Ray. Tomorrow's challenger: Ultrasound.
End User:
Procurement authority concentrates in consolidated hospital trusts while smaller facilities fragment purchasing decisions across distributor channels.
- Hospitals:Acute care institutions with centralized radiology departments manage high-throughput imaging workflows. Regional health services in Madrid aggregate tendering for multi-site equipment standardization.
- Clinics:Ambulatory facilities prioritize compact footprint systems for same-day diagnostic services. Primary care networks in Catalonia deploy portable ultrasound for frontline triage acceleration.
- Diagnostic Labs:Independent imaging centers operate on per-scan revenue models requiring rapid patient turnover. Private operators in Barcelona concentrate PET-CT investments for oncology referral networks.
- Research Facilities:University-affiliated institutions demand experimental imaging protocols and algorithm development environments. Biomedical research clusters in Madrid and Barcelona anchor preclinical MRI placements.
Hospital procurement volumes dominate current revenue; clinic point-of-care expansion shows steepest trajectory.
Technology:
Digital detector platforms displace analog film while software-enabled modalities create aftermarket service dependencies.
- Digital Imaging:Flat-panel detector systems capture radiographic images without chemical processing. Direct digital radiography is displacing computed radiography in Spanish facilities seeking workflow efficiency gains.
- Computed Tomography:Spiral acquisition techniques reconstruct volumetric datasets through iterative reconstruction algorithms. Stroke centers in Valencia prioritize dual-energy CT for hemorrhage characterization.
- Nuclear Medicine:Gamma camera and PET systems detect radiopharmaceutical distribution for functional assessment. Cancer referral networks drive SPECT-CT hybrid system placements in Madrid.
- Magnetic Resonance:Radiofrequency pulse sequences exploit nuclear magnetic resonance for soft-tissue contrast. EU MDR recertification deadlines accelerate replacement cycles for pre-2017 installed base.
Digital imaging holds current volume leadership; AI-embedded magnetic resonance software layers represent emerging value capture.
Application:
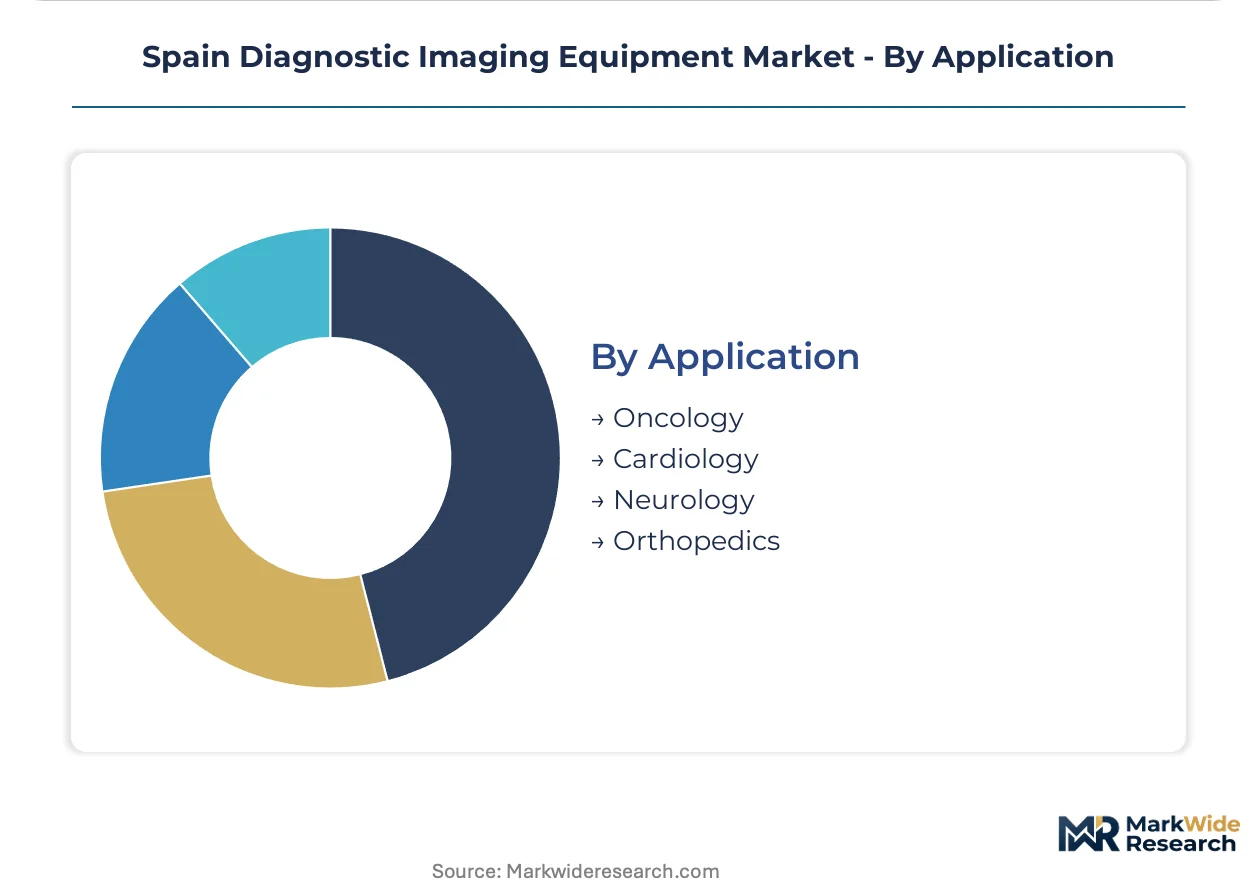
Oncology and cardiology anchor premium modality utilization while orthopedics sustains high-volume X-ray demand.
- Oncology:Tumor staging and treatment response monitoring require multi-modality imaging protocols. PET-CT and MRI systems concentrate in Madrid's specialized cancer centers under regional health service capital plans.
- Cardiology:Coronary angiography and cardiac MRI enable structural and functional assessment. Tertiary cardiovascular institutes in Catalonia deploy CT calcium scoring for preventive screening programs.
- Neurology:Brain parenchyma and vascular imaging demands high-field MRI and perfusion CT. Stroke networks prioritize rapid CT availability for thrombectomy triage decisions.
- Orthopedics:Musculoskeletal trauma and degenerative joint disease drive radiography and MRI utilization. Sports medicine clinics in Barcelona seek compact extremity MRI for outpatient joint assessment.
Oncology commands premium system deployment; cardiology screening programs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical engineering talent clusters in Madrid and Barcelona anchor Spain's diagnostic imaging equipment deployment. Specialized biomedical technicians concentrate in these metropolitan health hubs, supporting high-field MRI and CT maintenance demands. Regional health services leverage this workforce density to operate consolidated procurement frameworks.
Madrid
Tertiary oncology and cardiovascular centers drive capital allocation toward PET-CT and cardiac MRI systems. The Spanish Agency for Medicines and Health Products enforces EU MDR recertification timelines for legacy equipment replacements. Hospital trusts in the Madrid region aggregate multi-site tenders, displacing traditional distributor channels through direct manufacturer negotiations.
Catalonia
Emergency departments prioritize rapid trauma CT capabilities while outpatient networks deploy portable ultrasound for frontline triage. EU recovery fund allocations concentrate capital releases through 2024-2026 procurement windows. Barcelona anchors biomedical research clusters demanding preclinical MRI placements and algorithm development environments.
Andalusia
Primary care networks seek compact digital radiography systems to replace aging analog units. Regional health service budgets channel EU structural funds toward outpatient clinic digitization. Seville and Málaga concentrate diagnostic imaging demand as referral hubs for southern Spain.
Basque Country
Industrial automation expertise supports advanced manufacturing of imaging components and software integration. Regional technology policies incentivize AI-embedded diagnostic algorithm development. Bilbao hosts specialized clinical engineering training programs addressing national technician shortages.
Valencia
Stroke networks prioritize dual-energy CT availability for hemorrhage characterization and thrombectomy triage decisions. Autonomous community procurement frameworks bundle hardware with maintenance service terms. Valencia city anchors capital deployment for rapid diagnostic assessment capabilities across eastern Spain.
Spain Diagnostic Imaging Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's restructuring procurement environment. Siemens Healthineers and GE Healthcare leverage installed base advantages to secure service contract renewals in consolidated hospital tenders. Three archetypes dominate: full-line modality manufacturers, ultrasound-focused portability specialists, and software-embedded AI developers. Strategic moves center on multi-year framework agreements bundling equipment with maintenance, plus AI algorithm integration creating aftermarket revenue layers atop hardware placements.
Among the full-line modality manufacturers, Siemens Healthineers and GE Healthcare exemplify the service-contract-driven competitive model. Esaote SpA occupies a specialist position within the ultrasound portability tier. These three anchors represent distinct strategic postures: German conglomerate breadth, American hospital-system integration, and Italian outpatient-clinic focus. Their positioning reflects the market's bifurcation between high-volume public hospital tenders and decentralized point-of-care expansion.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Carestream Health |
| GE Healthcare |
| Hologic Inc |
| Esaote SpA |
| Siemens Healthineers |
| Canon |
| Shimadzu Corporation |
| Koninklijke Philips |
| Others |
Value Network & Pricing Analysis
Digital detector retrofits across Andalusia and Valencia simultaneously compress per-unit hardware margins and concentrate procurement leverage in consolidated regional health services. EU recovery fund allocations accelerate analog-to-digital transitions while bundling service contracts into multi-year framework agreements.
Pricing Analysis
Bundled service contracts versus unbundled equipment-only sales split Spain's diagnostic imaging market sharply. Three-tier pricing structure across premium, standard, and economy levels reflects magnet field strength and software capability differentiation. Price differentiation stems from EU MDR certification tier and after-sales service integration depth. Cost compression in economy-tier digital radiography intensifies because Chinese manufacturers expand direct distribution. Primary care networks in southern Spain exhibit highest price sensitivity; Madrid's tertiary oncology centers show lowest.
Supply Chain Analysis
EU Medical Device Regulation local-content requirements and notified body capacity constraints reshape sourcing patterns for superconducting magnet assemblies. Niobium-titanium wire supply draws from Japan, China, and the United States. Production rests on helium cryogen logistics, rare-earth magnet materials, and radiofrequency coil manufacturing. Single-source vulnerability concentrates in superconducting wire suppliers outside Europe. Distribution runs through manufacturer-direct regional health service contracts and specialized clinical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's diagnostic imaging market compounds regulatory-driven replacement demand. EU MDR recertification timelines for legacy MRI and CT systems force capital deployment decisions regardless of budget cycles.
For Market Incumbents: Acquire AI-embedded diagnostic software assets to layer aftermarket revenue atop hardware placements. Siemens Healthineers and GE Healthcare should deepen backward integration into superconducting magnet maintenance capabilities. Consolidated tendering frameworks threaten distributor margins; direct hospital trust negotiations preserve pricing power. Certification investment in EU AI Act algorithmic transparency documentation defends against software-enabled entrants.
For New Entrants and Emerging Players: Specialized ultrasound distributors represent the most accessible channel partnership for portable system penetration. Point-of-care deployment in Andalusia and Valencia emergency departments offers white-space expansion outside Madrid-Catalonia concentration. Primary care clinic networks seek compact digital radiography with workflow integration support. AI-assisted image interpretation software creates wedge opportunities atop competitor hardware installed base.
For Investors and Strategic Acquirers: Valuations sit cheapest among clinical engineering service specialists with regional health service contracts. Five-to-ten year viability frames around EU recovery fund allocation exhaustion and subsequent replacement cycle normalization. Acquisition targets should show embedded software recurring revenue and superconducting system maintenance certification. Watch autonomous community budget release timing as capital deployment inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Accelerates replacement cycles for pre-2017 MRI and CT installed base across Spanish hospital networks. |
| Hospital System Partnership | Direct negotiations with Madrid regional health trusts displace traditional distributor intermediaries. |
| Software Companion Development | AI-embedded lesion detection algorithms create aftermarket revenue streams atop hardware placements. |
| CE Marking Pathway | EU AI Act conformity requirements reshape radiology software vendor competitive positioning. |
| Reimbursement Strategy | Autonomous community diagnostic imaging tariff structures influence point-of-care expansion economics. |
Research Methodology
Multiple input streams — hospital procurement committee interviews, biomedical engineer surveys, and regulatory filing analysis — were reconciled against secondary validation. Primary discussions with GPO contracts managers, regional health service capital planners, clinical radiologists, and imaging equipment service technicians informed demand-side dynamics. Secondary sources encompassed Spanish Agency for Medicines and Health Products MDR guidance documents, EU medical device notified body registers, autonomous community budget appropriations, and hospital procurement database extracts. Bottom-up equipment unit forecasts and top-down health expenditure allocations were triangulated for convergence.
Data-stream reconciliation across product type, end user, technology, and application dimensions anchored the analytical framework. Segmentation modeling incorporated magnet field strength tier, care setting acuity level, software integration depth, and regional procurement consolidation status. CAGRs were derived from replacement cycle analysis and EU funding allocation schedules. Forecast inputs included superconducting magnet supply lead times and clinical engineer workforce expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU notified body capacity resolution and autonomous community fiscal autonomy negotiations. Projections reflect assumptions around MDR enforcement consistency and recovery fund disbursement pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market