
 UAE Flexible Office Space Market | 2026-2036
UAE Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Flexible Office Space Market Analytics
Modular furniture systems and demountable partition materials are pivoting traditional fit-out economics toward faster deployment cycles. WeWork sustains its presence through scale advantages in Dubai's prime commercial corridors. Nasab differentiates via boutique design-led spaces targeting creative agencies. IWG (Regus) anchors the premium serviced office tier with extended lease flexibility for corporate relocations.
Flexible office space denotes commercial real estate configured for short-term occupancy with shared amenities, movable partitions, and plug-and-play IT infrastructure enabling rapid tenant turnover. Coworking spaces capture the fastest expansion as entrepreneurs prioritize community access over isolated suites, while serviced offices retain margin depth from corporate clients demanding reception services and dedicated meeting facilities. Technology integration through smart desking and IoT-enabled access control now functions as a baseline hygiene factor rather than a premium differentiator.
MOHAP governs workplace health standards for shared environments, while Dubai's Department of Economic Development enforces commercial licensing frameworks that directly permit flexible workspace operations. Stakeholders must monitor how evolving free zone regulations across Abu Dhabi Global Market and Dubai International Financial Centre reshape tenant eligibility and cross-emirate operational permissions.
Market Dynamics
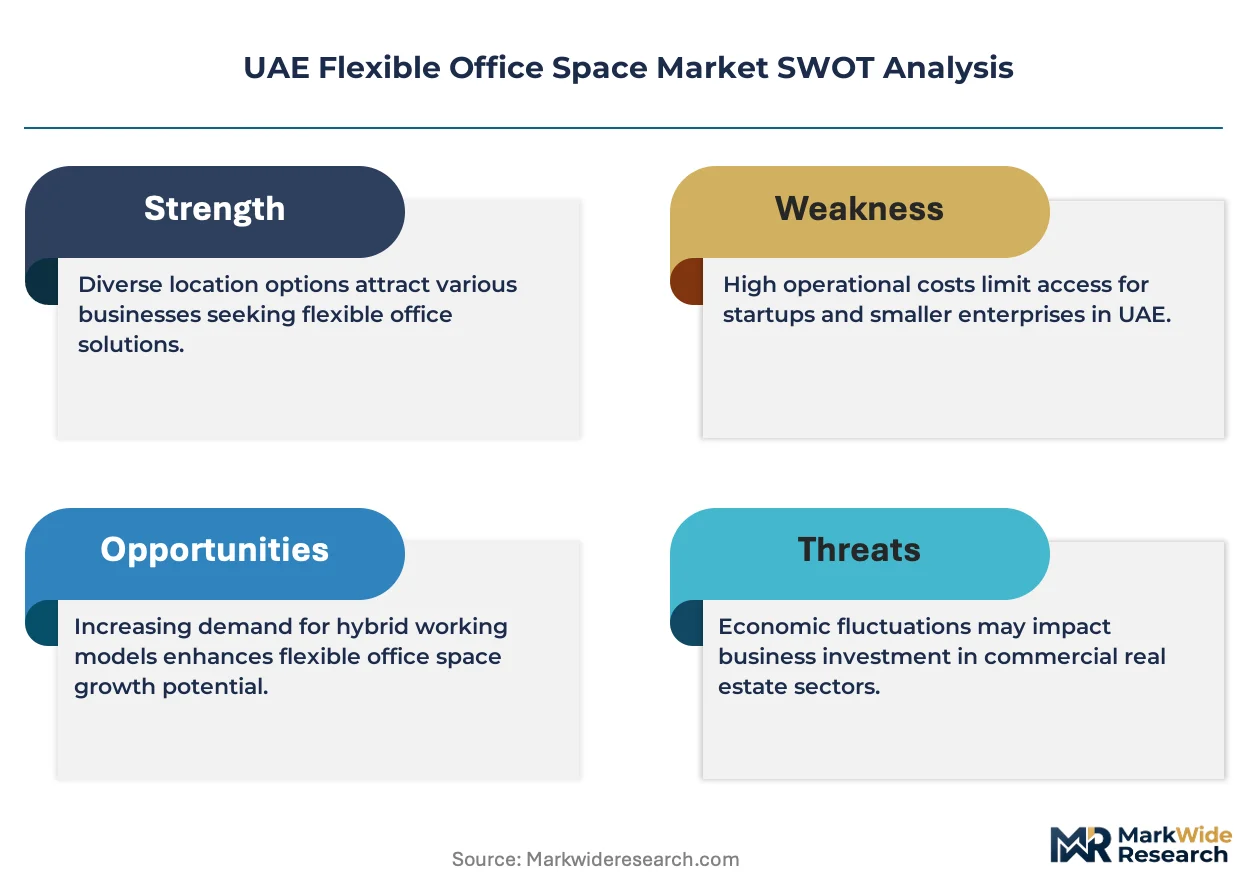
Technology firms and fintech startups are compressing lease cycles across Dubai and Abu Dhabi, forcing operators to deploy modular fit-outs and IoT infrastructure within weeks rather than months to capture venture-backed tenants.
Growth Catalysts
- Hub71 Cluster Policy:Abu Dhabi's government-backed innovation hub attracts venture capital firms seeking turnkey office solutions, creating concentrated demand for premium flexible workspaces.
- Smart Desking Systems:IoT-enabled access control and automated space management reduce operational overhead while enabling real-time occupancy optimization for operators.
- DIFC Licensing Streamlining:Dubai's Department of Economic Development permits shared commercial premises licensing, eliminating regulatory friction for cross-border enterprise setups.
Market Restraints
- Prime Real Estate Concentration:Supply concentrates in Dubai's DIFC and Abu Dhabi's Al Maryah Island, limiting expansion options and inflating base rents for new entrants.
- Demountable Partition Costs:Modular fit-out materials command 40-60% premiums over conventional construction, compressing operator margins during rapid scaling phases.
- Free Zone Eligibility Variability:Divergent tenant qualification rules across Dubai International Financial Centre and Abu Dhabi Global Market fragment operational permissions for multi-location providers.
Strategic Opportunities
- Ras Al Khaimah Expansion:Underpenetrated emirate with emerging gaming and logistics clusters presents first-mover advantage for boutique operators targeting mid-market tenants.
- Corporate Relocation Servicing:Extended lease flexibility and reception services capture enterprise clients downsizing permanent footprints while maintaining regional headquarters presence.
- Community-Driven Coworking:Entrepreneur preference for network access over isolated suites enables premium pricing for curated programming and sector-specific clustering.
Industry Challenges
- Fit-Out Talent Scarcity:Shortage of technicians skilled in rapid-deployment modular systems delays space activation timelines and strains project pipelines.
- Legacy IT Integration:Enterprise tenants demand seamless connection with proprietary security protocols, requiring custom infrastructure builds that erode standardization benefits.
- MOHAP Compliance Complexity:Workplace health standards for shared environments mandate frequent ventilation and density monitoring, adding operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Flexible Office Space Market |
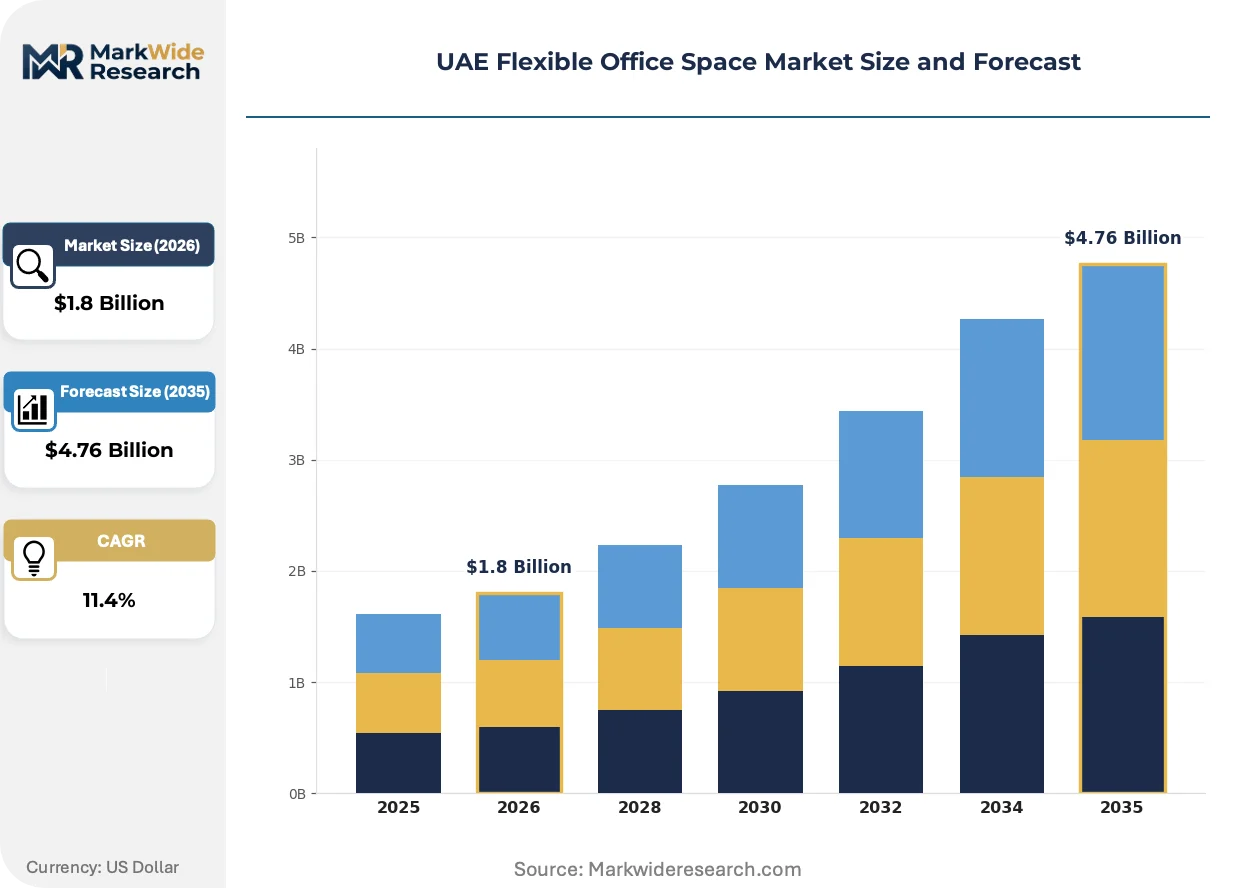
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serviced Offices, Coworking Spaces, Virtual Offices, Meeting Rooms Customer Type: Startups, SMEs, Corporates, Freelancers Service Type: Flexibility Plans, Booking Systems, Membership Packages, Short-term Rentals Technology: Access Control, IoT Integration, Smart Desking, High-speed Internet |
| Companies Covered | Nasab, LetsWork, WeWork, Servcorp, WitWork, IWG (Regus), Nook, The Co-Dubai, Astrolabs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Flexible Office Space Market Evolving Landscape
Flexible workspace operators are weaponizing speed of deployment as a competitive differentiator, compressing traditional fit-out timelines through prefabrication and intelligent building systems.
Smart desking technology is consolidating control over occupancy analytics, climate adjustment, and access management into unified platforms. Fintech and technology tenants now mandate these systems as baseline requirements during site selection. This consolidation is compressing differentiation timelines as operators race to match feature parity.
MOHAP workplace health standards are reshaping density calculations and ventilation specifications for shared commercial environments. Operators must now integrate continuous air quality monitoring and automated occupancy caps into space design. Dubai-based providers are responding fastest, embedding compliance infrastructure during initial construction rather than retrofitting.
Enterprise procurement patterns are fragmenting as corporate real estate teams unbundle long-term leases into portfolio mixes of flexible space, traditional offices, and remote stipends. Technology sector buyers now rotate between operators quarterly based on project team proximity requirements. This fragmentation is most visible in Dubai's DIFC corridor, where switching costs have collapsed and loyalty mechanisms have failed to materialize.
UAE Flexible Office Space Market Segmentation
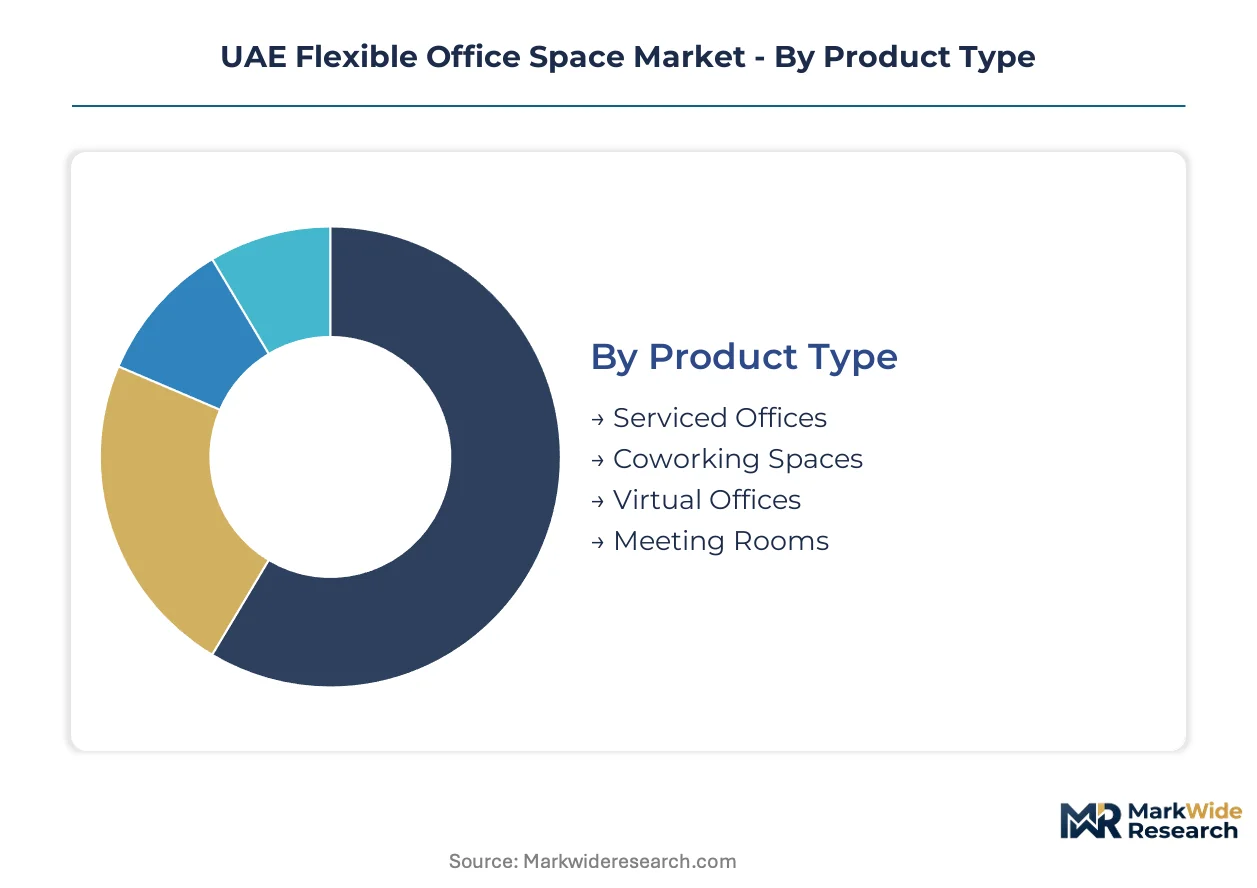
Tenant mobility patterns and compressed lease cycles create divergent performance across product configurations. Operators optimize portfolio mix by matching segment-specific deployment speeds to local demand velocity in Dubai and Abu Dhabi corridors.
Product Type:
Upgrade cycles accelerate as venture-backed tenants rotate between configurations based on funding stage and headcount volatility.
- Serviced Offices:Fully fitted suites with dedicated reception, mail handling, and administrative support. Corporate relocations into Dubai International Financial Centre drive sustained occupancy as enterprises shed permanent footprints while retaining premium addresses.
- Coworking Spaces:Open-plan environments with shared amenities and community programming. Fintech clusters in Abu Dhabi's Hub71 prioritize network proximity over isolation, compressing traditional lease commitments into monthly memberships.
- Virtual Offices:Address registration and call handling without physical occupancy. Freelancers and single-founder entities leverage these for MOHAP-compliant commercial licensing at minimal overhead.
- Meeting Rooms:Bookable conference facilities with AV infrastructure and catering coordination. Project-based teams across Ras Al Khaimah's emerging gaming sector utilize these for client presentations without permanent suite commitments.
Serviced offices sit at the top of the volume ranking, with coworking spaces climbing the fastest.
Customer Type:
Cost tier differentiation separates premium service bundles from stripped-down access packages.
- Corporates:Regional headquarters and project offices demanding extended lease flexibility, dedicated meeting facilities, and seamless IT integration with proprietary security protocols. These clients anchor revenue stability across DIFC and Al Maryah Island.
- Startups:Venture-backed enterprises prioritizing speed-to-occupancy and proximity to investor networks. Hub71's government-backed incentives concentrate these tenants in Abu Dhabi corridors with turnkey activation timelines.
- SMEs:Mid-market firms balancing cost control with professional presence. Dubai's Department of Economic Development licensing streamlining enables rapid setup without legacy bureaucratic friction.
- Freelancers:Individual operators seeking desk access and community affiliation. Nasab and boutique operators capture this tier through design-led environments targeting creative professionals.
Corporates command the premium pricing tier, while startups generate the steepest expansion trajectory.
Service Type:
Application-specific packaging determines margin capture across transient versus sticky tenant relationships.
- Membership Packages:Tiered access models bundling desk time, meeting credits, and event participation. Community-driven programming enables premium pricing in creative agency clusters.
- Short-term Rentals:Daily or weekly occupancy for project teams and visiting executives. Seasonal demand spikes around Dubai's conference calendar create utilization volatility.
- Flexibility Plans:Scalable commitments allowing monthly adjustments to desk count and location. Enterprise procurement teams favor these for distributed workforce management.
- Booking Systems:Digital platforms for real-time space reservation and payment processing. These function as baseline infrastructure rather than differentiation across established operators.
Membership packages dominate recurring revenue, with short-term rentals gaining share fastest.
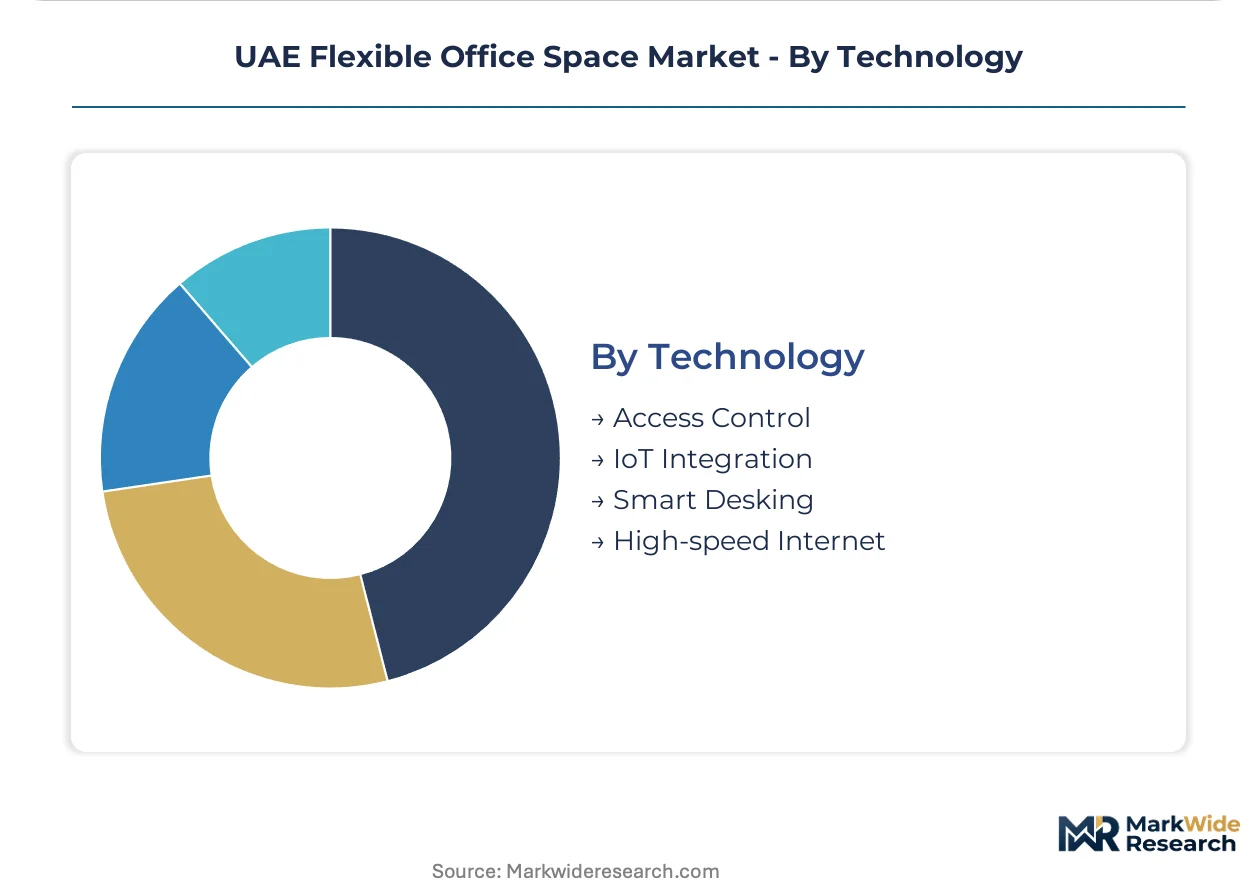
Technology:
Supply concentration in smart infrastructure vendors shapes deployment standardization across operator tiers.
- Smart Desking:IoT-enabled workstations with automated climate adjustment, occupancy sensing, and usage analytics. Fintech tenants mandate these systems as non-negotiable baseline requirements.
- Access Control:Biometric and mobile credential systems managing entry permissions. MOHAP workplace health standards integrate these with automated density monitoring and ventilation triggers.
- High-speed Internet:Dedicated fiber connectivity with redundant failover. Enterprise clients demand SLA-backed performance for cloud-dependent operations.
- IoT Integration:Unified platforms consolidating lighting, HVAC, and security management. Rapid-deployment modular fit-outs embed these during initial construction rather than retrofitting.
Smart desking leads technology investment priority, with IoT integration expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Financial Centre anchors UAE flexible office demand through its concentration of fintech and professional services tenants. The emirate-level regulatory divergence between Dubai and Abu Dhabi shapes operator licensing requirements and cross-border expansion strategies. Sub-regional clusters concentrate supply in government-backed innovation districts with streamlined commercial permitting.
Dubai
DIFC's streamlined licensing from Dubai's Department of Economic Development attracts venture-backed enterprises seeking rapid establishment. MOHAP workplace health standards mandate density controls and ventilation monitoring in shared commercial environments. Downtown Dubai and Business Bay corridors host WeWork and IWG scale operations alongside Nasab's design-led boutique spaces.
Abu Dhabi
Hub71's government-backed innovation cluster policy concentrates startup demand through subsidized activation timelines and investor network proximity. Abu Dhabi Global Market free zone regulations govern tenant eligibility for financial services firms. Al Maryah Island and Masdar City sub-markets attract corporate relocation clients demanding extended lease flexibility.
Sharjah
Cost-sensitive SME demand drives mid-market operator expansion beyond prime Dubai and Abu Dhabi corridors. Sharjah's Department of Economic Development permits shared commercial premises licensing with reduced fee structures. University City and Sharjah Research Technology and Innovation Park clusters serve education and media sector tenants.
Ras Al Khaimah
Emerging gaming and logistics clusters present first-mover positioning for boutique operators targeting underpenetrated demand. Ras Al Khaimah Economic Zone authority streamlines foreign ownership structures for workspace providers. Al Hamra and Mina Al Arab commercial districts lack incumbent flexible space supply.
Northern Emirates
Ajman and Fujairah free zones attract virtual office registrations from freelancers and single-founder entities seeking minimal overhead commercial licensing. Federal MOHAP standards apply uniformly across these emirates without local regulatory variation. Industrial corridor proximity in Fujairah serves project-based teams requiring temporary meeting facilities.
UAE Flexible Office Space Market Competitive Landscape
Global majors compete with regional champions across licensing agility and deployment speed in the UAE flexible office market. Market structure tiers between scale-driven international operators and design-differentiated local boutiques. Three archetypes dominate: premium serviced office providers, community-focused coworking specialists, and hybrid virtual-meeting room aggregators. Consolidation pressures favor portfolio diversification and cross-emirate geographic expansion over single-location depth.
Within the scale-driven tier, WeWork and IWG (Regus) occupy positions exemplifying global network leverage and corporate relocation servicing. Nasab and LetsWork represent the design-differentiated archetype targeting creative agencies through aesthetic programming. Astrolabs anchors the startup-specialist segment with sector-specific clustering around technology mentorship.
| Leading Market Players |
|---|
| Nasab |
| LetsWork |
| WeWork |
| Servcorp |
| WitWork |
| IWG (Regus) |
| Nook |
| The Co-Dubai |
| Astrolabs |
| Others |
Value Network & Pricing Analysis
Premium-to-commodity fit-out tiering separates DIFC's turnkey serviced offices from Sharjah's stripped-down desk rentals, with that divergence compressing margins at the mid-market level while concentrating supplier relationships among Dubai-based modular furniture specialists and Chinese IoT hardware vendors. Input cost pass-through mechanics favor operators with captive installation teams over those reliant on third-party fit-out contractors, as demountable partition premiums and smart desking hardware costs now constitute the largest variable in unit economics.
Pricing Analysis
Input cost pass-through from modular construction materials and IoT infrastructure hardware shapes operator pricing power across the UAE flexible office market. Three-tier pricing structure across premium, standard, and economy levels segments DIFC's corporate relocations from Hub71's startup memberships and Ras Al Khaimah's emerging mid-market demand. Pricing pressure stems from compressed deployment timelines as venture-backed tenants mandate activation within weeks rather than months. Corporates anchored in Al Maryah Island exhibit lowest price sensitivity, while freelancers and single-founder entities in Northern Emirates free zones drive commoditization at the entry tier.
Supply Chain Analysis
Direct-to-operator channels from Dubai-based fit-out specialists and Shenzhen IoT hardware manufacturers handle hyperscale demand from WeWork and IWG portfolio expansions. Geographic supply concentration centers on China's smart desking component ecosystem, Germany's demountable partition engineering, and the UAE's local modular furniture fabrication. Raw material dependencies include aluminum framing systems, acoustic panel composites, and biometric sensor arrays. Single-source vulnerability in IoT firmware licensing creates operational risk for operators standardizing on proprietary platforms. Distribution runs through project-based procurement contracts rather than inventory stocking models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where enterprise procurement teams now mandate MOHAP-compliant ventilation infrastructure and SLA-backed connectivity as baseline specifications, not premium upgrades. That demand shift toward certified operational standards rewards operators who embedded compliance during initial construction.
For Market Incumbents: Deepen vertical control over rapid-deployment fit-out capabilities through captive technician teams, as third-party contractor scarcity delays space activation timelines and strains project pipelines. Anchor DIFC and Al Maryah Island positions against emerging boutique competitors by extending lease flexibility terms beyond standard market offerings. Certification investment in MOHAP workplace health infrastructure functions as a defensive moat as regulatory compliance costs rise. For New Entrants and Emerging Players: Smart building automation platforms offer technology-first positioning against legacy operators relying on retrofit IoT installations. Ras Al Khaimah's underpenetrated gaming and logistics corridors present the most penetrable geography for first-mover boutique formats. Go-to-market execution should target mid-market SME demand through Sharjah's streamlined licensing framework, avoiding direct confrontation with scale-driven incumbents in prime Dubai corridors. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented local operators lack capital to match smart infrastructure investment requirements demanded by enterprise tenants. Long-term viability favors portfolio diversification across multiple emirates rather than single-location depth, given tenant rotation patterns and collapsed switching costs. Acquisition target archetype: design-differentiated boutiques with established community programming and cross-emirate operational permissions. The signal to watch is MOHAP regulatory tightening that raises compliance capital requirements and accelerates operator attrition.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Infrastructure Integration | IoT-enabled space management satisfies fintech tenant baseline requirements across DIFC and Hub71 corridors. |
| Modular Fit-Out Capability Buildout | Prefabricated deployment systems compress activation timelines to capture venture-backed startup demand. |
| Cross-Emirate Geographic Expansion | Ras Al Khaimah and Sharjah licensing frameworks enable portfolio diversification beyond saturated prime markets. |
| MOHAP Compliance Certification Program | Workplace health infrastructure investment differentiates operators as regulatory standards tighten. |
| Enterprise Servicing Partnership | Extended lease flexibility and dedicated reception services capture corporate relocation demand in Al Maryah Island. |
Research Methodology
Bottom-up tenant segmentation modeling reconciled against top-down operator capacity tracking forms the analytical core of this study. Primary interviews with flexible workspace operators, commercial real estate brokers, venture capital investors, and MOHAP regulatory officials combined with secondary validation from Dubai Department of Economic Development licensing records, free zone authority filings, and customs data on modular furniture imports. Triangulation across supply-side facility counts and demand-side occupancy patterns anchored volume estimates.
Historical trendline analysis of fit-out deployment timelines and lease cycle compression informed projection assumptions across the modeling period. Segmentation dimensions modeled include product configuration, customer archetype, service bundling tier, and technology integration level. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points and capital cycle timing. Industry-specific forecast inputs incorporated Hub71 subsidy policy durability and DIFC licensing streamlining momentum.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to free zone regulatory divergence and MOHAP standard evolution. Forecasts reflect documented assumptions regarding venture capital deployment cycles and enterprise real estate unbundling trends. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
United States Office Real Estate Market