
 United Kingdom Flexible Office Space Market | 2026-2036
United Kingdom Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Flexible Office Space Market Analytics
Cloud-based workspace management platforms and IoT-enabled building systems are fragmenting how flexible office providers configure and monetize real estate assets. Workspace Group leverages proprietary technology to optimize space utilization across its London-centric portfolio. Bruntwood Works anchors its competitive position through deep Manchester and Birmingham presences with integrated amenity programming. International Workplace Group sustains global operational standards while competing aggressively on corporate account penetration in UK tier-one cities.
Flexible office space encompasses commercially operated work environments offering short-term, scalable occupancy arrangements without traditional long-lease commitments, typically featuring shared infrastructure, reception services, and digital connectivity with service-level agreements for bandwidth and uptime. Serviced offices dominate transaction volume due to established corporate procurement pathways and predictable cost structures, while coworking spaces capture the fastest expansion as hybrid work policies normalize distributed team coordination. Private offices within coworking and serviced formats concentrate margin pools, whereas hot desks and virtual offices serve price-sensitive freelancers and remote workers with lower operational overhead.
UK planning authorities enforce the Use Classes Order and permitted development rights that determine whether commercial buildings qualify for flexible workspace conversion, while the Building Safety Regulator mandates fire and structural standards for multi-tenant occupancies. ESG reporting through the UK Sustainability Disclosure Standards pressures landlords to disclose energy performance and embodied carbon data, directly affecting refurbishment financing and tenant selection criteria. Stakeholders must monitor how local authority spatial strategies and tightening operational carbon targets reshape viable supply locations and retrofit economics.
Market Dynamics
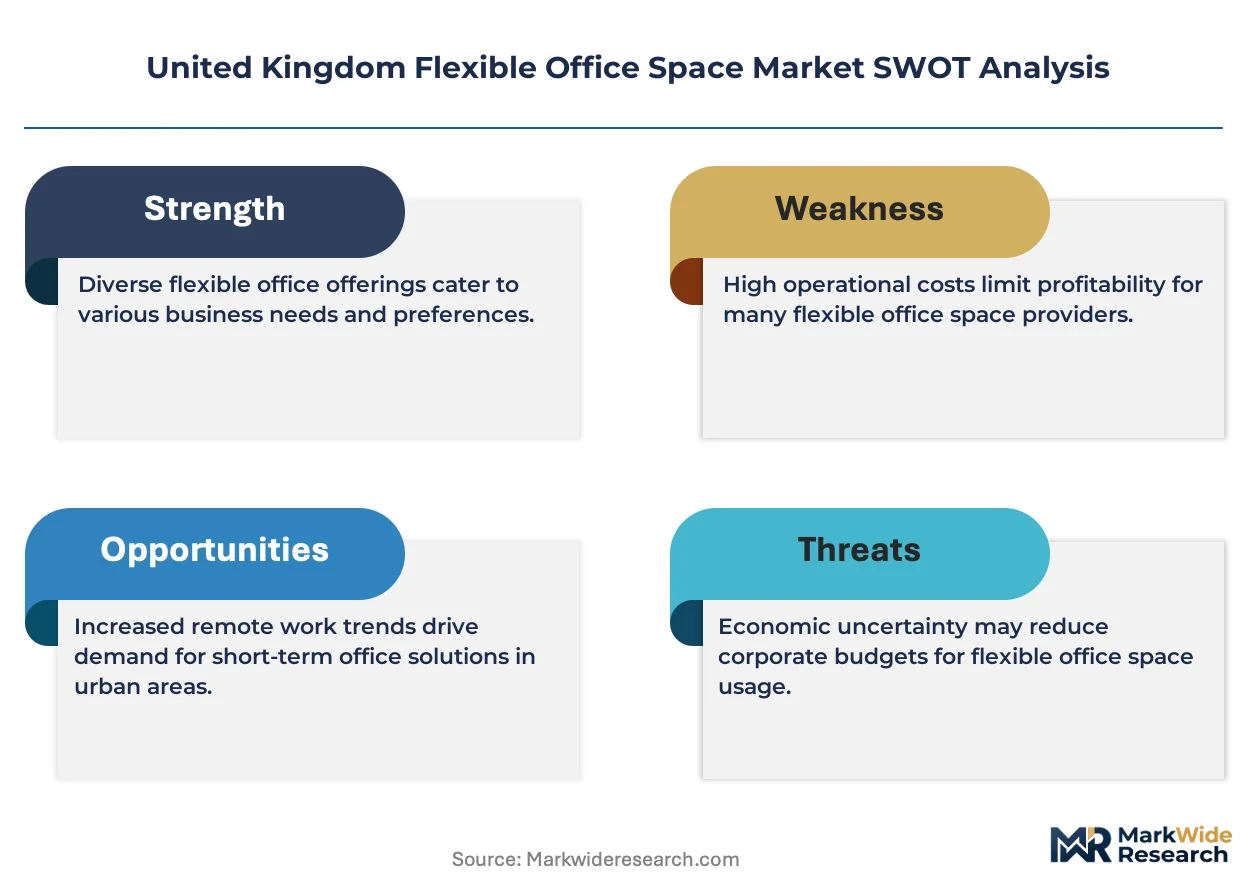
Hybrid work normalization is fragmenting corporate real estate demand across the United Kingdom, forcing landlords to reconfigure lease structures and accelerate amenity investments to retain tenant loyalty.
Growth Catalysts
- SME Professional Services Expansion:Accounting, legal, and consulting firms are downsizing traditional leases in favor of serviced offices with embedded reception and IT support.
- Town and Country Planning (Use Classes) Order Reforms:Permitted development rights for commercial-to-flexible conversions are unlocking dormant office stock in secondary locations.
- IoT-Enabled Building Systems:Sensor networks optimizing space utilization and energy consumption are lowering operational costs for multi-tenant operators.
Market Restraints
- Interest Rate Sensitivity:Refurbishment financing costs for older building stock have risen substantially, compressing developer margins on retrofit projects.
- London Supply Concentration:Overdependence on the capital's transaction volume exposes operators to localized demand shocks and rental volatility.
- Embodied Carbon Disclosure Requirements:UK Sustainability Disclosure Standards mandate granular carbon accounting that many legacy assets cannot satisfy without costly audits.
Strategic Opportunities
- Regional City Tiers:Manchester, Birmingham, and Edinburgh present undersupplied flexible workspace markets with lower competitive density than London.
- ESG-Certified Refurbishment:BREEAM and WELL certification pathways are attracting corporate tenants with net-zero commitments and premium budget allocations.
- Workspace-as-a-Service Platforms:Subscription-based models bundling physical space with virtual collaboration tools are capturing distributed enterprise teams.
Industry Challenges
- Building Safety Regulator Compliance:Fire and structural standards for multi-tenant occupancies require specialized remediation expertise that contractors struggle to source.
- Legacy Lease Integration:Hybrid contracts blending traditional tenancies with flexible terms create accounting complexity and tenant dispute risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Flexible Office Space Market |
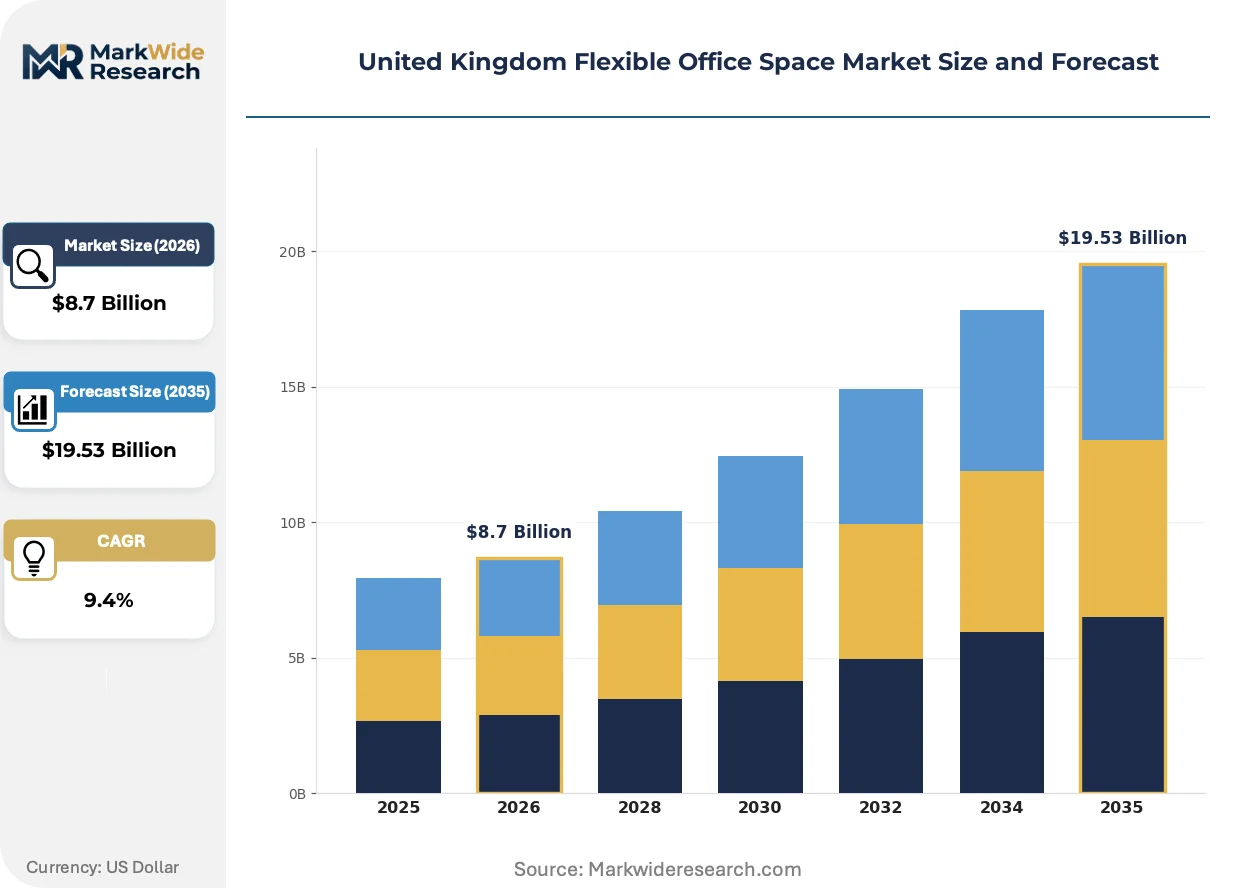
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serviced Offices, Coworking Spaces, Virtual Offices, Executive Suites End User: SMEs, Startups, Freelancers, Corporations Service Type: Membership Plans, Dedicated Desks, Private Offices, Hot Desks Distribution Channel: Online Platforms, Brokers, Direct Sales, Partnerships |
| Companies Covered | Workspace Group, Bruntwood Works, International Workplace Group, Huckletree, Landmark Space, WeWork, BizSpace, Fora, The Office Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Flexible Office Space Market Evolving Landscape
Technology convergence and regulatory pressure are compressing traditional property management cycles, forcing operators to embed digital infrastructure and sustainability credentials into core offerings.
Cloud-based workspace management platforms are digitizing how landlords configure real-time occupancy, dynamic pricing, and tenant services across distributed portfolios. Mid-market operators in Manchester and Birmingham are adopting these systems fastest to compete with London-centric incumbents. The technology is digitizing asset monetization by enabling granular space utilization data that feeds into investor reporting and refinancing negotiations.
The UK Sustainability Disclosure Standards are mandating operational carbon and embodied carbon disclosure for commercial real estate holdings above specific thresholds. Landlords must now commission whole-life carbon assessments before refinancing or divestment, directly affecting refurbishment project viability. Prime London assets are responding fastest through BREEAM Excellent retrofits, while secondary stock faces stranded asset risk.
Corporate procurement teams are unbundling real estate decisions from centralized facilities management, empowering regional business units to source flexible space directly. This fragmentation is displacing traditional broker relationships with platform-based booking systems and direct operator contracts. The shift is most visible among technology firms scaling engineering hubs in East London and South Bank corridors without headquarters approval cycles.
United Kingdom Flexible Office Space Market Segmentation
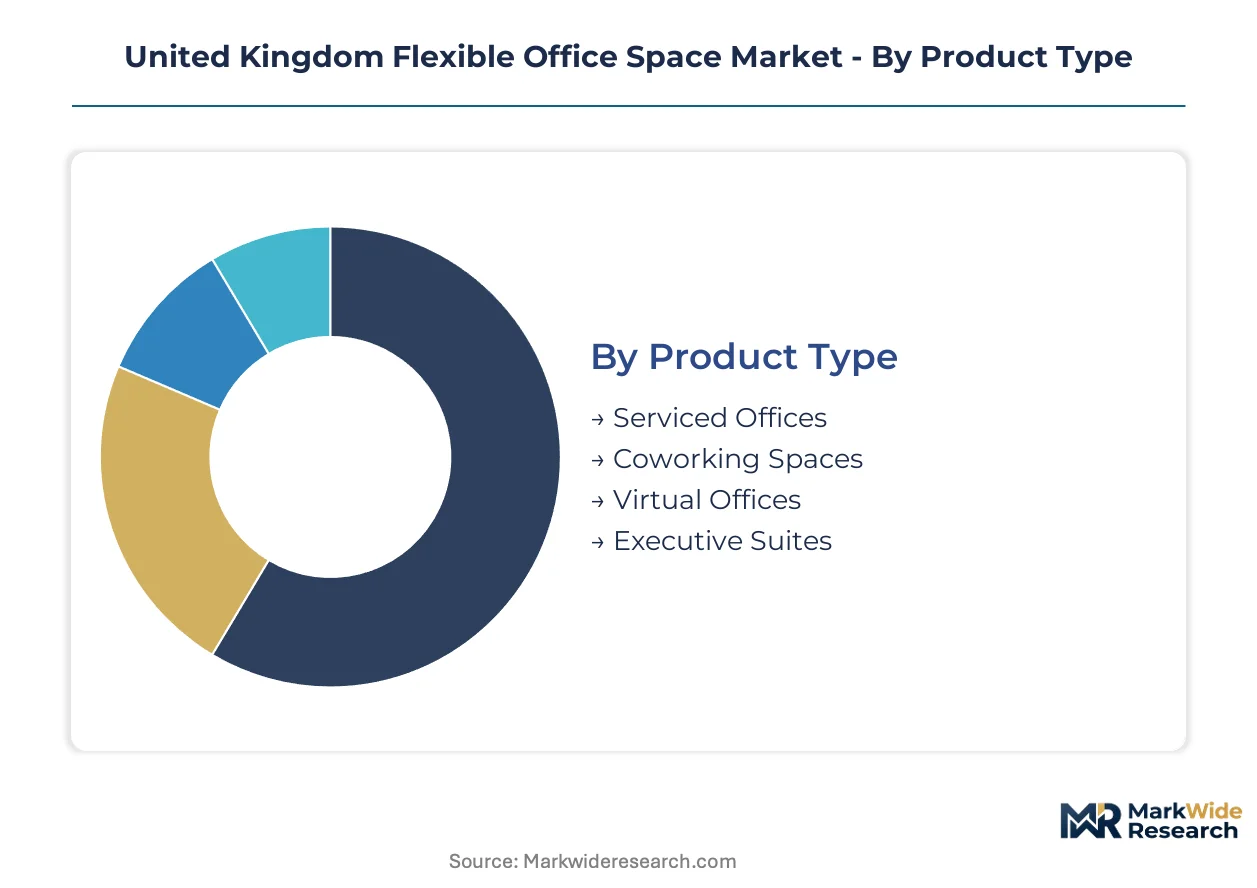
Flexible office space operators must align portfolio configuration with distinct occupancy patterns across product formats and customer segments. Segmentation reveals where contract velocity, margin structure, and capital intensity diverge most sharply.
Product Type:
Cycle times vary dramatically across physical formats, with daily-turnover hot desks refreshing inventory fastest and multi-year serviced office leases locking capital longest.
- Serviced Offices:Fully fitted private suites with embedded reception, IT infrastructure, and facilities management. Corporate legal and accounting firms in London's Square Mile and Canary Wharf favor these for predictable cost structures and brand separation from coworking environments.
- Coworking Spaces:Open-plan environments with shared amenities and community programming. Technology firms and creative agencies cluster in Manchester's Northern Quarter and Birmingham's Digbeth, drawn by networking density and month-to-month scalability.
- Virtual Offices:Mailing addresses and telephone answering without physical occupancy. Freelancers and remote-first SMEs use these for registered business presence in premium postcodes at minimal overhead.
- Executive Suites:Premium private offices with concierge services and boardroom access. Financial services boutiques in Edinburgh's financial district select these for client-facing prestige.
Serviced offices anchor the volume base while coworking spaces gain share at the steepest rate.
End User:
Customer scale determines procurement complexity, with enterprise accounts demanding bespoke service level agreements and individual users transacting through self-serve platforms.
- SMEs:Professional services firms with 10-100 employees seeking cost predictability. Regional clusters in Leeds and Bristol favor flexible terms to accommodate headcount volatility without lease liability.
- Startups:Venture-backed technology companies prioritizing network effects and investor proximity. East London corridors from Shoreditch to Stratford concentrate this demand.
- Freelancers:Independent consultants and creative professionals with intermittent space needs. Price sensitivity drives concentration in secondary city fringe locations.
- Corporations:Established enterprises deploying satellite teams or project-based workforces. These accounts negotiate enterprise pricing and dedicated floor plates.
SMEs generate the steadiest occupancy base while startups expand and contract most dramatically.
Service Type:
Commitment depth shapes revenue predictability, with annual private office contracts delivering cash flow stability and drop-in hot desks creating demand volatility.
- Membership Plans:Bundled access combining physical space with virtual services and event programming. Hybrid-remote teams in Cambridge and Oxford science parks value the flexibility.
- Dedicated Desks:Permanently assigned workstations within shared environments. Small professional practices favor these for territorial security without private office cost.
- Private Offices:Enclosed suites for teams requiring confidentiality and brand control. Law firms and consultancies in Manchester's Spinningfields specify these exclusively.
- Hot Desks:Unassigned seating available on demand. Transient workers and visiting executives absorb excess capacity during off-peak hours.
Private offices command margin leadership while hot desks maximize space utilization efficiency.
Distribution Channel:
Channel selection reflects customer sophistication, with enterprise procurement teams engaging directly and smaller users discovering space through platform algorithms.
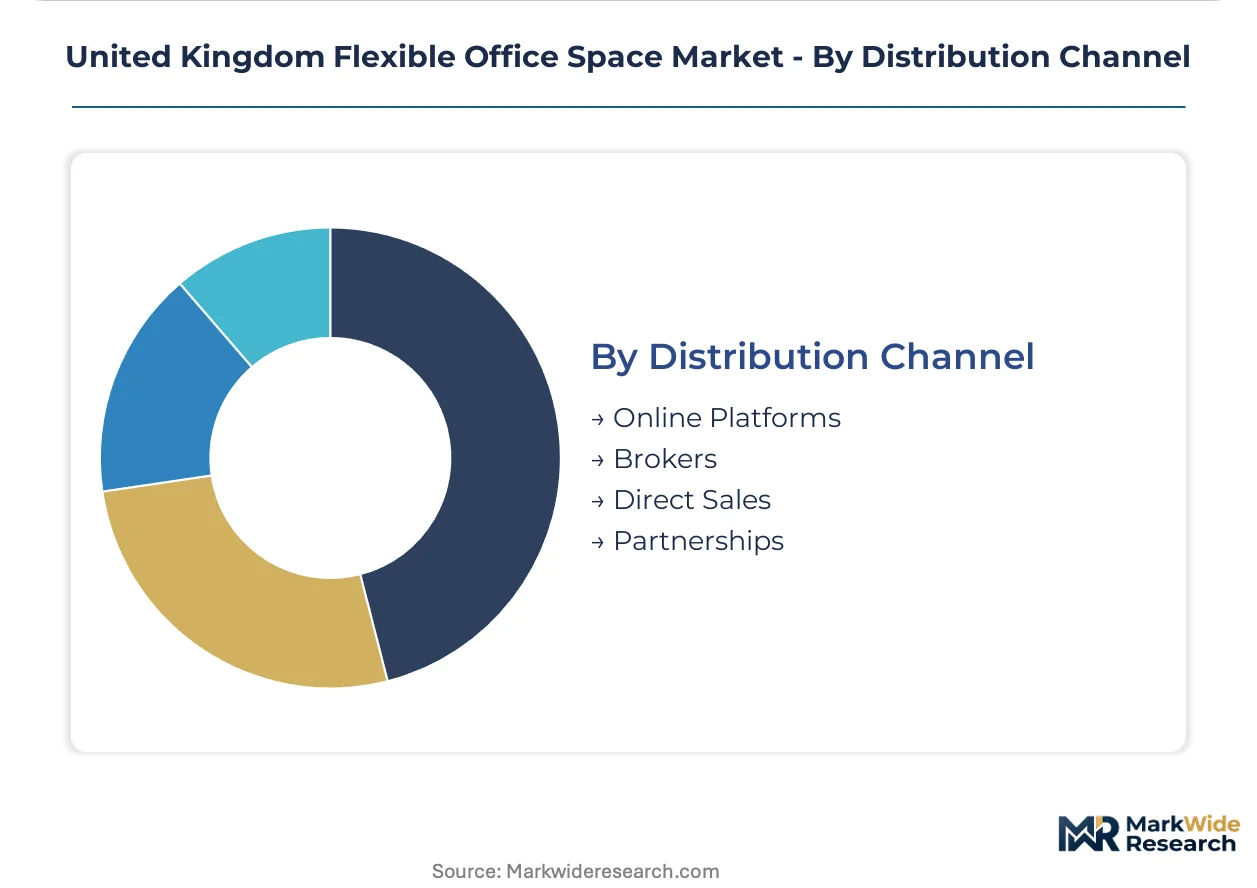
- Online Platforms:Digital marketplaces enabling real-time availability search and instant booking. Independent freelancers and startup founders in Brighton and Glasgow use these for transparency and speed.
- Brokers:Intermediaries negotiating terms for corporate relocations and portfolio expansions. These relationships dominate transactions above 50 desks.
- Direct Sales:Operator-led account management for enterprise relationships. Major providers maintain field teams targeting FTSE 250 real estate directors.
- Partnerships:Embedded distribution through commercial property landlords, business accelerators, and professional services firms. University enterprise hubs in Sheffield and Nottingham channel graduate ventures toward affiliated workspace.
Direct sales capture the highest-value contracts while online platforms scale fastest in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom exports flexible workspace expertise and operational models to Ireland, the Netherlands, and the Nordics, where UK-based operators license management platforms and design standards to local partners seeking proven hybrid-work infrastructure.
London and the Southeast
Technology firms and professional services SMEs drive absorption across South Bank and East London tech corridors. The Town and Country Planning (Use Classes) Order reforms accelerate commercial-to-flexible conversions in Canary Wharf and Shoreditch. Landlords retrofit 1980s office stock into serviced offices near Liverpool Street and Stratford to capture corporate satellite demand.
Midlands
Professional services firms and logistics headquarters seek cost arbitrage against London rents. Birmingham's permitted development rights unlock dormant industrial buildings in Digbeth for coworking conversion. Operators cluster near HS2 interchange zones to intercept corporate relocations from the capital.
North England
Media agencies and fintech startups expand Manchester operations for talent access and lower occupancy costs. The Greater Manchester Combined Authority spatial strategy designates creative industry quarters in the Northern Quarter and Spinningfields. Bruntwood Works anchors supply through integrated amenity programming across the city centre.
Scotland
Asset management boutiques and renewable energy consultancies populate Edinburgh's financial district. Scottish Government planning guidance prioritizes town centre regeneration through flexible workspace activation. Operators target Leith and Glasgow's Merchant City for secondary location premiums.
Wales and Northern Ireland
Public sector contractors and remote-first SMEs absorb capacity in Cardiff and Belfast. Welsh Government property procurement frameworks now mandate flexible tenure options for departmental satellite offices. Limited supply concentration creates pricing power for early entrants in these peripheral markets.
United Kingdom Flexible Office Space Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct operational models. London-centric portfolio operators compete with regional specialists and global platform providers for corporate account penetration. Strategic archetypes include technology-integrated landlords, amenity-heavy regional developers, and scale-driven international franchisors. Dominant competitive moves involve portfolio acquisitions in secondary cities and proprietary platform licensing to asset-light partners.
Within the London-centric tier, Workspace Group and The Office Group exemplify technology-integrated landlords optimizing space utilization through proprietary systems. Bruntwood Works anchors the regional specialist archetype through deep Manchester and Birmingham presences. International Workplace Group occupies the scale-driven franchisor position, sustaining global operational standards while competing aggressively on corporate account penetration.
| Leading Market Players |
|---|
| Workspace Group |
| Bruntwood Works |
| International Workplace Group |
| Huckletree |
| Landmark Space |
| WeWork |
| BizSpace |
| Fora |
| The Office Group |
| Others |
Value Network & Pricing Analysis
Interest rate sensitivity in refurbishment financing compresses developer margins and determines both the spread between premium and economy workspace tiers and the geographic shape of supply chain investment. Capital costs for retrofitting 1980s office stock in secondary locations feed directly into pricing structures, while supply chain partners concentrate on regions where permitted development rights unlock conversion economics fastest.
Pricing Analysis
Prior-generation serviced office contracts with fixed five-year terms now trade at discounts against current-generation hybrid-ready formats with embedded IoT infrastructure and month-to-month scalability. Pricing stratifies across premium BREEAM-certified assets, standard refurbished stock, and economy conversions of dormant industrial buildings in peripheral zones. Cost compression in the standard tier intensifies because regional operators in Manchester and Birmingham compete aggressively on rate to displace London-centric incumbents. Freelancers and remote-first SMEs exhibit the highest price sensitivity, while financial services boutiques in Edinburgh's financial district absorb premium executive suite rates without volume negotiation.
Supply Chain Analysis
Tariff exposure between the United Kingdom and EU member states dominates supply chain risk for imported building materials and IoT sensor hardware deployed in workspace retrofits. Manufacturing concentration for smart building systems rests on Germany, the Netherlands, and China, while fit-out contractors and specialized fire remediation expertise source predominantly from domestic UK markets. Single-source vulnerability concentrates in cloud-based workspace management platforms licensed from US-based software providers. Distribution runs through direct operator procurement for enterprise-grade installations and platform-mediated spot purchasing for smaller regional projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid work normalization represents an early-cycle expansion story for UK flexible workspace, with corporate procurement decentralization accelerating penetration beyond traditional headquarters-centric models.
For Market Incumbents: Harden portfolio resilience through BREEAM Excellent certification investment and proprietary technology platform development to defend against asset-light competitors licensing management systems to regional entrants. Vertical integration into in-house refurbishment capabilities reduces exposure to contractor scarcity and Building Safety Regulator compliance bottlenecks. For New Entrants and Emerging Players: Pursue white-space opportunity in Cardiff, Belfast, and Edinburgh's Leith corridor where limited supply concentration grants pricing power to early entrants. Target public sector contractors and remote-first SMEs through Welsh Government procurement frameworks and Scottish spatial strategy alignment. Go-to-market traction accelerates through university enterprise hub partnerships channeling graduate ventures toward affiliated workspace. For Investors and Strategic Acquirers: UK Sustainability Disclosure Standards implementation reshapes the acquisition landscape by stranding legacy assets without whole-life carbon assessments and elevating ESG-certified refurbishment pipelines. Long-term viability centers on operators with technology-integrated landlord capabilities and regional density in Manchester, Birmingham, or Edinburgh. Monitor corporate account procurement decentralization as the inflection signal—when FTSE 250 real estate directors cede sourcing authority to regional business units, platform-based booking penetration accelerates and traditional broker relationships fragment.| Strategic Initiative | Industry Significance |
|---|---|
| ESG-Certified Refurbishment Pipeline | BREEAM and WELL certification attracts corporate tenants with net-zero commitments and premium budget allocations. |
| Proprietary Platform Licensing | Technology-integrated landlords monetize management systems through asset-light partnerships in secondary cities. |
| Regional City Expansion | Undersupplied Manchester, Birmingham, and Edinburgh markets offer lower competitive density than London corridors. |
| Hybrid Contract Development | Blended traditional-flexible lease structures capture corporate satellite demand without headquarters approval cycles. |
| University Partnership Embedding | Enterprise hub affiliations channel graduate ventures and create captive demand pipelines in Sheffield and Nottingham. |
Research Methodology
A spread of perspectives from flexible workspace operators, corporate real estate directors, facilities procurement managers, and planning authority officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with portfolio strategists at London-centric and regional specialist firms alongside secondary validation through UK planning authority spatial strategy documents, Building Safety Regulator guidance publications, and corporate sustainability disclosure filings. Bottom-up lease transaction analysis triangulated against top-down investment flow data from commercial real estate financing databases.
Demand-supply-balance dynamics across the analysis window shaped the analytical framework, with segmentation modeled across product format, end-user scale, service commitment depth, and distribution channel sophistication. CAGRs derived from historical absorption velocity, refurbishment pipeline visibility, and corporate procurement pattern shifts. Industry-specific forecast inputs incorporated Town and Country Planning Use Classes Order reform implementation timelines and UK Sustainability Disclosure Standards compliance thresholds for operational carbon disclosure.
Sensitivities concentrate around interest rate trajectory effects on refurbishment financing viability, localized demand shocks from corporate headquarters consolidation decisions, and Building Safety Regulator enforcement intensity on legacy multi-tenant assets. Forecasts reflect assumptions regarding hybrid work policy durability and ESG certification adoption curves among corporate tenants. Macroeconomic deviation, regulatory enforcement acceleration, or technological displacement of physical workspace requirements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Flexible Office Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market