
 Japan Office Real Estate Market | 2026-2036
Japan Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Office Real Estate Market Foresight
Buyer concentration across Japan's office landscape is broadening as technology startups and regional financial institutions fragment demand alongside traditional corporate anchors. Mitsubishi Estate Co., Ltd. leverages its Marunouchi district dominance to sustain premium lease rates through integrated retail and transit connectivity. Mitsui Fudosan Co., Ltd. anchors its portfolio in mixed-use developments that blend office, residential, and cultural facilities. Sumitomo Realty & Development Co., Ltd. competes through specialized logistics-adjacent office complexes near major transport corridors.
Japan office real estate comprises commercial structures designed for administrative, professional, and service-sector operations, typically featuring reinforced concrete or steel-frame construction with floor loading capacities of 300-500 kg per square meter and integrated building management systems for energy and security control. Grade A properties command the deepest tenant loyalty pools due to seismic resilience certifications and transit proximity, while co-working spaces represent the fastest-growing property type as hybrid work policies normalize. Corporations and SMEs diverge sharply in lease structure preferences, with the former gravitating toward long-term pre-lease commitments in new high-rise towers and the latter driving flexible-term volume in mid-rise composite buildings.
METI's energy efficiency mandates and the Building Energy Efficiency Act shape development specifications, compelling developers to exceed baseline insulation and HVAC performance thresholds before securing construction permits. JIS standards for seismic design and fire safety, administered by the Ministry of Land, Infrastructure, Transport and Tourism, constrain structural options while elevating compliance costs for mid-tier projects. Stakeholders must monitor how evolving municipal zoning in Tokyo, Osaka, and Fukuoka reallocates floor-area ratios between office and residential uses.
Market Dynamics
Hybrid work stabilization is fragmenting tenant demand across Japan's office corridors, forcing landlords to differentiate through seismic resilience certifications and transit-integrated amenities rather than location alone.
Growth Catalysts
- Building Energy Efficiency Act:METI's mandates are accelerating retrofit investments in existing stock as developers pursue net-zero carbon pathways to secure construction permits and premium lease rates.
- Technology firm expansion:Domestic and international software companies are pre-leasing entire floors in Tokyo's central wards, creating sustained absorption in Grade A towers despite broader economic headwinds.
- Osaka-Fukuoka corridor:Corporate relocations to secondary cities are diversifying demand geography and reducing tenant concentration risk for portfolio managers seeking yield outside the capital.
Market Restraints
- Construction input volatility:Reinforced concrete and structural steel pricing fluctuations are compressing development margins on mid-rise projects outside prime Tokyo submarkets.
- Zoning fragmentation:Municipal governments in Osaka and Fukuoka are reallocating floor-area ratios toward residential uses, constraining office supply expansion in emerging corporate destinations.
- Seismic retrofit costs:JIS certification upgrades for aging 1980s and 1990s stock require capital expenditures that exceed rental recovery timelines for Class B assets.
Strategic Opportunities
- Co-working space conversion:Underutilized mid-rise buildings in Tokyo's peripheral wards present repositioning potential as flexible-term operators capture SME demand for hybrid-compatible footprints.
- Integrated transit development:Railway operators and developers are unlocking air rights above major stations, creating captive tenant pipelines through direct platform connectivity.
- Energy performance contracting:METI subsidy frameworks for building efficiency retrofits are enabling third-party financing models that reduce landlord capex burdens while accelerating compliance timelines.
Industry Challenges
- Specialized asset management talent:Shortages of professionals fluent in both JIS seismic standards and green building certification systems are delaying repositioning project execution.
- Legacy system integration:Building management system upgrades for energy and security control require interoperability with 1990s-era infrastructure, extending tenant improvement timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Office Real Estate Market |
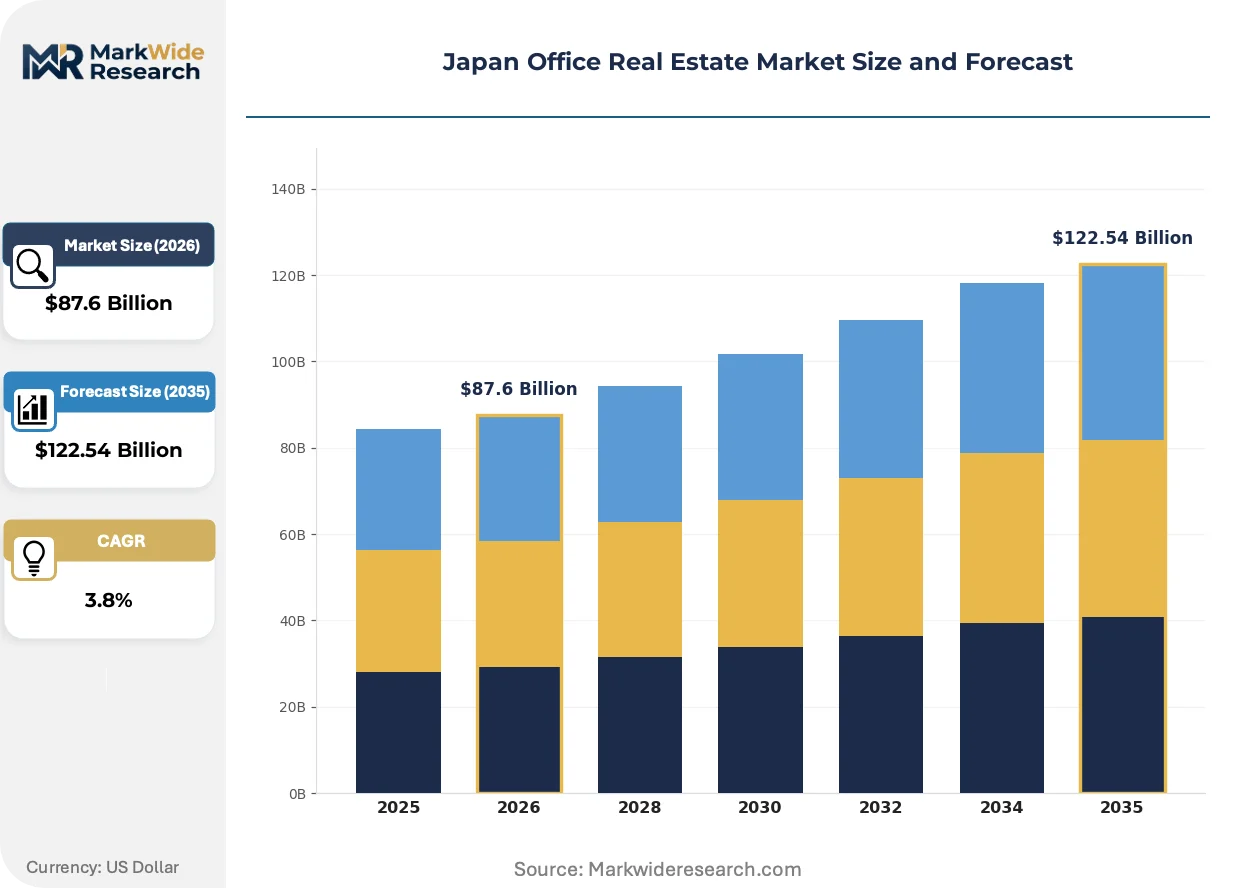
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $122.54 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Grade A, Grade B, Co-Working Spaces, Serviced Offices Client Type: Startups, SMEs, Corporations, Government Entities Lease Type: Short-Term, Long-Term, Flexible Terms, Pre-Lease Building Class: High-Rise, Mid-Rise, Low-Rise, Composite Types |
| Companies Covered | Mitsubishi Estate Co., Ltd., Mitsui Fudosan Co., Ltd., Sumitomo Realty & Development Co., Ltd., Tokyu Land Corporation, Nomura Real Estate Holdings, Inc., Daiwa House Industry Co., Ltd., Hulic Co., Ltd., Mori Building Co., Ltd., ORIX Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Office Real Estate Market Shifts & Advancements
Digital infrastructure and regulatory pressure are converging to redefine how office space is delivered, operated, and consumed across Japan's major metropolitan areas.
Prefabricated building envelope systems are modularizing facade and core construction for mid-rise office developments. Regional contractors in Osaka and Nagoya are adopting factory-assembled curtain wall units to compress on-site installation schedules. This approach is modularizing project delivery timelines and reducing skilled labor dependencies that constrain traditional build methods.
METI's progressive tightening of insulation and HVAC performance thresholds under the Building Energy Efficiency Act is mandating heat recovery ventilation and high-performance glazing in all new construction. Developers must exceed baseline specifications to secure occupancy permits, elevating mechanical system costs. Tokyo's central ward projects are most affected, with design teams specifying variable refrigerant flow systems and dedicated outdoor air units to meet compliance.
Tenant organizations are unbundling traditional lease structures to separate base rent from amenity access and service provision. Corporations are negotiating core-shell agreements while procuring workplace management, wellness programming, and digital infrastructure through specialized operators. This pattern is most pronounced among technology sector tenants in Shibuya and Roppongi submarkets, where hybrid work policies demand flexible space reconfiguration rights.
Japan Office Real Estate Market Segmentation
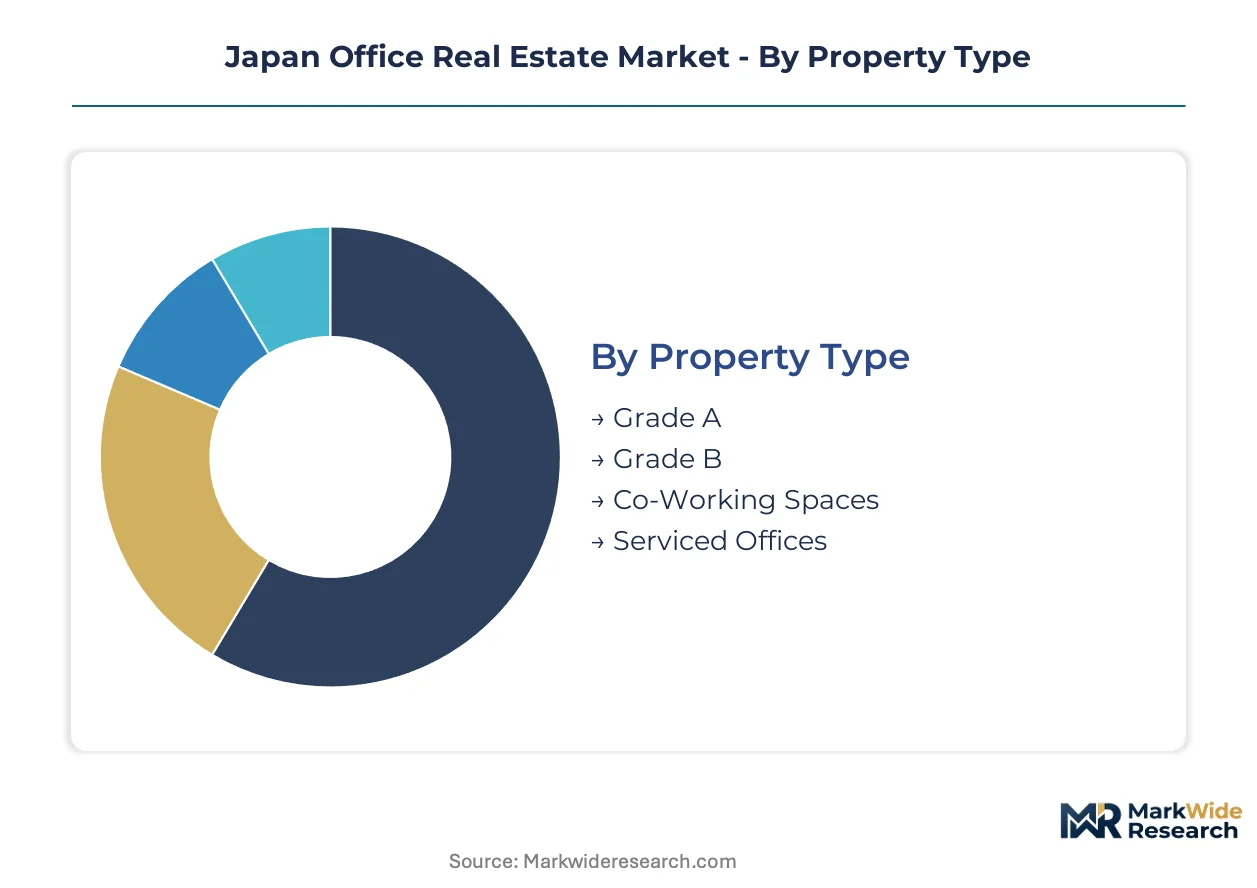
Japan's office market fragments across property grades, tenant profiles, and lease structures that reflect divergent capital commitments and operational flexibility needs. Understanding these divisions reveals where METI efficiency mandates and hybrid work policies concentrate pressure on landlord repositioning strategies.
Property Type:
Upgrade cycles vary dramatically across property tiers as seismic retrofit deadlines and energy performance thresholds force capital deployment decisions at different vintages.
- Grade A:Premium towers in Tokyo's Marunouchi and Roppongi districts feature reinforced concrete cores with base-isolation systems and floor loading of 500 kg per square meter. METI's tightening energy standards are accelerating HVAC replacement cycles in 1990s-vintage stock as landlords pursue net-zero pathways to defend rent premiums.
- Co-Working Spaces:Flexible-term operators are capturing fragmented SME demand across Shibuya and Osaka's Umeda corridor, converting underutilized mid-rise inventory into hybrid-compatible footprints with shorter capital recovery timelines than traditional leases.
- Grade B:Peripheral ward buildings from the 1980s face compressed yields as seismic certification upgrades exceed rental recovery potential.
- Serviced Offices:Fully fitted suites near major stations cater to project-based corporate teams requiring immediate occupancy without tenant improvement delays.
Grade A sits at the top of the volume ranking, with Co-Working Spaces climbing the fastest.
Client Type:
Cost tier differentiation separates tenants by balance sheet capacity and lease commitment horizons, driving landlord portfolio specialization.
- Corporations:Multinational technology firms and financial institutions pre-lease entire floors in new high-rise towers, negotiating core-shell agreements with 10-15 year terms and built-in expansion rights. Their capital reserves absorb premium rents for transit-integrated locations with JIS seismic certifications.
- SMEs:Regional professional services firms and technology startups drive flexible-term volume in mid-rise composite buildings, prioritizing shorter lease commitments and shared amenity access over proprietary infrastructure investment.
- Startups:Venture-backed software companies cluster in co-working nodes near Shibuya and Fukuoka's Tenjin district, scaling footprint quarterly rather than annually.
- Government Entities:Prefectural and municipal administrative offices occupy purpose-built facilities with standardized security and accessibility specifications.
Corporations command the deepest lease commitments by value, though Startups are expanding most quickly in square-meter terms.
Lease Type:
Volume concentration in long-term instruments is eroding as hybrid work policies normalize space reconfiguration rights and shorter commitment horizons.
- Long-Term:Traditional 5-10 year leases with fixed escalation clauses dominate Grade A absorption in Tokyo's central wards, providing landlords with financing collateral and predictable revenue streams for development underwriting.
- Flexible Terms:Month-to-month or annual agreements with bundled service provision are capturing technology sector demand in Shibuya and Roppongi, where workplace management and digital infrastructure are unbundled from base rent.
- Short-Term:Project-based corporates and consulting firms utilize 6-18 month commitments for satellite offices and team overflow capacity.
- Pre-Lease:Forward commitments during construction secure anchor tenancy for new high-rise developments, reducing developer lease-up risk and enabling construction financing.
Long-Term leases retain the largest share of contracted value, with Flexible Terms gaining share fastest among new transactions.
Building Class:
Margin structures diverge sharply by vertical scale as high-rise construction costs and mid-rise conversion economics reshape development pipelines.
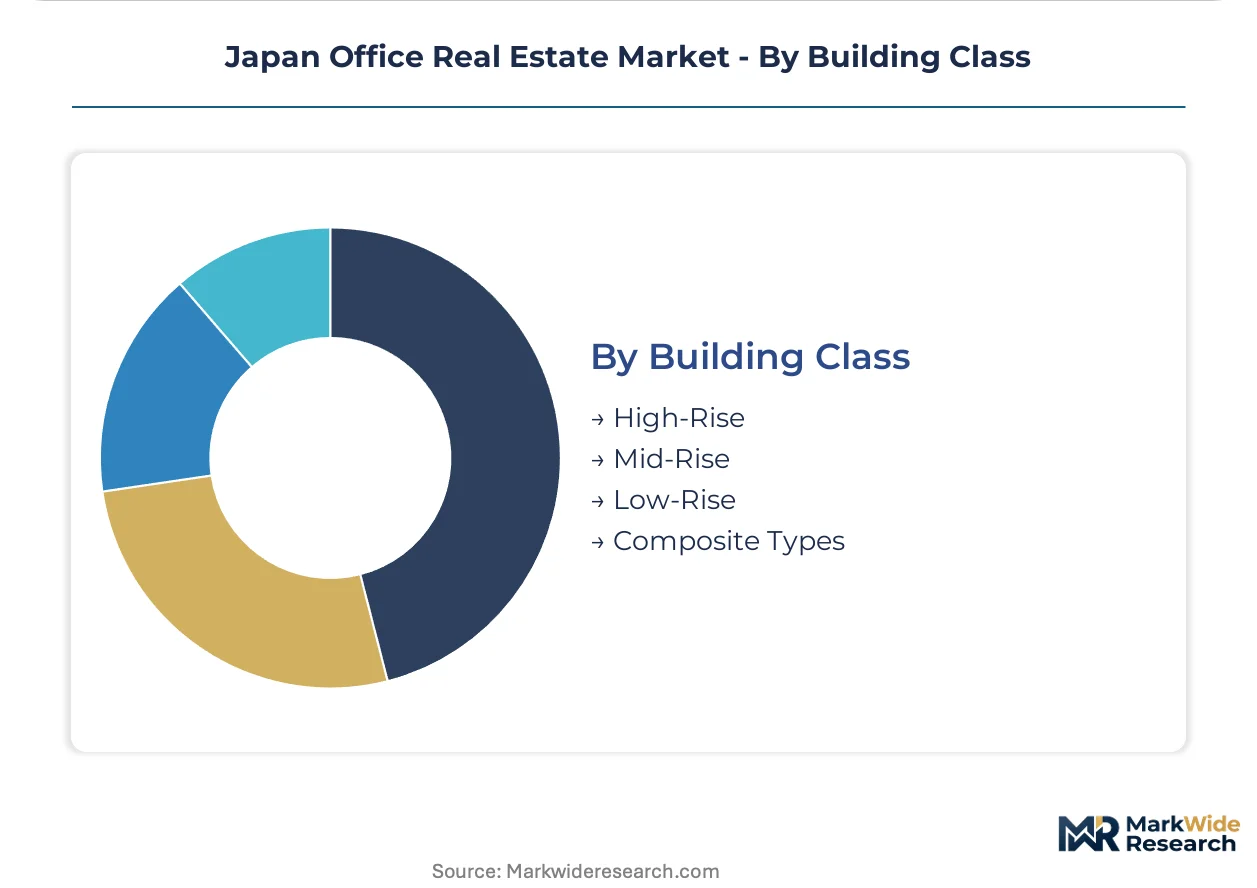
- High-Rise:Steel-frame towers exceeding 20 stories concentrate in Tokyo's Minato and Chiyoda wards, commanding premium rents through seismic resilience certifications and direct platform connectivity to JR and subway lines. Construction input volatility compresses margins on speculative developments outside established submarkets.
- Mid-Rise:5-12 story reinforced concrete structures in Osaka's Nakanoshima and Fukuoka's Hakata districts present repositioning potential as co-working conversions, with lower capital barriers to energy retrofit compliance than high-rise alternatives.
- Low-Rise:Suburban office parks and detached corporate facilities accommodate back-office functions with lower land cost burdens than central ward alternatives.
- Composite Types:Mixed-use developments integrating office, retail, and residential components leverage railway operator air rights above major stations.
High-Rise captures the steepest rent premiums per square meter, while Mid-Rise shows the fastest expansion in transaction volume as secondary cities attract corporate relocations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Grade A office absorption in Frankfurt and Munich contrasts with Japan's Tokyo-centric concentration, where secondary cities command smaller transaction volumes despite similar hybrid work adoption rates.
Kanto/Tokyo
Technology firms and financial services groups are expanding footprints in Minato and Chiyoda wards as hybrid work models stabilize. METI's building energy efficiency standards compel developers to exceed baseline HVAC and insulation thresholds before securing construction permits. Marunouchi and Roppongi districts concentrate premium Grade A towers with base-isolation systems and direct JR line connectivity.
Kansai/Osaka
Corporate relocations from Tokyo are diversifying demand geography across Nakanoshima and Umeda corridors. Municipal zoning reallocations toward residential uses are constraining office supply expansion in emerging corporate destinations. Umeda district hosts repositioned mid-rise inventory as co-working conversions capture SME demand for flexible-term commitments.
Chubu/Nagoya
Automotive and industrial equipment headquarters sustain stable absorption in reinforced concrete structures near Nagoya Station. JIS seismic design standards administered by the Ministry of Land, Infrastructure, Transport and Tourism elevate compliance costs for mid-tier development projects. Sakae submarket attracts regional financial institutions seeking lower rent burdens than Tokyo alternatives.
Kyushu
Technology startups and venture-backed software companies are clustering in Fukuoka's Tenjin district with quarterly footprint scaling rather than annual lease commitments. Prefectural incentive programs for corporate relocations reduce establishment costs for Tokyo-based firms expanding westward. Hakata district presents mid-rise repositioning potential with lower capital barriers to energy retrofit compliance than high-rise alternatives.
Hokkaido
Back-office functions and call center operations occupy low-rise suburban facilities with reduced land cost burdens. Sapporo municipal planning emphasizes mixed-use development integration rather than pure office zone expansion. Susukino corridor maintains limited Grade B inventory serving regional corporate administrative needs.
Japan Office Real Estate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's office development landscape, creating a tiered structure where integrated railway operators and standalone developers pursue distinct tenant capture strategies. Large-scale players leverage air rights above major stations to generate captive demand pipelines, while mid-cap specialists concentrate on peripheral ward repositioning. Two strategic archetypes dominate: transit-integrated mixed-use developers and flexible-term workspace operators. Competitive intensity manifests through portfolio diversification into residential and retail components, plus selective M&A to secure development land positions.
Among Japan-based developers, Mitsubishi Estate Co., Ltd., Mitsui Fudosan Co., Ltd., and Sumitomo Realty & Development Co., Ltd. represent the established integrated conglomerate tier, occupying positions defined by decades-long district dominance and balance sheet capacity for large-scale mixed-use projects. These entities exemplify the transit-connected development archetype through holdings concentrated around Tokyo's major railway nodes. Mori Building Co., Ltd. and Hulic Co., Ltd. sit within the specialized urban regeneration segment, anchoring premium tower development in specific Tokyo submarkets. Tokyu Land Corporation represents railway operator-affiliated development, leveraging captive transit infrastructure to secure tenant pipelines. ORIX Corporation and Daiwa House Industry Co., Ltd. exemplify diversified industrial conglomerates with real estate arms, while Nomura Real Estate Holdings, Inc. occupies a position bridging financial services and property development.
| Leading Market Players |
|---|
| Mitsubishi Estate Co., Ltd. |
| Mitsui Fudosan Co., Ltd. |
| Sumitomo Realty & Development Co., Ltd. |
| Tokyu Land Corporation |
| Nomura Real Estate Holdings, Inc. |
| Daiwa House Industry Co., Ltd. |
| Hulic Co., Ltd. |
| Mori Building Co., Ltd. |
| ORIX Corporation |
| Others |
Supply & Pricing Matrix
Technology firm pre-leasing commitments for entire floors in Tokyo's central wards are compressing development timelines and elevating structural steel and reinforced concrete procurement costs. Developers must absorb these input pressures while maintaining rent premiums that justify METI-mandated energy efficiency upgrades.
Pricing Analysis
Capacity additions in Osaka and Fukuoka are reshaping price floors for Grade B assets as secondary cities attract corporate relocations from Tokyo. Three-tier pricing structure across premium, standard, and economy levels separates base-isolation certified towers from mid-rise composite buildings and peripheral ward conversions. Cost compression in mid-rise construction is intensifying because municipal zoning reallocations constrain developable supply. SMEs exhibit highest price sensitivity, while multinational technology firms absorb premiums for transit-integrated Grade A towers with JIS seismic certifications.
Supply Chain Analysis
Structural steel supply rests on Japanese integrated mills and selected Korean and Chinese specialty producers. Reinforced concrete draws from domestic limestone quarries and imported fly ash additives. Single-source vulnerability concentrates in seismic isolation bearing systems manufactured by a limited tier of certified domestic suppliers. Distribution runs through general contractors with captive relationships to major developers and railway operator-affiliated construction entities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's office real estate functions as a stable compounder anchored by METI's progressive energy efficiency mandates that perpetuate capital deployment into compliant stock. Hybrid work stabilization sustains absorption even as tenant preferences fragment.
For Market Incumbents: Extend district dominance through air rights acquisitions above JR and private railway stations, creating captive tenant pipelines. Deepen vertical integration into energy performance contracting to capture METI subsidy flows and reduce retrofit capex burdens. Defend against flexible-term operators by embedding workplace management services into base rent structures. For New Entrants and Emerging Players: Launch via co-working conversions of underutilized mid-rise inventory in Tokyo's peripheral wards and Osaka's Nakanoshima corridor. Target SME demand for hybrid-compatible footprints with quarterly scaling rights rather than annual commitments. Penetrate through specialized logistics-adjacent office complexes near major transport corridors where incumbents maintain weaker positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with railway operator-affiliated developers leveraging captive transit infrastructure. Long-term viability centers on assets with clear net-zero carbon pathways and platform connectivity. Watch municipal zoning reallocation announcements in Fukuoka and Osaka as inflection indicators for supply-constrained submarkets.| Strategic Initiative | Industry Significance |
|---|---|
| Air Rights Development | Railway operators unlock captive tenant demand through direct platform connectivity. |
| Energy Retrofit Partnership | Third-party financing models accelerate METI compliance while reducing landlord capex. |
| Co-Working Conversion | Flexible-term operators capture fragmented SME demand in peripheral ward mid-rise stock. |
| Seismic Certification Upgrade | JIS base-isolation systems defend rent premiums in Tokyo's Marunouchi and Roppongi districts. |
| Mixed-Use Integration | Developers blend office, residential, and retail components to diversify revenue streams. |
Research Methodology
Direct dialogue with development executives, asset managers at institutional investors, municipal planning officers in Tokyo and Osaka, and construction procurement leads grounded the qualitative foundation. Secondary validation drew from Ministry of Land, Infrastructure, Transport and Tourism permit filings, METI energy efficiency compliance databases, and railway operator air rights disclosure statements. Bottom-up project pipeline tracking and top-down macroeconomic absorption modeling enabled triangulation across data sources.
Market size outputs and segment-level projections across the analysis window reflect econometric modeling of construction cost indices, lease transaction velocity, and regulatory compliance timelines. Segmentation dimensions span property grade, tenant type, lease structure, and building class. CAGRs were derived from trend extrapolation of absorption rates against supply pipeline constraints, with specific inputs including technology sector footprint expansion patterns and municipal zoning amendment frequencies.
Several conditions sit outside the modeled scope, including abrupt shifts in monetary policy affecting construction financing costs, major seismic events altering retrofit prioritization, and unforeseen regulatory accelerations of net-zero carbon deadlines. Forecasts reflect documented assumptions about hybrid work stabilization and METI enforcement consistency. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
Global Office Space Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Office Real Estate Market