
 Australia Co-Working Office Spaces Market | 2026-2036
Australia Co-Working Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Co-Working Office Spaces Market Outlook
Property leasing channels in Australian commercial real estate is tilting toward flexible, short-term arrangements as landlords recalibrate exposure to traditional ten-year contracts. WeWork Management LLC leverages its international platform to secure premium CBD locations across Sydney and Brisbane. Hub Australia sustains a differentiated position through curated community programming and sector-specific floors targeting climate-tech founders. JustCo anchors its growth in Melbourne's suburban corridors, competing on price against incumbent office towers with lower fit-out costs and faster occupancy timelines.
Australia co-working office spaces comprise serviced work environments offering furnished desks, private suites, meeting facilities, and digital infrastructure on flexible contractual terms, typically provisioned through membership subscriptions rather than conventional leases. These spaces integrate high-speed connectivity, ergonomic furnishings, and shared amenities to support knowledge workers, creative professionals, and distributed corporate teams requiring adaptable real estate without capital-intensive fit-outs. Private offices command premium pricing and longer commitments from scaling startups, while shared desks attract solo practitioners and early-stage founders seeking network effects without fixed overhead. Meeting rooms and event spaces generate ancillary revenue streams with higher margins, particularly from enterprises booking project-based collaboration sessions. Virtual offices within the service-type taxonomy represent the fastest-expanding margin pool, enabling remote companies to register commercial addresses and access mail handling without physical occupancy.
The Australian Securities and Investments Commission governs disclosure requirements for co-working operators structuring membership agreements as financial products, while the Australian Competition and Consumer Commission monitors unfair contract terms in standard-form subscriptions. Building codes administered by state-based regulators mandate fire safety, accessibility, and ventilation standards that shape fit-out costs and location feasibility for new entrants. Workplace health and safety frameworks under Safe Work Australia impose duty-of-care obligations on operators managing high-density, shared environments. Stakeholders must track how evolving tenancy law reforms in Victoria and New South Wales reclassify membership arrangements as retail or commercial leases, with material implications for termination rights and bond requirements.
Market Dynamics
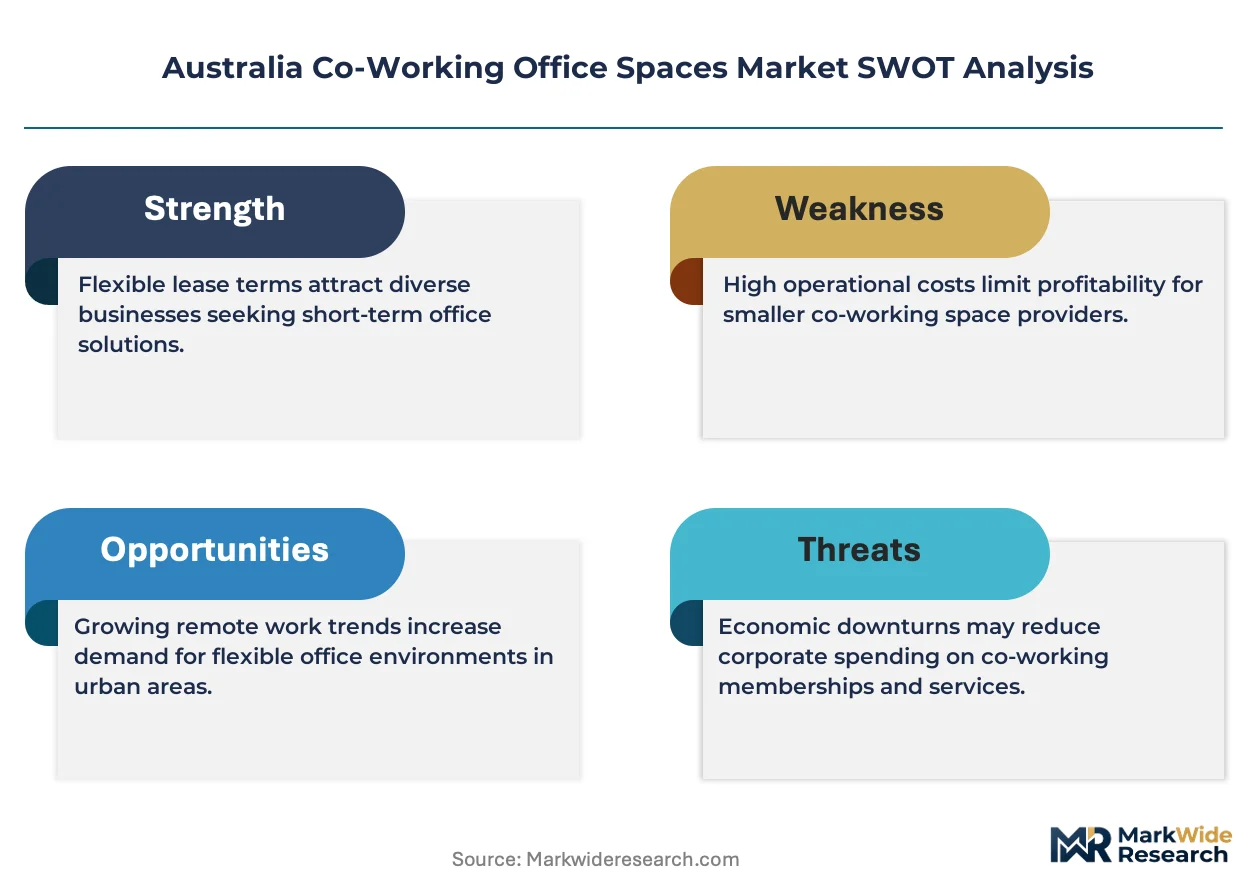
Australian landlords are dismantling traditional ten-year lease templates as venture-backed startups in Sydney and Melbourne demand month-to-month flexibility with embedded expansion options.
Growth Catalysts
- Instant Asset Write-Off:The Australian Taxation Office's accelerated depreciation scheme incentivizes small businesses to classify co-working memberships as deductible operational expenditures rather than capital commitments.
- Venture Capital Density:Melbourne's inner-northern corridor and Sydney's Tech Central precinct concentrate climate-tech and fintech founders requiring proximity to investor networks without fixed real estate overhead.
- Cloud-Native Infrastructure:Distributed authentication systems and software-defined networking enable operators to provision enterprise-grade security across multi-tenant environments without dedicated IT staff per location.
Market Restraints
- Construction Input Volatility:Timber and steel price fluctuations inflate fit-out costs for new entrants targeting premium CBD positions, compressing payback periods below operator hurdle rates.
- Landlord Concentration:Three institutional property trusts control 60% of Sydney CBD commercial stock, extracting revenue-sharing clauses that erode operator margins during occupancy troughs.
- Substitution Threat:Enterprise software vendors including Microsoft and Slack are bundling virtual collaboration tools that replicate serendipitous networking without physical proximity.
Strategic Opportunities
- Suburban Penetration:Brisbane's middle-ring council districts and Perth's Fremantle corridor remain underserved by branded operators, presenting first-mover advantages in car-dependent knowledge-worker catchments.
- Climate-Tech Clustering:Victoria's renewable energy certificate trading infrastructure and federal green bond programs attract founders seeking sector-specific facilities with shared laboratory prototyping equipment.
- Channel Convergence:Hotel loyalty programs and airline status tiers are integrating co-working day passes as redemption options, accessing corporate travel budgets previously excluded from workspace procurement.
Industry Challenges
- Building Code Fragmentation:State-based fire safety and ventilation standards create compliance complexity for operators scaling across New South Wales, Victoria, and Queensland jurisdictions.
- Legacy Lease Reclassification Risk:Proposed tenancy law reforms in Victoria threaten to recategorize membership agreements as retail leases, triggering bond requirements and termination notice periods that undermine flexibility value propositions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Co-Working Office Spaces Market |
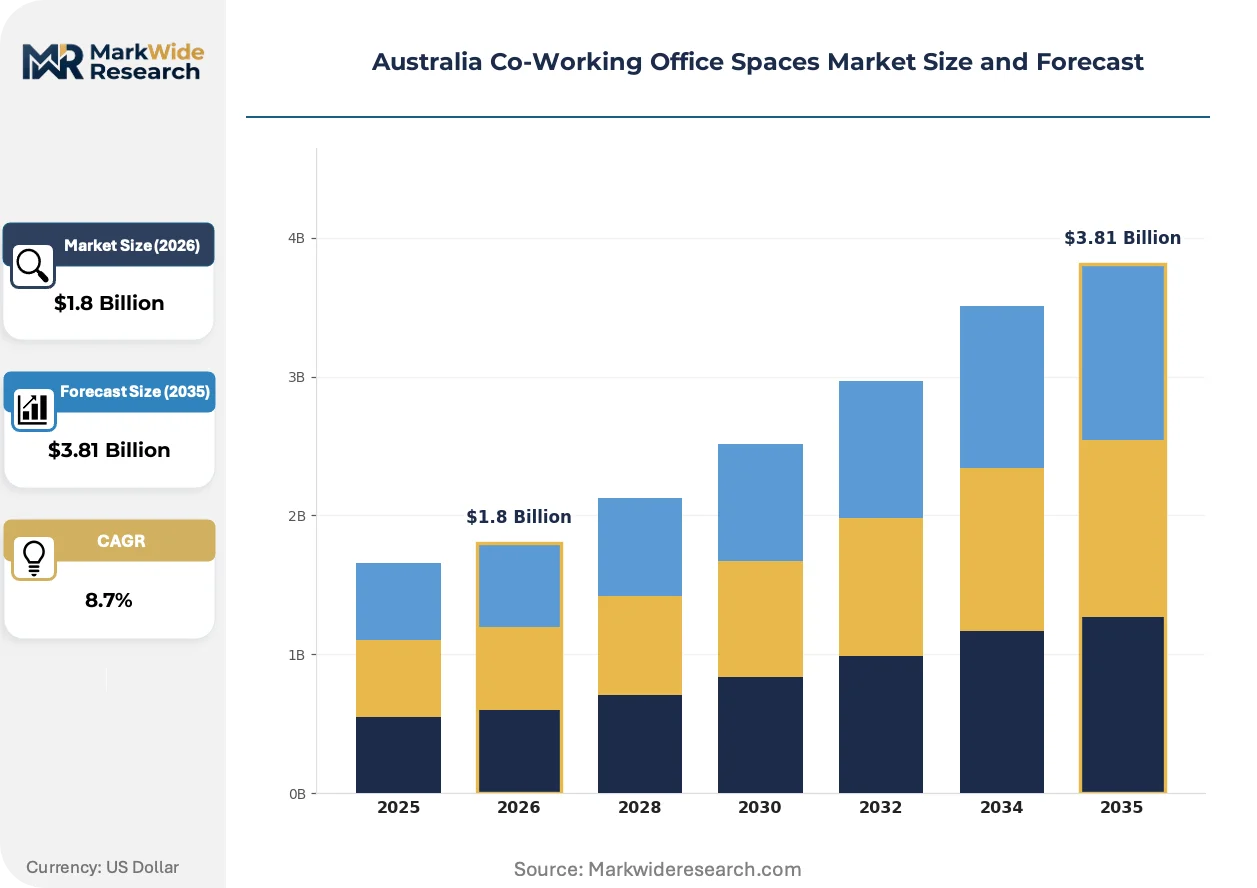
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Private Offices, Shared Desks, Meeting Rooms, Event Spaces End User: Freelancers, Startups, Enterprises, Remote Companies Service Type: Membership Plans, On-Demand Services, Dedicated Desks, Virtual Offices Pricing Model: Hourly Rates, Monthly Subscriptions, Annual Contracts, Pay-as-You-Go |
| Companies Covered | Spaces, JustCo, Hub Australia, Stone & Chalk, CreativeCubes.Co, WOTSO Limited, Servcorp, York Butter Factory, WeWork Management LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Co-Working Office Spaces Market Strategic Shifts
Workspace technology stacks are compressing the distinction between physical and virtual presence, forcing operators to reconceptualize membership value around data-driven community curation rather than square-meterage allocation.
Biometric access control paired with occupancy analytics is collapsing the traditional front-desk staffing model across Australian co-working networks. Operators including Hub Australia deploy computer-vision systems to monitor desk utilization and automatically adjust climate settings. This automation reduces fixed labor costs by 40% while generating granular data on member behavior patterns that inform dynamic pricing algorithms.
Safe Work Australia's updated psychological health regulations are mandating explicit duty-of-care protocols for high-density shared environments. Operators must now document noise exposure limits, air quality monitoring, and conflict mediation procedures to maintain compliance. Premium CBD locations in Sydney face the steepest adaptation costs as older buildings require ventilation retrofits to meet refreshed standards.
Enterprise procurement teams are unbundling long-term headquarters commitments into distributed satellite arrangements. ASX-listed corporations now maintain core presence in traditional towers while licensing flexible seats for project teams in suburban co-working nodes. This pattern is most pronounced among financial services firms establishing regulatory technology development pods in Melbourne's Docklands precinct.
Australia Co-Working Office Spaces Market Segmentation
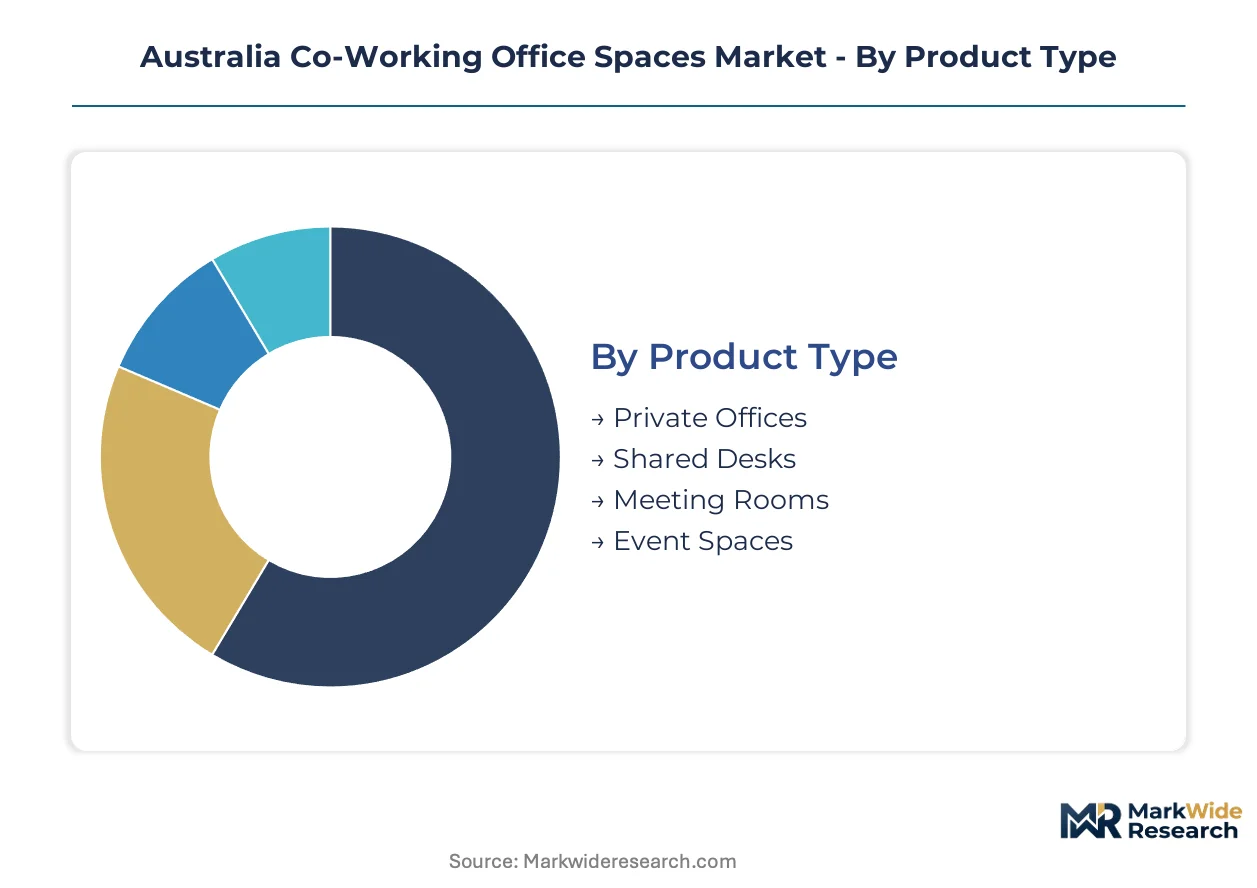
Segmentation in the Australian co-working market reveals how operators balance fixed-cost recovery against variable demand patterns across membership tiers. Each dimension exposes distinct margin structures and occupancy risks that shape capital deployment strategies.
Product Type:
Cost tier differentiation separates premium private suites from volume-driven shared environments.
- Private Offices:Enclosed suites with dedicated infrastructure and branding rights command the highest per-square-meter yields. Melbourne's climate-tech founders in Carlton and Fitzroy cluster here for confidentiality during investor due diligence.
- Shared Desks:Hot-desking arrangements in open-plan floors maximize density and community interaction. Sydney solo practitioners in Surry Hills and Pyrmont drive volume, though churn rates exceed private office retention by significant margins.
- Meeting Rooms:Bookable conference facilities generate ancillary revenue with minimal fixed staffing overhead.
- Event Spaces:Flexible floorplates for product launches and networking functions capture corporate event budgets.
Private Offices holds installed capacity. Shared Desks is rotating up the share rankings.
End User:
Customer type stratification maps directly to contract duration and credit risk profiles.
- Startups:Venture-backed teams in scaling phase anchor demand for expansion-ready footprints with short commitment terms. ASIC disclosure requirements for membership agreements as financial products add compliance overhead for operators serving this segment.
- Enterprises:ASX-listed corporations unbundle headquarters into distributed satellite arrangements. Financial services firms establishing reg-tech development pods in Melbourne's Docklands precinct represent concentrated procurement volume.
- Freelancers:Individual knowledge workers prioritize network effects and location convenience over space specifications.
- Remote Companies:Distributed teams without physical headquarters seek registered commercial addresses and mail handling.
Enterprises holds installed capacity. Startups is rotating up the share rankings.
Service Type:
Application flexibility determines how closely revenue correlates with physical occupancy.
- Virtual Offices:Address registration and mail forwarding without desk access carries minimal operational cost and the steepest margin expansion trajectory. Remote companies across Brisbane and Perth drive adoption as they establish commercial presence without capital commitment.
- Membership Plans:Tiered access bundles combine workspace hours with amenities under recurring billing. Hub Australia's curated community programming targets climate-tech founders through sector-specific floors.
- On-Demand Services:Ad-hoc bookings for single days or hours capture sporadic usage patterns.
- Dedicated Desks:Reserved workstations in shared environments split the difference between hot-desking flexibility and private office security.
Membership Plans holds installed capacity. Virtual Offices is rotating up the share rankings.
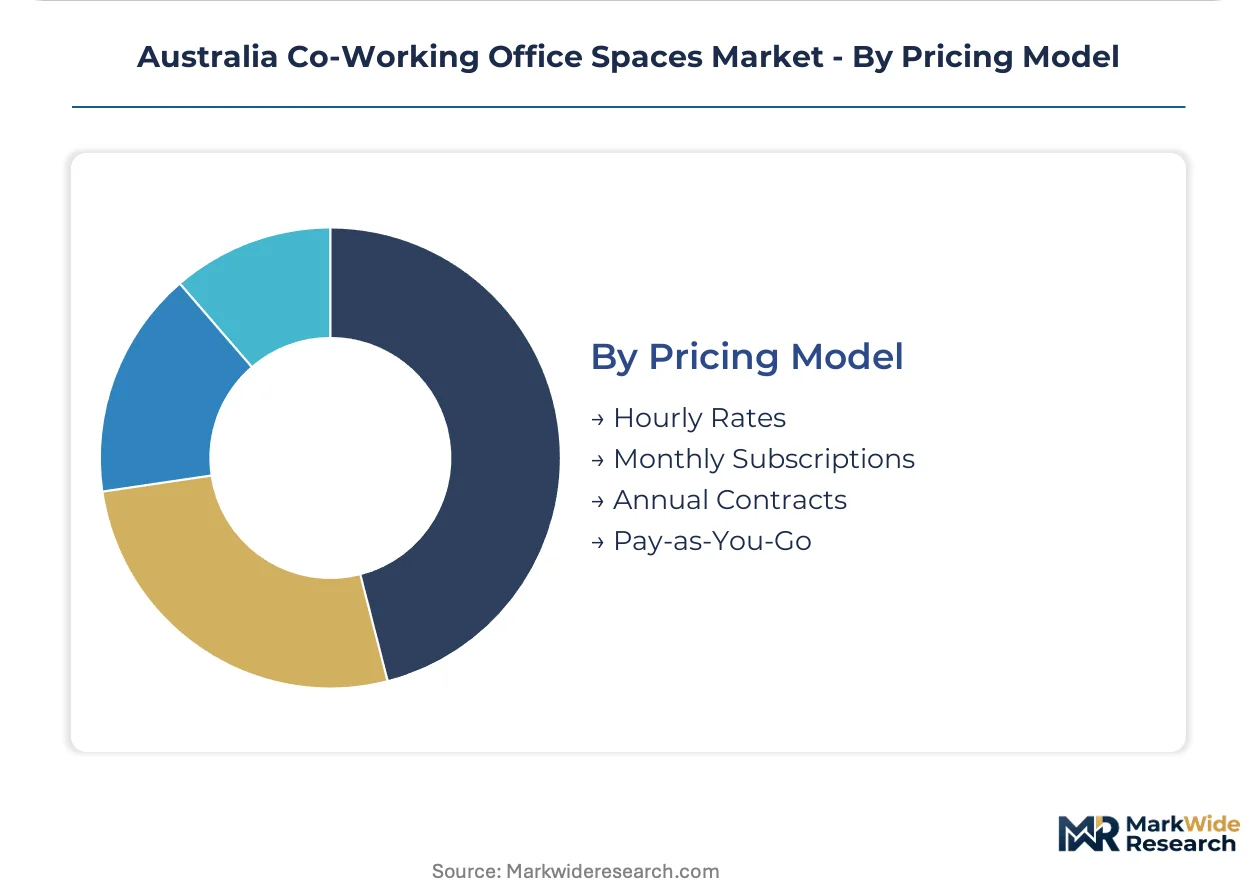
Pricing Model:
Contract maturity structures align payment timing with operator cash flow needs and member risk preferences.
- Monthly Subscriptions:Recurring revenue with 30-day cancellation terms dominates the Australian market. The Australian Taxation Office's instant asset write-off scheme incentivizes small businesses to classify these payments as deductible operational expenditures.
- Annual Contracts:Prepaid commitments secure discounted rates and guaranteed capacity for scaling teams. JustCo anchors growth in Melbourne's suburban corridors using longer terms to undercut incumbent office towers.
- Hourly Rates:Micro-transactions for meeting rooms and day passes access corporate travel budgets through hotel loyalty program integrations.
- Pay-as-You-Go:Usage-based billing without minimum commitments attracts experimental users with unpredictable schedules.
Monthly Subscriptions holds installed capacity. Annual Contracts is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales commands premium pricing power through Sydney's Tech Central precinct, while Victoria's suburban corridors compete on accessibility and cost efficiency for scaling teams.
New South Wales
Tech Central in Sydney anchors demand from fintech and enterprise software teams seeking proximity to venture capital networks. Safe Work Australia mandates psychological health protocols for high-density shared environments, forcing ventilation retrofits in older CBD buildings. Barangaroo and Pyrmont clusters concentrate ASX-listed corporations unbundling headquarters into satellite arrangements.
Victoria
Melbourne's inner-northern suburbs of Carlton and Fitzroy attract climate-tech founders requiring sector-specific facilities and investor access. Proposed tenancy law reforms threaten to recategorize membership agreements as retail leases, triggering bond requirements that undermine flexibility value propositions. Docklands precinct hosts financial services firms establishing regulatory technology development pods.
Queensland
Brisbane's middle-ring council districts present first-mover opportunities in car-dependent knowledge-worker catchments underserved by branded operators. State-based building codes mandate fire safety and accessibility standards that shape fit-out costs for new entrants. Fortitude Valley and suburban corridors compete on price against incumbent office towers.
Western Australia
Perth's Fremantle corridor remains underpenetrated by national operators despite growing demand from resources sector professionals and remote companies. The Australian Taxation Office's instant asset write-off scheme incentivizes small businesses to classify co-working memberships as deductible operational expenditures. Suburban nodes attract distributed teams seeking registered commercial addresses without CBD premiums.
South Australia
Adelaide's innovation precincts concentrate defense-tech and space industry startups requiring flexible expansion options. State regulators administer workplace health and safety frameworks imposing duty-of-care obligations on operators managing shared environments. The city's lower cost base attracts remote companies establishing commercial presence without eastern seaboard overheads.
Australia Co-Working Office Spaces Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with fit-out and amenity provisioning. The Australian market fragments across international platforms, national networks, and niche community operators. Three archetypes dominate: global brands leveraging international scale for premium CBD positions, regional specialists curating sector-specific programming, and suburban price competitors optimizing for occupancy velocity. Dominant competitive moves include revenue-sharing negotiations with institutional landlords and automation of front-desk operations through biometric access systems.
Within the international platform tier, WeWork Management LLC and JustCo exemplify scale-driven positioning across Sydney and Melbourne corridors. Hub Australia occupies a position as a national network operator with curated community programming targeting climate-tech founders through sector-specific floors. Stone & Chalk represents the niche archetype, anchoring fintech and enterprise software clusters through sector-dedicated facilities with embedded investor networks.
| Leading Market Players |
|---|
| Spaces |
| JustCo |
| Hub Australia |
| Stone & Chalk |
| CreativeCubes.Co |
| WOTSO Limited |
| Servcorp |
| York Butter Factory |
| WeWork Management LLC |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Sydney CBD premium suites compresses operator yields while accelerating suburban price competition, forcing landlords to trade headline rents for occupancy velocity and revenue-sharing structures that reshape procurement economics across the Australian market.
Pricing Analysis
The customization-premium spread between branded private offices and unbranded shared desks spans approximately 3x in effective monthly rates per workstation. Three-tier pricing structure across premium, standard, and economy levels anchors the Australian market, with Hub Australia commanding brand premiums through sector-specific climate-tech programming while JustCo competes on stripped-down fit-outs in Melbourne's suburban corridors. Price differentiation rests on location accessibility and embedded amenity bundling rather than pure square-meterage. Cost compression in the shared desk tier is intensifying because suburban supply expansion outpaces demand absorption in Brisbane and Perth. Freelancers and solo practitioners exhibit the highest price sensitivity, while ASX-listed corporations procurement teams prioritize contract flexibility over rate minimization.
Supply Chain Analysis
Tariff exposure between Australia and China dominates fit-out cost volatility for timber, steel, and imported furnishings that constitute 60% of construction inputs. Domestic manufacturing concentrates in Victoria and New South Wales for joinery and soft furnishings, while China, Vietnam, and Malaysia anchor hard goods supply. Raw material dependencies span engineered timber products, commercial-grade carpeting, and biometric access hardware. Single-source vulnerability concentrates in cloud infrastructure provisioning, where Amazon Web Services and Microsoft Azure host the majority of operator technology stacks. Distribution runs through national logistics networks with last-mile fit-out coordination handled by regional contracting consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern as venture capital deployment rebounds from trough levels and instant asset write-off schemes sustain small business workspace procurement through deductible operational expenditure classification.
For Market Incumbents: Build switching-cost moats through embedded community programming and sector-specific floor curation that replicates Stone & Chalk's fintech cluster model. Defensive moves should prioritize biometric access automation to collapse front-desk labor costs by 40%, and secure revenue-sharing renegotiations with institutional landlords before occupancy troughs trigger margin erosion. The substitution threat from Microsoft Teams and Slack bundled collaboration tools demands rapid response through irreplaceable physical networking programming.
For New Entrants and Emerging Players: Middle-ring council districts in Brisbane and Perth's Fremantle corridor represent the most penetrable entry points with first-mover advantages in car-dependent knowledge-worker catchments underserved by branded operators. Climate-tech laboratory prototyping facilities in Victoria's renewable energy certificate trading infrastructure zones offer white-space positioning. Virtual office address registration services carry minimal operational cost and the steepest margin expansion trajectory. Go-to-market execution should anchor on hotel loyalty program integrations that access corporate travel budgets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across virtual office and on-demand service sub-segments as technology automation reduces fixed staffing requirements. Long-term viability over a five-to-ten year window favors operators with demonstrated suburban occupancy velocity and landlord relationship depth rather than premium CBD footprint scale. Acquisition target archetypes include niche sector specialists with embedded investor networks and proven community programming. The signal to watch is tenancy law reform progression in Victoria and New South Wales that could recategorize membership agreements as retail leases with bond requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Access Automation | Computer-vision systems reduce labor costs 40% while generating behavioral data for dynamic pricing algorithms. |
| Suburban Corridor Expansion | First-mover positioning in Brisbane middle-ring districts captures car-dependent knowledge workers at lower fit-out cost. |
| Sector-Specific Floor Curation | Climate-tech programming in Carlton and Fitzroy replicates Stone & Chalk's embedded investor network model. |
| Virtual Office Scale-Up | Address registration services carry minimal operational cost and the steepest margin expansion trajectory. |
| Hotel Loyalty Integration | Day pass redemption through airline status tiers accesses corporate travel budgets excluded from workspace procurement. |
Study Parameters
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings on membership agreement structuring and landlord negotiation dynamics. Workspace operators, commercial property leasing directors, venture capital firm operations managers, and Safe Work Australia compliance officers contributed operational perspective. Secondary sources include Australian Securities and Investments Commission disclosure filings, Australian Taxation Office scheme documentation, state-based building code registers, and tenancy law reform parliamentary records. Bottom-up location-level capacity assessment triangulates against top-down market sizing from subscription revenue flows.
Calibration against historical occupancy volatility patterns and venture capital deployment cycles shapes the projection framework. Segmentation dimensions span product type, end user archetype, service flexibility tier, and pricing model maturity across the modeling period. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection scenarios. Industry-specific inputs include instant asset write-off scheme uptake rates and proposed tenancy law reform probability weightings.
Macroeconomic conditions sit as an overlay; deviation in venture capital deployment velocity, construction input price indices, or commercial property yield compression would shift the trajectory. Forecasts embed assumptions on membership agreement regulatory classification stability and cloud infrastructure cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
Asean Office Real Estate Market