
 Saudi Arabia Office Real Estate Market | 2026-2036
Saudi Arabia Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Office Real Estate Market Analytics
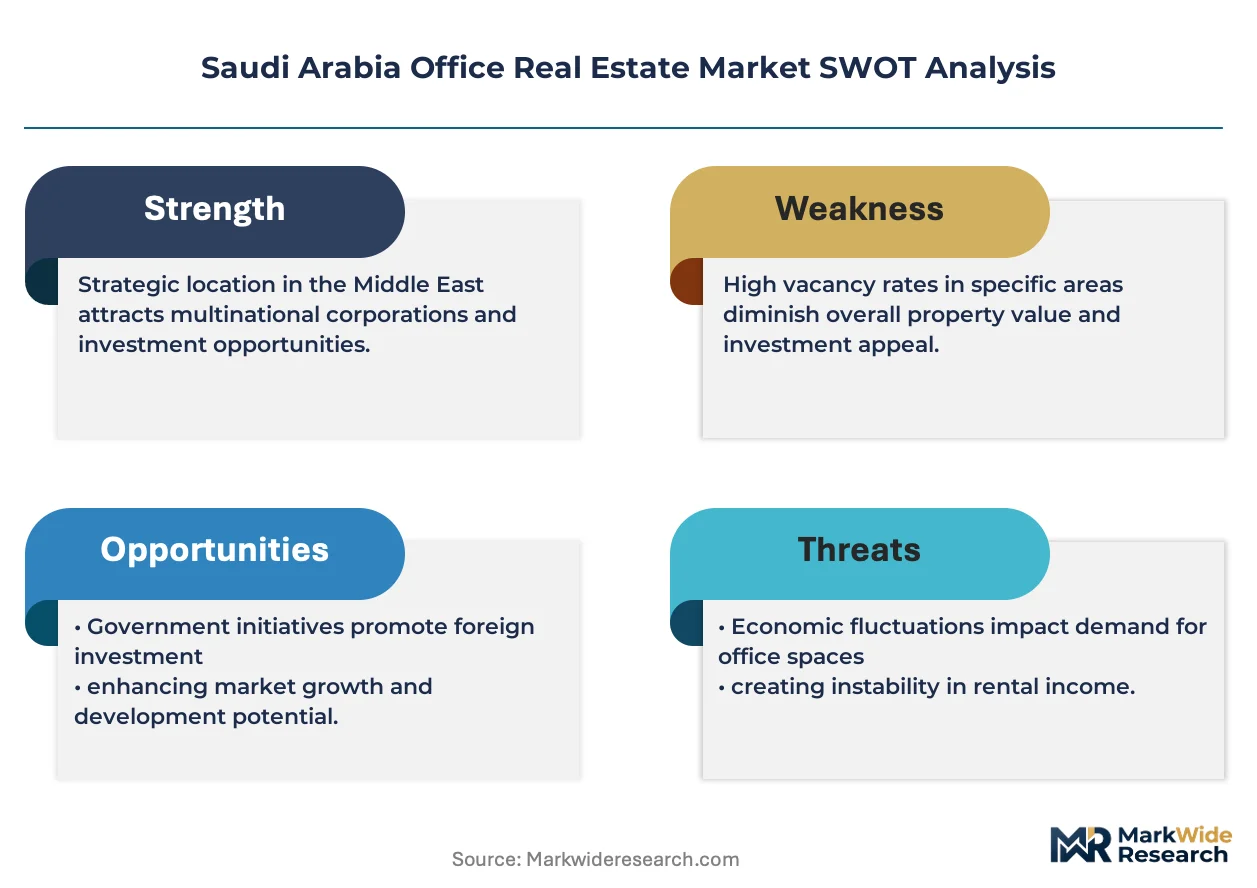
Saudi Vision 2030 is realigning the cost-of-entry calculus for commercial developers, with giga-project mandates and localization requirements raising capital thresholds for new office supply. JLL Riyadh leverages its multinational platform to anchor corporate leasing mandates across the Kingdom. SEDCO Development sustains a diversified portfolio spanning Riyadh, Jeddah, and Dammam. Kingdom Holding Company dominates premium Grade A developments in Riyadh's central business district.
Saudi Arabia office real estate encompasses purpose-built commercial structures designed for administrative, professional, and corporate operations, typically constructed with reinforced concrete frames, curtain wall glazing systems, and centralized HVAC infrastructure achieving 150-200 watts per square meter cooling loads; these assets generate rental income through lease contracts and serve as operational headquarters for banking, technology, and government entities. Grade A offices command the deepest tenant pools and longest lease durations, while co-working spaces represent the fastest-expanding property type as hybrid work policies reshape occupier preferences. Flexible lease structures are capturing growing share from traditional long-term corporate commitments, particularly among information technology entrants and consulting firms seeking scale agility.
The Saudi Building Code and Saudi Standards, Metrology and Quality Organization set structural safety and energy efficiency benchmarks that all new office developments must satisfy, while the Saudi Green Building Forum promotes LEED-equivalent certification pathways that increasingly influence institutional investor capital allocation. Municipalities in Riyadh, Jeddah, and Dammam enforce zoning overlays that restrict office density in heritage districts while encouraging vertical expansion in designated financial zones. Stakeholders must monitor how giga-project office pipelines in NEOM and Red Sea Global redirect tenant demand from established city centers.
Market Dynamics
Saudi Vision 2030 giga-projects are redrawing tenant demand maps, pulling corporate headquarters from established Riyadh and Jeddah CBDs toward purpose-built NEOM and Red Sea Global office clusters with integrated live-work amenities.
Growth Catalysts
- Foreign Bank Licensing Reforms:Saudi Central Bank eased capital requirements and branch restrictions, drawing regional financial services firms to establish Riyadh headquarters.
- LEED-Aligned Efficiency Mandates:Saudi Green Building Forum certification pathways now influence institutional capital allocation toward low-carbon office stock.
- King Abdullah Financial District Concentration:Riyadh's purpose-built financial zone offers regulatory sandbox benefits and consolidated government services that anchor multinational back-office operations.
Market Restraints
- Steel and Aluminum Input Volatility:Curtain wall glazing and reinforced concrete frame costs fluctuate with global commodity markets, compressing developer margins on fixed-price contracts.
- Giga-Project Supply Pipeline Concentration:NEOM and Red Sea Global office stock threatens to oversaturate premium segments before absorption rates stabilize in established cities.
- Saudi Building Code Compliance Timelines:Municipal permitting delays for structural safety and energy efficiency benchmarks extend project delivery schedules by eight to fourteen months.
Strategic Opportunities
- Eastern Province Undersupply:Dammam and Khobar office markets lack Grade A stock relative to petrochemical and logistics tenant demand, creating first-mover positioning for developers.
- Smart Building Convergence:Integration of IoT sensor networks with centralized HVAC infrastructure enables predictive maintenance contracts and utility cost arbitrage.
- Localization Requirements:Saudization mandates and local content rules favor joint ventures with Saudi-owned developers for government-anchored lease contracts.
Industry Challenges
- FM Talent Scarcity:Facility management professionals with smart building certification expertise command premium wages that strain operating expense budgets.
- Legacy System Integration:Retrofitting 1990s-era office stock with centralized cooling loads of 150-200 watts per square meter requires complete MEP infrastructure replacement.
- Hybrid Work Policy Uncertainty:Corporate tenants hesitate to commit to traditional ten-year lease structures while headcount per square foot ratios remain unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Office Real Estate Market |
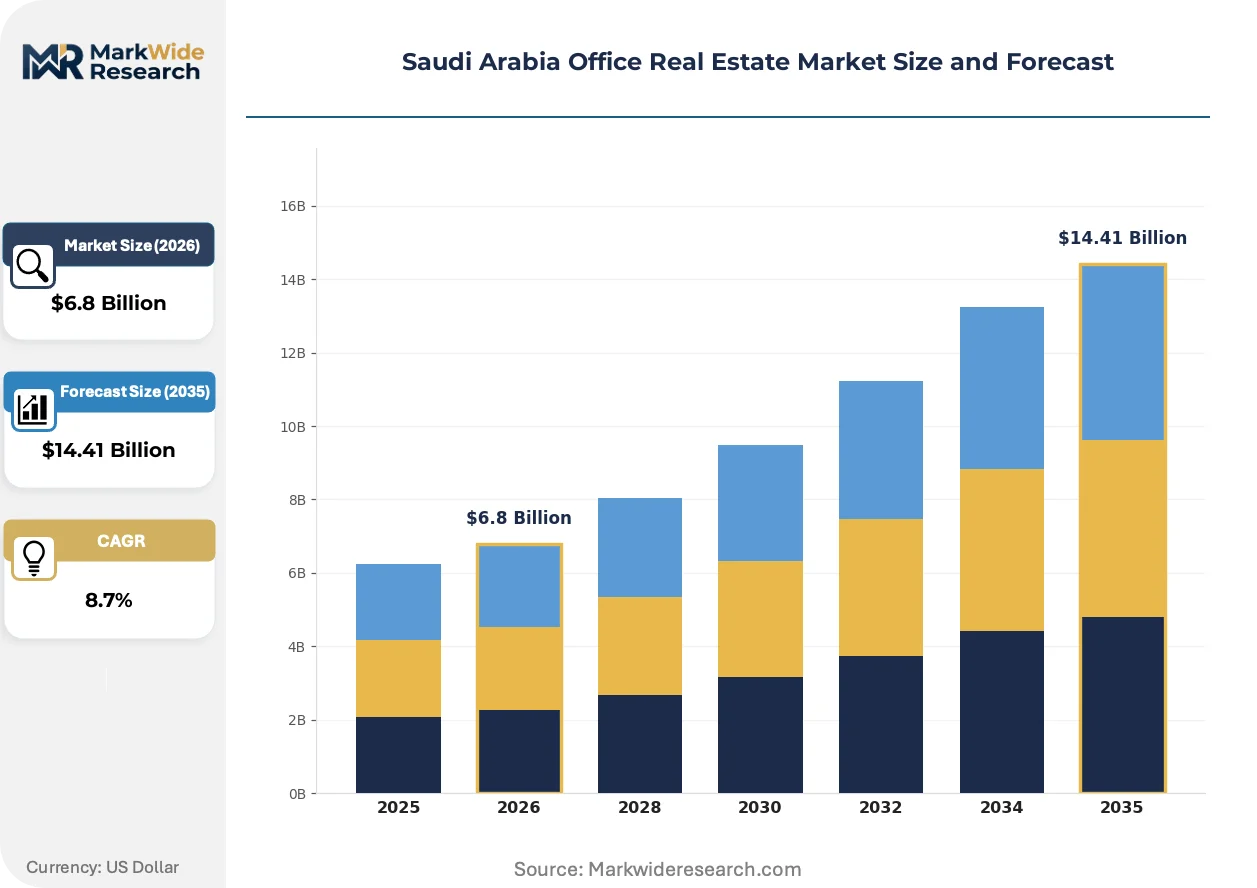
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Grade A Offices, Grade B Offices, Serviced Offices, Co-working Spaces, Executive Suites Lease Term: Short-term, Medium-term, Long-term, Flexible Lease, Corporate Lease Occupier Industry: Financial Services, Information Technology, Consulting Firms, Government Agencies, Legal Services Building Facilities: Parking Spaces, Security Systems, Conference Rooms, Cafeteria, High-speed Internet |
| Companies Covered | JLL Riyadh, Century 21 Saudi Arabia, Saudi Real Estate Company, NAI Saudi Arabia, Esrar, SEDCO Development, Kingdom Holding Company, Abdul Latif Jameel, Dar Al Arkan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Office Real Estate Market Evolving Landscape
Flexible workspace configurations and intelligent building systems are compressing traditional lease economics while elevating operational efficiency expectations across the Kingdom's commercial stock.
Smart building management platforms that integrate real-time occupancy sensors with automated HVAC and lighting controls are overtaking conventional building automation systems in new Grade A developments. Financial services tenants in King Abdullah Financial District specify these platforms as standard lease requirements. The technology is compressing energy operating costs by twenty to thirty percent while generating granular space utilization data that feeds lease renegotiation strategies.
Saudi Standards, Metrology and Quality Organization energy efficiency benchmarks now mandate thermal performance testing for all new office glazing systems. Developers must demonstrate compliance with centralized cooling load specifications before municipal occupancy permits issue. The policy is accelerating curtain wall specification upgrades in Riyadh's financial zone while delaying certificate of completion timelines for projects designed under prior code editions.
Corporate occupiers increasingly unbundle long-term lease commitments into shorter-term flexible contracts with expansion options. Consulting firms and technology entrants in Jeddah's commercial corridor favor this structure over traditional ten-year corporate mandates. The pattern concentrates in information technology verticals where headcount volatility exceeds real estate planning cycles.
Saudi Arabia Office Real Estate Market Segmentation
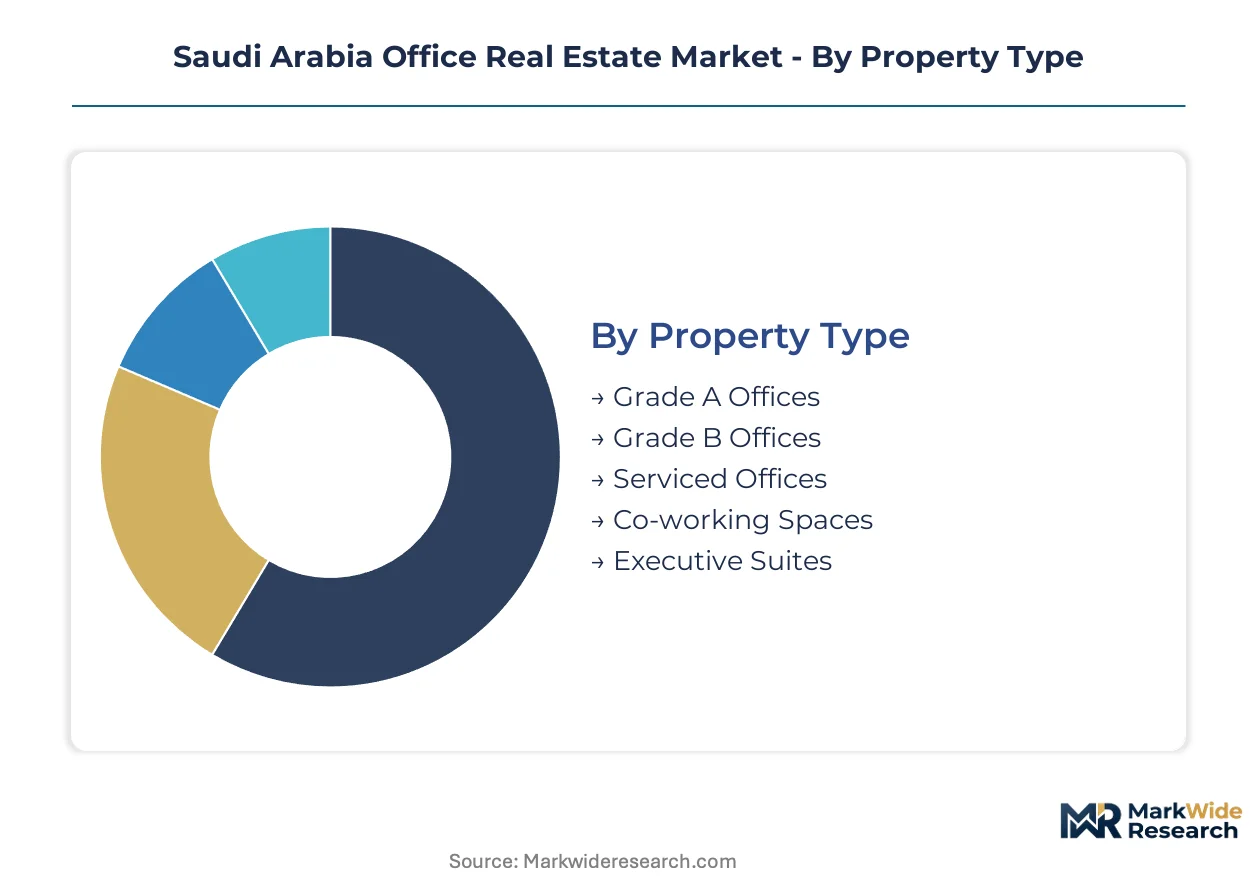
Office real estate segmentation in Saudi Arabia reflects divergent capital intensity, tenant retention economics, and regulatory compliance burdens across property tiers and lease structures. Understanding these axes enables developers to align supply specifications with Vision 2030 localization mandates and giga-project demand redirection.
Property Type:
Curtain wall glazing specifications and reinforced concrete frame standards differentiate capital deployment requirements across the quality spectrum.
- Grade A Offices:Premium stock features centralized HVAC infrastructure rated at 150-200 watts per square meter cooling loads, full-height glazing systems, and smart building management platforms. Demand concentrates in Riyadh's King Abdullah Financial District where Saudi Central Bank licensing reforms anchor multinational financial services headquarters.
- Co-working Spaces:Modular fit-outs with hot-desking configurations and shared amenity clusters serve hybrid work policies. Jeddah's commercial corridor shows the steepest expansion trajectory as information technology entrants prioritize scale agility over long-term commitments.
- Grade B Offices:Older reinforced concrete stock with partial glazing retrofits and conventional building automation systems.
- Serviced Offices:Turnkey configurations with reception staffing and utility-inclusive pricing for rapid market entry.
- Executive Suites:Premium sub-segments within larger buildings offering dedicated floors with private amenities.
Grade A Offices lead on scale; Co-working Spaces lead on momentum.
Lease Term:
Contract duration directly shapes developer financing structures and tenant improvement amortization schedules.
- Flexible Lease:Month-to-month or sub-12-month structures with expansion options and minimal fit-out obligations. Consulting firms in Riyadh's financial zone favor this format for project-based staffing volatility.
- Corporate Lease:Traditional 5-10 year commitments with fixed escalation clauses and comprehensive maintenance responsibilities. Government agencies anchor this segment through Saudization-mandated localization requirements.
- Short-term:Sub-24 month contracts for market testing and temporary project offices.
- Medium-term:2-5 year structures balancing commitment security with renegotiation flexibility.
- Long-term:10+ year anchors with renewal options and capital contribution clauses.
Corporate Lease dominates revenue stability; Flexible Lease captures volume expansion.
Occupier Industry:
Tenant verticals impose distinct spatial ratios, security protocols, and technology infrastructure demands.
- Financial Services:Trading floors require redundant power systems, low-latency connectivity, and Saudi Central Bank compliance zones. King Abdullah Financial District regulations consolidate these requirements into purpose-built clusters.
- Information Technology:Open-plan configurations with raised floor systems and server room adjacencies predominate. Jeddah's commercial corridor absorbs the fastest-growing demand as software entrants scale engineering teams.
- Consulting Firms:Client-facing reception zones combined with hot-desking back-office layouts.
- Government Agencies:Saudization-mandated local content requirements and secure document handling protocols.
- Legal Services:Private partner offices with confidential meeting room adjacencies and document retention compliance.
Financial Services commands premium pricing; Information Technology drives absorption velocity.
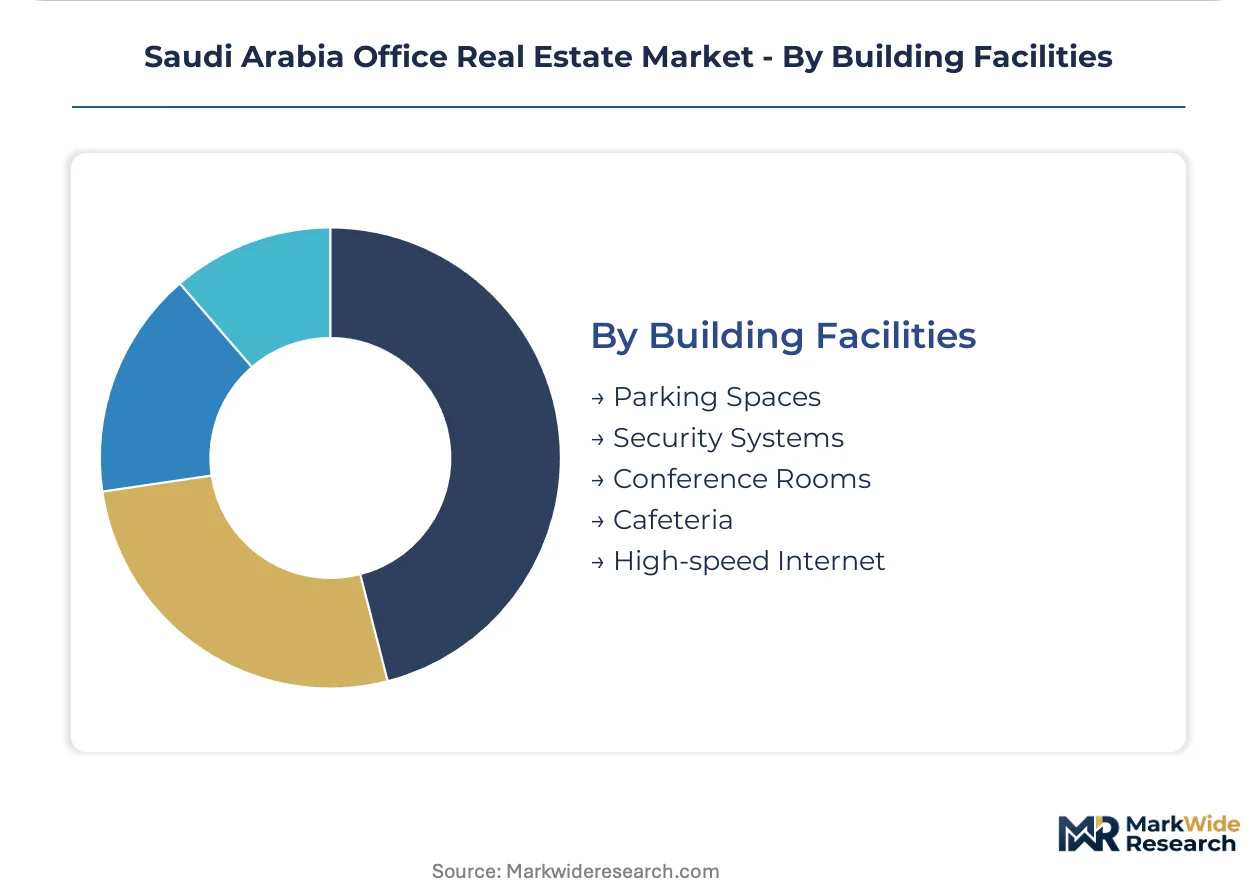
Building Facilities:
Amenity bundling increasingly determines lease renewal rates and effective rent achievement in competitive submarkets.
- High-speed Internet:Fiber-optic backbone infrastructure with redundant carrier diversity and sub-10ms latency to financial exchanges. Grade A specifications in Riyadh's financial zone mandate this as baseline tenant utility.
- Security Systems:Biometric access control, CCTV networks, and perimeter monitoring integrated with municipal emergency response protocols. Government-anchored leases in Dammam require compliance with Saudi Building Code safety benchmarks.
- Parking Spaces:Basement and podium configurations with electric vehicle charging pre-wiring.
- Conference Rooms:Video-conferencing equipped meeting suites bookable through building management platforms.
- Cafeteria:Food service facilities with prayer room adjacencies and Saudization staffing requirements.
High-speed Internet anchors tenant retention; Security Systems gates institutional capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's workforce concentration in Riyadh anchors national office demand, with government, finance, and technology employment clustering in the capital's specialized districts.
Riyadh
King Abdullah Financial District and Diriyah Gate anchor financial services and heritage-tourism adjacent office demand. Saudi Central Bank licensing reforms draw regional banks to establish headquarters here. Grade A stock with smart building platforms commands premium rents in the purpose-built financial zone.
Eastern Province
Petrochemical and logistics corporate headquarters drive Grade A office requirements in Dammam and Khobar. Aramco and SABIC-affiliated entities anchor long-term corporate lease demand. The region lacks sufficient premium stock relative to industrial tenant requirements.
Western Region
Jeddah's commercial corridor absorbs information technology and consulting firm expansion with flexible lease preferences. Red Sea Global's coastal developments threaten to redirect hospitality-adjacent office demand from the established city center. Port logistics and pilgrimage-related services sustain secondary office requirements.
NEOM Northwest
THE LINE and Oxagon projects promise purpose-built office clusters with integrated live-work amenities. Saudi Vision 2030 giga-project mandates concentrate public sector and technology tenant demand in this greenfield development. Completion timelines and absorption rates remain uncertain against established city centers.
Saudi Arabia Office Real Estate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's office development and services landscape. Kingdom Holding Company and Abdul Latif Jameel represent integrated conglomerate developers with cross-sector asset portfolios. SEDCO Development and Dar Al Arkan occupy focused real estate development archetypes with geographic specialization. Competitive positioning hinges on securing government-anchored lease contracts through localization joint ventures and acquiring prime land parcels in Riyadh's financial zone ahead of foreign bank entry waves.
Among Riyadh-based service providers, JLL Riyadh exemplifies multinational platform leverage for corporate leasing mandates. Century 21 Saudi Arabia and NAI Saudi Arabia occupy the brokerage and advisory tier, facilitating tenant-landlord matching across property grades. Esrar represents technology-enabled property services, while Saudi Real Estate Company anchors the development-focused segment with historical market presence.
| Leading Market Players |
|---|
| JLL Riyadh |
| Century 21 Saudi Arabia |
| Saudi Real Estate Company |
| NAI Saudi Arabia |
| Esrar |
| SEDCO Development |
| Kingdom Holding Company |
| Abdul Latif Jameel |
| Dar Al Arkan |
| Others |
Value Network & Pricing Analysis
Multinational financial services firms concentrating in Riyadh's King Abdullah Financial District negotiate bundled service contracts that merge base rent with smart building platform fees and facility management charges. This buyer archetype's procurement scale forces developers to unbundle legacy lease structures or absorb technology upgrade costs into headline rates.
Pricing Analysis
Bundled amenity-inclusive contracts dominate Grade A stock in Riyadh's financial zone, while unbundled base-plus-utility structures prevail in Jeddah's flexible workspace segment. Price differentiation rests on LEED-aligned certification tiers and Saudization compliance levels that gate government-anchored leases. Cost compression in Grade B retrofits is intensifying because Saudi Building Code mandates trigger complete MEP replacement. Flexible lease tenants in information technology verticals exhibit highest price sensitivity; financial services headquarters show lowest sensitivity due to regulatory sandbox requirements.
Supply Chain Analysis
Freight costs from China, South Korea, and Germany for curtain wall glazing systems and HVAC compressors feed directly into developer pro-forma assumptions. Raw material dependencies span aluminum extrusions, low-emissivity glass, and copper refrigerant piping. Single-source vulnerability concentrates in smart building sensor networks sourced from East Asian manufacturing clusters. Distribution runs through Riyadh-based general contractors with municipal pre-qualification status, bypassing direct developer-procurement for major mechanical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's office market represents a late-cycle quality story as Vision 2030 giga-projects redirect demand toward premium specifications with integrated live-work amenities and smart building certifications.
For Market Incumbents: Acquire Grade A development pipelines in Dammam and Khobar before petrochemical tenant demand outstrips Eastern Province supply. Kingdom Holding Company and SEDCO Development should consolidate land positions in Riyadh's financial zone ahead of foreign bank licensing waves. Joint venture structures with Saudi-owned partners satisfy Saudization mandates for government lease contracts. Smart building certification investments differentiate retention economics against NEOM's purpose-built competition. For New Entrants and Emerging Players: The price-point gap between flexible workspace operators and traditional corporate lease providers offers entry space for hybrid-format specialists. Target Jeddah's commercial corridor where information technology entrants prioritize scale agility over long-term commitments. Co-working configurations with expansion options capture consulting firm demand that hesitates on ten-year structures. Partner with existing facility management platforms to bypass FM talent scarcity constraints. For Investors and Strategic Acquirers: Sovereign wealth funds and regional pension managers are the most active acquirer in this space, prioritizing income-generating Grade A stock with government-anchored tenants. Long-term viability hinges on lease duration weighted toward financial services and public sector verticals resistant to hybrid work displacement. Monitor absorption rates in NEOM's THE LINE and Oxagon projects as inflection indicators for established city center repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Building Certification Investment | LEED-aligned specifications from Saudi Green Building Forum unlock institutional capital allocation. |
| Joint Venture Localization | Saudization mandates favor partnerships with Saudi-owned developers for government lease contracts. |
| Eastern Province Capacity Addition | Grade A stock scarcity in Dammam and Khobar creates first-mover positioning for petrochemical tenant capture. |
| Flexible Lease Platform Launch | Modular configurations with expansion options address information technology sector headcount volatility. |
| Integrated Live-Work Development | NEOM and Red Sea Global projects redirect demand toward amenity-rich office clusters outside established CBDs. |
Research Methodology
Bottom-up occupier industry modeling reconciled against top-down development pipeline tracking forms the analytical core of this study. Primary interviews with real estate development executives, corporate leasing directors, municipal planning officers, and facility management specialists were cross-validated against Saudi Building Code filings, Saudi Central Bank licensing registers, and municipal occupancy permit databases. Secondary sources include Vision 2030 giga-project disclosures, JLL and CBRE market reports, and Saudi Standards, Metrology and Quality Organization technical bulletins.
Input-output matrices map construction cost indices to rental achievement across property type and lease term segments over the projection horizon. Segmentation dimensions include property grade tier, contract duration structure, occupier vertical, and building facility specification. CAGRs were derived from supply absorption rates against foreign bank entry timelines and giga-project completion schedules. Forecast inputs incorporate steel and aluminum commodity volatility, municipal permitting delay distributions, and hybrid work policy adoption curves.
The model assumes a particular technology adoption path; alternative pathways for smart building platform integration would alter the outlook if corporate tenants delay IoT sensor deployment or if Saudi Green Building Forum mandates accelerate beyond baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
United States Office Real Estate Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Global Office Space Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Australia Flexible Office Space Market