
 India Co-Working Office Spaces Market | 2026-2036
India Co-Working Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
India Co-Working Office Spaces Market Foresight
Flexible membership tiers are decoupling real estate from long-term lease obligations, transforming how occupancy gets sold in Indian commercial property. Awfis Space Solutions Limited leverages its asset-light franchise model to penetrate Tier-2 cities without direct capital deployment. WeWork India anchors premium positioning in Mumbai and Delhi-NCR through design-forward corporate offices. Smartworks Coworking Spaces Limited dominates enterprise-grade dedicated desk contracts with IT/ITES firms seeking compliance-ready infrastructure.
India co-working office spaces constitute commercially managed work environments offering furnished workstations, shared amenities, and enterprise IT infrastructure on contractual terms shorter than traditional commercial leases. These facilities typically deliver internet bandwidth above 100 Mbps per seat, biometric access control, and plug-and-play configurations to reduce client capex. Private offices command the highest margin pools among space type categories, while dedicated desks represent the fastest-growing configuration as mid-market enterprises abandon conventional leasing. The corporate customer segment leads absolute absorption, though startups sustain the highest churn-adjusted velocity across pay-as-you-go service models.
CDSCO guidelines on workplace health infrastructure and state-level RERA registrations shape fit-out standards and disclosure requirements for facility operators. BIS standards for electrical safety and fire suppression systems directly influence capital expenditure thresholds for new center launches. The PLI scheme for IT hardware manufacturing indirectly amplifies co-working demand as electronics firms establish design and testing operations near Bengaluru and Chennai clusters. Stakeholders must monitor how municipal corporation zoning relaxations for commercial-to-co-working conversions in Mumbai and Hyderabad reshape competitive entry barriers.
Market Dynamics
Enterprise IT/ITES firms are compressing lease commitments from five-year terms to twelve-month rolling contracts, forcing facility operators to restructure revenue recognition and capital deployment models around occupancy volatility rather than tenant stability.
Growth Catalysts
- Smart Cities Mission infrastructure:Municipal zoning relaxations in Hyderabad and Mumbai accelerate commercial-to-co-working conversions, reducing fit-out timelines for new center launches.
- PLI scheme for IT hardware:Electronics manufacturing clusters near Bengaluru and Chennai generate co-located design and testing operations requiring compliance-ready workspace infrastructure.
- Biometric access control:Enterprise-grade security specifications from IT/ITES clients normalize 100 Mbps+ bandwidth and plug-and-play configurations as baseline service expectations.
Market Restraints
- Grade A commercial rent escalation:Mumbai's Bandra-Kurla Complex and Delhi-NCR's Cyber Hub command premiums that compress operator margins on fixed-desk configurations.
- BIS electrical safety compliance:Fire suppression and power backup standards impose capital expenditure thresholds that deter unbranded operators from multi-floor dedicated desk contracts.
- CDSCO workplace health mandates:Medical infrastructure requirements for large floorplates add recurring operational costs without direct revenue attribution.
Strategic Opportunities
- Tier-2 city penetration:Jaipur, Indore, and Kochi exhibit latent demand from regional IT services firms underserved by asset-heavy direct ownership models.
- Franchise-led expansion:Asset-light partnership structures enable rapid center deployment without balance-sheet property concentration.
- RERA registration alignment:State-level real estate disclosure requirements create compliance moats that favor organized operators with standardized documentation protocols.
Industry Challenges
- Network infrastructure scaling:Delivering sub-20 millisecond latency to enterprise clients across distributed center portfolios strains capital allocation.
- Churn velocity management:Startup segment pay-as-you-go models generate high transaction volumes with unpredictable revenue recognition patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Co-Working Office Spaces Market |
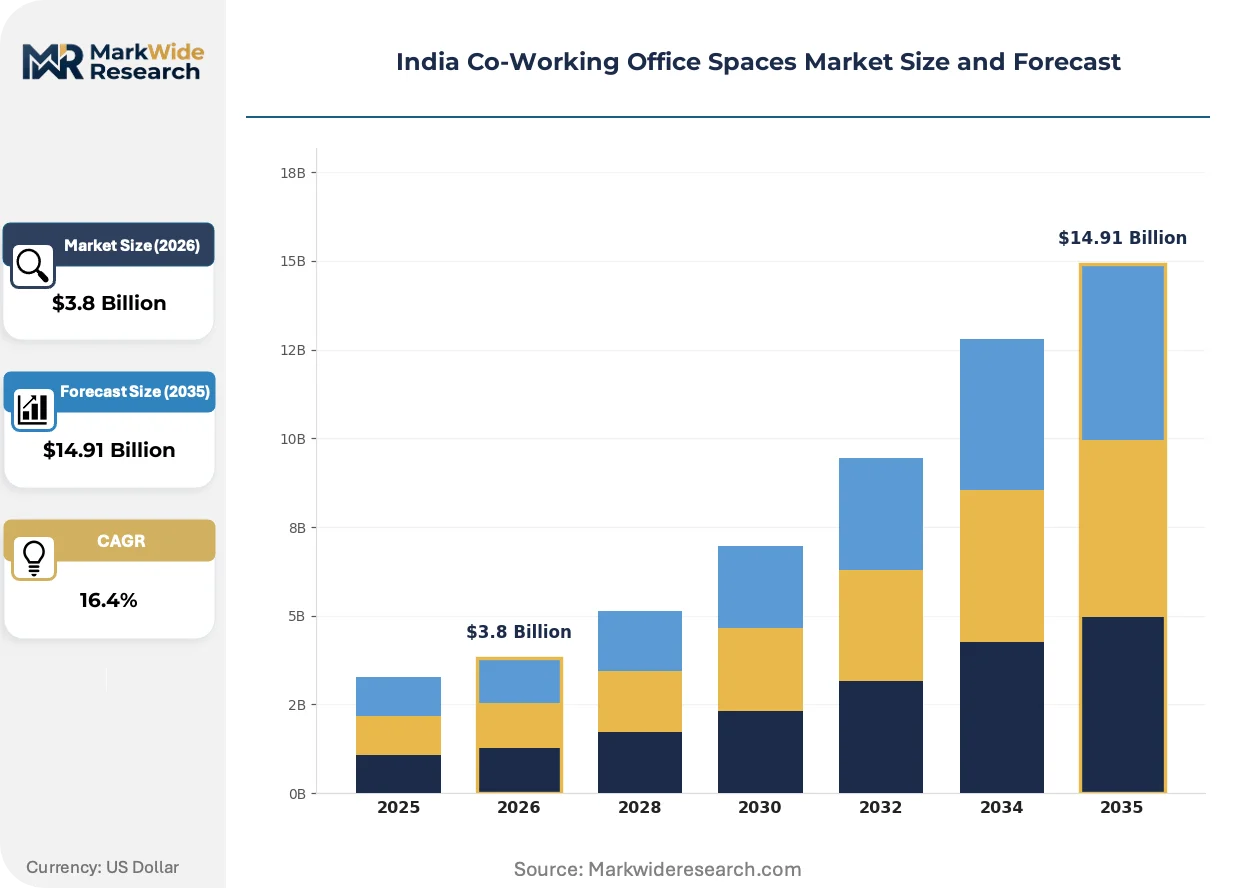
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Space Type: Private Offices, Hot Desks, Dedicated Desks,Conference Rooms Customer Segment: Startups, Freelancers, SMEs, Corporates Facility Type: Corporate Offices, Business Hubs, Innovation Centers, Creative Spaces Service Model: Membership Packages, Pay-as-you-go, Virtual Offices, Event Spaces |
| Companies Covered | Indiqube Spaces Limited, 91springboard, Awfis Space Solutions Limited, The Executive Centre, Incuspaze, WeWork India, EFC Limited, BHIVE Workspace, Smartworks Coworking Spaces Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Co-Working Office Spaces Market Shifts & Advancements
Workspace technology stacks are converging around unified platform architectures that collapse access control, bandwidth provisioning, and billing into single-pane operator dashboards.
Internet-of-Things sensor networks is integrating real-time occupancy analytics with HVAC and lighting systems. Facility operators in Bengaluru's ORR corridor deploy these systems to optimize energy spend per seat. The technology is integrating dynamic pricing algorithms that adjust membership rates based on utilization patterns, compressing revenue leakage from underoccupied floorplates.
State-level RERA registrations now mandate pre-launch disclosure of co-working fit-out specifications and amenity commitments. Maharashtra and Telangana enforcement actions against non-compliant operators have elevated documentation standards across the sector. Mid-market enterprises increasingly require RERA-compliant centers for vendor onboarding, filtering informal competitors from contract consideration sets.
Enterprise procurement teams now specify outcome-based workspace contracts with service-level agreements covering uptime, bandwidth consistency, and security incident response times. IT/ITES firms in Hyderabad and Chennai displace traditional lease negotiations with performance-governed agreements. This shift is most visible among firms with distributed delivery center strategies requiring standardized experience across multiple city locations.
India Co-Working Office Spaces Market Segmentation
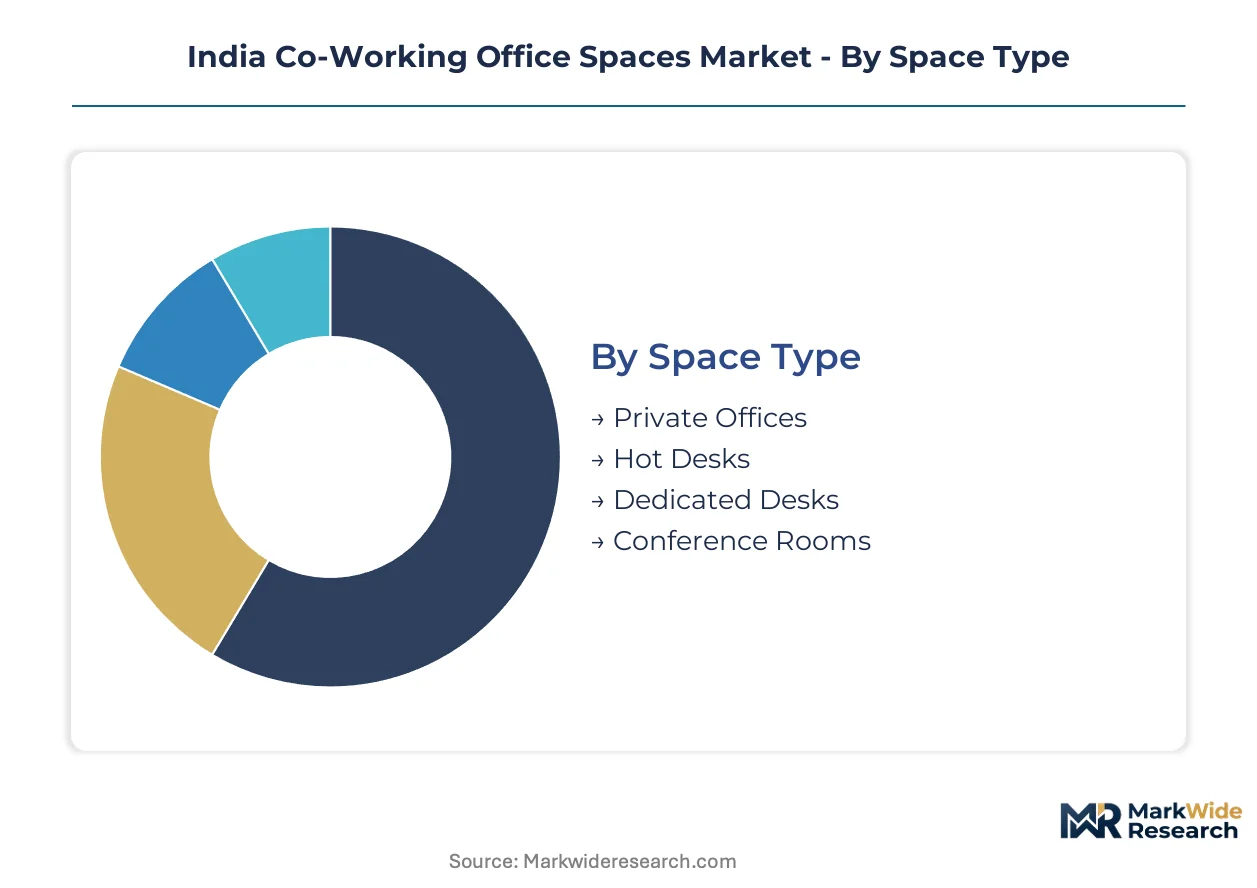
India's co-working operators configure revenue models around four intersecting dimensions: physical space formats, customer scale tiers, facility positioning, and contractual flexibility. Each segmentation axis carries distinct margin profiles and capital intensity requirements that shape competitive strategy.
Space Type:
Supply concentrates in configurations that balance utilization efficiency against enterprise compliance demands.
- Private Offices:Enclosed suites with dedicated infrastructure and branded entry points. Bengaluru's ORR corridor drives absorption as IT/ITES firms deploy compliance-ready satellite operations. BIS electrical safety standards elevate fit-out costs, filtering unbranded competitors from multi-floor contracts.
- Dedicated Desks:Permanently assigned workstations in shared floorplates with lockable storage. Mid-market enterprises in Hyderabad and Mumbai compress lease commitments from five-year terms to twelve-month rolling contracts. CDSCO workplace health mandates add recurring operational costs without direct revenue attribution.
- Hot Desks:Unassigned seating with first-come access across rotating inventory pools.
- Conference Rooms:Bookable meeting infrastructure with AV systems and video conferencing capabilities.
Private offices absorb the bulk of installed capacity; dedicated desks are expanding most quickly.
Customer Segment:
Cost tier differentiation separates transaction-heavy startup models from enterprise procurement cycles.
- Corporates:IT/ITES firms and professional services companies seeking standardized workspace infrastructure across distributed locations. Performance-governed contracts with SLA-backed uptime and bandwidth consistency displace traditional lease negotiations in Chennai and Delhi-NCR.
- SMEs:Regional services firms and professional practices requiring compliance-ready facilities for vendor onboarding. RERA registration requirements in Maharashtra and Telangana filter informal operators from consideration sets.
- Startups:Technology ventures with unpredictable headcount trajectories and minimal capex tolerance.
- Freelancers:Individual professionals purchasing workspace access on sporadic schedules.
Corporates anchor revenue stability; startups generate the steepest expansion trajectory in seat volume.
Facility Type:
Application context determines amenity specifications and municipal zoning compliance pathways.
- Business Hubs:Transit-oriented centers in commercial districts with retail and F&B integration. Mumbai's Bandra-Kurla Complex and Cyber Hub command rent premiums that compress margins on fixed-desk configurations.
- Corporate Offices:Design-forward facilities targeting headquarters relocation and satellite expansion. Smart Cities Mission infrastructure relaxations accelerate commercial-to-co-working conversions in Hyderabad.
- Innovation Centers:R&D-focused facilities with lab infrastructure and maker spaces.
- Creative Spaces:Loft-style configurations with production studios and exhibition capacity.
Business hubs dominate seat inventory; corporate offices are climbing the fastest in contract value per square foot.
Service Model:
Volume scalability depends on contractual structure and revenue recognition predictability.
- Membership Packages:Prepaid monthly or annual commitments with tiered amenity access. Enterprise procurement teams in Bengaluru specify outcome-based contracts with bandwidth consistency SLAs.
- Virtual Offices:Address registration and mail handling without physical occupancy. Regional IT services firms in Jaipur and Indore leverage these for market presence without capital deployment.
- Pay-as-you-go:Per-hour or per-day access with minimal commitment requirements.
- Event Spaces:Temporary venue rental for programming, training, and corporate functions.
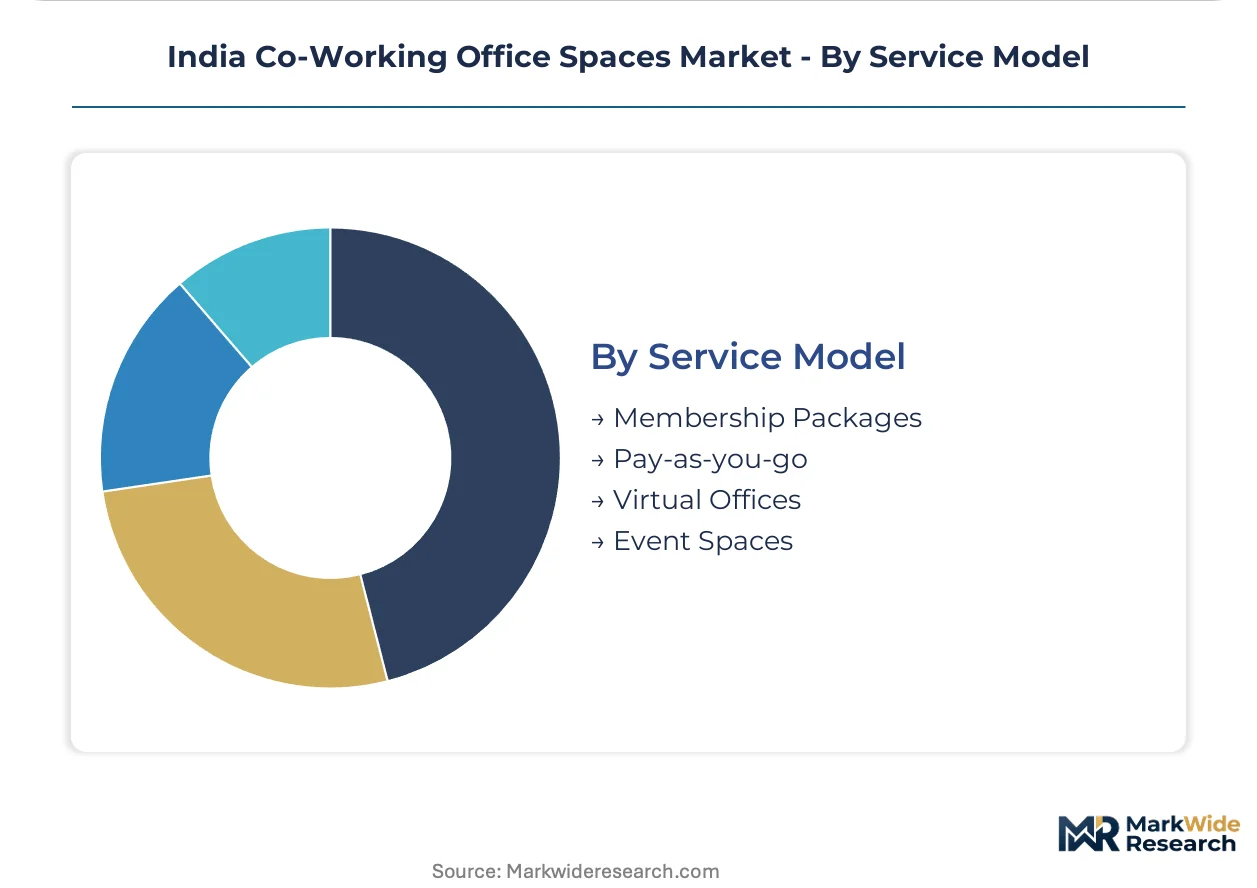
Membership packages capture the majority of contracted revenue; virtual offices are gaining share fastest among Tier-2 city entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Co-working supply concentrates in India's western and southern economic corridors, while demand diffusion pulls operators toward emerging Tier-2 clusters. Maharashtra and Karnataka anchor installed seat capacity. Telangana and Tamil Nadu drive contract velocity through IT/ITES procurement.
Maharashtra
Mumbai's Bandra-Kurla Complex and Lower Parel districts absorb premium private office configurations from financial services and consulting firms. The state's RERA registration mandates filter informal operators from multi-floor enterprise contracts. Pune's Hinjewadi IT corridor attracts satellite deployment from Bengaluru-headquartered technology firms seeking disaster recovery redundancy.
Karnataka
Bengaluru's Outer Ring Road corridor dominates dedicated desk absorption as IT/ITES firms compress lease commitments to twelve-month rolling terms. The state's IT policy framework extends stamp duty exemptions for commercial-to-co-working conversions in designated technology zones. Electronics City and Whitefield clusters generate concentrated demand for compliance-ready infrastructure from semiconductor design operations.
Telangana
Hyderabad's HITEC City and Gachibowli districts anchor enterprise-grade facility deployment driven by pharmaceutical and IT services procurement teams. The Telangana State Industrial Project Approval and Self-Certification System accelerates municipal zoning clearances for Grade A commercial conversions. Genome Valley proximity pulls co-located R&D workspace demand from life sciences firms.
Delhi-NCR
Gurugram's Cyber Hub and Noida's Sector 62 concentrate corporate office configurations for professional services and e-commerce headquarters operations. The National Capital Region's unified RERA authority mandates standardized disclosure of fit-out specifications and amenity commitments. Aerocity hospitality corridor generates transient demand for bookable conference infrastructure.
Tamil Nadu
Chennai's OMR and Guindy industrial districts absorb dedicated desk contracts from automotive and electronics manufacturing support operations. The state's Electronics Manufacturing Policy incentivizes co-located design workspace through subsidized land allocation in Sriperumbudur cluster. Mount-Poonamallee Road corridor attracts IT/ITES satellite operations from firms with distributed delivery center strategies.
India Co-Working Office Spaces Market Competitive Landscape
Capital-heavy asset owners compete with asset-light franchise operators for contract flow across India's co-working market. The vendor base stratifies between balance-sheet property holders and partnership-structured deployers. Three archetypes dominate: enterprise-grade dedicated desk specialists, premium design-forward positioners, and rapid Tier-2 penetrators via franchise networks. Competitive moves center on municipal zoning alignment for commercial conversions and outcome-based contract structuring with bandwidth SLAs.
Among asset-light expansion specialists, Awfis Space Solutions Limited and Smartworks Coworking Spaces Limited occupy positions representing franchise-led and enterprise-contract archetypes respectively. WeWork India anchors the premium-tier vector through design-forward positioning in Mumbai and Delhi-NCR. These three exemplify how operator strategy diverges across capital deployment models while converging on compliance-ready infrastructure specifications demanded by IT/ITES procurement teams.
| Leading Market Players |
|---|
| Indiqube Spaces Limited |
| 91springboard |
| Awfis Space Solutions Limited |
| The Executive Centre |
| Incuspaze |
| WeWork India |
| EFC Limited |
| BHIVE Workspace |
| Smartworks Coworking Spaces Limited |
| Others |
Supply & Pricing Matrix
Enterprise procurement teams compressing lease commitments from five-year terms to twelve-month rolling contracts force facility operators to restructure revenue models around occupancy volatility, compressing margins on fixed-desk configurations and elevating pricing power for operators with compliance-ready infrastructure.
Pricing Analysis
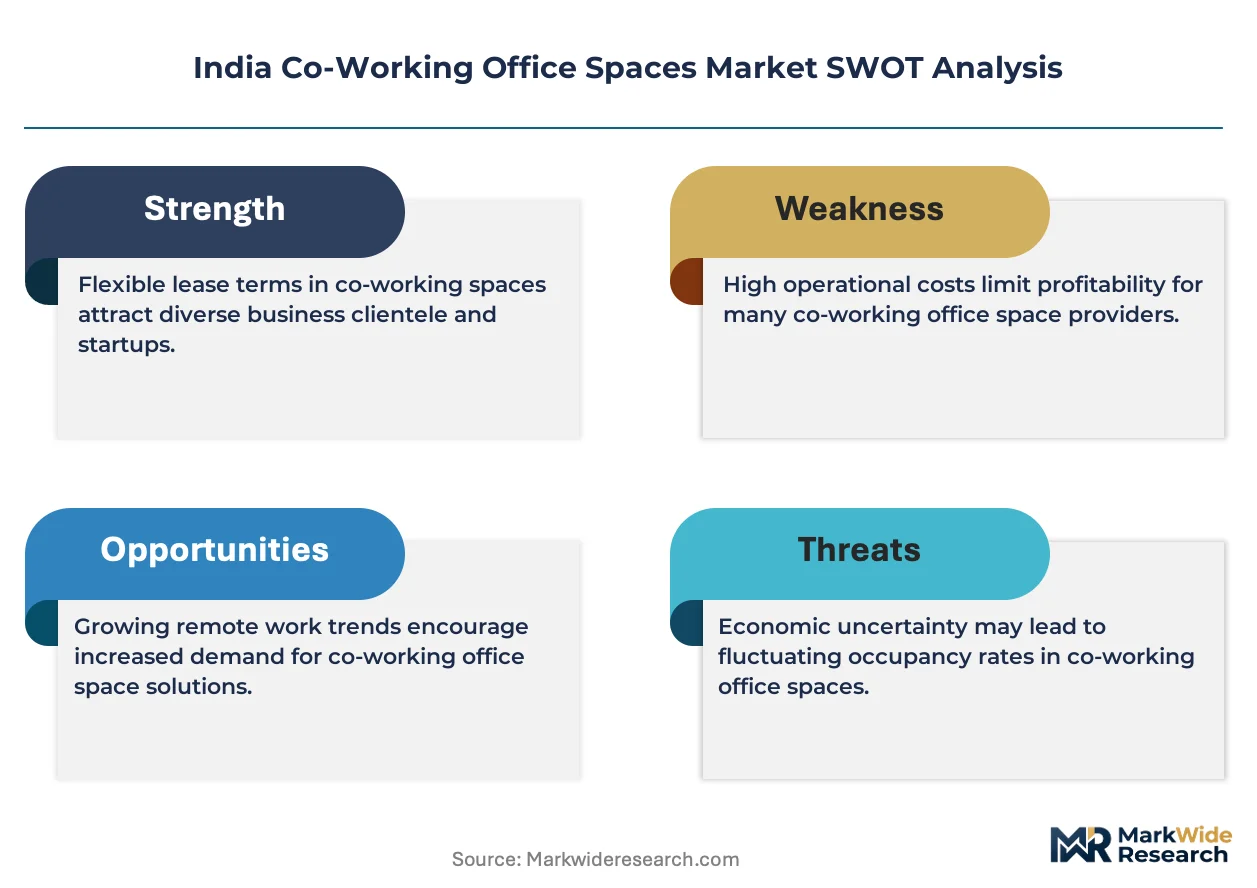
Margin tightening in dedicated desk tiers reflects IT/ITES procurement teams specifying outcome-based contracts with bandwidth SLAs and biometric access mandates. Three-tier pricing structure across premium, standard, and economy levels separates WeWork India's design-forward positioning from Awfis's asset-light franchise penetration and Smartworks's enterprise-grade dedicated desk specialization. Cost-down pressure on private office configurations accelerates because BIS electrical safety compliance elevates fit-out thresholds. Startups sustain highest price sensitivity through pay-as-you-go models; corporates exhibit lowest sensitivity where compliance documentation filters informal competitors.
Supply Chain Analysis
Direct-to-corporate channels handle hyperscale IT/ITES demand in Bengaluru's ORR corridor and Hyderabad's HITEC City, while franchise partnerships distribute supply into Jaipur, Indore, and Kochi. Geographic supply concentration centers on Maharashtra, Karnataka, and Telangana for Grade A commercial conversions. Raw material dependencies include fiber-optic bandwidth infrastructure, biometric access hardware, and fire suppression systems. Single-source vulnerability in municipal zoning clearances strains expansion timelines. Distribution runs through asset-light partnership structures for Tier-2 penetration alongside direct balance-sheet deployment in premium corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over compliance-ready infrastructure and municipal zoning relationships determines contract flow. Operators pursuing upstream integration into property management platforms and downstream integration into enterprise IT service bundling capture pricing power.
For Market Incumbents: Cement multi-floor dedicated desk relationships with IT/ITES procurement teams through RERA-compliant documentation protocols that filter informal competitors. Deepen captive supply of bandwidth infrastructure via direct ISP partnerships to defend against margin compression from enterprise SLA demands. Expand footprint in Hyderabad and Chennai electronics manufacturing clusters before PLI scheme saturation elevates rent premiums. For New Entrants and Emerging Players: Municipal zoning relaxations under the Smart Cities Mission in Tier-2 cities open a window for franchise-led penetration without direct capital deployment. Target Jaipur, Indore, and Kochi where regional IT services firms remain underserved by asset-heavy operators. Pursue virtual office service models as the most penetrable entry point, enabling market presence before physical center buildout. For Investors and Strategic Acquirers: The window for entry favors asset-light franchise platforms with standardized documentation protocols and rapid deployment capabilities. Long-term viability hinges on operators capturing enterprise-grade contracts with compliance moats rather than transaction-heavy startup segments. Monitor municipal corporation enforcement actions against non-RERA-compliant operators as the inflection indicator for sector consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Franchise Network Expansion | Asset-light structures enable Tier-2 penetration without balance-sheet property concentration in Kochi and Indore. |
| Compliance Infrastructure Investment | BIS electrical safety and CDSCO workplace health certification filters unbranded competitors from enterprise contracts. |
| Enterprise SLA Structuring | Outcome-based contracts with bandwidth consistency mandates displace traditional lease negotiations in Bengaluru. |
| Smart Cities Zoning Alignment | Municipal relaxations for commercial-to-co-working conversions accelerate center launches in Hyderabad and Mumbai. |
| Vertical Integration into Bandwidth | Direct ISP partnerships reduce latency exposure and capture margin from 100 Mbps+ enterprise specifications. |
Research Methodology
Multi-period observation of seat absorption rates, lease term compression, and municipal zoning enforcement anchored the trend analysis, supplemented by interviews with facility operators, IT/ITES procurement managers, commercial real estate developers, and municipal planning officers. Primary fieldwork combined with secondary validation from state RERA registration databases, BIS standards documentation, Smart Cities Mission progress reports, and CDSCO workplace health guidelines. Bottom-up center-level capacity tracking and top-down state-level commercial absorption data provided triangulation across data sources.
Segment-weighting across space type, customer segment, facility positioning, and service model dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points and procurement pattern shifts. Industry-specific forecast inputs included PLI scheme disbursement timelines for electronics manufacturing clusters and municipal corporation zoning relaxation schedules.
The model assumes a particular technology adoption path for IoT-enabled occupancy analytics and dynamic pricing algorithms; alternative pathways for workspace automation would alter the outlook if enterprise clients delay smart infrastructure procurement. Forecasts reflect assumptions about IT/ITES headcount expansion, municipal zoning enforcement consistency, and bandwidth infrastructure deployment rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
North America Office Real Estate Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
France Office Real Estate Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market