
 Germany Office Real Estate Market | 2026-2036
Germany Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Office Real Estate Market Foresight
Premium-grade specification is collapsing the traditional A-Class versus B-Class boundary as tenants demand unified digital infrastructure, wellness certifications, and carbon-neutral operations in a single lease structure. Vonovia SE anchors its portfolio through in-house property management platforms that reduce operating cost variance across multi-city holdings. CBRE competes by embedding energy analytics into its tenant advisory services, while LEG Immobilien specializes in workforce housing-adjacent office clusters that capture commuter-driven demand in secondary cities.
Germany office real estate comprises purpose-built commercial structures designed for administrative, professional, and knowledge-based work, typically engineered to DIN 18599 energy performance standards with floor plates exceeding 500 square meters and technical installations supporting dense IT cabling and climate control redundancy. The primary commercial purpose centers on generating rental yield through long-term tenant contracts while preserving capital value via locational scarcity and building quality depreciation management. A-Class properties command the deepest margin pools as institutional capital chases income stability, yet Co-Working Spaces represent the fastest-growing demand channel as corporate occupiers seek balance-sheet flexibility without sacrificing brand-address prestige. Business Parks retain structural importance in peripheral locations where land scarcity pressures remain subdued and parking ratios accommodate hybrid-commuting patterns.
KBA building codes, the German Building Energy Act, and EU taxonomy disclosure requirements under CSRD collectively reshape development feasibility by mandating operational carbon thresholds and embodied-carbon reporting before financing clearance. These frameworks compress returns on obsolete stock while accelerating capital flows toward redevelopment and certified new-build pipelines. Stakeholders must monitor regulatory calibration cycles and green financing cost spreads to time asset rotation decisions effectively.
Market Dynamics
The German Building Energy Act compresses investment timelines for existing stock while technology tenants in Berlin and Munich accelerate specification demands beyond traditional grade boundaries.
Growth Catalysts
- Banking sector consolidation:Frankfurt's financial district absorbs expanded floorplate requirements as institutions centralize operations. Premium lease structures capture yield compression from scarce A-Class supply.
- CSRD disclosure mandates:EU taxonomy alignment accelerates capital flows toward certified new-build pipelines. Green financing cost spreads reward early compliance.
- Hybrid work infrastructure:Dense IT cabling and climate redundancy specifications attract technology occupiers seeking operational resilience. Business Parks accommodate parking ratios for distributed commuting patterns.
Market Restraints
- Embodied-carbon reporting thresholds:EU taxonomy requirements delay financing clearance for redevelopment projects. Pre-construction compliance extends project timelines.
- Secondary city land scarcity:Peripheral locations face subdued development pressure. Workforce housing-adjacent clusters concentrate in specific commuter corridors.
- Operating cost variance:Multi-city holdings require standardized property management platforms to stabilize margins. Unintegrated portfolios face competitive disadvantage.
Strategic Opportunities
- HafenCity corridor expansion:Hamburg's waterfront regeneration creates certified office clusters with integrated wellness specifications. Mixed-use zoning permits flexible lease structures.
- Co-Working Space penetration:Corporate occupiers seek balance-sheet flexibility without sacrificing brand-address prestige. Operator consolidation creates white space for institutional-backed platforms.
- DIN 18599 retrofit acceleration:Energy performance standard upgrades unlock green financing for obsolete stock. Technical installations supporting dense IT cabling command rental premiums.
Industry Challenges
- Certification timeline compression:KBA building codes and German Building Energy Act cycles require synchronized compliance. Misaligned upgrade schedules strand capital in non-compliant assets.
- Carbon-neutral operations integration:Unified digital infrastructure, wellness certifications, and net-zero mandates must coexist within single lease structures. Tenant advisory services require embedded energy analytics capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Office Real Estate Market |
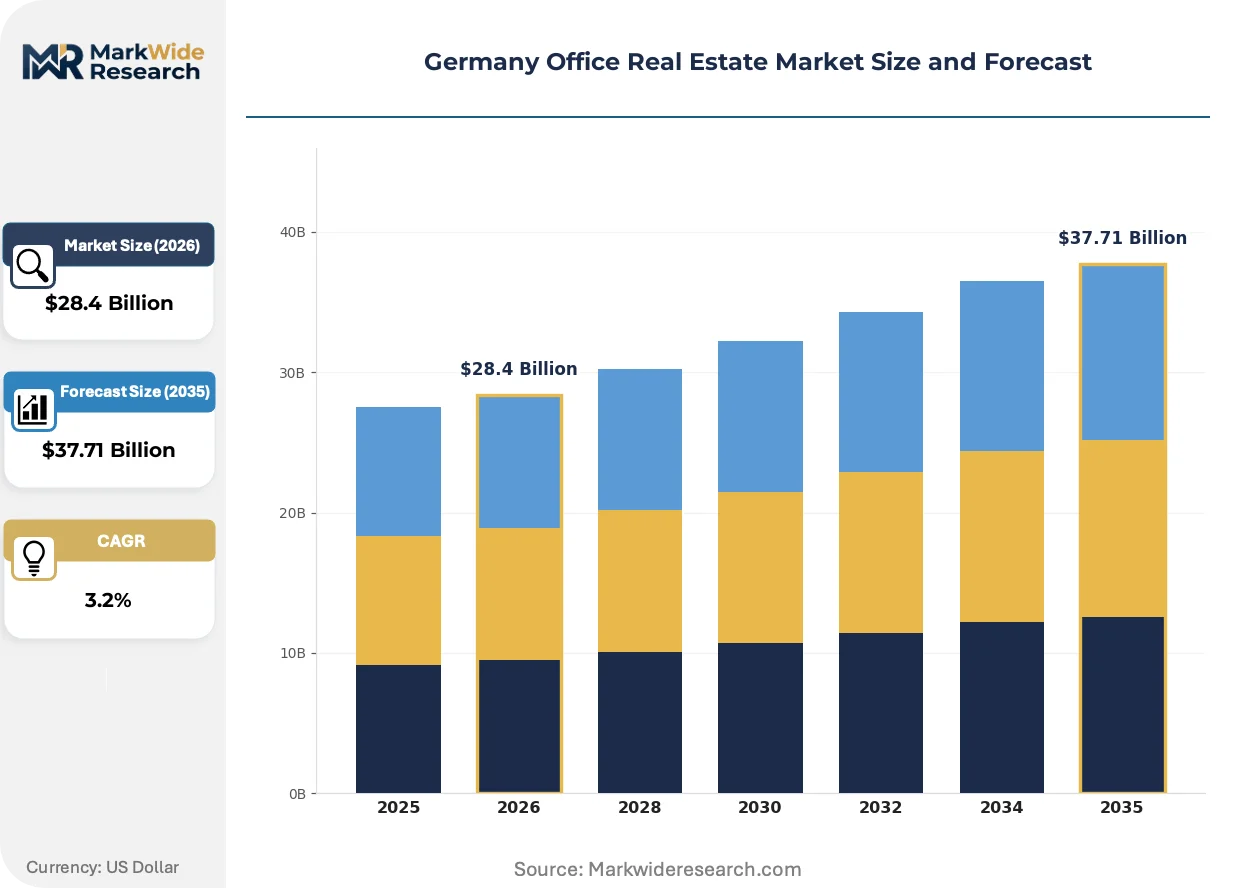
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $37.71 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: A-Class, B-Class, Co-Working Spaces, Business Parks Occupancy Status: Vacant, Occupied, Under Development, Redeveloped Lease Type: Short-Term, Long-Term, Fixed-Term, Flexible Investment Type: Direct Purchase, REITs, Joint Ventures, Fund Investments |
| Companies Covered | Savills, Colliers, CBRE, Vonovia SE, BNP Paribas Real Estate, Jones Lang LaSalle IP, Knight Frank, LEG Immobilien, Cushman & Wakefield, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Office Real Estate Market Shifts & Advancements
Specification convergence and regulatory disclosure requirements are collapsing traditional asset classifications while redistributing competitive advantage toward integrated service capabilities.
Smart building management systems is fragmenting control architectures across German office stock. Technology tenants in Munich and Berlin demand API-accessible infrastructure that permits custom climate and security configurations. Traditional facilities management contracts compress as occupiers seek direct system integration.
CSRD mandates under EU taxonomy disclosure requirements reshape development feasibility by mandating operational carbon thresholds before financing clearance. German lenders now require embodied-carbon reporting for construction loans. Redevelopment pipelines accelerate as obsolete stock faces yield compression from compliance gaps.
Corporate occupiers now unbundle long-term lease commitments into flexible term structures that preserve brand-address prestige. Co-Working Space operators capture this demand rotation by offering certified infrastructure without capital deployment. Frankfurt's banking district and Hamburg's HafenCity corridor exhibit the fastest adoption of hybrid-tenure arrangements.
Germany Office Real Estate Market Segmentation
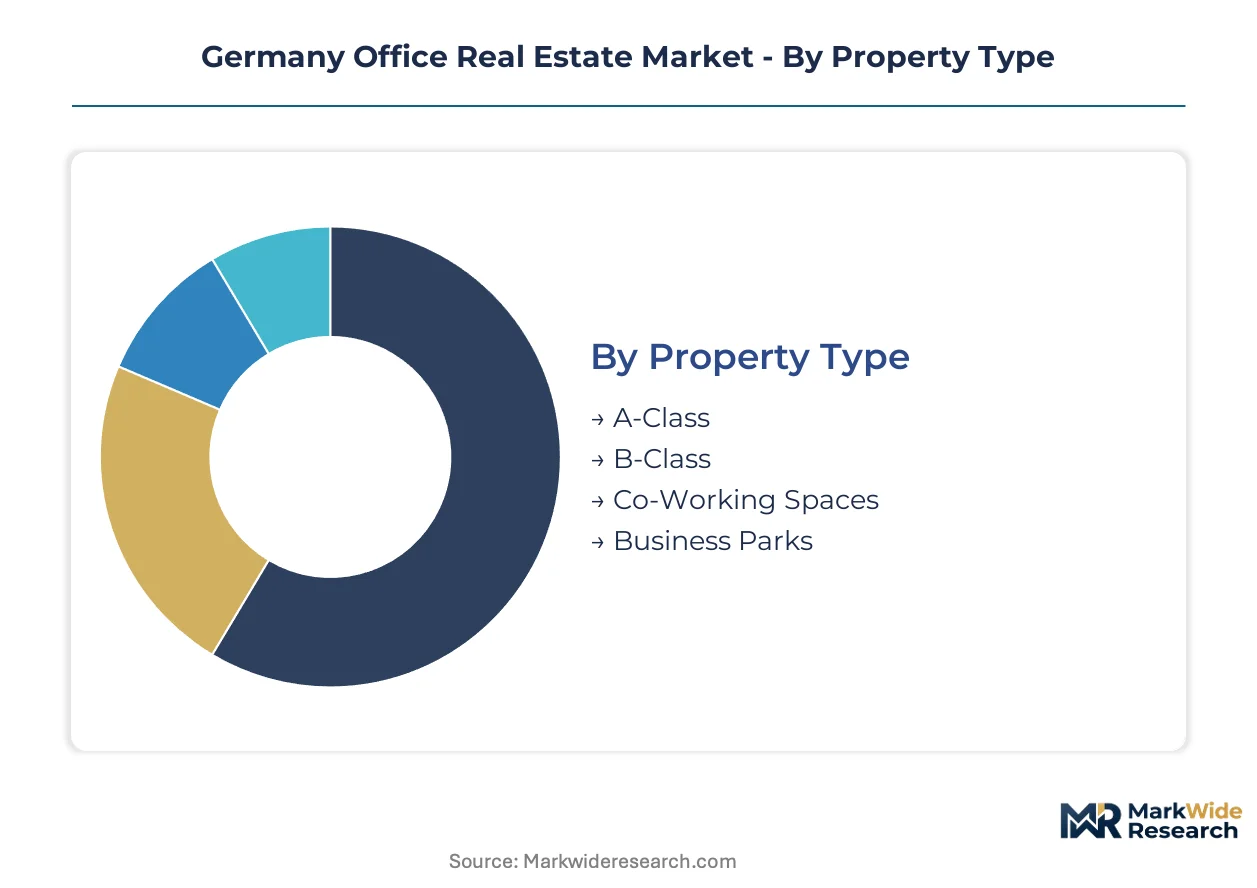
German office real estate segmentation reveals how capital allocation, tenant preferences, and regulatory pressure fragment across asset classes. Understanding these divisions exposes where yield compression concentrates and which structures face obsolescence risk under the German Building Energy Act.
Property Type:
Co-Working Spaces exert the strongest substitution pressure on traditional lease structures as corporate occupiers prioritize balance-sheet flexibility over fixed commitments.
- A-Class:Premium-grade assets engineered to DIN 18599 standards with floor plates exceeding 500 square meters, technical redundancy for dense IT cabling, and integrated wellness certifications. Frankfurt's banking district concentrates institutional capital chasing income stability through scarcity-driven yield compression.
- Co-Working Spaces:Operator-managed environments offering certified infrastructure without tenant capital deployment, capturing corporate demand for brand-address prestige without long-term liability. Berlin and Munich technology firms drive fastest adoption of hybrid-tenure arrangements.
- B-Class:Secondary stock facing accelerated obsolescence under energy efficiency mandates, requiring substantial retrofit investment to maintain financing access.
- Business Parks:Peripheral locations with subdued land scarcity pressure and parking ratios accommodating hybrid-commuting patterns across secondary city corridors.
A-Class properties anchor the volume base while Co-Working Spaces gain share at the steepest rate.
Occupancy Status:
Cost tier stratification separates income-generating assets from capital-intensive development pipelines facing extended compliance timelines.
- Occupied:Stabilized assets with contracted rental streams, where German Building Energy Act upgrade schedules must synchronize with lease rollover windows to prevent tenant disruption.
- Under Development:New-build pipelines requiring embodied-carbon reporting and operational carbon threshold certification before financing clearance under EU taxonomy requirements.
- Vacant:Non-revenue-producing stock exposed to immediate yield compression, particularly B-Class assets in secondary locations with limited retrofit economics.
- Redeveloped:Obsolete stock repositioned through DIN 18599-compliant technical installations that command rental premiums from technology occupiers seeking climate control redundancy.
Occupied stock dominates institutional portfolios while Under Development assets face the steepest expansion trajectory as green financing cost spreads reward certified pipelines.
Lease Type:
Application-specific demand patterns separate corporate headquarters requirements from project-based or growth-phase tenant needs.
- Long-Term:Traditional ten-to-fifteen-year structures preserving capital value through income stability, concentrated in Frankfurt's financial district where banking institutions centralize operations.
- Flexible:Term structures unbundling commitment length from infrastructure quality, expanding most quickly in Hamburg's HafenCity corridor where mixed-use zoning permits adaptive lease configurations.
- Short-Term:Interim arrangements occupying transitional stock or accommodating project-based demand with limited capital deployment tolerance.
- Fixed-Term:Predetermined duration contracts with standardized escalation clauses, prevalent in established business parks with stable tenant bases.
Long-Term leases anchor income stability while Flexible structures climb the fastest as corporate occupiers reconfigure balance-sheet treatment of real estate liabilities.
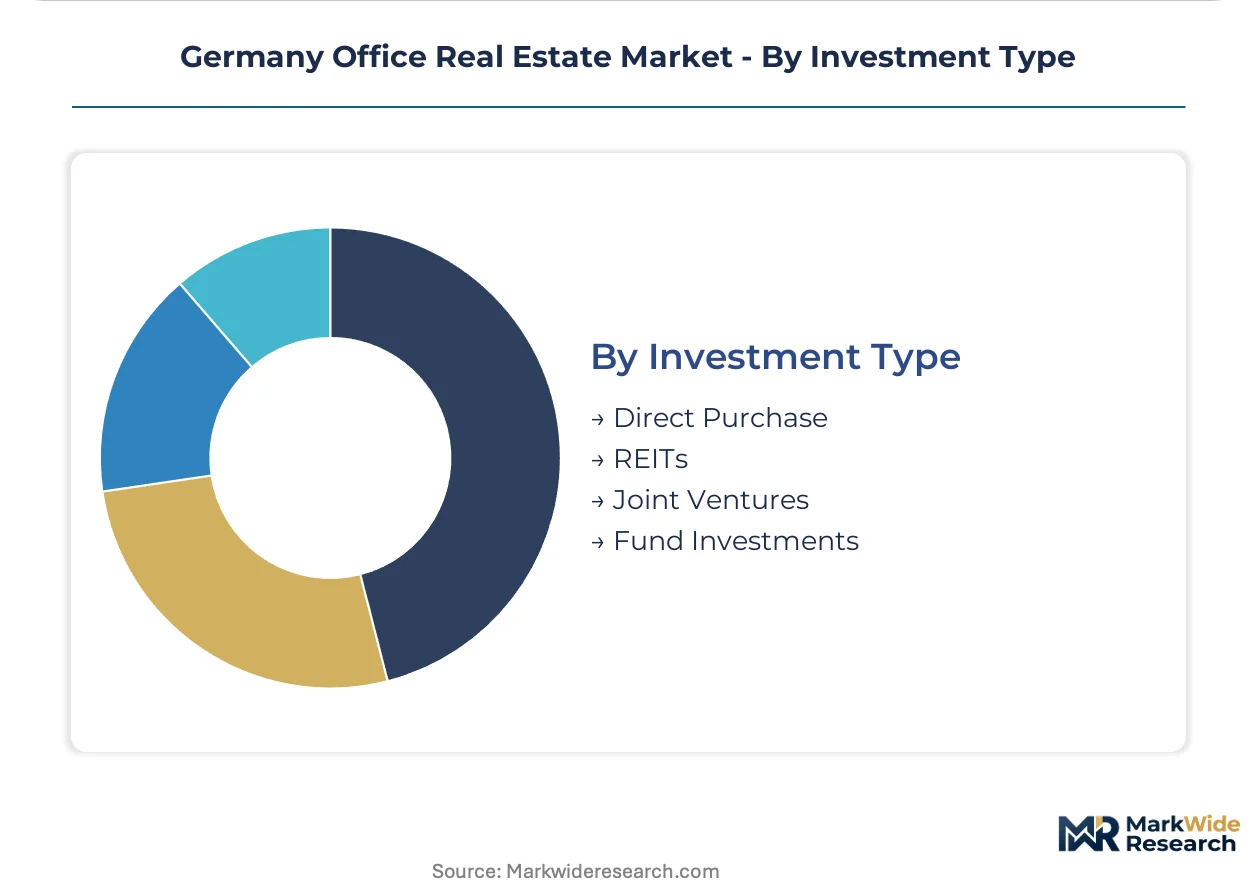
Investment Type:
Customer-type differentiation separates direct operational control from passive exposure to German office yield curves.
- Direct Purchase:Single-asset or portfolio acquisitions granting operational control over property management platforms and energy upgrade scheduling, favored by domestic institutional investors with multi-city integration capabilities.
- REITs:Listed vehicles providing liquidity and diversified exposure to premium-grade stock, with regulatory disclosure requirements aligning with CSRD mandates for transparency on carbon performance.
- Joint Ventures:Partnership structures distributing development risk and capital requirements, common in HafenCity corridor regeneration where mixed-use complexity demands specialized expertise.
- Fund Investments:Commingled vehicles accessing scale advantages in due diligence and green financing negotiation, targeting certified new-build pipelines with early EU taxonomy compliance.
Direct Purchase vehicles dominate volume allocation while Fund Investments expand most quickly as institutional capital seeks distributed exposure to compliant development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional capital concentrates in Germany's seven federal economic zones, each shaped by distinct industry compositions and regulatory timelines under the German Building Energy Act. Regional performance diverges based on technology tenant density, banking sector consolidation, and green financing accessibility.
Bavaria
Munich anchors technology tenant expansion with dense IT cabling specifications and climate redundancy requirements. The KBA building codes enforce DIN 18599 retrofit schedules across existing stock. The Munich metropolitan corridor exhibits fastest adoption of API-accessible smart building systems as occupiers demand direct infrastructure control.
Hesse
Frankfurt's banking district absorbs expanded floorplate requirements from consolidating financial institutions. EU taxonomy disclosure requirements under CSRD accelerate capital flows toward certified new-build pipelines in the Mainhattan cluster. Long-term lease structures preserve income stability through scarcity-driven yield compression on A-Class supply.
Hamburg
HafenCity corridor regeneration creates mixed-use office clusters with integrated wellness certifications and flexible lease configurations. The German Building Energy Act mandates operational carbon thresholds before financing clearance for waterfront redevelopment. Hamburg's port-adjacent business parks accommodate hybrid-commuting patterns with elevated parking ratios.
North Rhine-Westphalia
Düsseldorf and Cologne office markets face compressed investment timelines for B-Class stock under efficiency upgrade mandates. LEG Immobilien specializes in workforce housing-adjacent clusters capturing commuter-driven demand across the Rhine-Ruhr metropolitan region. Secondary cities exhibit subdued land scarcity pressure compared to core western markets.
Berlin-Brandenburg
Berlin technology firms accelerate specification demands beyond traditional A-Class versus B-Class boundaries. Co-Working Space operators capture corporate demand for brand-address prestige without long-term capital deployment. The capital region exhibits steepest adoption of hybrid-tenure arrangements as balance-sheet flexibility priorities reshape lease structures.
Germany Office Real Estate Market Competitive Landscape
Concentration sits with integrated property management platforms and tenant advisory specialists that embed energy analytics into service delivery. The market structure tiers between scale-driven residential-office hybrids and transaction-focused international brokerages. Three archetypes dominate: in-house platform operators reducing operating cost variance, advisory services layering CSRD compliance tools, and flexible workspace providers capturing tenure unbundling demand. Competitive moves center on portfolio diversification into certified new-build pipelines and strategic partnerships for green financing access.
Among international brokerage networks, Savills, Colliers, and CBRE occupy positions as advisory archetypes embedding regulatory compliance capabilities. Vonovia SE exemplifies the integrated platform model with multi-city holdings stabilized through proprietary management systems. LEG Immobilien represents workforce housing-adjacent specialization targeting commuter corridors in secondary cities. These three anchors illustrate how competitive advantage redistributes toward service integration rather than pure transaction scale.
| Leading Market Players |
|---|
| Savills |
| Colliers |
| CBRE |
| Vonovia SE |
| BNP Paribas Real Estate |
| Jones Lang LaSalle IP |
| Knight Frank |
| LEG Immobilien |
| Cushman & Wakefield |
| Others |
Supply & Pricing Matrix
Ninety-day construction material lead times for steel and concrete frame assemblies compress developer pricing power across German metropolitan corridors, as supply bottlenecks interact with KBA building code compliance schedules to force early procurement commitments that lock in cost bases before tenant lease negotiations conclude.
Pricing Analysis
The German Building Energy Act dictates the pricing tier structure across office stock, separating DIN 18599-certified assets from obsolete B-Class properties facing retrofit cost burdens. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and wellness specification bundling. Cost compression in secondary city B-Class stock is intensifying because financing access narrows for non-compliant assets. Corporate technology tenants in Berlin and Munich exhibit lowest price sensitivity, prioritizing API-accessible infrastructure over rental rate minimization.
Supply Chain Analysis
Port congestion at Hamburg and Rotterdam container terminals elevates inbound logistics costs for HVAC equipment and smart building control systems sourced from China and South Korea. German development pipelines draw from domestic steel producers, Polish concrete suppliers, and Dutch glazing manufacturers for facade assemblies. Single-source vulnerability concentrates in semiconductor-dependent building automation controllers. Distribution runs through regional contractor networks with direct-to-site delivery coordination managed by general contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
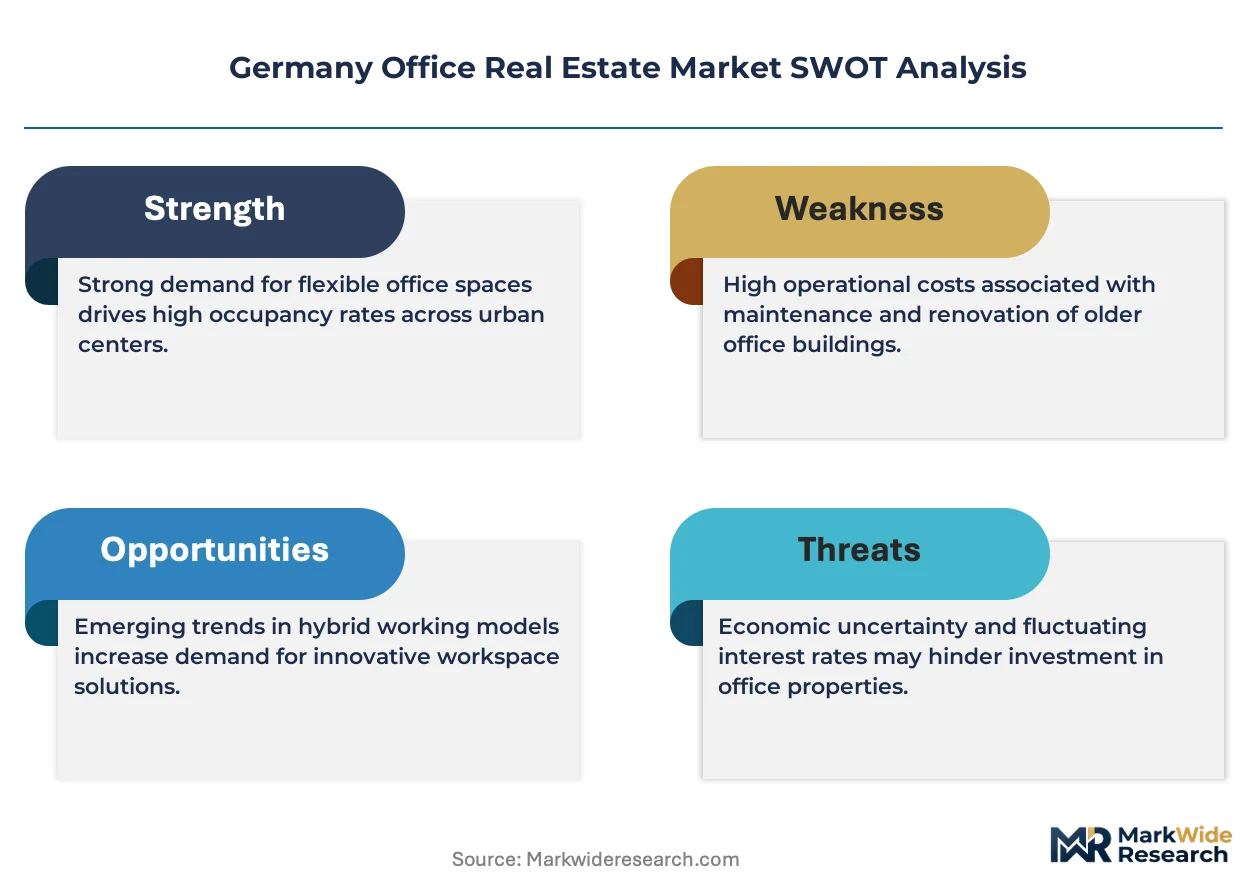
The German office real estate sector faces high-growth disruption as CSRD disclosure mandates under EU taxonomy requirements reclassify investable assets based on embodied-carbon reporting thresholds.
For Market Incumbents: Secure green financing relationships before cost spreads widen for compliant new-build pipelines. Defend portfolio positioning through accelerated DIN 18599 retrofit scheduling that synchronizes with lease rollover windows. Vertical integration into in-house property management platforms reduces operating cost variance across multi-city holdings against emerging operator competition. For New Entrants and Emerging Players: EU taxonomy fast-track certification pathways open white space in Hamburg's HafenCity corridor regeneration and Berlin-Brandenburg technology corridors. Co-Working Space penetration remains most penetrable as corporate occupiers unbundle long-term commitments. Go-to-market execution should emphasize balance-sheet flexibility messaging to CFO audiences at growth-phase technology firms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across redevelopment pipelines as embodied-carbon reporting extends project timelines. Long-term viability over the coming decade rests on early compliance positioning rather than yield chasing in obsolete stock. Acquisition targeting should prioritize stabilized A-Class assets with synchronized upgrade schedules. The signal to monitor is green financing cost spread divergence between certified and non-certified pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| DIN 18599 Retrofit Acceleration | Unlocks green financing access for obsolete stock while commanding rental premiums from technology occupiers. |
| Smart Building Platform Integration | API-accessible infrastructure attracts Munich and Berlin tenants seeking direct climate and security control. |
| CSRD Compliance Tool Development | Embedded energy analytics capabilities differentiate tenant advisory services from transaction-focused competitors. |
| Workforce Housing-Adjacent Cluster Expansion | Captures commuter-driven demand across Rhine-Ruhr and secondary city corridors with subdued land scarcity. |
| Flexible Lease Structure Innovation | Hybrid-tenure arrangements in Frankfurt and Hamburg preserve brand-address prestige without balance-sheet liability. |
Research Methodology
Cross-validation between property management platform operators and green financing specialists anchors the qualitative findings on compliance cost trajectories. Primary interviews with portfolio asset managers, development project directors, tenant advisory brokers, and sustainability certification consultants combined with secondary validation from KBA regulatory filings, EU taxonomy disclosure databases, German federal construction statistics, and institutional investor portfolio reports. Bottom-up lease transaction analysis and top-down macroeconomic scenario modeling provide triangulation.
Sensitivity analysis around regulatory calibration cycles and financing cost spread assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include property grade tier, occupancy status, lease structure type, investment vehicle format, and regional regulatory cluster. CAGRs derive from lease rollover timing distributions and development pipeline absorption rates. Forecast inputs incorporate KBA building code amendment schedules and EU Green Deal implementation timelines.
Underlying assumptions cover stable regulatory enforcement intensity and continued institutional capital allocation to German real estate, with deviation risk concentrated in accelerated embodied-carbon threshold tightening or green financing subsidy withdrawal. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Australia Flexible Office Space Market