
 Spain Office Real Estate Market | 2026-2036
Spain Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Office Real Estate Market Analytics
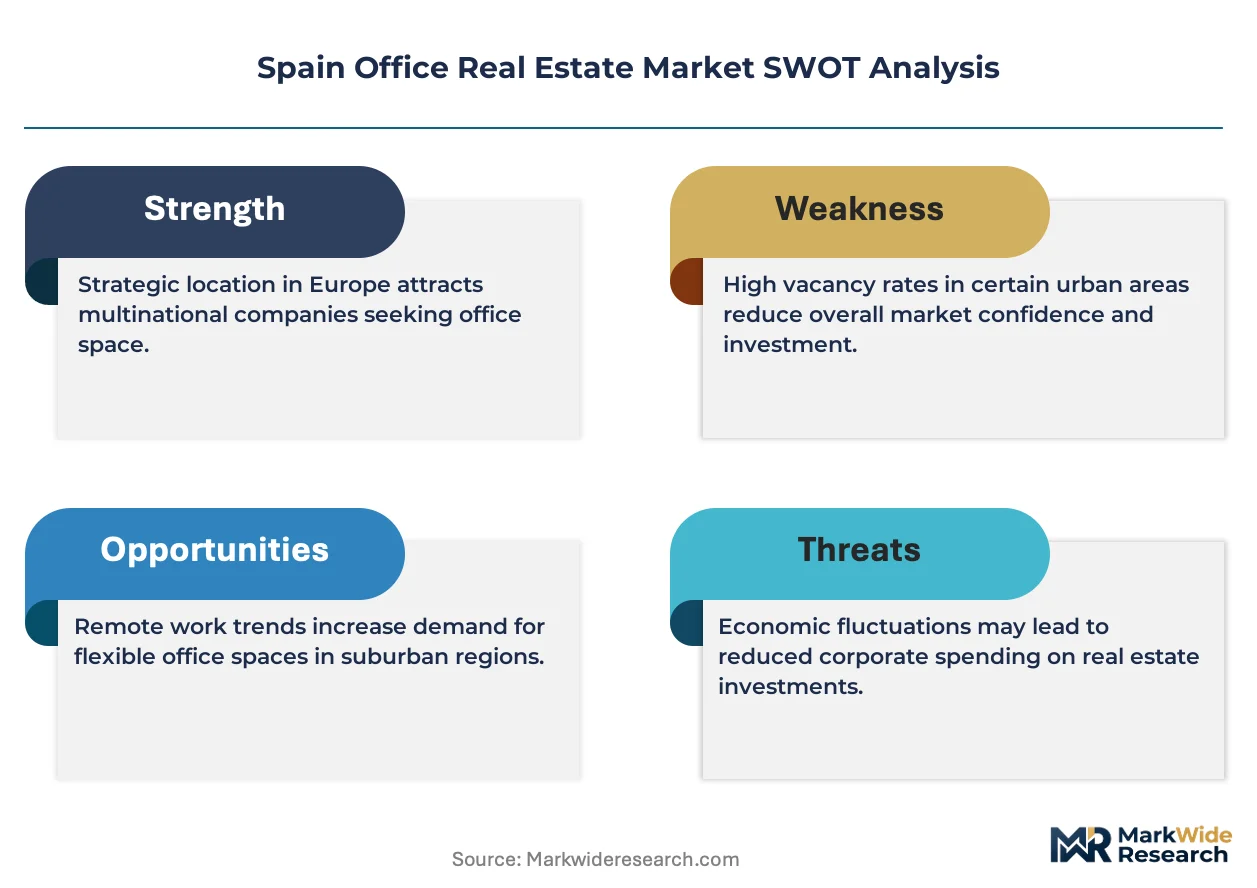
Institutional capital deployment is reconfiguring how prime office stock reaches end users in Spain. Hines leverages its global platform to source trophy assets in Madrid's AZCA corridor. Acciona anchors its competitive stance through integrated development and construction capabilities. Savills differentiates via tenant advisory services that navigate complex lease restructurings.
Spain office real estate comprises purpose-built commercial structures with floor plates exceeding 500 square meters, climate control systems, and vertical transportation designed for continuous occupancy. These assets serve as operational headquarters for enterprises requiring centralized workforce coordination and client-facing infrastructure. A-Class properties command premium rents through superior specifications and location attributes, while Co-Working Spaces capture growing demand from scale-ups seeking operational flexibility without long-term capital commitment. The Facility Feature dimension shows Sustainability Certification emerging as a decisive filtering criterion for corporate occupiers.
Spain's Technical Building Code and municipal urban planning regulations in Madrid and Barcelona govern energy performance standards and zoning permissions for new office development. The national regulator and local planning authorities collectively shape permissible density, height restrictions, and retrofit obligations that determine project viability. Stakeholders must monitor how evolving environmental compliance thresholds affect obsolescence risk across Spain's existing stock.
Market Dynamics
Spain's Technical Building Code mandates energy efficiency retrofits across existing office stock, accelerating capital deployment toward sustainability-certified assets while compressing obsolescence timelines for non-compliant buildings in Madrid and Barcelona.
Growth Catalysts
- Technology Sector Expansion:Software and fintech firms are scaling physical footprints in Madrid's AZCA corridor and Barcelona's 22@ district, generating sustained absorption of A-Class floor space.
- CSRD Alignment:The EU Corporate Sustainability Reporting Directive compels multinational tenants to prioritize LEED and BREEAM-certified premises, filtering demand toward compliant Spanish assets.
- Integrated Development Models:Construction-to-asset-management pipelines are compressing project delivery timelines and capturing value that previously leaked to third-party contractors.
Market Restraints
- Construction Cost Volatility:Steel and concrete input prices fluctuate with energy markets, eroding development pro forma certainty for speculative office projects.
- Financing Concentration:Domestic banks dominate commercial real estate lending, creating refinancing vulnerability when monetary policy tightens.
- Zoning Rigidity:Barcelona's municipal urban planning regulations restrict height and density in prime submarkets, capping supply response to tenant demand.
Strategic Opportunities
- Secondary City Activation:Valencia and Bilbao office markets remain underpenetrated relative to Madrid and Barcelona, offering yield premiums for early institutional positioning.
- Adaptive Reuse Pipeline:Obsolete retail and industrial assets in peripheral Madrid zones present conversion opportunities to flexible office product.
- Green Bond Financing:EU Taxonomy-aligned debt instruments reduce cost of capital for developments meeting stringent energy performance thresholds.
Industry Challenges
- Technical Skill Scarcity:Deep energy retrofit execution requires building systems engineers and commissioning agents that Spain's construction labor pool currently lacks.
- Certification Timeline Compression:BREEAM Outstanding and LEED Platinum documentation cycles extend lease-up schedules, straining developer carry costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Office Real Estate Market |
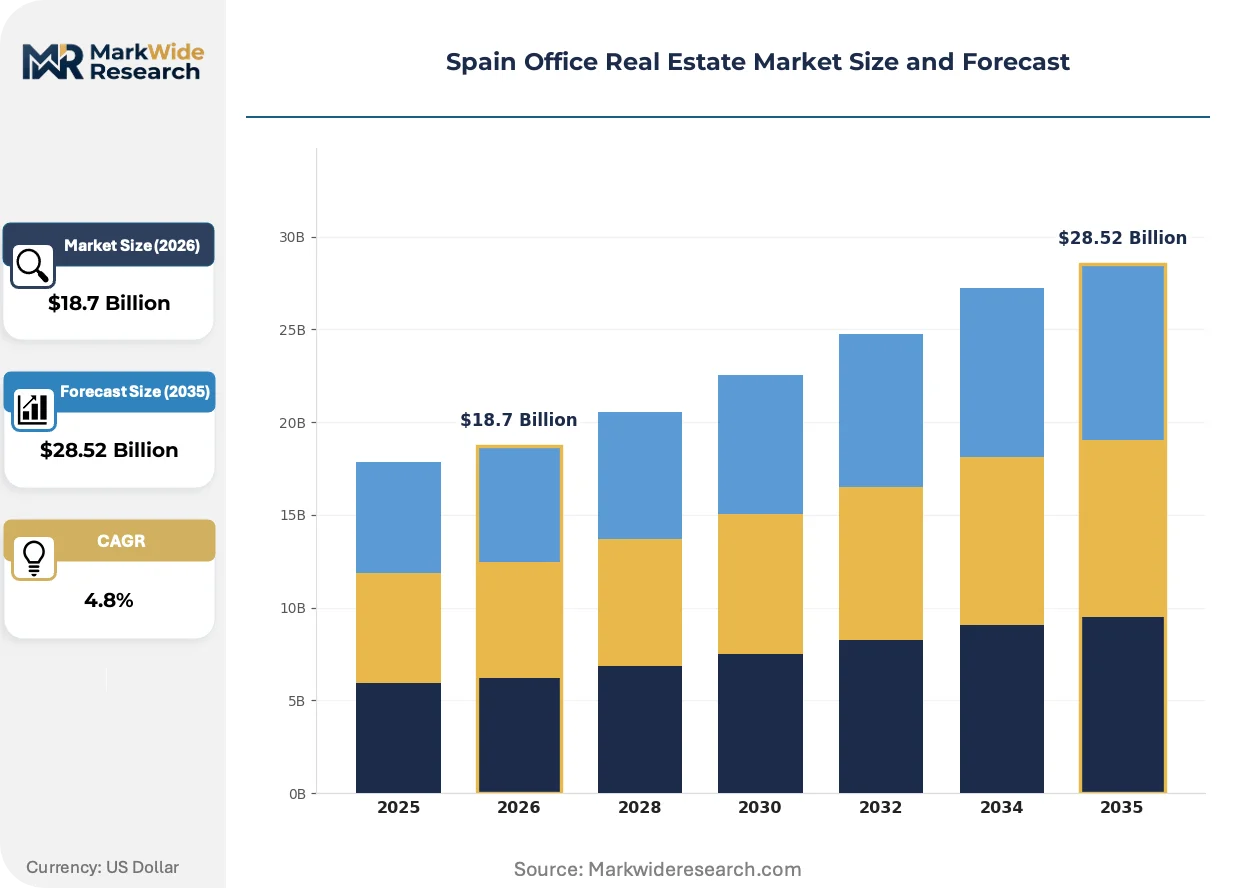
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: A-Class, B-Class, Co-Working Spaces, Serviced Offices End User: Corporations, Startups, Government Agencies, Nonprofits Lease Type: Long-Term Leases, Short-Term Leases, Flex Leases, Subleases Facility Feature: Smart Building Technology, Sustainability Certification, High-Speed Internet, Parking Availability |
| Companies Covered | Acciona, INVERTICA-IRELS, Hines, NuvoBarcelona, Savills, Neinor Homes, Realia, Grupo Lobe, AQ Acentor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Office Real Estate Market Evolving Landscape
Building operations are converging with data infrastructure, rewiring how landlords monetize space and how tenants evaluate total occupancy costs across Spanish office markets.
Smart building management systems are digitizing energy consumption patterns, HVAC optimization, and predictive maintenance protocols. Institutional landlords in Madrid's CBD are deploying these platforms to reduce operating expenditure and justify rent premiums. The technology stack is digitizing traditional facility management into measurable service level agreements.
Spain's Technical Building Code updates are tightening thermal envelope and renewable energy requirements for new construction and major renovations. The regulatory pressure is accelerating obsolescence of 1990s-vintage stock and redirecting development capital toward net-zero-ready specifications. Madrid and Barcelona planning authorities are enforcing these standards through permitting delays for non-compliant submissions.
Tenants are unbundling long-term lease commitments in favor of managed space contracts with term flexibility and expansion options. Scale-ups and satellite offices of multinational corporations are driving this demand rotation away from conventional ten-year agreements. Barcelona's 22@ innovation district exhibits the most pronounced shift toward service-based occupancy models.
Spain Office Real Estate Market Segmentation
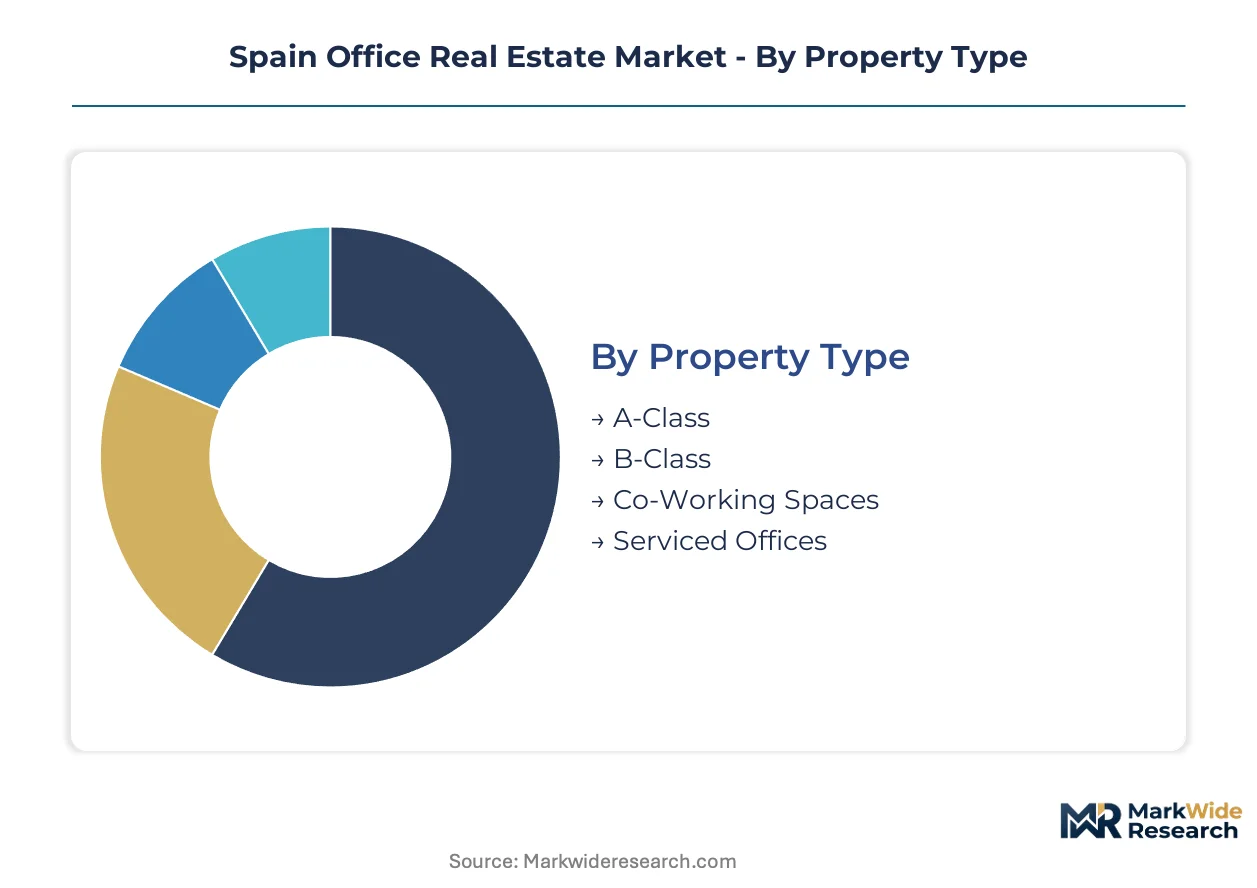
Segmentation in Spain's office market reveals how capital allocation and tenant procurement diverge across asset quality, occupier sophistication, and contract structures. Understanding these fault lines exposes where rent premiums concentrate and where obsolescence risk accumulates.
Property Type:
Cost tier structures tenant expectations and investor underwriting across Madrid and Barcelona submarkets.
- A-Class:Trophy assets deliver floor plates exceeding 1,500 square meters, raised flooring systems, and 24/7 climate control. Demand concentrates in Madrid's AZCA corridor from technology and financial services tenants seeking ESG-compliant headquarters space.
- B-Class:Secondary stock built between 1985 and 2005 lacks modern MEP infrastructure and faces accelerated obsolescence under Spain's Technical Building Code retrofit mandates. Value-add investors target these for repositioning in peripheral Barcelona zones.
- Co-Working Spaces:Managed environments with hot-desking protocols and month-to-month terms capture scale-ups in Barcelona's 22@ district.
- Serviced Offices:Fully fitted suites with reception and IT support serve project-based teams and market entry scenarios.
A-Class commands the established base. The steepest expansion runs through Co-Working Spaces.
End User:
Customer type determines lease duration, fit-out investment, and sensitivity to location attributes.
- Corporations:Multinational headquarters and regional back-office operations drive bulk leasing of contiguous floor plates. Madrid's CBD absorbs these requirements from banking and professional services sectors prioritizing metro connectivity and prestige address.
- Startups:Venture-backed technology firms prioritize expansion rights and short commitment horizons over specification grades. Barcelona's innovation corridor captures this cohort through flexible lease structures.
- Government Agencies:Public administration leases follow procurement frameworks with extended due diligence cycles and rent indexing clauses.
- Nonprofits:Mission-driven organizations optimize for cost containment in peripheral submarkets with transit access.
Corporations anchor the revenue base. Startups are climbing the fastest.
Lease Type:
Contract maturity shapes landlord cash flow stability and tenant balance sheet treatment.
- Long-Term Leases:Conventional ten-to-fifteen-year agreements with stepped rent escalations and tenant improvement allowances. Institutional landlords in Madrid's prime submarkets favor these for securitization eligibility.
- Short-Term Leases:One-to-three-year commitments with limited landlord capex obligations serve project-based occupiers and market entrants testing location fit.
- Flex Leases:Hybrid structures with core term and expansion/contraction options accommodate workforce planning uncertainty.
- Subleases:Surplus space remarketing by primary tenants creates opportunistic availability at discounted rents.
Long-Term Leases dominate institutional portfolios. Flex Leases are gaining share fastest.
Facility Feature:
Technical specifications increasingly filter tenant shortlists and refinancing terms.
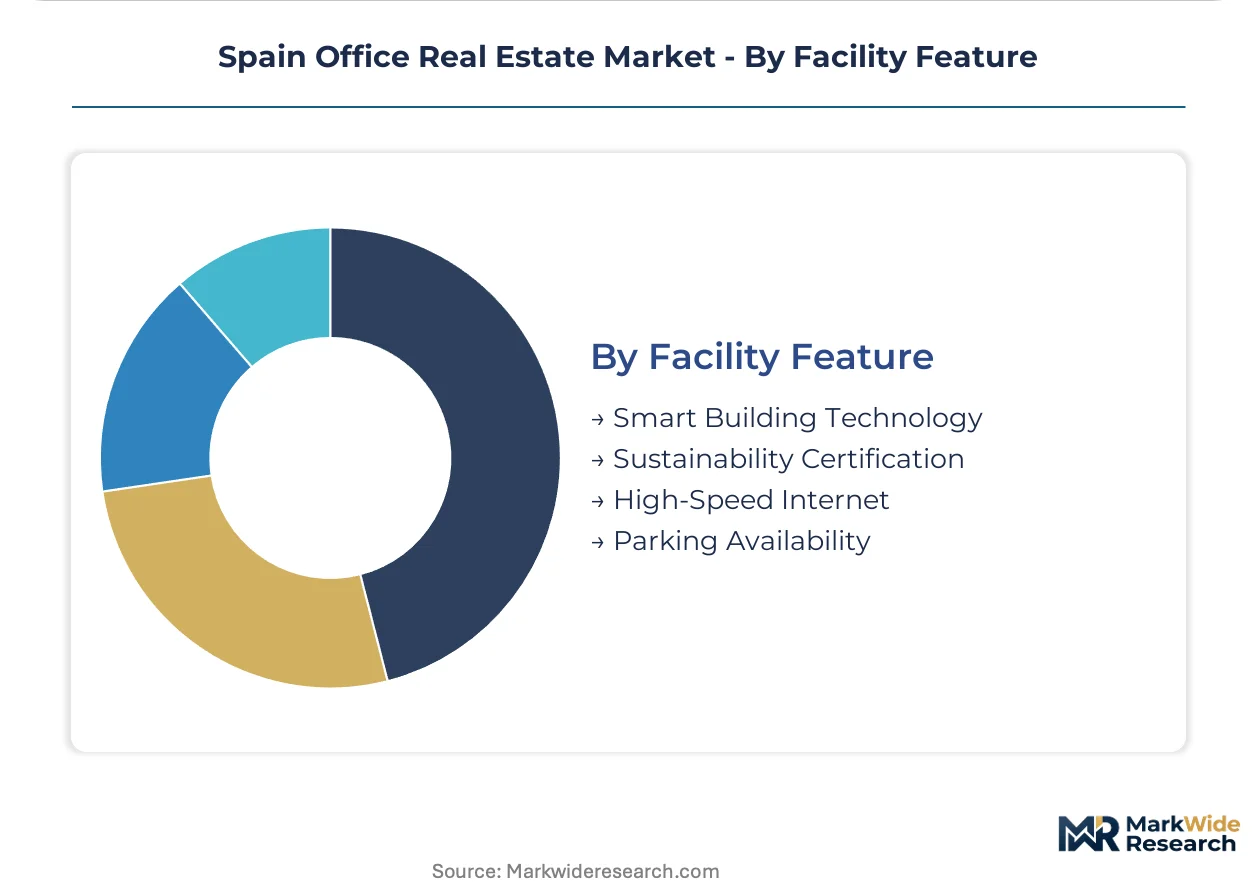
- Smart Building Technology:Integrated BMS platforms with occupancy sensors and predictive HVAC analytics reduce opex by twelve to eighteen percent. Madrid CBD landlords deploy these to justify rent premiums and attract technology sector tenants.
- Sustainability Certification:LEED Gold or BREEAM Excellent ratings satisfy CSRD-aligned corporate reporting requirements. Barcelona planning authorities fast-track permitting for developments targeting net-zero operational carbon.
- High-Speed Internet:Redundant fiber connectivity with sub-ten-millisecond latency to financial exchanges supports trading floor operations.
- Parking Availability:Underground capacity ratios of one space per 100 square meters retain relevance for suburban Madrid campuses despite metro expansion.
Sustainability Certification commands the established base. Smart Building Technology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Madrid commands rent premiums that exceed Barcelona by fifteen to twenty percent, while Valencia and Bilbao trade at yield spreads attracting early institutional positioning. This pricing-power asymmetry reflects concentration of multinational headquarters and technology sector expansion in Spain's capital.
Madrid
Technology and financial services firms drive absorption of A-Class floor space in the AZCA corridor and Cuatro Torres district. Spain's Technical Building Code enforces energy efficiency retrofits that accelerate obsolescence of 1990s-vintage stock. The CBD concentrates trophy asset development where Hines and Acciona deploy integrated development models.
Catalonia
Barcelona's 22@ innovation district captures scale-ups and fintech firms seeking flexible lease structures and ESG-compliant premises. Municipal urban planning regulations restrict height and density in prime submarkets, capping supply response. The metropolitan area leads conversion of obsolete industrial assets to flexible office product.
Basque Country
Advanced manufacturing headquarters and energy sector back-office operations sustain demand in Bilbao's Abandoibarra district. Regional planning authorities enforce strict environmental compliance thresholds for new development. The port city attracts yield-focused investors seeking exposure outside Madrid-Barcelona concentration.
Valencia
Logistics and professional services firms activate office demand in Spain's third-largest metropolitan economy. The city's national regulator and municipal planning framework permits higher-density development than Barcelona's constrained core. Ciudad de las Artes y las Ciencias anchors emerging submarket formation.
Andalusia
Tourism-related corporate functions and public administration leases support secondary market stability in Málaga and Seville. Regional government procurement frameworks extend due diligence cycles for public sector tenancies. Málaga's technology corridor exhibits nascent demand from software firms seeking cost arbitrage.
Spain Office Real Estate Market Competitive Landscape
Integrated developers and global investment platforms split the market between construction-to-asset-management pipelines and trophy asset accumulation. The competitive terrain shows moderate consolidation around vertically capable players and specialized tenant advisors. Three archetypes dominate: construction-integrated developers capturing value leakage, global platforms sourcing prime stock, and advisory specialists navigating complex restructurings. Dominant competitive moves include portfolio diversification into sustainability-certified assets and strategic partnerships securing development land.
Among construction-integrated players, Acciona anchors the development-capability archetype through in-house construction execution. Hines occupies a position representing global platform access to institutional capital deployment. Savills exemplifies the advisory-specialist tier with tenant-facing service differentiation. These three entities collectively illustrate how competitive positioning in Spanish office real estate depends on capability integration depth rather than scale alone.
| Leading Market Players |
|---|
| Acciona |
| INVERTICA-IRELS |
| Hines |
| NuvoBarcelona |
| Savills |
| Neinor Homes |
| Realia |
| Grupo Lobe |
| AQ Acentor |
| Others |
Value Network & Pricing Analysis
Port of Valencia freight corridors feed construction material costs into Madrid and Barcelona development pipelines, concentrating supply leverage among integrated developers while compressing margins for speculative builders dependent on spot procurement.
Pricing Analysis
Configured-to-order premiums for LEED Platinum and BREEAM Outstanding specifications run forty to sixty percent above standard Class A base rates. Pricing stratifies across premium, standard, and economy tiers based on sustainability certification grade and smart building technology integration. Cost compression in B-Class repositioning projects is intensifying because retrofit timelines extend under Spain's Technical Building Code mandates. Corporate occupiers with CSRD reporting obligations show least price sensitivity; scale-ups in co-working environments exhibit highest elasticity.
Supply Chain Analysis
Supplier-financing facilities from domestic construction majors extend payment terms to sixty-ninety days for steel and concrete procurement. Spain's supply chain draws from Germany, Italy, and domestic producers for MEP systems and façade components. Single-source vulnerability concentrates in specialized building automation controllers sourced from German industrial suppliers. Distribution runs through construction-integrated developers with captive project delivery capabilities and third-party general contractors serving smaller institutional investors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's office market is approaching a platform-economics inflection where building management system interoperability determines tenant stickiness and landlord pricing power.
For Market Incumbents: Insulate trophy asset positions in Madrid's AZCA corridor through backward integration into energy retrofit execution capabilities. Accelerate BREEAM Outstanding certification pipelines to preempt regulatory obsolescence timelines. Defensive consolidation should target distressed B-Class stock in peripheral Barcelona zones before municipal retrofit mandates activate. For New Entrants and Emerging Players: Pursue Valencia and Bilbao submarkets where yield premiums compensate for lower liquidity and thinner tenant depth. The most penetrable segment lies in adaptive reuse of obsolete industrial assets to flexible office product with managed space contracts. A go-to-market angle anchored in EU Taxonomy-aligned green bond financing reduces cost-of-capital disadvantage against established players. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified European real estate platforms with underperforming Spanish office exposure lacking local development capabilities. Long-term viability hinges on positioning ahead of Technical Building Code enforcement waves that will strand non-compliant stock. Monitor permitting velocity at Barcelona's municipal planning authority as an inflection indicator for supply-constrained rent growth.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Retrofit Execution Capability | Captures value leakage from third-party contractors under Technical Building Code mandates. |
| Sustainability Certification Pipeline | Accelerates lease-up velocity for CSRD-aligned corporate tenants in Madrid CBD. |
| Secondary City Geographic Expansion | Deploys capital into Valencia and Bilbao yield premiums before institutional crowding. |
| Adaptive Reuse Project Development | Converts obsolete industrial stock to flexible office product in supply-constrained Barcelona. |
| Green Bond Financing Structure | Reduces weighted average cost of capital for EU Taxonomy-aligned development pipelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with institutional asset managers, development directors at integrated construction firms, tenant advisory specialists, and municipal planning officers in Madrid and Barcelona. Secondary validation drew from Spain's Ministry of Transport and Sustainable Mobility building code filings, BREEAM and LEED certification databases, European Central Bank commercial real estate lending surveys, and municipal urban planning registries. Bottom-up project pipelines were triangulated against top-down capital deployment estimates.
Calibration against historical absorption patterns and regulatory implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include property quality tier, end-user sophistication, lease structure maturity, and facility feature integration. CAGRs were derived from rent trajectory projections and capital value appreciation assumptions. Forecast inputs incorporated energy retrofit cost curves and corporate sustainability reporting adoption rates.
Macroeconomic conditions sit as an overlay; deviation in ECB policy rates and construction input cost indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and tenant preference evolution. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Global Office Space Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market