
 Bahrain Flexible Office Space Market | 2026-2036
Bahrain Flexible Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Flexible Office Space Market Outlook
Bahrain's national green building mandate is restructuring how flexible office operators configure fit-outs and energy systems. Regus leverages its international design playbook to sustain premium positioning across Manama's commercial core. Space 340 anchors its model in localized community programming that differentiates it from standardized global competitors.
Flexible office space denotes commercial real estate configured with modular partitions, shared infrastructure, and short-term lease terms that allow tenants to scale square footage without capital expenditure on permanent build-outs. These environments integrate IT backbone redundancy, acoustic zoning, and hot-desking algorithms to serve project-based teams and satellite corporate functions. Co-working spaces lead transaction volume among office types due to their appeal to early-stage ventures, while executive suites capture higher margin per seat through bundled reception and secretarial services. The sector focus dimension shows SMEs generating the most consistent occupancy cycles, with enterprise demand expanding fastest as regional headquarters adopt hub-and-spoke models.
The Bahrain Economic Development Board and the country's national urban planning authority shape operator licensing through commercial zoning codes and foreign ownership allowances in designated investment zones. The Central Bank of Bahrain's fintech sandbox regulations indirectly stimulate demand by legitimizing startup formations that require scalable workspace. Stakeholders must monitor how municipal parking capacity constraints and fiber infrastructure parity between districts influence site selection economics.
Market Dynamics
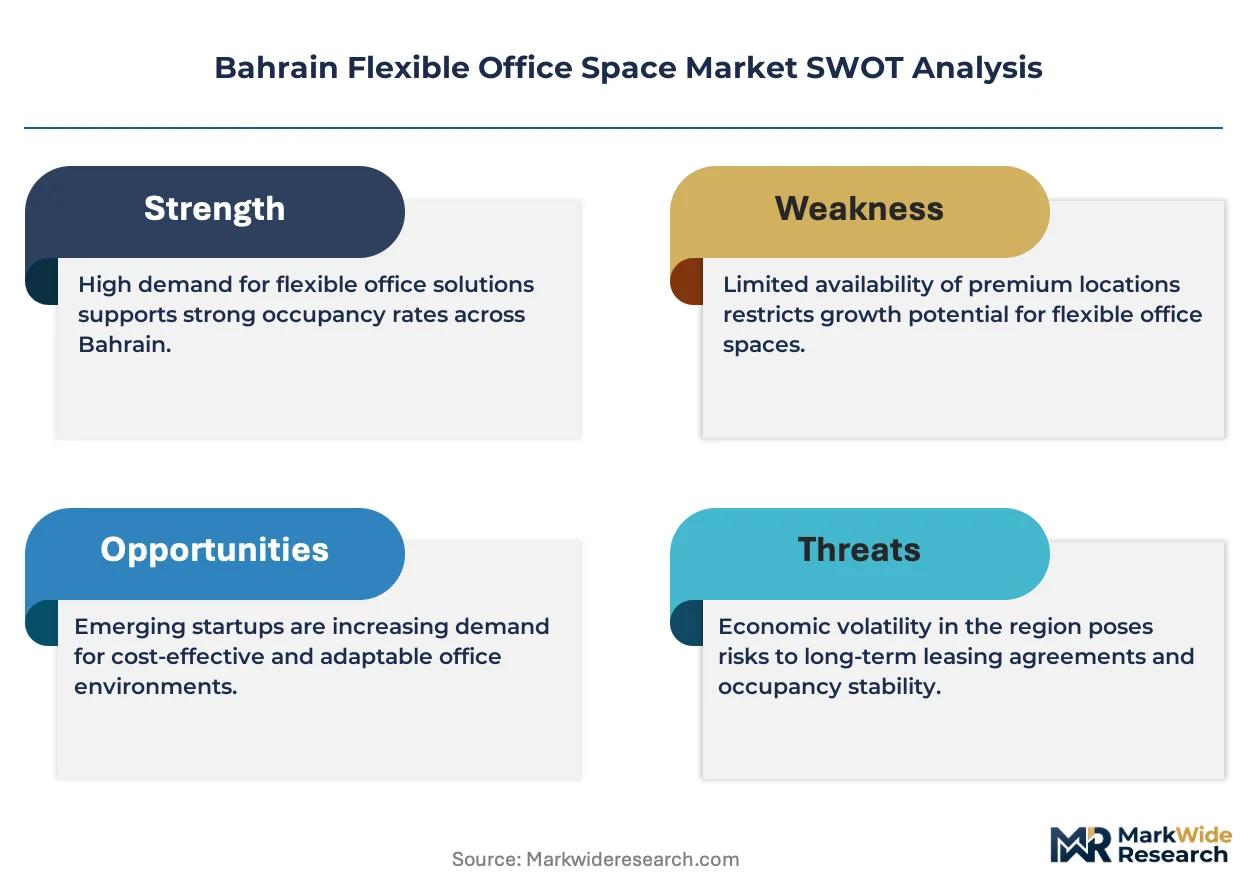
The Central Bank of Bahrain's fintech sandbox regulations are catalyzing startup formations that require scalable, short-term workspace commitments without capital-intensive build-outs.
Growth Catalysts
- SME Licensing Simplification:The Bahrain Economic Development Board's streamlined commercial registration protocols reduce operator onboarding friction and accelerate market entry for new flexible space providers.
- Hub-and-Spoke Corporate Models:Regional headquarters operations are distributing teams across satellite offices rather than consolidated towers, generating demand for distributed flexible footprints in Manama's commercial districts.
- Fiber Infrastructure Parity:Municipal investments in district-level broadband equivalence enable operators to locate beyond traditional financial cores while maintaining enterprise-grade connectivity standards.
Market Restraints
- Parking Capacity Constraints:Municipal zoning limitations on vehicle bay ratios in Seef and Diplomatic Area districts restrict density economics for high-occupancy co-working configurations.
- Fit-Out Cost Volatility:Green building mandate compliance requires premium-grade HVAC and lighting systems that compress operator margins on short-term lease structures.
- Landlord Concentration Risk:Commercial ownership in Bahrain's designated investment zones clusters with a limited pool of institutional property holders, constraining site selection flexibility for expanding operators.
Strategic Opportunities
- Community-Programmed Differentiation:Localized event programming and sector-specific networking calendars create defensible positioning against standardized global competitors in Manama's core.
- Executive Suite Premiumization:Bundled reception, secretarial, and concierge services capture higher per-seat margins from established professional services firms seeking prestige addresses without long-term commitments.
- Acoustic Zoning Innovation:Advanced sound-masking and modular partition systems enable operators to serve project-based teams requiring confidentiality without dedicated private offices.
Industry Challenges
- IT Backbone Redundancy Engineering:Operators must architect dual-path connectivity and failover systems to meet enterprise tenant uptime requirements, demanding specialized technical talent scarce in the local market.
- Hot-Desking Algorithm Optimization:Dynamic seat allocation systems require continuous refinement to balance utilization rates against member experience expectations in high-churn environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Flexible Office Space Market |
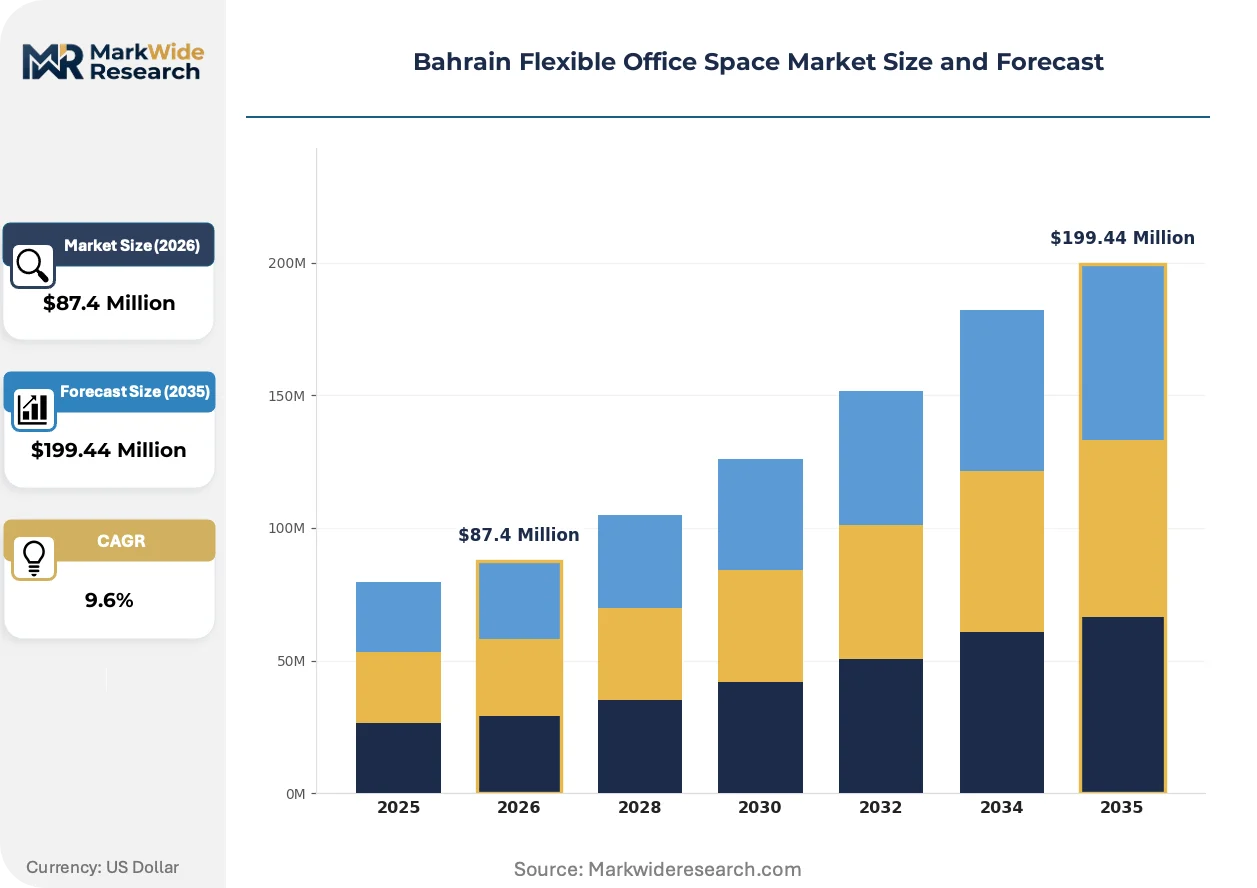
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $199.44 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Office Type: Co-Working Spaces, Executive Suites, Private Offices, Virtual Offices Service Model: Dedicated Desks, Hot Desks, Meeting Rooms, Event Spaces Sector Focus: Startups, SMEs, Enterprises, Freelancers Pricing Model: Monthly Subscription, Pay-As-You-Go, Membership Fees, Flex Pricing |
| Companies Covered | Space 340, Spire Hub, Regus, Alfanar, Brilliant Lab, Servcorp, Letswork, The Startup Factory, Diwan Hub, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Flexible Office Space Market Strategic Shifts
Workspace technology stacks are fragmenting as tenant expectations shift from standardized amenities to configurable, on-demand service layers.
Cloud-based access control and environmental management platforms are decentralizing operational oversight from centralized facilities teams to tenant-facing mobile interfaces. Early-stage ventures and satellite corporate functions are adopting these self-service configurations fastest. This architecture is decentralizing the traditional property management hierarchy, compressing response times for space modifications while reducing on-site staffing requirements.
Bahrain's national green building mandate is restructuring fit-out specifications across commercial zoning codes. The policy requires energy-efficient HVAC systems and smart lighting controls in new flexible office configurations. SME-focused operators are responding by modularizing sustainable infrastructure to spread compliance costs across shorter lease cycles.
Enterprise procurement teams are unbundling workspace commitments from bundled real estate contracts. Regional headquarters in the Gulf are separating core headquarters leases from project-team overflow requirements. This pattern is most visible among fintech formations in Bahrain's regulatory sandbox, where headcount volatility demands month-to-month scalability rather than annual fixed obligations.
Bahrain Flexible Office Space Market Segmentation
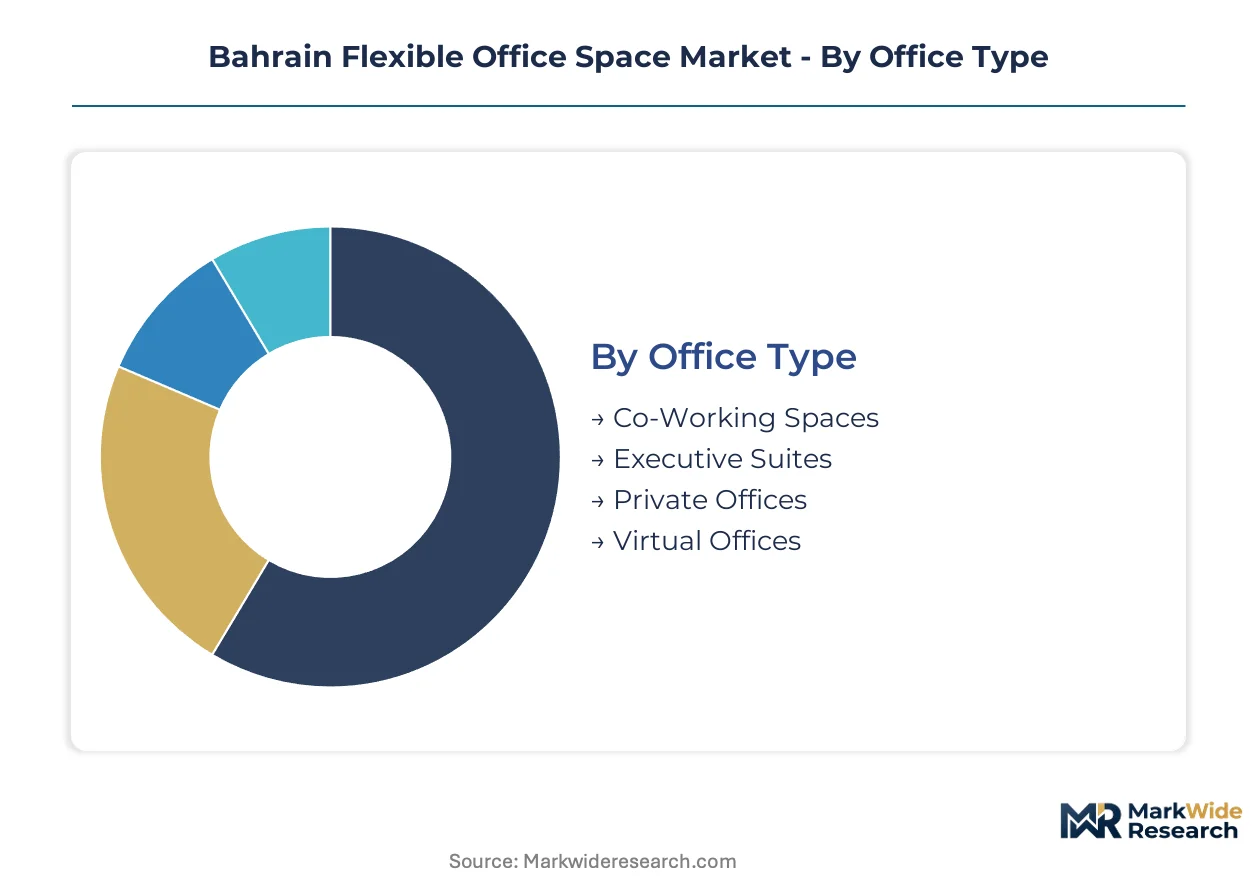
Flexible office operators in Bahrain configure their service architectures around four distinct segmentation axes. Each dimension carries specific regulatory licensing requirements and capital intensity profiles that determine market entry economics.
Office Type:
Commercial zoning codes in Manama's Seef and Diplomatic Area districts impose differentiated fit-out standards across office configurations. The Bahrain Economic Development Board's green building mandate applies variable compliance thresholds based on occupancy density and lease term structures.
- Co-Working Spaces:Open-plan environments with modular partitions and shared infrastructure serve high-density, short-lease clientele. Demand concentrates among fintech formations in Bahrain's regulatory sandbox, where headcount volatility requires month-to-month scalability without capital-intensive build-outs.
- Executive Suites:Premium configurations bundle reception, secretarial, and concierge services with prestige addressing. Professional services firms in Manama's commercial core drive uptake, seeking corporate-grade amenities without multi-year lease commitments.
- Private Offices:Enclosed suites with dedicated IT backbone and acoustic isolation accommodate confidential project work. Law firms and financial advisory practices generate consistent occupancy in the Diplomatic Area district.
- Virtual Offices:Address-only packages with mail handling and occasional meeting room access serve remote-first operations. Freelancers and single-founder startups dominate this tier, minimizing overhead while maintaining commercial credibility.
Co-Working Spaces sits at the top of the volume ranking, with Executive Suites climbing the fastest.
Service Model:
Revenue stability varies sharply across service configurations, with fixed-asset deployments generating predictable cash flows against variable-demand offerings that maximize space utilization.
- Dedicated Desks:Permanently assigned workstations with storage and personalized access credentials anchor recurring revenue streams. SME formations in Bahrain's simplified licensing regime favor this tier for team continuity without private office premiums.
- Hot Desks:Dynamic allocation systems assign seating based on real-time availability algorithms. Early-stage ventures with irregular attendance patterns absorb excess capacity, though churn rates exceed dedicated alternatives.
- Meeting Rooms:Bookable conference facilities with AV infrastructure and catering coordination generate ancillary revenue from non-members. Enterprise satellite teams utilize these for periodic offsites without permanent footprint.
- Event Spaces:Configurable areas for workshops, product launches, and sector networking command premium day rates. Community-programmed differentiation strategies leverage this segment to build defensible positioning against standardized global competitors.
Hot Desks generate the highest transaction velocity, while Meeting Rooms deliver the steepest margin expansion trajectory.
Sector Focus:
Tenant procurement patterns diverge across organizational maturity stages, with each segment presenting distinct technical requirements and contract duration preferences.
- Startups:Venture-backed and bootstrapped formations prioritize minimal commitment structures with rapid scaling pathways. Fintech operators in Bahrain's sandbox cluster demonstrate highest uptake velocity.
- SMEs:Established small and medium enterprises generate the most consistent occupancy cycles, favoring dedicated desk configurations with six-to-twelve month terms. The Central Bank of Bahrain's regulatory push accelerates formations in this bracket.
- Enterprises:Regional headquarters adopting hub-and-spoke models represent the steepest expansion trajectory, unbundling core leases from overflow requirements. Distributed team footprints concentrate in Manama's fiber-equivalent districts.
- Freelancers:Independent professionals drive pay-as-you-go utilization, with demand peaking around project milestones and client presentation requirements.
SMEs anchor current revenue concentration, with Enterprises gaining share fastest through corporate real estate restructuring.
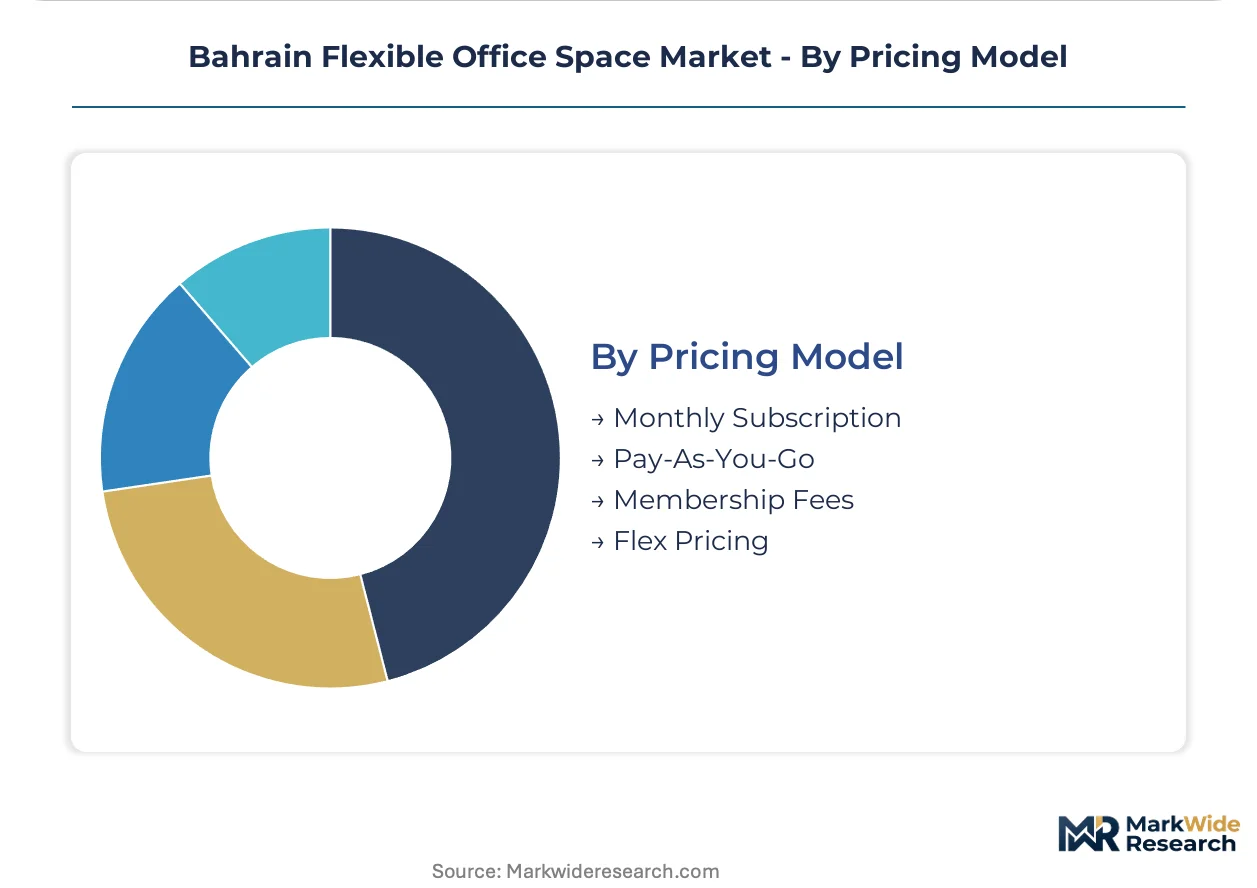
Pricing Model:
Cash flow predictability and customer acquisition economics trade off across billing structures, with subscription models favoring operator stability and consumption-based alternatives maximizing accessibility.
- Monthly Subscription:Fixed recurring fees cover baseline access with predefined usage allowances. Dedicated desk and private office segments default to this structure, supporting operational forecasting.
- Pay-As-You-Go:Per-use billing for hot desks, meeting rooms, and event spaces captures occasional users without barrier pricing. Freelancers and project-based teams dominate this tier.
- Membership Fees:Tiered packages bundle multiple services at discounted rates against à la carte alternatives. Community-programmed operators deploy this structure to deepen engagement.
- Flex Pricing:Dynamic rate adjustment based on occupancy, time-of-day, and advance booking windows optimizes yield management. Algorithmic pricing engines differentiate technologically advanced operators.
Monthly Subscription commands the largest revenue pool, with Flex Pricing expanding most quickly as operators invest in yield optimization infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manama's diplomatic and financial workforce concentration anchors flexible office demand across Bahrain's commercial districts, with Seef and the Diplomatic Area serving as primary absorption zones for scalable workspace procurement.
Capital Governorate
Manama's central business district generates the highest transaction velocity for executive suites and private offices. The Bahrain Economic Development Board's SME licensing simplification accelerates operator registrations in this zone. Seef Mall proximity and diplomatic quarter access concentrate premium flexible space configurations serving professional services firms.
Northern Governorate
Mixed-use developments in Muharraq and Hidd attract logistics-adjacent workspace demand from trade and maritime service providers. Municipal fiber infrastructure investments enable operators to locate beyond traditional financial cores while maintaining enterprise-grade connectivity. The Bahrain International Airport corridor supports satellite corporate functions requiring proximity to transit.
Southern Governorate
Industrial zone proximity drives demand for project-team overflow space among manufacturing and energy sector contractors. The Central Bank of Bahrain's fintech sandbox regulations indirectly stimulate satellite demand as startups seek lower-cost configurations outside premium core districts. Riffa and Isa Town host emerging community-programmed operators differentiating on localized networking.
Central Governorate
Administrative and government-adjacent service providers cluster in this zone seeking mid-tier flexible configurations. Parking capacity constraints are less severe than in Manama's core, enabling higher-density co-working economics. Budaiya and Hamad Town sub-markets attract freelancers and single-founder formations minimizing overhead.
Bahrain Flexible Office Space Market Competitive Environment
Capital-heavy property owners compete with asset-light operators licensing space rather than owning real estate. The vendor base spans three tiers: global network operators with standardized design playbooks, regional specialists emphasizing localized community programming, and niche providers targeting sector-specific tenant cohorts. Consolidation pressure favors operators achieving scale in fit-out procurement and technology platform deployment. Geographic expansion into secondary districts and portfolio diversification across office types represent the dominant competitive vectors.
Among global network operators, Regus occupies a position exemplifying standardized international service architectures. Space 340 anchors the community-programmed differentiation archetype through localized event programming. Servcorp represents the executive suite premiumization tier, targeting professional services firms with bundled reception and secretarial configurations.
| Leading Market Players |
|---|
| Space 340 |
| Spire Hub |
| Regus |
| Alfanar |
| Brilliant Lab |
| Servcorp |
| Letswork |
| The Startup Factory |
| Diwan Hub |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap property holders in Bahrain's designated investment zones anchor supply-side concentration, compressing site selection flexibility while sustaining premium lease rate discipline through scarcity economics. Their concentrated ownership patterns feed directly into operator margin structures, as limited alternative supply forces flexible space providers to absorb fit-out cost volatility rather than pass through rent escalations.
Pricing Analysis
The bundled-vs-unbundled service split defines Bahrain's flexible office pricing architecture. Monthly subscription models dominate dedicated desk and private office segments, supporting operator cash flow predictability, while pay-as-you-go structures capture hot desk and meeting room utilization. Price differentiation rests on service tier depth—executive suites with bundled reception and secretarial commands premium positioning against bare co-working configurations. Cost compression in mid-tier co-working is intensifying because green building mandate compliance demands premium-grade HVAC and lighting systems. Freelancers and single-founder startups exhibit highest price sensitivity, while regional headquarters adopting hub-and-spoke models absorb premium positioning without material negotiation leverage.
Supply Chain Analysis
Dual-sourcing requirements for IT backbone redundancy compel operators to qualify multiple connectivity providers across Manama's fiber-equivalent districts. Fit-out materials draw from UAE, Saudi Arabia, and European specialist manufacturers, with modular partition systems and acoustic zoning components imported through consolidated logistics channels. Supply chain risk centers on single-source vulnerability for enterprise-grade failover systems, where specialized technical talent scarcity in the local market constrains rapid deployment. Distribution runs through landlord-operator direct contracting, bypassing traditional CRE brokerage layers and compressing transaction timelines for space modifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's flexible office market functions as a regulatory compounder, where the Central Bank of Bahrain's fintech sandbox regulations continuously generate startup formations demanding scalable workspace without capital-intensive build-outs.
For Market Incumbents: Acquire distressed fit-out assets from green building mandate non-compliant competitors to consolidate premium positioning in Seef and Diplomatic Area districts. Deploy backward integration into modular sustainable infrastructure manufacturing to spread compliance costs across shorter lease cycles and defend margins against asset-light entrants licensing space rather than owning real estate.
For New Entrants and Emerging Players: Begin with community-programmed differentiation in Riffa and Isa Town sub-markets, where localized networking calendars face minimal competition from standardized global operators. Target satellite corporate functions in Northern Governorate logistics corridors, exploiting municipal fiber infrastructure investments that enable enterprise-grade connectivity beyond traditional financial cores.
For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light operators licensing space with concentrated landlord exposure, offering roll-up potential as consolidation pressure favors scale in technology platform deployment. Monitor enterprise procurement team unbundling patterns as the inflection signal—where regional headquarters separate core headquarters leases from project-team overflow requirements, flexible space absorption accelerates materially.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Compliance Modularization | Spreads Bahrain's national green building mandate costs across shorter lease cycles for SME-focused operators. |
| Community-Programmed Differentiation | Builds defensible positioning against Regus and other standardized global competitors through localized event calendars. |
| Executive Suite Premiumization | Captures higher per-seat margins from professional services firms seeking prestige Diplomatic Area addresses. |
| Acoustic Zoning Innovation | Enables confidential project work without dedicated private offices, serving law firms and financial advisory practices. |
| Hub-and-Spoke Satellite Expansion | Distributes regional headquarters teams across fiber-equivalent districts beyond Manama's consolidated towers. |
Study Parameters
Bottom-up tenant segmentation modeling reconciled against top-down commercial supply tracking forms the analytical core of this study. Primary interviews with flexible office operators, commercial real estate landlords, fintech startup founders, and corporate real estate procurement officers combine with secondary validation from Bahrain Economic Development Board licensing disclosures, Central Bank of Bahrain regulatory sandbox participant lists, and municipal zoning code amendments. Customs records for fit-out material imports, property transaction databases, and fiber infrastructure deployment maps complete the source triangulation.
Historical trendline analysis of occupancy rates, lease term structures, and pricing trajectories establishes baseline momentum across the projection horizon. Segmentation dimensions modeled include office type configuration, service model tier, sector focus maturity stage, and pricing model structure, with geographic sub-market differentiation as an additional industry-specific dimension. CAGRs derive from curve-fitting observed growth patterns against regulatory catalyst timing and infrastructure investment pipelines, incorporating SME licensing simplification velocity and fintech formation rates as Bahrain-specific forecast inputs.
Several conditions sit outside the modeled scope, including macroeconomic shocks to regional headquarters expansion budgets, abrupt shifts in Central Bank of Bahrain sandbox eligibility criteria, and landlord concentration risk crystallization through institutional portfolio sales. Deviation in enterprise unbundling adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
North America Flexible Office Market