
 Europe Smart Building Market | 2026-2036
Europe Smart Building Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Smart Building Market Analysis
Project finance through energy performance contracting is tilting competitive dynamics toward firms with balance-sheet capacity for long-dated asset ownership. Siemens leverages its automation heritage to dominate large-scale commercial retrofits in German metropolitan clusters. Schneider Electric anchors its position through integrated energy management platforms that span building operations and grid interconnection. Bosch GmbH sustains R&D intensity in sensor networks and edge computing for occupant analytics.
A smart building deploys networked sensors, actuators, and control systems to automate HVAC, lighting, security, and energy management functions through centralized or distributed intelligence architectures. These installations typically operate on IP-based backbone infrastructure with BACnet or Modbus protocol layers to enable real-time environmental optimization and predictive maintenance scheduling. Energy Management Systems command the deepest margin pools as utilities and regulators push for measurable demand reduction. IoT connectivity layers represent the fastest-expanding technology segment as wireless sensor density rises across existing building stock. Commercial Buildings absorb the majority of platform deployments, though Government Establishments are accelerating procurement under national renovation wave commitments.
The EU Green Deal and Energy Performance of Buildings Directive mandate near-zero energy standards for new public construction and deep renovation triggers for existing assets. ECHA chemical restrictions and CE marking requirements for electrical safety shape product certification pathways and market access conditions for non-European suppliers. Stakeholders must monitor how national transposition of the EU AI Act affects automated decision-making in building management systems and tenant data processing.
Market Dynamics
The EU Energy Performance of Buildings Directive is forcing asset owners to deploy sensor networks and automated control systems ahead of mandatory renovation triggers, compressing procurement cycles for building automation platforms across Western European commercial portfolios.
Growth Catalysts
- Renovation Wave mandates:National governments across the region are translating EU Green Deal targets into binding renovation quotas for public and commercial stock, creating immediate demand for integrated building management systems.
- Grid-interactive buildings:Distribution system operators in Germany and the Netherlands are piloting demand-response programs that reward automated load flexibility, pulling investment into bidirectional energy management infrastructure.
- Sensor cost deflation:MEMS and optical sensing modules have fallen below price thresholds that enable dense deployment across aging building stock without full infrastructure replacement.
Market Restraints
- Copper and rare-earth input volatility:Permanent magnet materials and high-purity copper for motor controls face concentrated supply from Chinese processing facilities, exposing automation vendors to margin compression.
- CE marking complexity:The Machinery Directive and Low Voltage Directive create multi-month certification timelines for non-European equipment suppliers, delaying market entry.
- Technical debt in legacy HVAC:Pneumatic control systems installed in 1980s-era commercial stock lack digital interfaces, requiring expensive gateway hardware that erodes retrofit project returns.
Strategic Opportunities
- Polish and Romanian commercial corridors:These member states show the lowest smart building penetration rates in the EU27, with accelerating FDI into logistics and light manufacturing facilities creating greenfield installation demand.
- EU AI Act compliance services:Automated decision-making in tenant comfort optimization and energy dispatch will require documented algorithmic transparency, opening advisory and software tooling revenue streams.
- Digital twin convergence:Integration of BIM models with real-time operational data from IoT networks is enabling predictive maintenance contracts that extend vendor relationships beyond equipment sale.
Industry Challenges
- Building systems integration expertise:The shortage of technicians fluent in both legacy BACnet networks and cloud-native API architectures is extending commissioning timelines and inflating implementation costs.
- Cybersecurity certification delays:IEC 62443 compliance for industrial control systems requires specialized third-party assessment that bottlenecks product release schedules.
- Interoperability fragmentation:Competing proprietary protocols from major automation vendors force system integrators to maintain multiple software stacks, increasing project complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Smart Building Market |
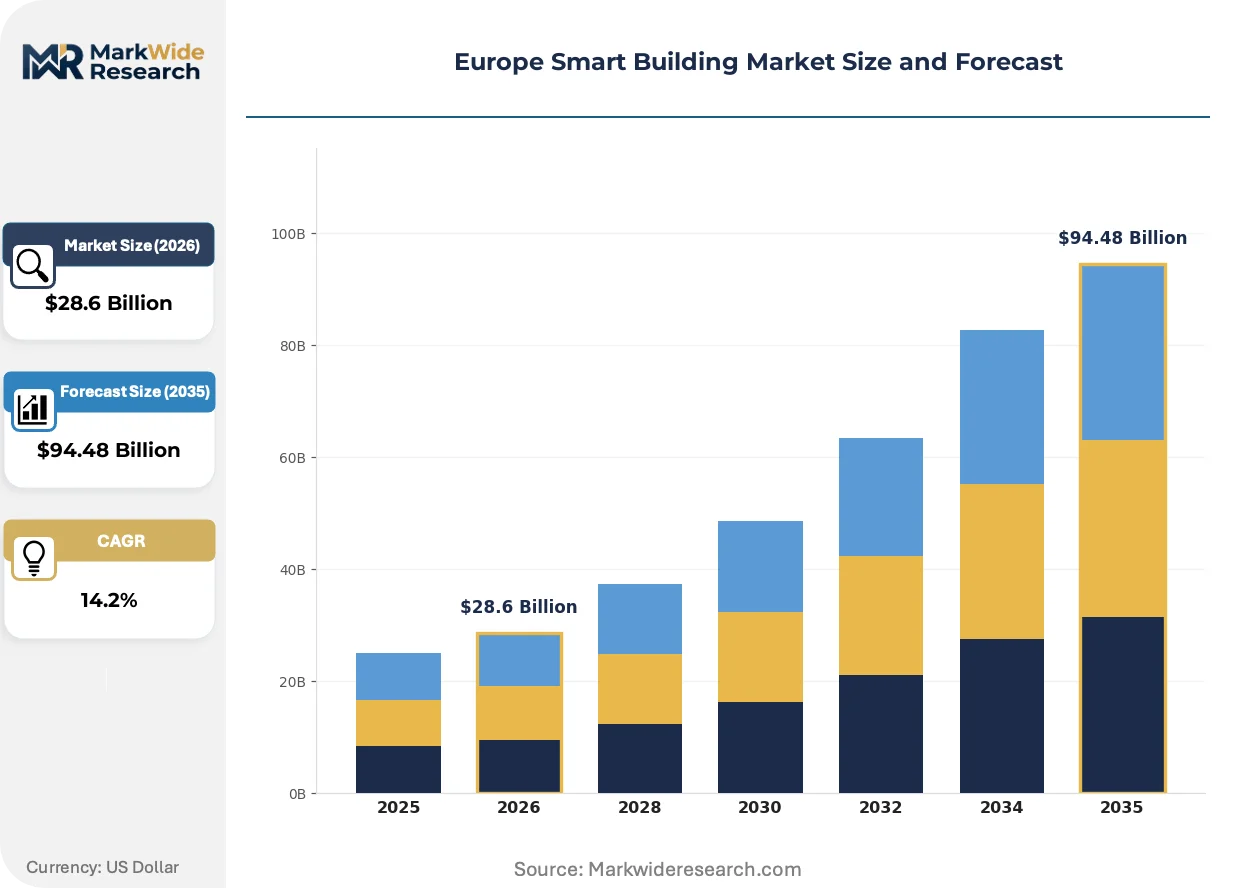
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, HVAC Systems, Security Systems, Energy Management Systems Technology: IoT, AI Integration, Wireless Protocols, Cloud Computing End User: Commercial Buildings, Residential Complexes, Industrial Facilities, Government Establishments Application: Energy Efficiency, Security Monitoring, Automation, Occupant Comfort |
| Companies Covered | Johnson Controls, Bosch GmbH, Schneider Electric, Huawei, Philips Lighting, Siemens, Legrand, Ericsson, ABB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Smart Building Market Emerging Trajectories
Edge computing architectures are redistributing intelligence from centralized building management servers to sensor-rich endpoints, collapsing latency for real-time environmental control while reducing cloud dependency. This shift is compressing hardware form factors and rewiring competitive advantage toward semiconductor and firmware capabilities.
Wireless mesh protocols operating in sub-GHz spectrum bands are rendering obsolete hardwired sensor backbones in retrofit applications. German and French facility managers are deploying these networks across 1960s-1990s office stock where conduit installation is structurally prohibitive. The elimination of wiring labor is shifting project economics toward equipment-heavy margin pools and accelerating payback calculations for deep energy retrofits.
The EU AI Act's risk classification framework for automated decision-making systems is triggering redesign cycles in building management software. Vendors serving commercial real estate investment trusts must now document algorithmic logic for tenant thermal comfort optimization and emergency evacuation routing. French and Dutch regulators are moving fastest on enforcement guidance, pushing procurement specifications toward certified transparency modules.
Energy-as-a-service contracting is displacing capital expenditure models for large commercial retrofits. Facility owners in Madrid and Milan are transferring performance risk to vendors who retain equipment ownership and capture savings shares. This structure concentrates project flow toward balance-sheet-capable automation firms and compresses margins for pure equipment suppliers locked into traditional sale terms.
Europe Smart Building Market Segmentation
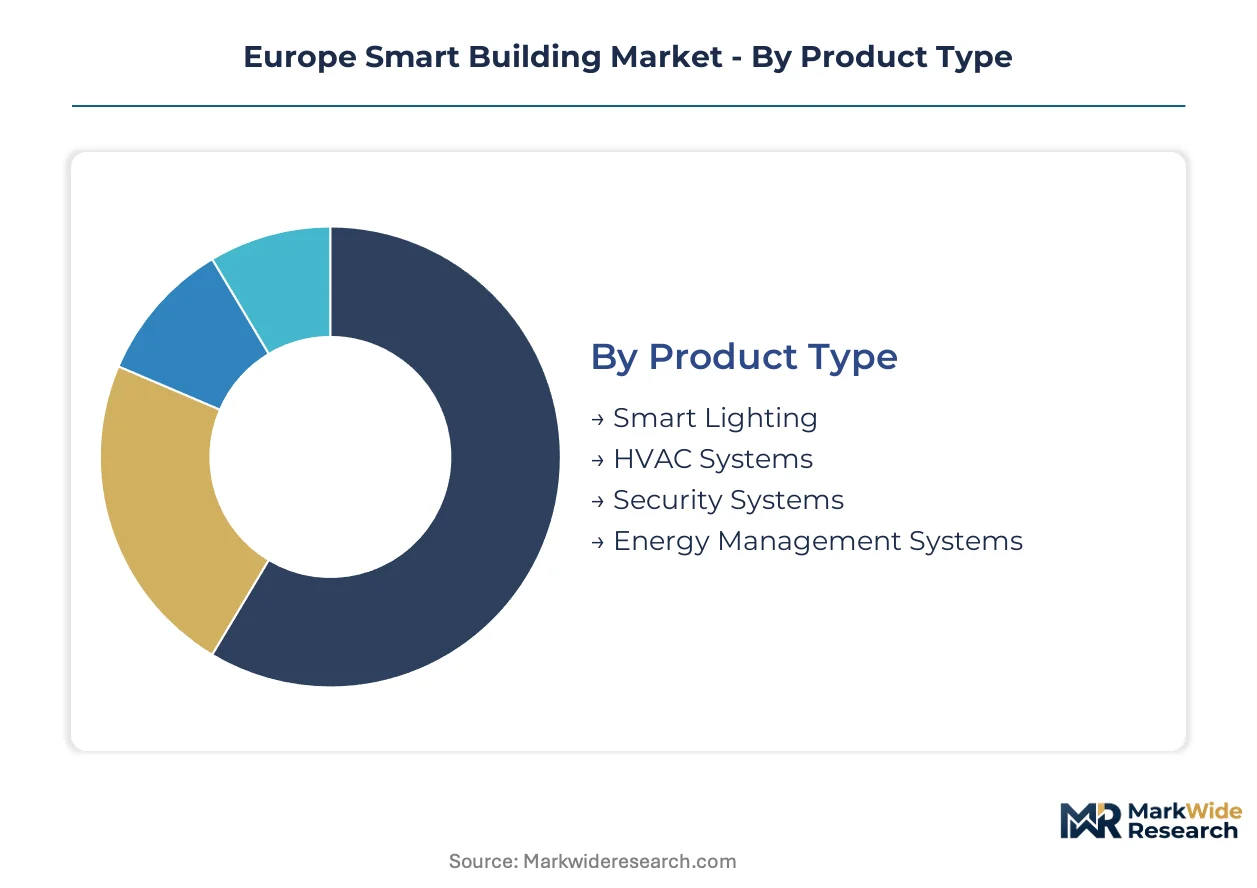
Smart building procurement in Europe fragments across multiple technical and commercial dimensions, each carrying distinct margin profiles and service attachment rates. Understanding these segment boundaries illuminates where automation vendors must build recurring revenue streams versus one-time equipment sales.
Product Type:
After-sales service intensity varies dramatically across building automation equipment categories, with predictive maintenance contracts and software subscriptions creating divergent lifetime value profiles for vendors.
- Smart Lighting:LED luminaires with embedded occupancy sensors and daylight harvesting algorithms now ship with 10-year service agreements in German commercial retrofits. Philips and Zumtobel bundle spectral tuning and circadian rhythm programming into recurring revenue models that extend beyond hardware depreciation cycles.
- HVAC Systems:Variable refrigerant flow units and heat pump controls generate the highest attach rates for remote monitoring services, as thermal performance directly impacts energy compliance audits under the Energy Performance of Buildings Directive. French facility managers prioritize systems with embedded fault detection to minimize on-site technician visits.
- Security Systems:Access control and video analytics platforms require continuous firmware updates to address evolving cybersecurity threats under IEC 62443 standards.
- Energy Management Systems:Dashboard software for utility submetering and demand response coordination commands premium pricing when bundled with performance guarantees.
By volume, HVAC Systems leads. By growth pace, Energy Management Systems is ahead.
Technology:
Technology selection in European smart buildings tracks directly to infrastructure age, with greenfield developments adopting fundamentally different architectures than retrofit projects constrained by legacy building fabric.
- IoT:Sensor density in commercial stock has reached thresholds where battery-less energy harvesting devices eliminate maintenance cycles entirely. EnOcean and Wirepas protocols dominate German and Nordic installations where wiring costs exceed equipment spend.
- AI Integration:Machine learning models for predictive HVAC control and anomaly detection face regulatory scrutiny under the EU AI Act's risk classification framework. Dutch building operators now require algorithmic transparency documentation before procurement approval.
- Wireless Protocols:Sub-GHz mesh networks from LoRa and Sigfox enable rapid deployment across 1970s-era concrete structures where conduit installation is structurally prohibitive.
- Cloud Computing:Edge-to-hybrid architectures are displacing pure cloud reliance as latency requirements tighten for real-time occupant comfort optimization.
IoT commands the largest installed base. AI Integration shows the steepest expansion trajectory as compliance frameworks mature.
End User:
End-user categories in Europe diverge sharply on procurement authority, with centralized government mandates creating fundamentally different sales cycles than fragmented private ownership structures.
- Commercial Buildings:Real estate investment trusts in London, Frankfurt, and Paris deploy integrated platforms to meet Science Based Targets initiative commitments and attract ESG-focused capital. Asset managers prioritize systems with open APIs to avoid vendor lock-in across multi-building portfolios.
- Residential Complexes:Multi-family housing associations in Denmark and the Netherlands adopt smart thermostats and shared energy storage controls as district heating networks integrate bidirectional flexibility services.
- Industrial Facilities:Food processing and pharmaceutical plants in Belgium and Ireland combine building automation with process control under unified SCADA architectures.
- Government Establishments:National renovation wave commitments in Italy and Spain are accelerating public school and hospital retrofits with standardized procurement frameworks that favor mid-tier system integrators over multinational vendors.
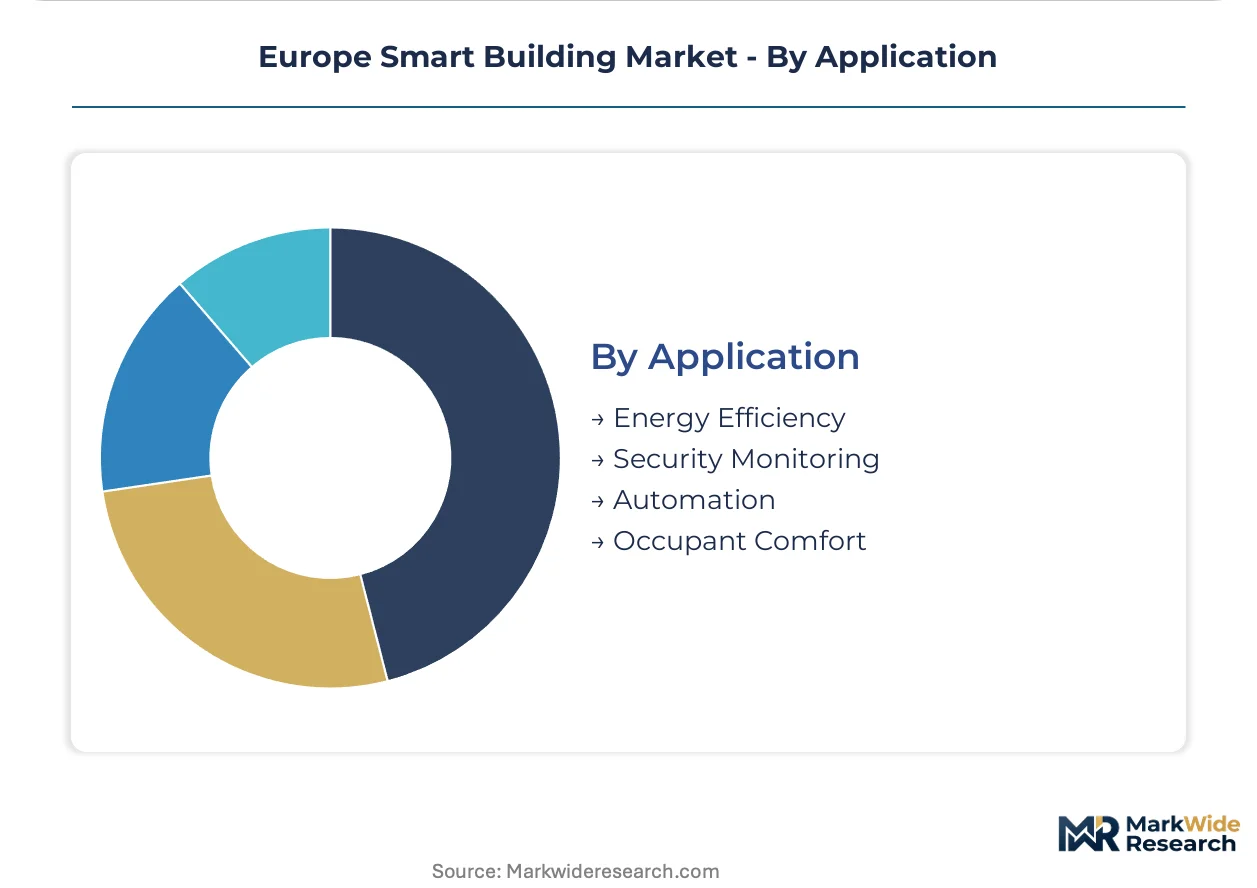
Commercial Buildings absorb the majority of platform spend. Government Establishments are climbing the fastest as binding renovation quotas take effect.
Application:
Application focus determines which sensor modalities and control algorithms receive investment priority, with energy compliance creating different technical requirements than security or comfort optimization.
- Energy Efficiency:Automated demand response and load shifting algorithms enable buildings to participate in grid flexibility markets operated by TenneT in the Netherlands and TransnetBW in Germany. These programs require certified measurement and verification protocols that shape equipment specifications.
- Security Monitoring:Video analytics with privacy-preserving edge processing address GDPR constraints on biometric data collection in French and German commercial properties.
- Automation:Integrated control of lighting, shading, and HVAC sequences reduces operational complexity for facility management teams with limited technical staffing.
- Occupant Comfort:Personalized environmental zones with mobile app control differentiate premium office stock in Madrid and Milan competitive leasing markets.
Energy Efficiency drives the deepest retrofit investment. Occupant Comfort is expanding most quickly as return-to-office strategies emphasize experiential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial real estate investment trusts and public sector procurement authorities dominate platform deployment decisions across European urban corridors. Buyer concentration in Frankfurt, Paris, and London drives specification standards that cascade into secondary markets.
Germany
Distribution system operators in Baden-Württemberg and North Rhine-Westphalia pilot demand-response programs that reward automated building load flexibility. The national transposition of the EU Energy Performance of Buildings Directive mandates sensor deployment ahead of 2030 renovation triggers. Munich and Hamburg commercial districts see accelerated procurement of integrated energy management platforms.
France
Real estate investment trusts in Île-de-France prioritize Science Based Targets initiative compliance through building automation retrofits. ANSM and CNIL enforcement guidance on the EU AI Act pushes procurement specifications toward certified algorithmic transparency. Lyon and Marseille logistics corridors adopt wireless sensor networks for greenfield facility construction.
United Kingdom
London commercial landlords deploy smart building platforms to attract ESG-focused institutional capital and meet net-zero pathway commitments. The Building Safety Regulator integrates automated fire safety and emergency evacuation systems into compliance frameworks. Birmingham and Manchester retrofit markets concentrate demand for BACnet-compatible control upgrades.
Netherlands
TenneT's grid flexibility markets pull investment into bidirectional energy management infrastructure from commercial asset owners in Randstad cities. National renovation wave commitments accelerate public school and hospital retrofits with standardized procurement frameworks. Eindhoven's technology corridor hosts pilot programs for edge-computing building control architectures.
Italy
Milan and Rome commercial property markets differentiate through occupant comfort optimization and mobile-app-controlled environmental zones. National transposition of EU Green Deal targets creates binding renovation quotas for public building stock. Turin's industrial districts combine building automation with process control under unified SCADA architectures.
Europe Smart Building Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways. Siemens, Schneider Electric, and Johnson Controls anchor the consolidated tier through long-dated service contracts and energy performance contracting structures. Mid-tier system integrators capture public sector flow through national renovation wave frameworks. Dominant competitive moves include M&A for software capabilities and strategic partnerships with distribution system operators for grid-interactive building programs.
Among diversified industrial conglomerates, Siemens and Bosch GmbH exemplify archetypes that leverage automation heritage and sensor R&D intensity respectively. Schneider Electric occupies a position bridging energy management and grid interconnection capabilities. These three anchors represent distinct strategic postures: hardware-integrated service models, component-specialist supply positions, and platform-centric energy orchestration.
| Leading Market Players |
|---|
| Johnson Controls |
| Bosch GmbH |
| Schneider Electric |
| Huawei |
| Philips Lighting |
| Siemens |
| Legrand |
| Ericsson |
| ABB |
| Others |
Supply Flow & Price Mechanics
Shenzhen's sensor module manufacturing clusters dictate downstream pricing power for European automation vendors, as MEMS component cost curves compress hardware margins while firmware and service layers capture residual value. CE marking timelines and rare-earth magnet supply concentration further amplify procurement cost volatility for system integrators bidding on deep retrofit projects.
Pricing Analysis
Certification level under the EU AI Act and Machinery Directive creates the primary spread between premium and standard automation platforms. Project-based contracting dominates, with energy performance contracting structures transferring capex burden to vendors in exchange for long-dated service revenue. Price differentiation rests on algorithmic transparency documentation and embedded cybersecurity certification under IEC 62443 standards. Cost compression in wireless sensor hardware intensifies as Chinese module suppliers expand capacity, while public sector procurement offices show highest price sensitivity compared to ESG-focused real estate investment trusts.
Supply Chain Analysis
Extended payment terms from German distribution system operators and supply-chain finance facilities anchored by Siemens and Schneider Electric reshape working capital requirements for mid-tier component suppliers. Manufacturing concentrates in China for MEMS sensors, Germany for industrial controllers, and the Netherlands for power electronics. Permanent magnet materials and high-purity copper for motor controls draw from concentrated Chinese processing facilities. Single-source vulnerability in rare-earth refining exposes automation vendors to margin compression. Distribution runs through authorized system integrator networks and direct procurement channels for large commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent automation vendors must defend against substitution from cloud-native building management platforms that bypass traditional BACnet infrastructure through API-first architectures.
For Market Incumbents: Pre-empt platform displacement by acquiring edge-computing software capabilities and embedding algorithmic transparency modules ahead of EU AI Act enforcement waves. Backward integration into sensor semiconductor supply secures margin control against Chinese module cost compression. Channel consolidation through exclusive service partnerships with TenneT and TransnetBW locks in grid-interactive building program participation. For New Entrants and Emerging Players: Establish a beachhead in Polish and Romanian logistics corridor retrofits where multinational vendor presence remains thin and greenfield facility construction accelerates. Wireless mesh deployment expertise targeting 1970s concrete structures bypasses incumbent hardwired infrastructure advantages. Energy-as-a-service contracting models transfer performance risk and unlock public sector procurement frameworks that favor agile system integrators over balance-sheet-heavy conglomerates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors firms with hybrid edge-cloud architectures and documented EU AI Act compliance tooling. Long-term viability hinges on recurring software revenue attach rates exceeding hardware depreciation cycles. Acquisition targets should demonstrate certified algorithmic transparency capabilities and established distribution system operator partnerships. The signal to watch is national transposition velocity of Energy Performance of Buildings Directive mandates across member states.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified BACnet and cloud-native API architectures reduce commissioning timelines for mixed-vendor retrofit portfolios. |
| Acquisition of Specialist Firm | Edge-computing software targets compress latency for real-time demand response coordination with TenneT. |
| Strategic Partnership | Grid-interactive building programs with TransnetBW unlock recurring revenue from automated load flexibility services. |
| Geographic Expansion | Polish and Romanian commercial corridors offer lowest smart building penetration and accelerating FDI inflows. |
| Product Launch | Algorithmic transparency modules address ANSM and CNIL enforcement guidance on EU AI Act risk classification. |
Methodological Framework
Operator-level perspectives from facility managers, system integrators, distribution system operators, and real estate asset managers anchored the qualitative base. Primary interviews combined with secondary validation from EU Energy Performance of Buildings Directive transposition documents, CE marking certification databases, and national renovation wave procurement records. Customs data on sensor module trade flows and EPC contractor project pipelines provided supply-side calibration. Bottom-up equipment shipment analysis triangulated against top-down building stock renovation obligation modeling.
Scenario-bracketing around regulatory enforcement timing and copper price volatility informed projection boundaries across the analysis window. Segmentation dimensions modeled include product type, technology layer, end-user category, and application focus, with additional granularity on building vintage and infrastructure constraint severity. CAGRs derived from equipment replacement cycle analysis and regulatory mandate compliance deadlines. Forecast inputs incorporated sensor cost deflation curves and grid flexibility market participation rates.
Sensitivities concentrate around EU AI Act transposition velocity, rare-earth supply disruption events, and public sector budget allocation shifts. Forecasts reflect documented assumptions on renovation wave funding continuity and distribution system operator program expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
United States Co-Working Office Space Market
Real Estate
Europe Commercial Real Estate Market
Real Estate
North America Luxury Residential Real Estate Market
Real Estate
IBC Rental Business Market
Real Estate
Norway Facility Management Market
Real Estate
Japan Office Real Estate Market
Real Estate
Egypt Condominiums and Apartments Market
Real Estate
Property Management Service Market
Real Estate
Chile Facility Management Market
Real Estate
India Condominium and Apartments Market
Real Estate
Serbia Facility Management Market
Real Estate
Relocation Management Service Market
Real Estate
Israel Commercial Real Estate Market
Real Estate
China Commercial Real Estate Market
Real Estate
US Real Estate and Hospitality Market
Real Estate
Belgium Facility Management Market