
 Saudi Arabia Real Estate Brokerage Market | 2026-2036
Saudi Arabia Real Estate Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Real Estate Brokerage Market Insights
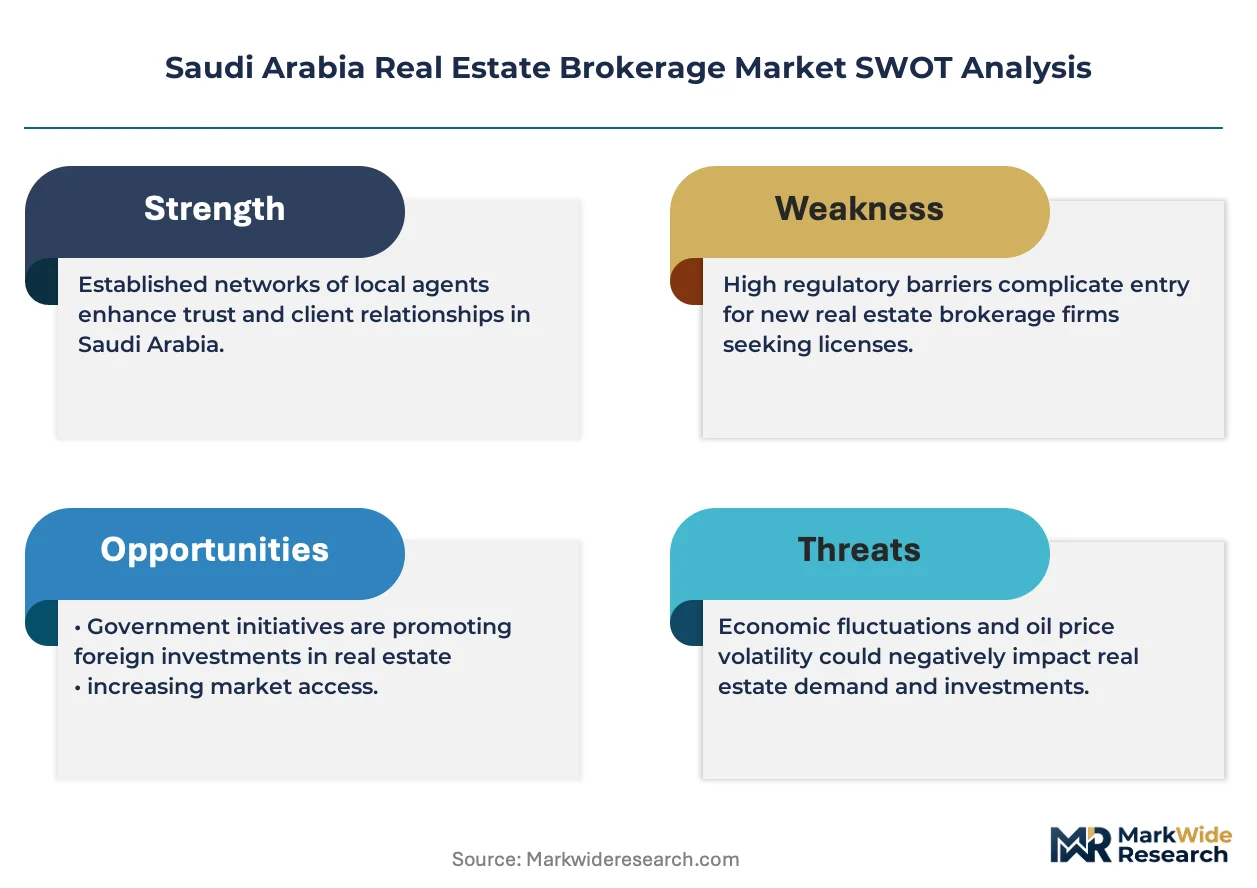
SFDA licensing requirements for real estate investment fund advisors is hardening the cost-of-entry calculus for new brokerage entrants. JLL leverages its cross-border capital markets desk to sustain advisory mandates on Riyadh giga-projects. CBRE Group anchors its competitive stance through specialized industrial and logistics brokerage teams serving Red Sea Gateway clients. Colliers International differentiates via integrated project management services tied to NEOM and Qiddiya masterplans.
Saudi Arabia real estate brokerage encompasses licensed intermediary services facilitating property transactions, valuation, and portfolio advisory under the Real Estate General Authority (REGA) regulatory framework, with practitioners required to hold professional indemnity coverage and complete certified training programs. The primary commercial purpose centers on matching capital deployment with regulated asset transfers across residential, commercial, and development land categories. Residential brokerage leads transaction volume as mortgage penetration expands under Sakani and Mortgage Finance Guarantee Programs, while commercial brokerage captures premium fee structures from institutional capital seeking stabilized income assets. Property management services represent the fastest-growing service type as foreign ownership rules relax and institutional landlords demand operational oversight.
REGA, the Saudi Central Bank, and the Zakat, Tax and Customs Authority collectively shape market access through mandatory broker registration, mortgage origination standards, and VAT treatment of commission income. The Real Estate Transaction Tax and newly enforced anti-money laundering protocols for high-value property transfers are tightening compliance burdens on smaller independent operators. Stakeholders must monitor regulatory harmonization between REGA's professional standards and municipal land-use plans as giga-project delivery accelerates across multiple economic cities.
Market Dynamics
REGA's tightening professional indemnity requirements and the Saudi Central Bank's mortgage origination standards are compressing the independent broker population while concentrating transaction flow through licensed, capitalized intermediaries capable of absorbing compliance costs.
Growth Catalysts
- Sakani Housing Program:Government-subsidized mortgage guarantees expand first-time buyer access, generating transaction volume for qualified brokers in Riyadh and Jeddah metropolitan zones.
- NEOM and Qiddiya Giga-Projects:Masterplan developments create sustained advisory demand for land aggregation, pre-development sales, and institutional capital placement services.
- Proptech Platforms:Digital listing aggregation and virtual property tours reduce search friction, accelerating transaction velocity for tech-enabled brokerage operators.
Market Restraints
- Professional Indemnity Coverage Costs:Mandatory REGA insurance requirements impose fixed cost burdens that disproportionately constrain smaller independent operators.
- Mortgage Origination Standards:Saudi Central Bank debt-to-income caps and valuation protocols extend transaction timelines, compressing broker commission realization cycles.
- Land Supply Concentration:Municipal land release schedules in Riyadh and Jeddah remain controlled by state-linked developers, limiting inventory access for non-preferred brokers.
Strategic Opportunities
- Red Sea Coastal Development:Tourism and logistics corridor projects around Jeddah create underpenetrated territory for specialized commercial brokerage services.
- REIT Advisory Services:Relaxation of foreign ownership rules for real estate investment trusts generates demand for portfolio construction and asset management mandates.
- Industrial-Logistics Brokerage:Red Sea Gateway port expansion and bonded zone development attract institutional capital seeking specialized warehouse and distribution facility placement.
Industry Challenges
- Certified Agent Shortage:REGA-mandated training completion requirements outpace qualified instructor capacity, extending onboarding timelines for new brokerage hires.
- Anti-Money Laundering Protocol Integration:High-value transaction monitoring systems require capital investment in compliance infrastructure, straining mid-tier operator margins.
- Legacy System Interoperability:Municipal land registry digitization varies across Saudi Arabia's regions, forcing brokers to maintain parallel paper and electronic documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Real Estate Brokerage Market |
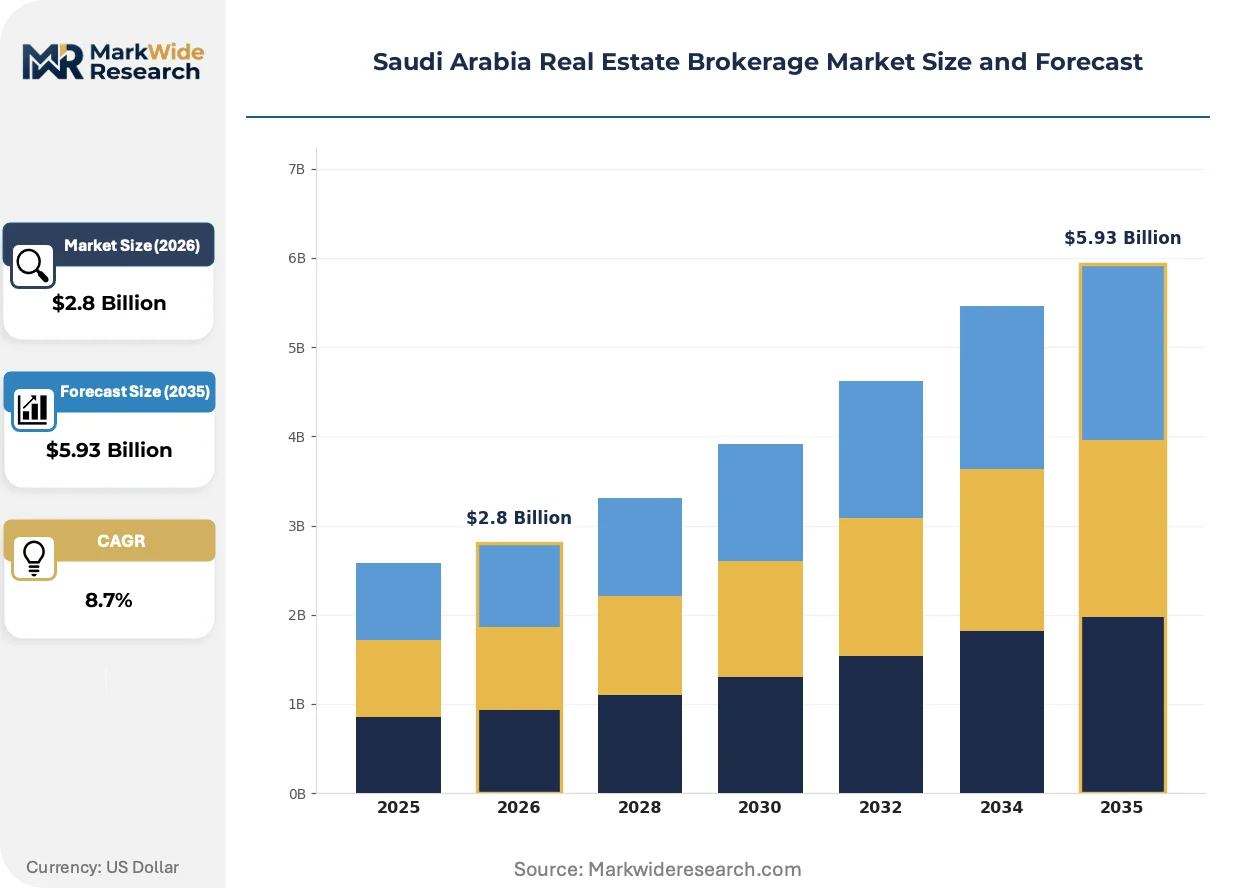
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Brokerage, Commercial Brokerage, Industrial Brokerage, Property Management Customer Type: Individual Buyers, Investors, Corporations, Developers Property Type: Residential, Commercial, Mixed-Use, Land Transaction Type: Sales, Leasing, Auctions, Property Swaps |
| Companies Covered | JLL, CBRE Group, Colliers International, Savills, Knight Frank, Hamptons International Saudi Arabia, Al Saedan Real Estate Co., Sumou Real Estate, Saudi Real Estate Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Real Estate Brokerage Market Trends and Innovations
Digital infrastructure deployment and regulatory digitization are compressing transaction timelines while elevating transparency expectations among institutional capital sources.
Blockchain-based property registries are integrating with municipal land authority systems in Riyadh and Jeddah. The Saudi Central Bank's sandbox initiative permits pilot implementations for title verification and smart contract escrow. Large developers in giga-project zones are mandating digital deed transfers, compressing settlement periods from weeks to days.
REGA's electronic broker licensing platform streamlines renewal and disciplinary tracking. The Real Estate Transaction Tax automation interface reduces manual filing errors but requires API integration with brokerage back-office systems. Smaller operators face upgrade costs or third-party platform dependency.
Institutional buyers now demand bundled property management alongside acquisition advisory. Sovereign wealth fund mandates and REIT formation requirements favor brokers offering operational oversight, not just transaction execution. This service unbundling concentrates revenue with full-service operators in Riyadh's northern corridor and Jeddah's waterfront zone.
Saudi Arabia Real Estate Brokerage Market Segmentation
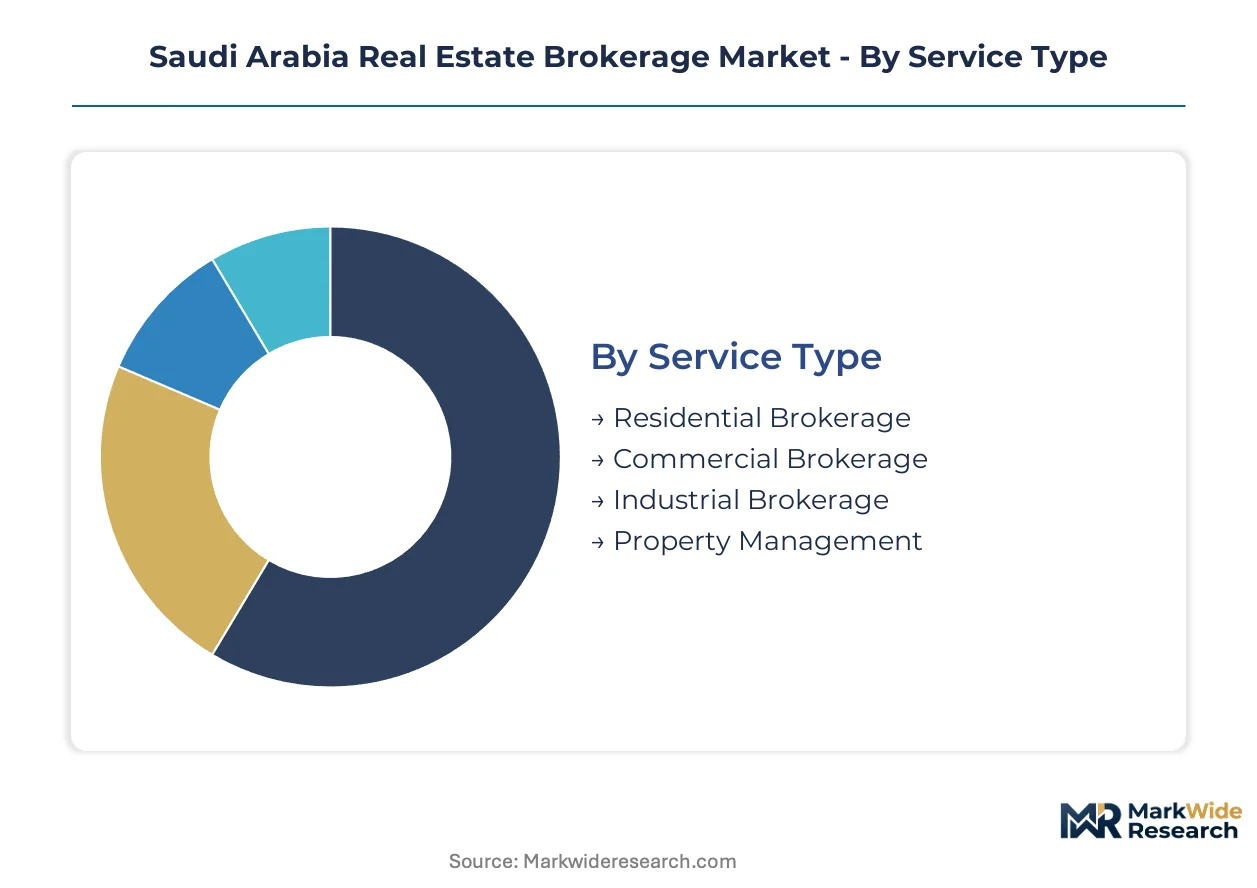
Segmentation in Saudi Arabia's brokerage market exposes divergent regulatory burdens and margin profiles across service lines. REGA licensing tiers, SFDA investment fund advisor mandates, and Saudi Central Bank mortgage origination rules create distinct compliance cost structures that reshape competitive positioning within each category.
Service Type:
REGA's professional indemnity requirements and SFDA fund advisor licensing impose graduated certification burdens across service lines, with capital markets advisory demanding the most stringent credentials.
- Residential Brokerage:Transaction execution for individual buyers and sellers of housing units, apartments, and villas. Demand concentrates in Riyadh's northern corridor and Jeddah's waterfront redevelopment zone under Sakani mortgage guarantee expansion. REGA's certified agent training requirements and mandatory professional indemnity coverage create fixed cost barriers that favor capitalized operators.
- Commercial Brokerage:Advisory on office, retail, and hospitality asset transactions for institutional capital. Leasing velocity in Riyadh's King Abdullah Financial District and Jeddah's Red Sea Gateway corridor drives fee generation. SFDA licensing requirements for real estate investment fund advisors harden entry calculus for new entrants serving sovereign wealth mandates.
- Industrial Brokerage:Specialized placement of warehouse, logistics, and manufacturing facilities. Red Sea Gateway port expansion and bonded zone development attract institutional capital seeking distribution infrastructure.
- Property Management:Operational oversight of leased assets including tenant relations, maintenance coordination, and financial reporting. Foreign ownership rule relaxation and REIT formation requirements accelerate demand for bundled management services.
Leading the category by volume: Residential Brokerage. Growing fastest: Property Management.
Customer Type:
Customer archetypes determine fee structure elasticity and advisory complexity, with institutional mandates commanding premium pricing and multi-year engagement terms.
- Individual Buyers:First-time homeowners and upgraders accessing Sakani-subsidized mortgage products. Riyadh metropolitan zone transaction density outpaces other regions as household formation accelerates under Vision 2030 housing targets.
- Investors:Domestic and foreign capital deploying into income-generating assets and development land. NEOM and Qiddiya giga-project pre-development sales generate sustained advisory demand for land aggregation strategies.
- Corporations:Occupier clients seeking headquarters, branch offices, and operational facilities. Jeddah's Red Sea coastal development corridor creates underpenetrated territory for tenant representation services.
- Developers:Masterplan developers and state-linked developers controlling municipal land release schedules. Preferred broker relationships concentrate transaction flow through licensed intermediaries with giga-project track records.
Highest fee compression: Individual Buyers. Steepest expansion trajectory: Investors.
Property Type:
Asset class specialization shapes technology infrastructure requirements and valuation methodology, with mixed-use developments demanding integrated residential-commercial expertise.
- Residential:Single-family villas, apartments, and compound housing across price tiers. Mortgage origination standards from the Saudi Central Bank extend transaction timelines, compressing commission realization cycles for brokers.
- Commercial:Office towers, retail centers, and hospitality assets. Riyadh's northern corridor giga-project integration reshapes transaction volumes as institutional capital seeks stabilized income.
- Mixed-Use:Integrated developments combining residential, commercial, and retail components. NEOM and Qiddiya masterplans mandate bundled advisory capabilities spanning multiple asset classes.
- Land:Development parcels and agricultural holdings subject to municipal zoning and REGA transaction protocols. State-linked developer land release concentration limits inventory access for non-preferred brokers.
Deepest liquidity: Residential. Gaining share fastest: Mixed-Use.
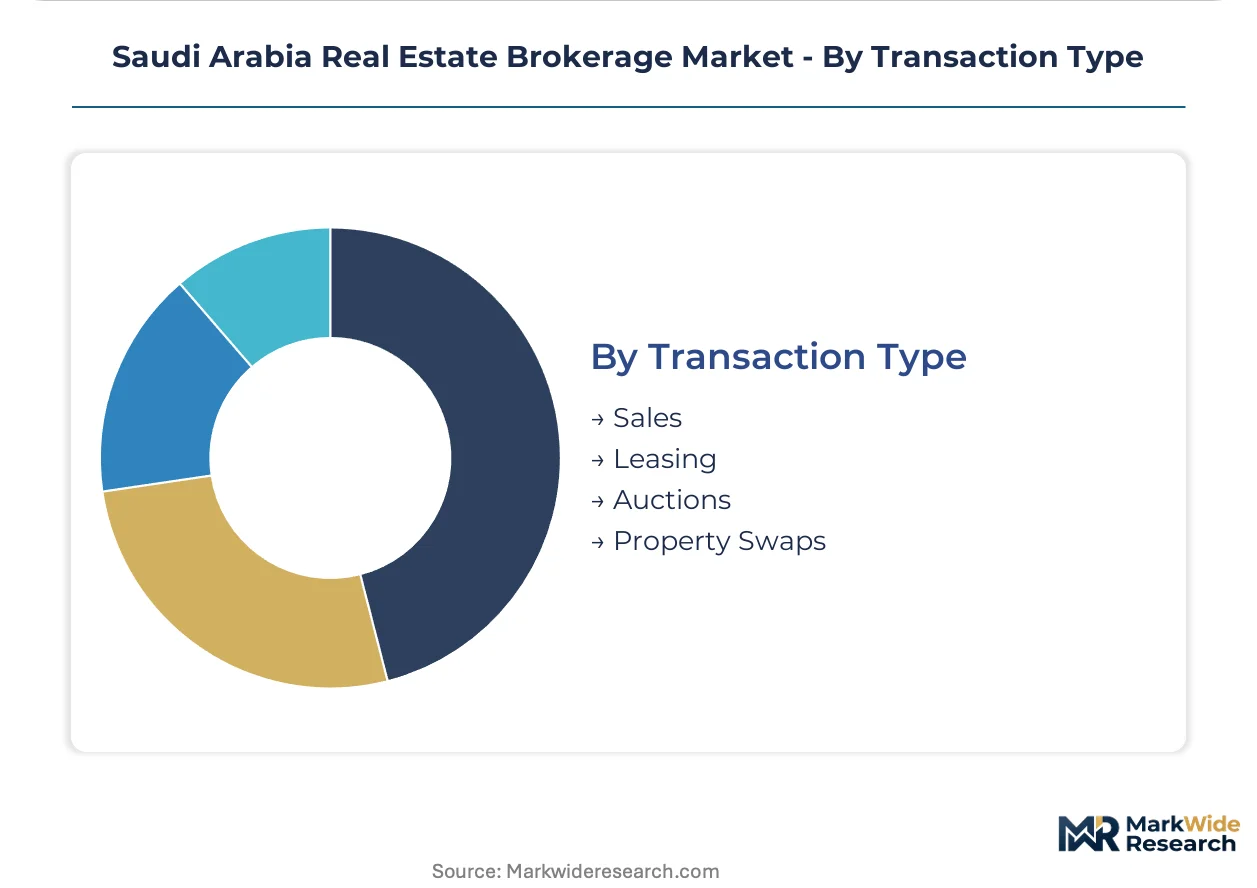
Transaction Type:
Transaction mechanism determines regulatory touchpoints and settlement timeline, with digital infrastructure deployment compressing periods for standardized sale executions.
- Sales:Permanent ownership transfers subject to Real Estate Transaction Tax and REGA documentation requirements. Blockchain-based property registries in Riyadh and Jeddah compress settlement from weeks to days.
- Leasing:Tenancy agreements for residential and commercial occupancy. Institutional landlord demand for operational oversight expands property management bundling.
- Auctions:Competitive bidding processes for distressed or unique assets. Anti-money laundering protocols for high-value transfers tighten compliance burdens on auction facilitators.
- Property Swaps:Like-kind exchanges and portfolio rebalancing transactions. Complex valuation requirements demand certified appraiser engagement under REGA standards.
Dominant mechanism: Sales. Climbing the fastest: Leasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transaction volume concentrates in Riyadh's northern corridor and Jeddah's waterfront zone, where giga-project integration is compressing settlement timelines. REGA's electronic licensing platform and municipal digitization initiatives are reshaping broker operations across Saudi Arabia's major metropolitan clusters.
Riyadh
The northern corridor drives residential brokerage demand as Sakani-subsidized mortgage guarantees expand first-time buyer access. REGA's mandatory professional indemnity requirements and certified agent training standards are compressing the independent broker population. King Abdullah Financial District leasing velocity sustains commercial advisory fees for capitalized intermediaries.
Jeddah
Waterfront redevelopment and Red Sea Gateway port expansion generate specialized industrial-logistics brokerage demand. The Saudi Central Bank's debt-to-income caps extend transaction timelines, compressing commission realization cycles. Municipal land release schedules controlled by state-linked developers limit inventory access for non-preferred operators.
Eastern Province
Industrial brokerage concentrates around petrochemical and logistics corridor developments near Jubail and Ras Tanura. Anti-money laundering protocols for high-value property transfers tighten compliance burdens on smaller operators. Bonded zone development attracts institutional capital seeking warehouse and distribution facility placement services.
NEOM Northwest
Masterplan developments create sustained advisory demand for land aggregation and pre-development sales. Blockchain-based property registries mandated by large developers compress settlement periods from weeks to days. Preferred broker relationships with giga-project sponsors concentrate transaction flow through licensed intermediaries with track records.
Western Region Secondary Cities
Tourism and logistics projects along the Red Sea coastal corridor create underpenetrated territory for commercial brokerage services. Municipal land registry digitization varies across regions, forcing parallel paper and electronic documentation workflows. Property management services accelerate as foreign ownership rules relax and institutional landlords demand operational oversight.
Saudi Arabia Real Estate Brokerage Market Competitive Landscape
Riyadh-based operators anchor one tier; Jeddah specialists hold differentiated positions in Red Sea corridor advisory. The market structure concentrates transaction flow through licensed, capitalized intermediaries capable of absorbing REGA compliance costs. Three archetypes dominate: global network firms with cross-border capital markets desks, regional specialists with giga-project track records, and emerging proptech-enabled platforms. Competitive moves center on bundled property management integration and municipal preferred-broker status acquisition.
Among global network firms, JLL, CBRE Group, and Colliers International occupy positions defined by service breadth and institutional client relationships. JLL exemplifies the cross-border capital markets archetype through its advisory presence on Riyadh giga-projects. CBRE Group anchors the industrial-logistics specialization vector serving Red Sea Gateway clients. Colliers International represents the integrated project management tier tied to NEOM and Qiddiya masterplans. These firms compete on regulatory compliance infrastructure, certified agent bench depth, and municipal relationship networks rather than price alone.
| Leading Market Players |
|---|
| JLL |
| CBRE Group |
| Colliers International |
| Savills |
| Knight Frank |
| Hamptons International Saudi Arabia |
| Al Saedan Real Estate Co. |
| Sumou Real Estate |
| Saudi Real Estate Company |
| Others |
Pricing and Supply Chain Analysis
Certified agent scarcity versus proptech-enabled scale creates a sharp bifurcation in Saudi Arabia's brokerage market, compressing margins for traditional operators while concentrating pricing power with capitalized intermediaries capable of absorbing REGA compliance infrastructure costs. This divergence manifests in fee structures that reward bundled property management capabilities and giga-project track records, while smaller independents face fixed-cost disadvantages from mandatory professional indemnity coverage.
Pricing Analysis
Volume concentration in residential brokerage under Sakani mortgage expansion generates thin per-transaction margins, while commercial and industrial advisory commands premium fee structures from institutional capital seeking stabilized income assets. Price differentiation rests on certification tier—REGA-licensed agents with SFDA fund advisor credentials capture sovereign wealth mandates—and bundled service depth, with property management integration increasingly table stakes. Pricing pressure stems from proptech platforms compressing search friction and commission realization timelines. Individual buyers accessing subsidized mortgage products exhibit highest price sensitivity; sovereign wealth funds and REIT sponsors demonstrate lowest sensitivity given mandate-driven deployment requirements.
Supply Chain Analysis
Reverse-logistics considerations are minimal in pure brokerage services, though property management operations generate refurbishment and tenant improvement workflows that feed back into advisory relationships. Brokerage capability concentrates in Saudi Arabia's Riyadh and Jeddah metropolitan corridors, with specialized industrial expertise clustering around Red Sea Gateway developments. The talent pipeline draws from certified training programs, cross-border capital markets experience, and municipal relationship networks. Supply chain risk centers on single-source vulnerability: REGA-mandated instructor capacity constraints limit qualified agent availability. Distribution runs through licensed intermediary networks, with transaction flow concentrating through preferred broker relationships with state-linked developers and giga-project sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's real estate brokerage market operates as a vertical-integration race, with winners capturing downstream property management revenue and upstream municipal preferred-broker status. Players are pursuing backward integration into operational oversight capabilities to lock in multi-year institutional mandates.
For Market Incumbents: Deepen property management bundling to defend against proptech-enabled disintermediation, while securing preferred-broker status with NEOM and Qiddiya masterplan developers. REGA's tightening professional indemnity requirements threaten smaller competitors; incumbents should absorb compliance infrastructure costs to compress the independent broker population further. Capacity addition in Red Sea coastal corridor advisory teams captures logistics and tourism development flows. For New Entrants and Emerging Players: SFDA licensing requirements for real estate investment fund advisors in Saudi Arabia open a window for specialized capital markets advisory boutiques serving REIT formation mandates. White-space targets include industrial-logistics brokerage around Red Sea Gateway bonded zones and tenant representation services for Jeddah corporate occupiers. Go-to-market angle: proptech platform integration with virtual property tours and blockchain-based deed transfer capabilities to accelerate transaction velocity. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier operators possessing REGA compliance infrastructure and giga-project track records given consolidation pressure from regulatory cost burdens. Long-term viability favors full-service platforms spanning transaction execution through operational oversight, positioned for foreign ownership rule relaxation and institutional landlord demand expansion. Signal to watch: municipal land release schedule acceleration in Riyadh's northern corridor as inflection indicator for transaction volume recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Property Management Integration | Bundled operational oversight captures REIT mandates and multi-year institutional engagement terms. |
| REGA Certification Investment | Professional indemnity infrastructure and certified agent bench depth compress independent competitor populations. |
| Giga-Project Advisory Track Record | NEOM and Qiddiya masterplan relationships concentrate transaction flow through preferred intermediaries. |
| Proptech Platform Deployment | Digital listing aggregation and blockchain deed transfers reduce settlement timelines from weeks to days. |
| Red Sea Corridor Specialization | Industrial-logistics expertise around port expansion and bonded zones attracts institutional capital placement. |
Research Methodology
REGA licensing databases, Saudi Central Bank mortgage origination statistics, and municipal land transaction records formed the secondary backbone, supplemented by SEC filings from listed real estate developers and proptech platform disclosures. Primary interviews with brokerage managing directors, REGA compliance officers, institutional investor real estate allocation heads, and property management operations leads validated segmentation assumptions and competitive positioning. Bottom-up transaction volume estimates triangulated against top-down giga-project investment flow projections.
Bottom-up modeling aggregated service-line transaction velocity across residential, commercial, and industrial categories, while top-down analysis tracked Vision 2030 housing target implementation and sovereign wealth deployment patterns. Segmentation dimensions included service type, customer archetype, property class, and transaction mechanism, with regional clustering by metropolitan corridor. CAGRs derived from historical transaction tax collection trends and mortgage guarantee program expansion trajectories, incorporating REIT formation pipeline and foreign ownership rule relaxation as demand-side inputs.
Caveats apply where REGA regulatory harmonization delays, Saudi Central Bank debt-to-income cap adjustments, or municipal land release schedule disruptions could materially shift the outlook. Forecasts embed assumptions regarding giga-project delivery timelines and institutional capital allocation continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Flexible Office Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
North America Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market