
 China Co Working Office Space Market | 2026-2036
China Co Working Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
China Co Working Office Space Market Insights
The gap between premium flexible workspace and commodity co-working is realigning as landlords in Beijing and Shanghai retrofit Grade-A towers for enterprise clients while secondary cities absorb standardized hot-desk inventory. Ucommune leverages its domestic network density to sustain occupancy rates across tier-one hubs. KR Space differentiates through design-led private offices targeting creative industry tenants. SOHO 3Q controls prime real estate in Beijing's Chaoyang district, anchoring its position through developer-backed asset ownership.
Co working office space denotes commercially leased environments where multiple unrelated occupants share infrastructure, typically provisioned with internet bandwidth exceeding 100 Mbps per workstation, climate control systems, and modular furniture systems configurable within 24-hour turnaround cycles. The primary purpose centers on reducing capital expenditure for occupiers while supplying landlord operators with yield premiums over traditional long-term leases. Private office configurations capture the deepest margin pools as enterprises trade fixed costs for operational flexibility. Meeting room bookings are expanding fastest among hybrid-work teams seeking episodic collaboration venues. Hot desk arrangements remain mature among solo freelancers with limited pricing power.
MIIT's broadband infrastructure mandates and SAMR's commercial lease disclosure rules shape operator compliance costs and tenant transparency requirements across Chinese municipalities. GB standards for indoor air quality and fire safety in multi-tenant buildings directly influence fit-out specifications and recurring certification spend. Stakeholders must monitor how local dual carbon enforcement timelines affect building retrofit obligations and operating expense pass-through structures.
Market Dynamics
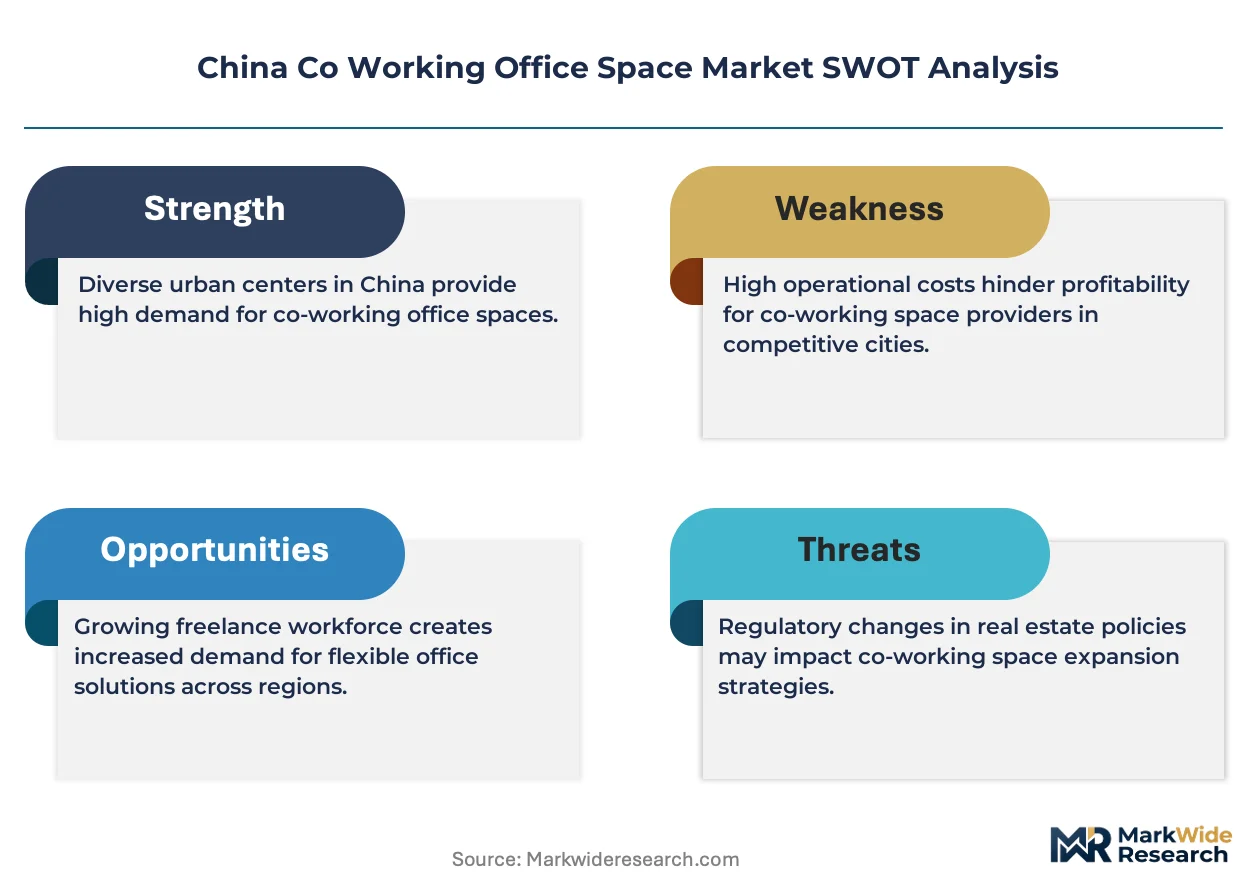
China's dual carbon goals are compressing building retrofit timelines across tier-one cities, forcing landlords and operators to absorb upfront capital costs for energy efficiency upgrades while recalibrating lease structures to pass through compliance expenses.
Growth Catalysts
- MIIT Broadband Mandates:The ministry's infrastructure requirements guarantee high-speed connectivity as a baseline utility, reducing tenant friction during space selection and shortening sales cycles for operators.
- Creative Industry Clustering:Design studios and content production houses in Shanghai and Shenzhen are consolidating into flexible private offices, generating sustained demand for configurable workspace environments.
- Enterprise Hybrid Work Normalization:Technology and financial services firms are shedding fixed headquarters footprints in favor of distributed hub-and-spoke models anchored by co-working satellite locations.
Market Restraints
- Grade-A Supply Concentration:Premium flexible inventory clusters in Beijing's Chaoyang and Shanghai's Lujiazui districts, creating localized oversupply risk and pricing pressure during demand troughs.
- GB Standard Compliance Costs:Indoor air quality and fire safety certification requirements impose recurring fit-out expenditures that compress operator margins on short-term memberships.
- Traditional Lease Substitution:Landlords in secondary cities retain negotiating power through conventional long-term contracts, limiting flexible workspace penetration outside tier-one hubs.
Strategic Opportunities
- Shenzhen Qianhai Expansion:The special economic zone's technology sector concentration remains underserved by design-forward flexible workspace, creating white space for differentiated operators.
- SAMR Lease Transparency Rules:Commercial disclosure mandates are standardizing contract terms, reducing tenant acquisition friction and enabling faster portfolio scaling across municipalities.
- Building Management System Convergence:Integration of IoT sensors with energy management platforms is creating premium service tiers that command membership rate premiums from sustainability-focused enterprises.
Industry Challenges
- Carbon Accounting Expertise Gap:Operators lack in-house capability to measure and report Scope 2 emissions under evolving municipal dual carbon enforcement timelines, forcing reliance on third-party consultants.
- Legacy HVAC Integration:Retrofitting centralized climate systems in 1990s-era towers for zoned, metered billing requires complex engineering coordination with building management committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Co Working Office Space Market |
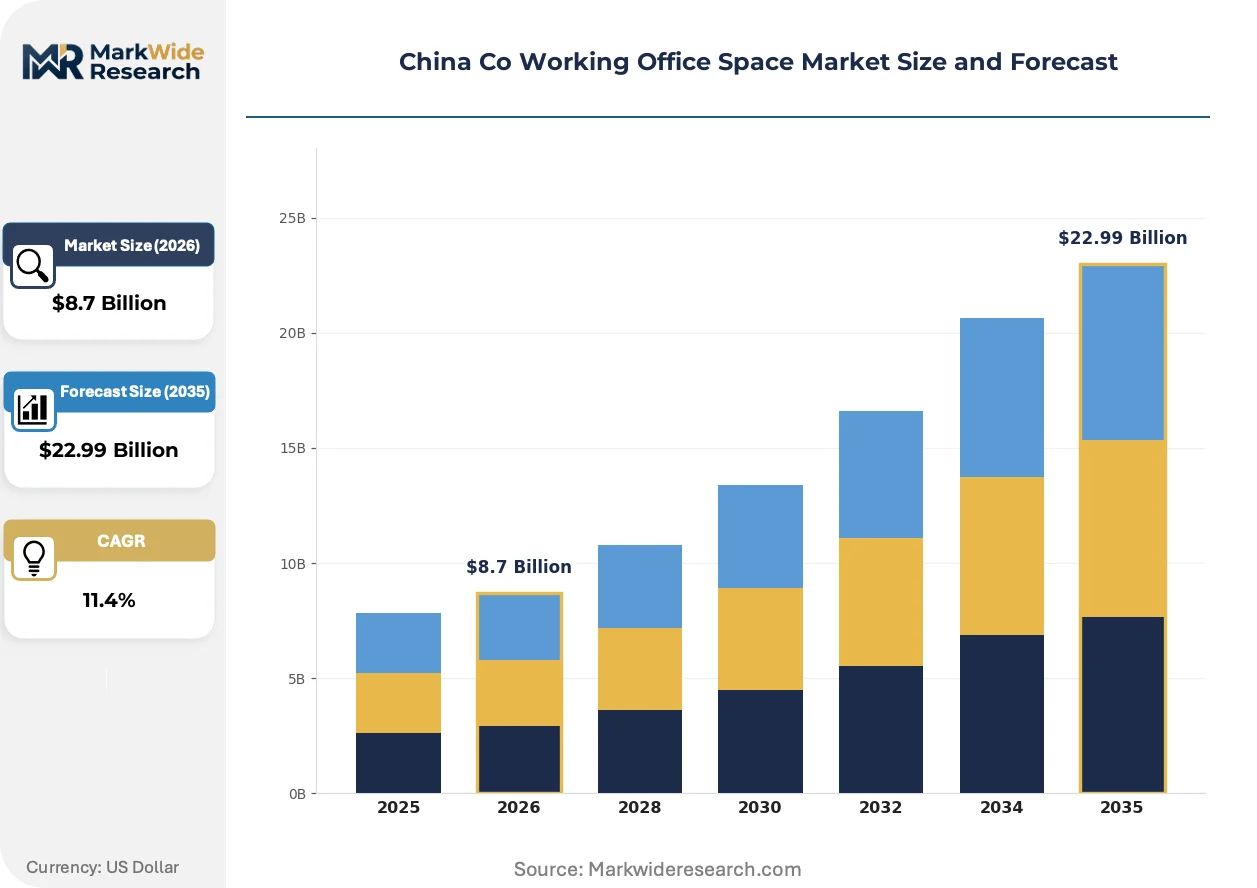
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Desk, Dedicated Desk, Private Office, Meeting Room Pricing Model: Hourly, Daily, Monthly, Membership End User: Freelancers, Startups, SMEs, Enterprises Service Type: Virtual Office, Event Space, Collaboration Space, Flexible Workspace |
| Companies Covered | WeWork, Regus, ServCorp, Ucommune, KR Space, People Squared, SOHO 3Q, MyDreamPlus, The Executive Centre, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Co Working Office Space Market Trends and Innovations
Workspace technology stacks are converging with building infrastructure, compressing the distinction between physical environment and digital service layer while reshaping how operators monetize square footage.
Smart access control systems leveraging facial recognition and mobile credentialing are integrating with tenant experience platforms to automate space utilization tracking. Enterprise clients in Beijing and Shanghai are deploying these systems across multiple locations to aggregate occupancy analytics. This convergence is integrating real estate operations with workforce management software, blurring procurement categories for corporate real estate departments.
China's dual carbon enforcement timelines are accelerating GB standard revisions for commercial building energy performance. Municipal environmental protection bureaus in Shanghai and Shenzhen are mandating sub-metering disclosure for multi-tenant properties. Premium flexible workspace operators are responding by pursuing green building certifications to differentiate inventory and justify rate premiums from carbon-conscious tenants.
Hybrid work patterns are fragmenting enterprise real estate decision-making, shifting procurement authority from centralized facilities teams to departmental budget holders. Satellite office selection now involves IT security, human resources, and finance stakeholders alongside traditional real estate functions. This diffusion is most pronounced among technology startups in Hangzhou and Chengdu, where distributed team structures complicate space planning and contract negotiation timelines.
China Co Working Office Space Market Segmentation
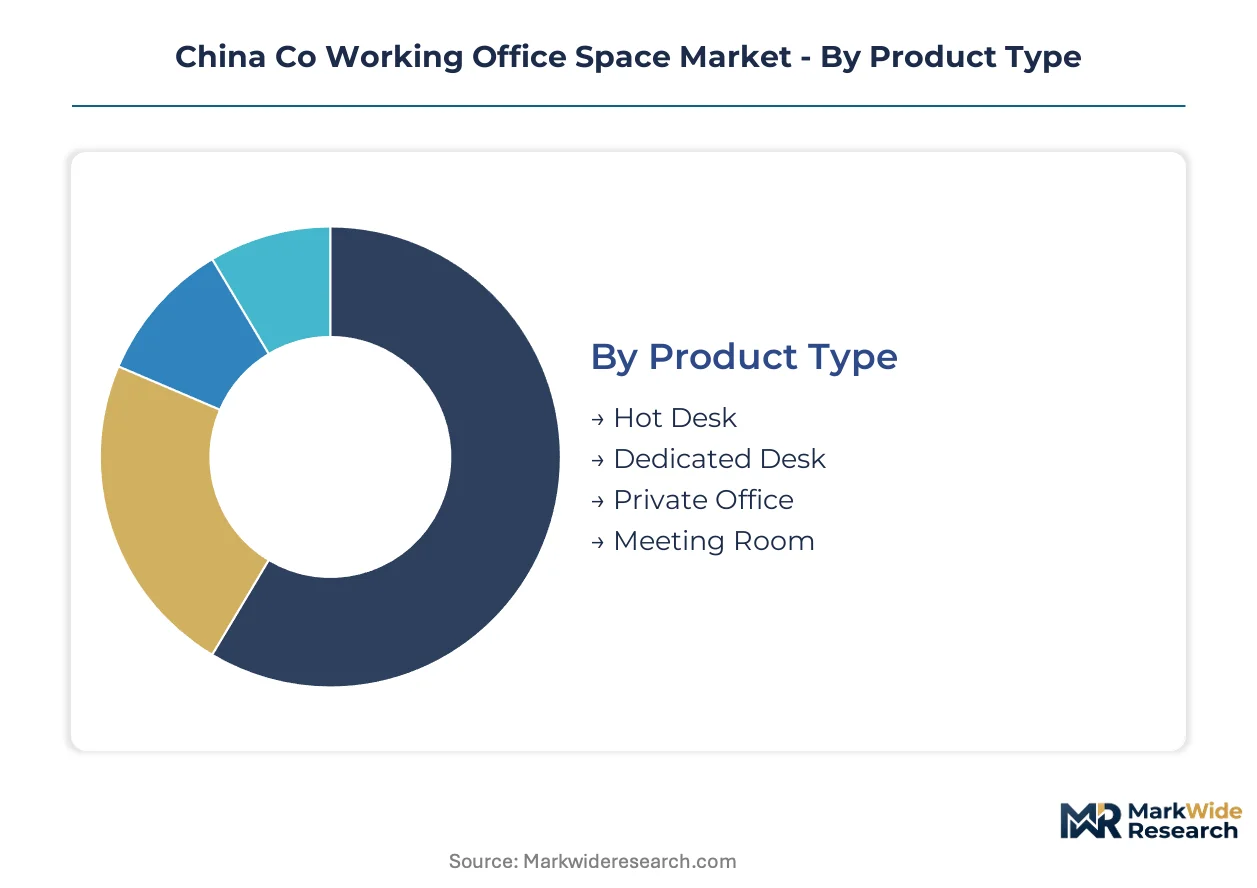
Segmentation in China's co-working market reveals how procurement authority fragments across buyer types and usage patterns. Operators must align product configurations with distinct capital expenditure tolerances and lease flexibility requirements.
Product Type:
Occupiers select workspace formats based on team size permanence and confidentiality requirements.
- Hot Desk:Unassigned seating in open floor plans with 100 Mbps baseline connectivity and 24-hour access credentials. Freelancers in Chengdu and Hangzhou absorb standardized inventory as landlords in secondary cities retain negotiating power through conventional long-term contracts.
- Private Office:Enclosed suites with dedicated climate zones and customizable branding surfaces, typically leased on 3-12 month terms. Enterprises in Shanghai's Lujiazui and Beijing's Chaoyang districts trade fixed costs for operational flexibility, generating the deepest margin pools for operators.
- Dedicated Desk:Permanently assigned workstations in shared areas with lockable storage and reserved power outlets. Small creative teams in Shenzhen's Qianhai zone cluster for episodic collaboration without full enclosure premiums.
- Meeting Room:Bookable enclosed spaces with video conferencing infrastructure and whiteboard systems. Hybrid-work teams deploy these for project sprints, with demand climbing fastest among technology startups normalizing distributed hub-and-spoke models.
Private office leads on scale; meeting room leads on momentum.
Pricing Model:
Payment structures calibrate cash flow predictability against utilization volatility.
- Monthly:Recurring subscriptions with fixed desk or office assignments, preferred by SMEs seeking budget certainty. SAMR's commercial lease disclosure rules reduce tenant acquisition friction for this standardized contract format.
- Membership:Tiered packages bundling workspace access with amenities like printing credits and event space hours. Premium operators leverage these to capture yield premiums over traditional long-term leases through service stacking.
- Hourly:Pay-per-use access for meeting rooms and hot desks, common among episodic users. GB standard compliance costs compress margins on these short-term transactions.
- Daily:Single-day passes for transient workers and visiting teams. This format absorbs overflow demand during peak periods without cannibalizing recurring revenue bases.
Monthly subscriptions anchor revenue stability; membership tiers capture expansion upside.
End User:
Buyer sophistication and procurement authority vary sharply across organizational scale.
- Enterprises:Multinational and domestic corporations with 500+ employees deploying satellite offices. IT security, human resources, and finance stakeholders now join facilities teams in Beijing and Shanghai selection processes, fragmenting decision timelines.
- Startups:Venture-backed technology companies prioritizing scalable footprints and minimal capital lockup. These firms in Hangzhou and Shenzhen are expanding their footprint in flexible workspaces as hybrid work normalizes.
- SMEs:Established small and medium enterprises with 10-100 employees seeking professional addresses without Grade-A tower lease commitments. This segment concentrates in tier-one central business districts where premium inventory clusters.
- Freelancers:Solo practitioners and independent contractors with limited pricing power. Hot desk arrangements remain mature among this group, particularly in secondary cities absorbing standardized inventory.
Enterprises drive contract value; startups drive seat expansion velocity.
Service Type:
Value-added offerings extend beyond physical space into administrative and community functions.
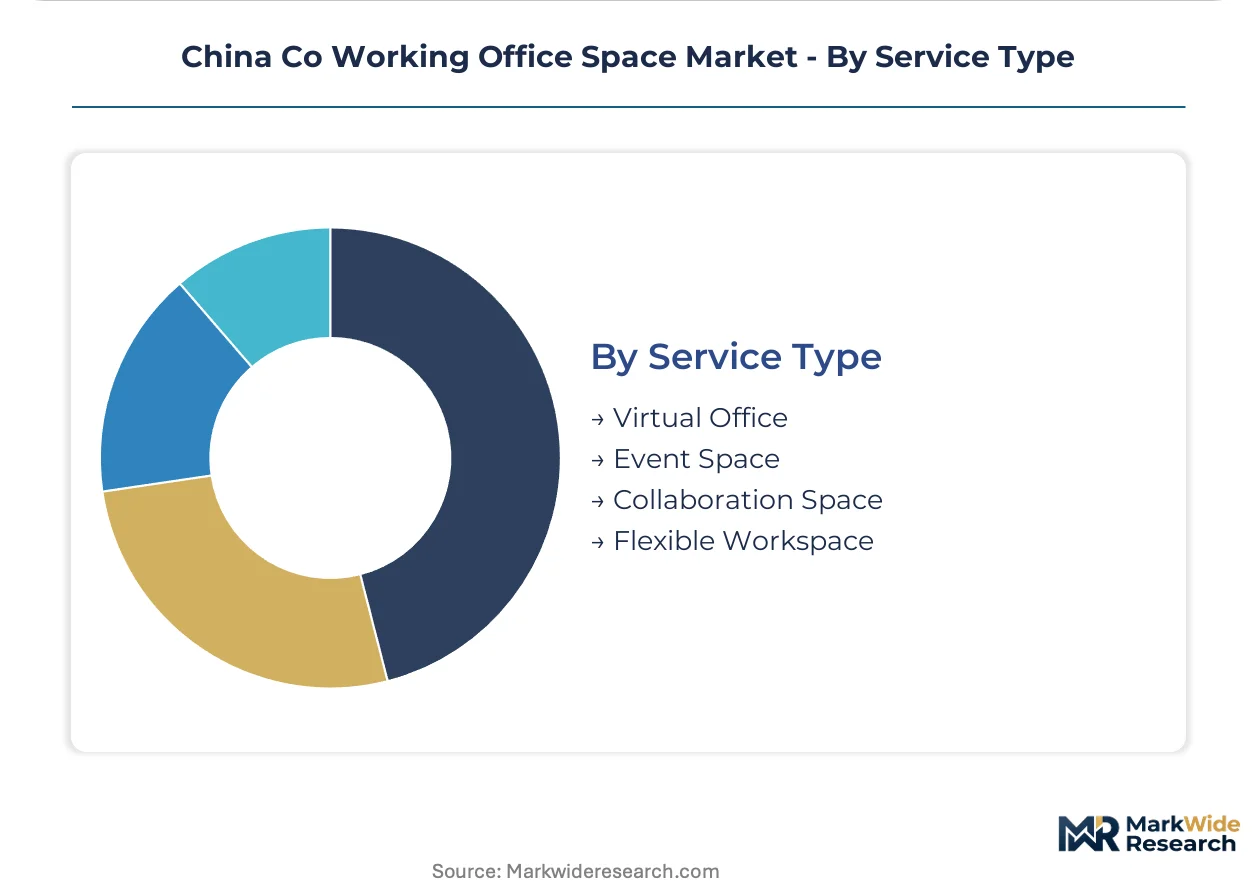
- Flexible Workspace:Core product combining physical infrastructure with operational services like reception and mail handling. MIIT's broadband infrastructure mandates guarantee high-speed connectivity as a baseline utility, reducing tenant friction during selection.
- Virtual Office:Business address registration and mail forwarding without physical occupancy, popular among offshore entities and remote-first companies. Municipal environmental protection bureaus are mandating sub-metering disclosure for multi-tenant properties, affecting cost allocation.
- Event Space:Bookable areas for product launches, training sessions, and networking functions. Creative industry tenants in Shanghai generate sustained demand for configurable environments supporting content production.
- Collaboration Space:Technology-enabled zones designed for team workshops and agile sprints. Integration of IoT sensors with energy management platforms creates premium service tiers commanding rate premiums from sustainability-focused enterprises.
Flexible workspace dominates revenue contribution; collaboration space gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology talent clusters in Shanghai, Beijing, and Shenzhen anchor flexible workspace demand across China's tier-one cities. Secondary hubs in Hangzhou and Chengdu absorb standardized inventory as remote work normalizes. Municipal dual carbon enforcement timelines compress retrofit schedules unevenly across provincial jurisdictions.
Yangtze River Delta
Multinational enterprise regional headquarters concentrate in Shanghai's Lujiazui and Jing'an districts, generating sustained demand for private office configurations. MIIT broadband infrastructure mandates guarantee baseline connectivity standards across Songjiang and Pudong sub-markets. Grade-A tower landlords in Hongqiao Business District retrofit HVAC systems for zoned energy metering ahead of municipal enforcement deadlines.
Pearl River Delta
Venture-backed technology startups in Shenzhen's Qianhai special economic zone expand satellite office footprints under hybrid work policies. SAMR commercial lease disclosure rules standardize contract terms across Guangzhou and Shenzhen municipalities, reducing tenant acquisition friction. Dongguan and Foshan manufacturing headquarters deploy flexible workspace for episodic engineering team collaboration.
Beijing-Tianjin-Hebei
State-owned enterprise technology spinoffs and fintech subsidiaries cluster in Beijing's Chaoyang and Haidian districts. GB standards for indoor air quality and fire safety impose recurring certification costs on multi-tenant building operators. Tianjin's Binhai New Area absorbs overflow demand from capital-constrained SMEs seeking professional addresses without core city premiums.
Sichuan-Chongqing
Game development studios and content production houses in Chengdu's Tianfu Software Park drive demand for design-led private offices. Local environmental protection bureaus mandate sub-metering disclosure timelines that lag coastal municipalities by 12-18 months. Chongqing's Liangjiang New Zone attracts distributed teams from coastal headquarters seeking lower operational cost bases.
Shandong Peninsula
Industrial technology SMEs in Qingdao and Jinan trade conventional long-term leases for flexible workspace as procurement authority fragments to departmental budget holders. Provincial dual carbon implementation guidelines create compliance cost uncertainty for 1990s-era tower retrofits. Yantai and Weihai satellite offices serve episodic client meeting requirements for sales teams covering northern coastal markets.
China Co Working Office Space Market Competitive Landscape
Top-tier vendors anchor prime real estate positions in Beijing and Shanghai central business districts, while mid-tier operators compete on network density across tier-two cities. The market structure fragments between developer-backed asset owners and pure-play operators leasing third-party space. Three archetypes dominate: domestic network-scale platforms, design-differentiated boutique operators, and international brand licensees. Competitive moves concentrate on portfolio diversification into satellite cities and vertical integration into building management system deployment.
Among domestic network-scale operators, Ucommune leverages tier-one hub density to sustain occupancy rates across standardized inventory configurations. KR Space occupies a position within the design-differentiated tier, targeting creative industry tenants through configurable private office environments. SOHO 3Q exemplifies the developer-backed archetype, controlling prime Chaoyang district assets through direct ownership structures rather than lease arbitrage.
| Leading Market Players |
|---|
| WeWork |
| Regus |
| ServCorp |
| Ucommune |
| KR Space |
| People Squared |
| SOHO 3Q |
| MyDreamPlus |
| The Executive Centre |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement teams in Beijing and Shanghai are consolidating vendor lists under hybrid work policies, forcing operators to absorb GB standard compliance costs for indoor air quality certification while recalibrating membership tiers to capture yield premiums from sustainability-focused tenants.
Pricing Analysis
Bundled membership tiers separating flexible workspace access from amenities like event space hours and printing credits dominate revenue architecture. Three-tier pricing structure across premium, standard, and economy levels tracks GB certification status and building energy performance grades. Pricing pressure stems from Grade-A supply concentration in Chaoyang and Lujiazui districts compressing margins on short-term hourly bookings. Freelancers in secondary cities exhibit highest price sensitivity, while enterprise satellite office deployers accept premium rates for green building credentials.
Supply Chain Analysis
Dual-sourcing requirements from enterprise clients mandate operators qualify multiple HVAC retrofit contractors and IoT sensor vendors across Beijing, Shanghai, and Shenzhen. Fit-out specifications draw from modular furniture systems in Guangdong, climate control equipment in Jiangsu, and smart access hardware in Zhejiang. Single-source vulnerability concentrates in legacy building management committees controlling 1990s-era tower retrofits. Distribution runs through direct landlord partnerships in tier-one central business districts and third-party lease arbitrage in tier-two expansion markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in China's co-working market rests on operational leverage from enterprise contract scaling and premium-tier green certification uptake that commands rate premiums from carbon-conscious tenants.
For Market Incumbents: Anchor occupancy stability through developer-backed asset ownership structures that eliminate lease arbitrage exposure, while investing in building management system convergence to capture enterprise clients fragmenting procurement authority across IT security and human resources stakeholders. Defend against pure-play operators by deepening backward integration into energy management platform deployment. For New Entrants and Emerging Players: Channel partners specializing in technology startup ecosystem access offer the most viable entry vector. White space concentrates in Shenzhen Qianhai's underserved design-forward flexible workspace segment and Chengdu's game development studio cluster. Target creative industry tenants through configurable private office environments with rapid branding surface turnaround. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier operators controlling network density across tier-two cities with established SAMR lease transparency compliance infrastructure. Long-term viability favors platforms with direct asset ownership capable of absorbing dual carbon retrofit timelines without third-party landlord coordination friction. Watch municipal environmental protection bureau sub-metering disclosure mandates as inflection indicator for green premium capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Green Building Certification Pursuit | GB standard compliance enables rate premiums from carbon-conscious enterprise tenants in Shanghai. |
| Building Management System Integration | IoT sensor convergence with energy platforms creates premium service tiers for sustainability-focused clients. |
| Tier-Two City Network Expansion | Hangzhou and Chengdu absorption of standardized inventory captures remote work normalization demand. |
| Enterprise Satellite Office Partnership | Hub-and-spoke deployment models anchor recurring revenue from technology and financial services firms. |
| Landlord Direct Asset Ownership | Developer-backed structures eliminate lease arbitrage exposure and compress retrofit coordination timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flexible workspace operators, commercial real estate developers, enterprise facilities managers, and municipal environmental protection bureau officials with secondary validation against MIIT infrastructure disclosures, SAMR commercial lease filings, and GB standard revision documents. Bottom-up seat inventory aggregation and top-down addressable market sizing were cross-referenced for triangulation.
Segment-weighting across product type, pricing model, end user category, and service tier dimensions anchored the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves calibrated to occupancy rate trajectories and membership expansion velocity in tier-one versus tier-two city clusters. Forecast inputs incorporated dual carbon enforcement timeline scenarios and broadband infrastructure mandate rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to municipal retrofit obligation timelines and enterprise hybrid work policy permanence. Deviation in MIIT broadband infrastructure investment pacing or SAMR disclosure rule enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
North America Flexible Office Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Flexible Office Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
China Office Real Estate Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
Latin America Office Real Estate Market