
 Canada Office Real Estate Market | 2026-2036
Canada Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Office Real Estate Market Outlook
Cross-laminated timber is restructuring structural material economics in Canadian office construction, reducing embodied carbon and accelerating permit timelines for mid-rise developments. Cadillac Fairview leverages its national portfolio to anchor premium Class A supply in Toronto and Calgary. Brookfield Asset Management sustains global capital flows into Canadian office assets through its infrastructure-linked investment platforms. Allied Properties REIT specializes in creative studio conversions, repurposing industrial heritage buildings into technology-tenant environments.
Canada office real estate encompasses income-producing commercial buildings designed for professional services occupancy, typically featuring floor plates of 15,000 to 40,000 square feet, HVAC systems targeting LEED Gold or Platinum certification, and base building infrastructure supporting dense digital connectivity. Class A offices command the deepest tenant pools and longest lease terms, while business parks outside Vancouver and Montreal attract back-office operations seeking lower per-square-foot costs. Triple net lease structures dominate institutional investment mandates, transferring operating expense volatility to tenants and stabilizing net operating income projections for core asset strategies.
Health Canada and the National Building Code of Canada shape indoor air quality and seismic resilience standards that directly affect retrofit capital requirements. CMHC's green building incentive programs and municipal inclusionary zoning bylaws in Toronto and Vancouver alter site feasibility calculations for new office supply. Stakeholders must monitor interest rate trajectories and hybrid work permanence to calibrate development starts against lease rollover schedules.
Market Dynamics
Hybrid work permanence is compressing lease rollover timelines across Canadian office portfolios, forcing landlords to front-load tenant improvement allowances and accelerate amenity upgrades to retain technology and professional services tenants.
Growth Catalysts
- Transit-oriented development bylaws:Municipal density incentives in Toronto and Vancouver are accelerating permit approvals for office projects within 800 meters of rapid transit stations.
- Technology sector expansion:Artificial intelligence and fintech firms are absorbing Class A floor plates in downtown Calgary and Montreal, displacing traditional energy and legal tenants.
- Green building certification mandates:The federal government's green building standards for federal lease renewals are pulling private landlords toward LEED Platinum and Net Zero Carbon upgrades.
Market Restraints
- Construction cost escalation:Cross-laminated timber and mass timber supply concentrates in British Columbia and Quebec, exposing developers to regional fiber availability constraints and volatile freight costs.
- Zoning fragmentation:Inclusionary zoning bylaws in Toronto and Vancouver impose affordable housing set-asides that erode office development yields and extend entitlement timelines.
- Interest rate sensitivity:Institutional capital deployment into Canadian office assets tracks Bank of Canada policy rate movements, compressing acquisition cap rates and freezing development starts during tightening cycles.
Strategic Opportunities
- Heritage asset repositioning:Industrial loft conversions in Montreal's Griffintown and Toronto's Liberty Village attract creative economy tenants seeking authentic character space unavailable in new construction.
- CMHC green financing:The agency's low-carbon building incentive programs reduce effective borrowing costs for developers achieving Net Zero Energy Performance standards.
- Life sciences crossover:Wet lab infrastructure requirements in Vancouver's Mount Pleasant and Toronto's Waterfront Innovation Centre are blurring traditional office and laboratory typologies.
Industry Challenges
- Building systems integration:Retrofitting 1980s vintage office towers with smart building platforms and electrified HVAC conflicts with existing base building infrastructure and tenant occupancy schedules.
- Carbon accounting complexity:Scope 3 emissions disclosure requirements under the National Building Code of Canada and municipal benchmarking bylaws demand new data collection capabilities most property managers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Office Real Estate Market |
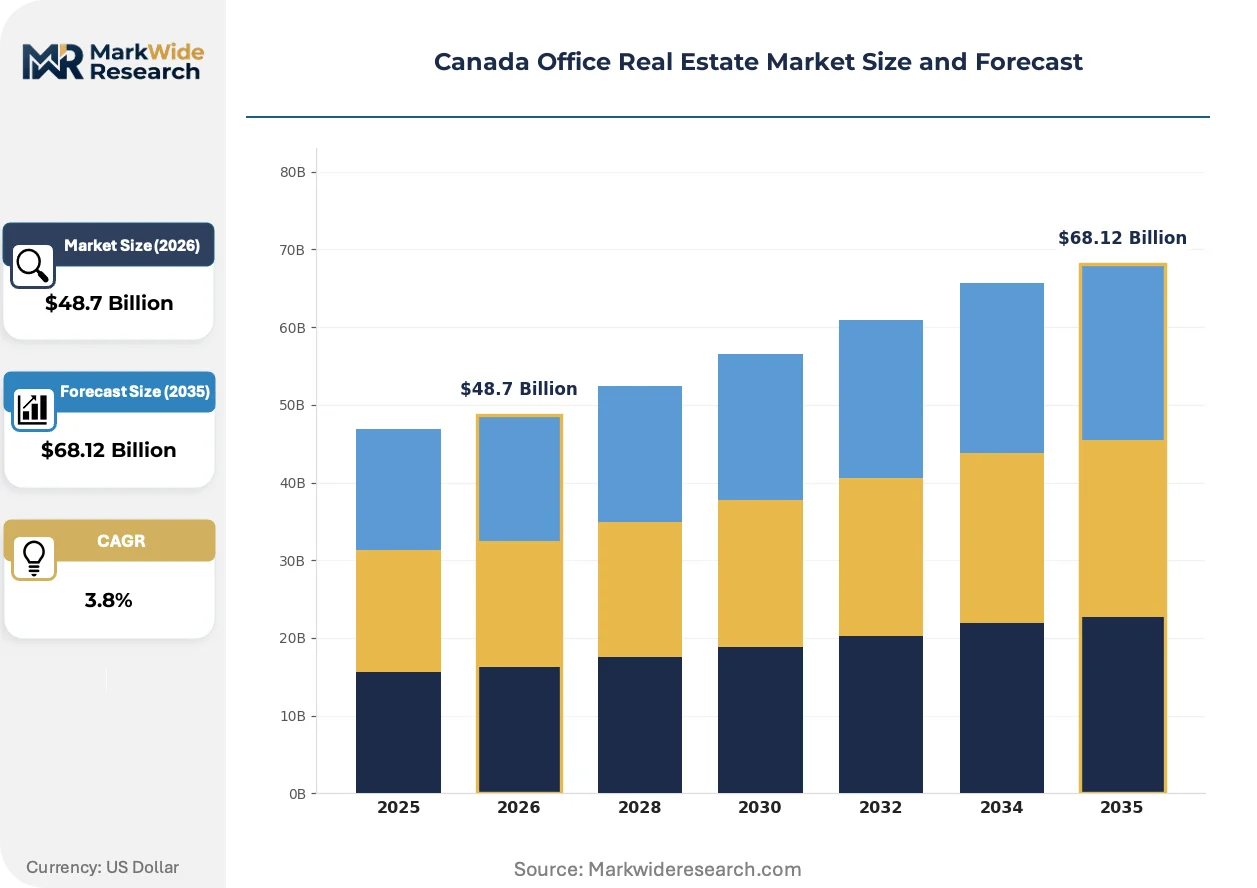
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $68.12 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Class A Offices, Class B Offices, Business Parks, Multi-Tenant Buildings, Single-Tenant Buildings Tenant Industry: Technology Firms, Financial Services, Legal Services, Consulting Agencies, Creative Studios Lease Structure: Triple Net Lease, Gross Lease, Modified Gross Lease, Percentage Lease, Full Service Lease Investment Type: Core Assets, Value-Add Properties, Opportunistic Investments, Stabilized Assets, Development Projects |
| Companies Covered | Cadillac Fairview, Choice Properties Real Estate Investment Trust, Brookfield Asset Management, FirstService Corporation, Colliers International Group, Oxford Properties Group, Allied Properties Real Estate Investment Trust, Morguard, Ivanhoé Cambridge, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Office Real Estate Market Strategic Shifts
Canadian office development is pivoting from speculative construction toward build-to-suit and pre-leased structures, with landlords absorbing design risk to secure long-term technology and life sciences tenants before breaking ground.
Mass timber structural systems are rewriting development economics for mid-rise office buildings across Canadian urban centers. Developers in Vancouver and Toronto are specifying glulam columns and CLT floor plates to reduce embodied carbon by 40 percent versus conventional steel. Health Canada and the National Building Code of Canada are accelerating permit pathways for timber structures up to 12 storeys, compressing entitlement timelines by six to nine months.
The federal government's green building standards and municipal benchmarking bylaws in Toronto and Vancouver are mandating operational carbon disclosure for buildings over 50,000 square feet. Landlords must now report energy intensity and greenhouse gas emissions annually or face lease ineligibility for federal and provincial tenancies. Class A assets in downtown Calgary and Montreal are retrofitting building automation systems to capture granular utility data.
Tenants are compressing decision cycles and demanding shorter initial lease terms with expansion options rather than traditional 10-year commitments. Technology firms in Vancouver's transit-oriented clusters and Toronto's downtown core are negotiating 3-year base terms with renewal rights tied to headcount triggers. Landlords are responding with modular interior build-outs and furniture-as-a-service partnerships to accelerate occupancy and reduce tenant capital burdens.
Canada Office Real Estate Market Segmentation
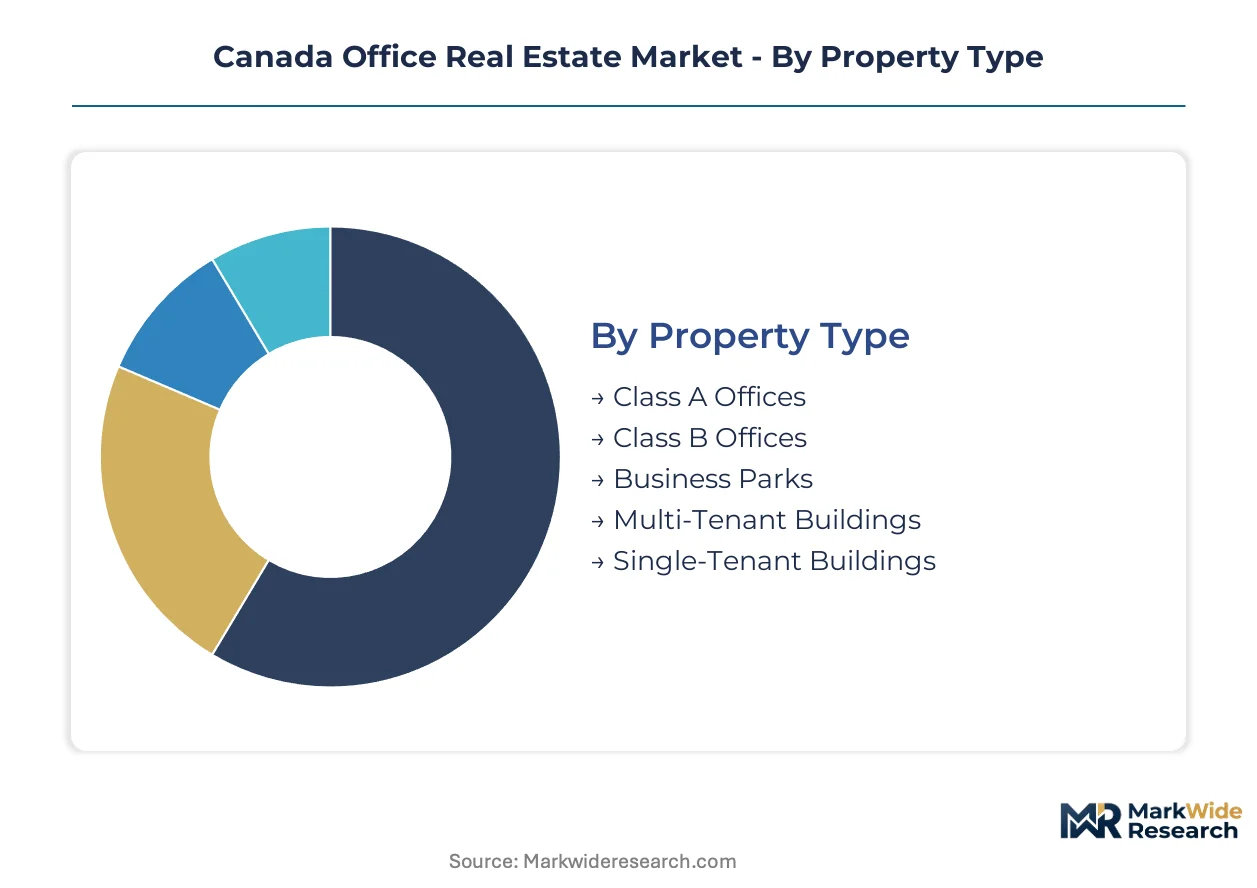
Canadian office real estate segmentation reveals divergent capital deployment strategies across risk-return profiles. Property type and lease structure classifications determine institutional mandate alignment, while tenant industry mix shapes locational preferences within Toronto, Vancouver, and Calgary submarkets.
Property Type:
Volume concentrates in mid-tier assets, while premium product commands institutional capital premiums.
- Class A Offices:These assets feature floor plates exceeding 25,000 square feet, LEED Gold or Platinum certification, and redundant digital infrastructure. Demand concentrates in Toronto's Financial District and Vancouver's Broadway Corridor, where technology and professional services tenants absorb space despite hybrid work pressures.
- Class B Offices:Typically 15-25 years old with functional but dated systems, these properties trade at yield premiums to Class A. Calgary's Beltline and Montreal's Ville-Marie attract value-add investors targeting renovation-driven rent resets.
- Business Parks:Low-rise campuses in suburban nodes serve back-office operations seeking parking ratios above 3.0 per 1,000 square feet.
- Multi-Tenant Buildings:Diversified rent rolls reduce single-tenant rollover risk for core income strategies.
- Single-Tenant Buildings:Credit-tenant lease structures appeal to insurance company mandates seeking bond-like cash flow profiles.
Today's leader: Class A Offices. Tomorrow's challenger: Business Parks.
Tenant Industry:
Application-driven segmentation maps tenant credit quality against space customization requirements.
- Technology Firms:These tenants demand dense power allocation, flexible lease structures, and amenity-rich environments. Toronto's downtown core and Vancouver's Mount Pleasant cluster absorb expansion from artificial intelligence and fintech subsectors.
- Financial Services:Banks and asset managers anchor Class A towers with long-dated lease commitments and minimal improvement allowances.
- Legal Services:Traditional ten-year terms with high tenant improvement contributions persist in Calgary and Montreal central business districts.
- Consulting Agencies:Hybrid work policies compress footprint requirements while elevating quality-per-square-foot demands.
- Creative Studios:Allied Properties REIT and similar landlords convert industrial heritage buildings in Liberty Village and Griffintown to serve this segment.
Financial Services currently anchor rent rolls. Technology Firms are climbing the fastest as lease rollover drivers.
Lease Structure:
Cost transfer mechanisms align landlord risk tolerance with tenant operational control preferences.
- Triple Net Lease:Tenants assume property tax, insurance, and maintenance obligations. Institutional investors favor this structure for stabilized income predictability in core Canadian office mandates.
- Gross Lease:Landlords absorb operating expense volatility, common in shorter-term creative studio arrangements.
- Modified Gross Lease:Expense stops and base year calculations split risk between parties.
- Percentage Lease:Rare in office, occasionally appearing in mixed-use retail-office hybrid assets.
- Full Service Lease:All-inclusive rents simplify budgeting for professional services tenants with limited facility management capacity.
Triple Net Lease dominates institutional allocations. Modified Gross Lease is gaining share fastest as hybrid work complicates expense forecasting.
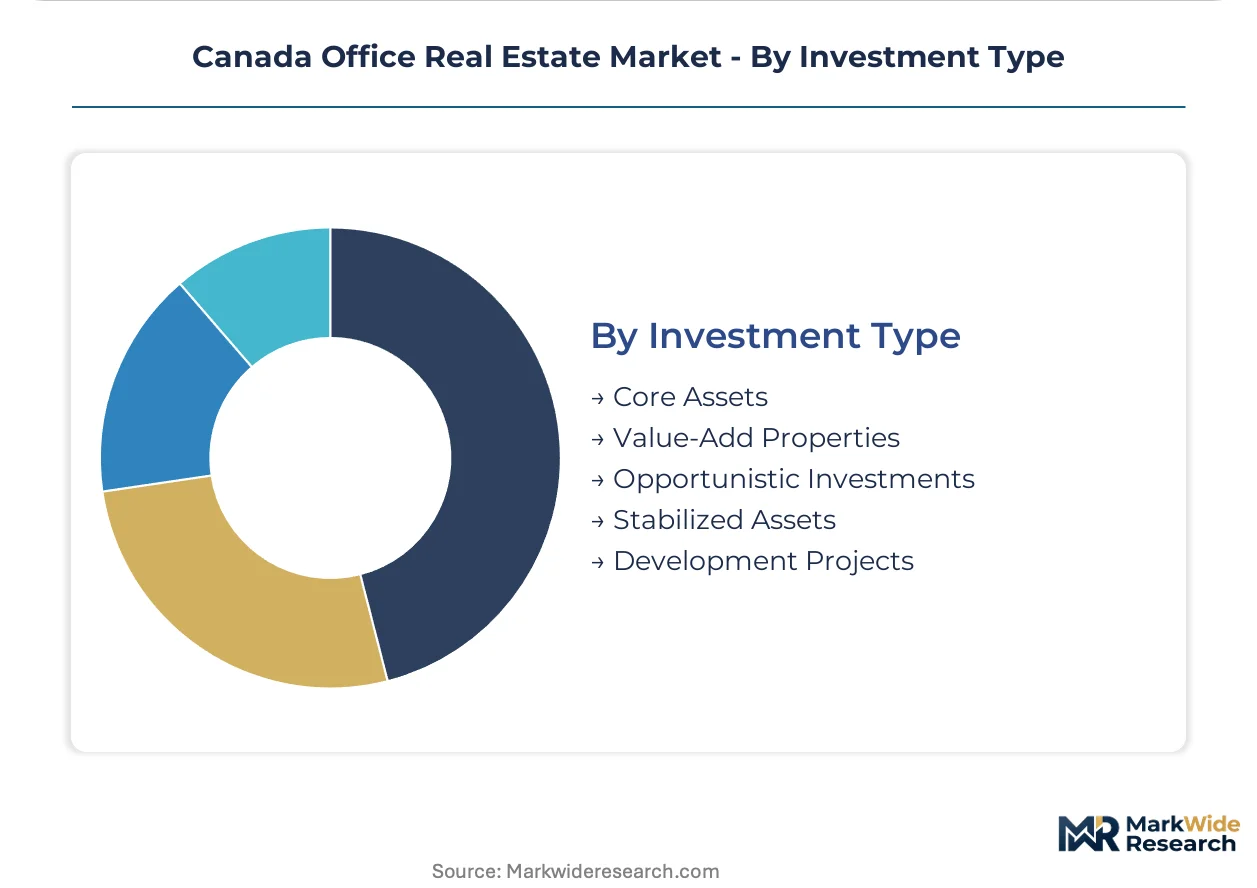
Investment Type:
Risk-return positioning stratifies capital sources from pension funds to opportunistic vehicles.
- Core Assets:Fully leased, stabilized properties in primary markets with minimal capital requirements. Canada Pension Plan Investment Board and similar entities concentrate Toronto and Vancouver allocations here.
- Value-Add Properties:Leasing upside or renovation-driven rent growth potential in secondary locations.
- Opportunistic Investments:Distressed acquisitions or development plays with higher leverage profiles.
- Stabilized Assets:Near-core product with modest lease rollover exposure over five-year hold periods.
- Development Projects:Ground-up construction or major repositioning requiring entitlement risk absorption.
Core Assets anchor pension fund portfolios. Value-Add Properties present the steepest expansion trajectory as interest rate stabilization unlocks transaction velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toronto's Financial District concentrates the deepest tenant pools and longest lease terms in Canadian office real estate. Provincial growth patterns diverge sharply based on energy sector exposure, technology sector migration, and transit infrastructure maturity.
Ontario
Technology firms and financial services anchor Class A absorption in Toronto's downtown core and Waterloo-Toronto corridor. Municipal density bylaws in Toronto accelerate permit approvals for transit-oriented office developments within 800 meters of subway stations. Ottawa's federal government tenancy stabilizes occupancy in the National Capital Region despite hybrid work pressures.
Quebec
Artificial intelligence research clusters and fintech expansion drive demand in Montreal's Ville-Marie and Griffintown districts. The provincial government's green building incentives complement federal standards for federal lease renewals. Cross-laminated timber construction concentrates in Quebec City's emerging office nodes, reducing embodied carbon for mid-rise developments.
British Columbia
Vancouver's Broadway Corridor and Mount Pleasant cluster absorb technology tenant expansion seeking transit-adjacent space. The provincial building code accelerates permit pathways for mass timber structures up to 12 storeys, compressing entitlement timelines. CMHC green financing programs reduce effective borrowing costs for developers achieving Net Zero Energy Performance in Vancouver's downtown peninsula.
Alberta
Calgary's Beltline and downtown core attract technology firms displacing traditional energy sector tenants in Class A towers. The city's inclusionary zoning bylaws impose affordable housing set-asides that erode office development yields. Business parks in suburban Calgary nodes serve back-office operations seeking parking ratios above 3.0 per 1,000 square feet.
Atlantic Canada
Halifax's emerging technology sector and federal government tenancy stabilize occupancy in smaller Class B assets. Provincial economic development programs incentivize creative economy conversions of heritage industrial buildings. St. John's energy sector exposure creates vacancy pressure in 1980s-vintage office towers requiring substantial retrofit capital.
Canada Office Real Estate Market Competitive Environment
Global majors compete with regional champions across capital deployment strategies and asset specialization dimensions. The market exhibits tiered consolidation with institutional landlords dominating core Class A supply and mid-cap operators capturing value-add opportunities. Three archetypes predominate: national portfolio landlords with multi-provincial scale, specialized creative space converters, and infrastructure-linked global capital platforms. Competitive positioning hinges on portfolio diversification into life sciences and technology segments, alongside strategic partnerships with municipal transit authorities for density-bonus entitlements.
Within the national portfolio tier, Cadillac Fairview anchors premium Class A supply concentration in Toronto and Calgary through its national development pipeline. Allied Properties REIT exemplifies the creative conversion archetype, repurposing industrial heritage buildings in Liberty Village and Griffintown for technology-tenant environments. Brookfield Asset Management occupies the infrastructure-linked capital platform position, sustaining global capital flows into Canadian office assets through dedicated investment vehicles. These three entities collectively represent the strategic positioning spectrum available to institutional capital seeking Canadian office exposure.
| Leading Market Players |
|---|
| Cadillac Fairview |
| Choice Properties Real Estate Investment Trust |
| Brookfield Asset Management |
| FirstService Corporation |
| Colliers International Group |
| Oxford Properties Group |
| Allied Properties Real Estate Investment Trust |
| Morguard |
| Ivanhoé Cambridge |
| Others |
Value Chain & Pricing Dynamics
Cross-laminated timber pricing from British Columbia and Quebec fiber mills cascades through Class A office construction budgets, compressing margins for mid-rise developments while accelerating permit timelines that justify premium rents in Toronto and Vancouver transit corridors.
Pricing Analysis
Input-cost pass-through from mass timber and steel volatility is reshaping development pro formas across Canadian urban centers. Pricing stratifies across LEED Platinum-certified premium towers, Gold-standard mid-tier assets, and unrenovated Class B stock in secondary locations. Cost compression in Class B retrofits is intensifying because hybrid work has shortened lease rollover timelines, forcing landlords to front-load tenant improvement allowances. Technology firms demonstrate lowest price sensitivity, absorbing premium rents for amenity-rich environments, while back-office operations in Calgary and Montreal suburban nodes negotiate aggressively on per-square-foot basis.
Supply Chain Analysis
Construction workforce availability in Vancouver, Toronto, and Calgary constrains development velocity despite strong permit pipelines. Mass timber supply draws from British Columbia interior mills and Quebec engineered wood manufacturers, with steel and concrete sourcing anchored in Ontario and Alberta production hubs. Single-source vulnerability concentrates in cross-laminated timber panel fabrication, where three regional producers service national demand. Distribution runs through project-specific direct procurement contracts tied to entitlement timelines, with developers pre-purchasing structural materials to lock in costs before groundbreaking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
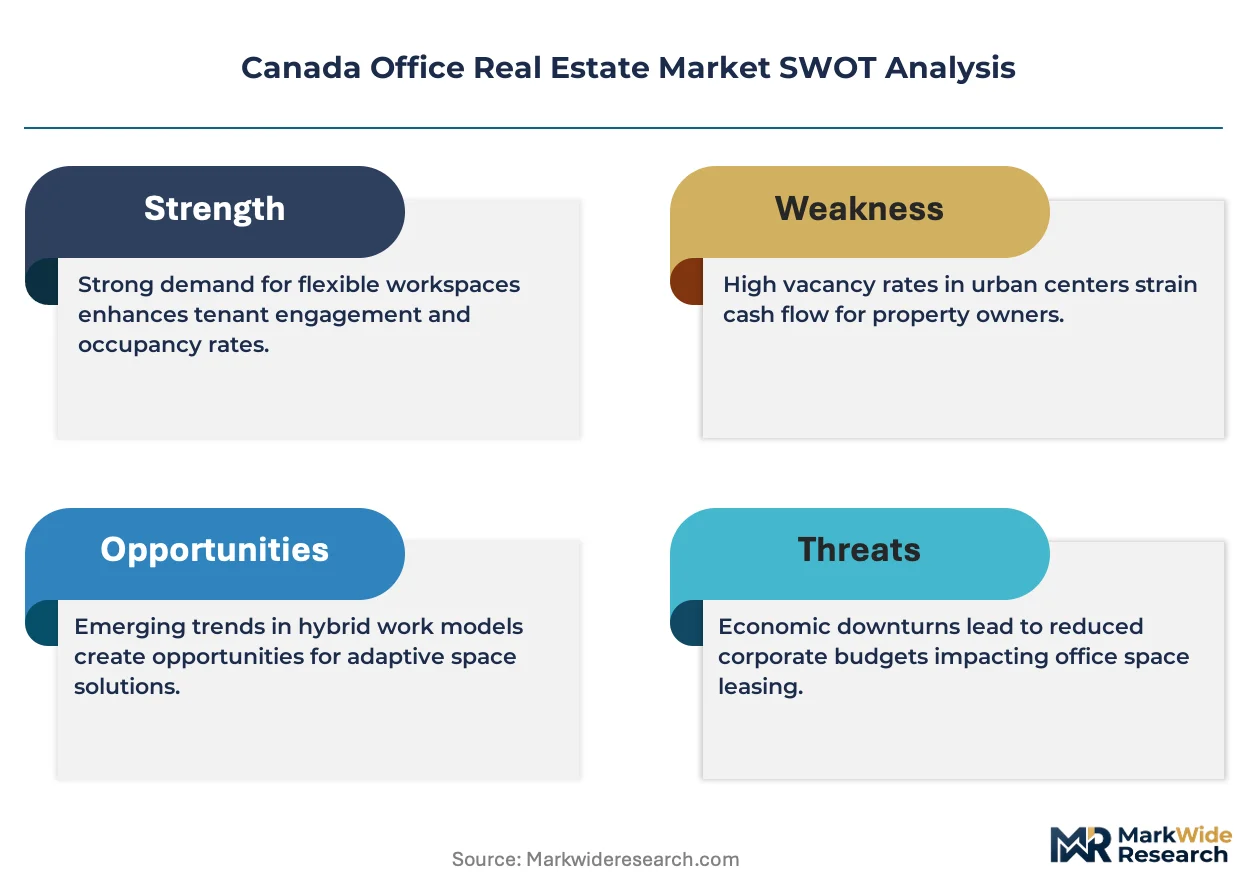
The Canada office real estate market reads as a late-cycle quality story, with tenant demand concentrating in transit-oriented Class A assets that command rent premiums through LEED Platinum certification and redundant digital infrastructure.
For Market Incumbents: Hedge interest rate exposure by accelerating pre-leasing commitments before Bank of Canada tightening cycles freeze acquisition cap rates. Prioritize backward integration into mass timber supply through strategic partnerships with British Columbia and Quebec fiber mills, securing cost certainty for mid-rise development pipelines. Defensive positioning requires portfolio rebalancing toward federal government tenancies in Ottawa and life sciences crossover assets in Toronto's Waterfront Innovation Centre, where lease durability offsets hybrid work headwinds. For New Entrants and Emerging Players: Capture heritage asset repositioning opportunities in Montreal's Griffintown and Toronto's Liberty Village, where industrial loft conversions attract creative economy tenants seeking authentic character space unavailable in new construction. Target CMHC green financing programs to reduce effective borrowing costs for Net Zero Energy Performance developments, leveraging municipal density bylaws for expedited permit approvals within 800 meters of rapid transit stations. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented Class B ownership in Calgary's Beltline and Montreal's Ville-Marie creates value-add acquisition targets with renovation-driven rent reset potential. Long-term viability centers on exposure to technology and life sciences tenant segments with expansion optionality. Monitor Bank of Canada policy rate trajectories as the critical inflection signal for unlocking development starts and transaction velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Transit-Oriented Density Partnerships | Municipal density bonuses in Toronto and Vancouver compress entitlement timelines by six to nine months. |
| Mass Timber Supply Integration | Backward integration into British Columbia and Quebec fiber mills secures structural material cost certainty. |
| Heritage Asset Repositioning | Industrial loft conversions in Griffintown and Liberty Village capture creative economy rent premiums. |
| Green Financing Program Access | CMHC low-carbon building incentives reduce effective borrowing costs for Net Zero developments. |
| Federal Tenancy Concentration | Ottawa government leases stabilize occupancy against hybrid work pressures in private sector assets. |
Study Parameters
Bottom-up tenant absorption modeling reconciled against top-down development pipeline tracking forms the analytical core of this study. Primary interviews with asset managers at institutional landlords, development executives at national portfolio owners, municipal planning officers in Toronto and Vancouver, and tenant representation brokers at commercial real estate services firms combined with secondary validation from CMHC housing market data, municipal benchmarking bylaw disclosures, National Building Code of Canada amendments, and Bank of Canada monetary policy reports. Cross-referencing bottom-up lease rollover schedules against top-down interest rate sensitivity matrices ensures segmentation integrity.
Historical trendline analysis of cap rate compression and rent growth patterns across property type classifications established baseline trajectory assumptions. The forecast framework models segmentation across Class A, Class B, and business park property types; technology, financial services, and creative studio tenant industries; triple net, gross, and modified gross lease structures; and core, value-add, and opportunistic investment risk profiles. CAGRs derive from regression analysis of permit issuance velocity, absorption rates, and capital deployment flows throughout the projection horizon. Hybrid work permanence assumptions and green building certification adoption curves constitute key industry-specific forecast inputs.
Underlying measurement precision varies by segment; Class A office absorption in Toronto and Vancouver carries tighter precision than Atlantic Canada secondary market projections due to transaction velocity and data availability disparities. Forecasts reflect documented assumptions regarding interest rate trajectories, hybrid work permanence, and municipal density incentive continuity. Material deviation in Bank of Canada policy rate movements or federal green building standard enforcement timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Asia Pacific Flexible Office Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
South Korea Office Real Estate Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market