
 Global Office Space Market | 2026-2036
Global Office Space Market Size, Share, and Industry Trends Forecast 2026-2036
Global Office Space Market Outlook
Market Context with Strategic Players
Hybrid workplace expertise is bifurcating the talent pool between traditional lease specialists and flexible-space operators. CBRE Group Inc. leverages its brokerage scale to dominate conventional office transactions across gateway cities. IWG plc anchors its competitive position through franchise-operated networks spanning secondary and tertiary markets. WeWork Inc. navigates restructuring pressures while competing on short-term membership accessibility.
Technical Definition and Structural Segments
Office space denotes commercially zoned built environments designed for administrative, professional, and knowledge-based work, typically incorporating raised-floor systems, HVAC zoning for 150-300 square feet per occupant, and structured cabling for data throughput. The primary commercial purpose centers on enabling productivity, collaboration, and client-facing operations for tenant organizations. Co-working and virtual offices capture expanding margin pools as startups and freelancers prioritize capital-light occupancy models. Private offices sustain premium pricing power among corporations requiring branded environments and controlled access protocols. Smart office solutions within the technology dimension are displacing legacy building management systems as landlords pursue operational efficiency and tenant retention.
Regulatory Frame and Forward-Looking Close
LEED certification administered by the U.S. Green Building Council, BREEAM standards in the United Kingdom, and the EU Energy Performance of Buildings Directive collectively reshape development specifications and retrofit timelines across major office markets. OSHA workplace safety mandates and local fire codes further constrain spatial density and egress design, directly influencing net rentable area calculations. Stakeholders must monitor how municipal zoning liberalization for mixed-use conversion interacts with tightening embodied-carbon regulations to determine viable holding strategies for aging inventory.
Market Dynamics
Hybrid work permanence is fragmenting lease tenures and compressing decision cycles, forcing landlords to reconfigure floor plates for density flexibility while absorbing retrofit costs for air quality and touchless systems.
Growth Catalysts
- LEED v4.1 Certification:U.S. Green Building Council standards for net-zero carbon operations are mandating sensor-based energy management retrofits across Class A inventory in gateway cities.
- Biophilic Design Integration:Living walls and circadian lighting systems are attracting life sciences and professional services tenants seeking wellness-branded environments for talent retention.
- Sun Belt Migration:Corporate relocations to Austin, Nashville, and Raleigh-Durham are generating absorption in markets with lower basis costs and expedited permitting timelines.
Market Restraints
- Interest Rate Sensitivity:Federal Reserve policy tightening has frozen transaction velocity and widened bid-ask spreads for institutional-quality assets in primary markets.
- Obsolescence Risk:Pre-2000 vintage buildings lacking column-free spans and adequate parking ratios face functional extinction without capital-intensive repositioning.
- Embedded Carbon Accounting:EU Energy Performance of Buildings Directive disclosure requirements are accelerating write-downs of concrete-heavy structures in continental European portfolios.
Strategic Opportunities
- India Tier-II Expansion:Hyderabad and Pune satellite markets offer first-mover advantage for flexible workspace operators targeting IT/ITES outsourcing clusters.
- PropTech Convergence:Integration of IoT occupancy sensors with AI-driven HVAC optimization is creating new recurring revenue streams for asset managers.
- Adaptive Reuse Incentives:Municipal zoning bonuses for office-to-residential conversion in distressed downtown cores unlock alternative exit strategies for underwater loans.
Industry Challenges
- Retrofit Coordination Complexity:Phased mechanical upgrades in occupied buildings require sequencing expertise that general contracting talent pools currently lack.
- WELL Certification Backlogs:Third-party assessor capacity constraints are extending project timelines for wellness-focused repositioning strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Office Space Market |
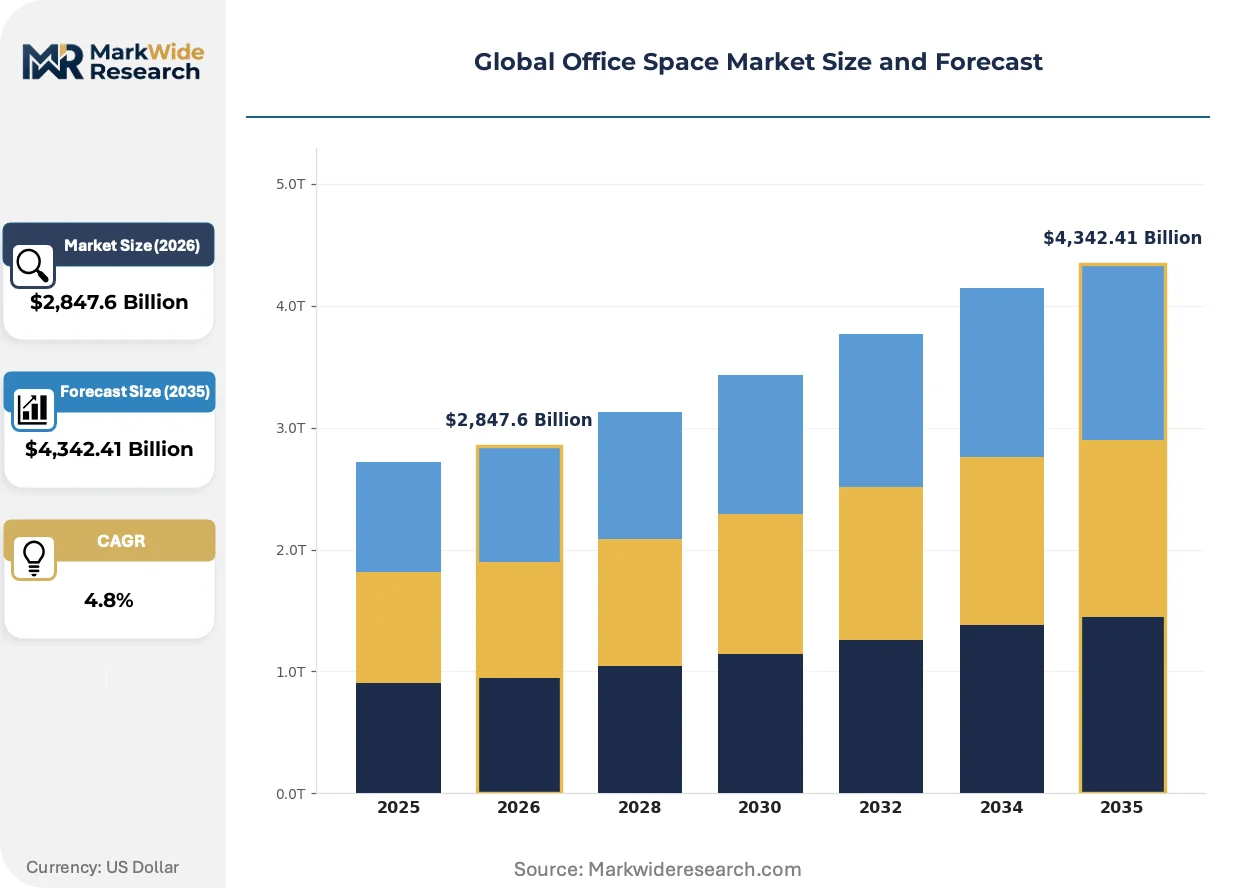
| Market Size in 2026 | $2,847.6 Billion |
| Market Size in 2035 | $4,342.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Co-Working, Private Offices, Virtual Offices, Executive Suites End User: Startups, SMEs, Corporations, Freelancers Service Type: Long-Term Lease, Short-Term Lease, Membership Plans, Custom Solutions Technology: Cloud Services, Smart Office Solutions, IoT Integration, Unified Communications |
| Companies Covered | CBRE Group Inc., Jones Lang LaSalle Incorporated, Cushman & Wakefield plc, Mitsui Fudosan Co., Ltd., IWG plc, WeWork Inc., Colliers International Group Inc., Industrious, Servcorp Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Office Space Market Strategic Shifts
Sensor infrastructure and algorithmic space management are compressing the traditional landlord-tenant information asymmetry, enabling real-time utilization optimization and dynamic pricing experiments.
Edge computing nodes embedded within raised-floor plenum systems are miniaturizing building automation footprints while reducing latency for access control and environmental adjustments. Technology firms and financial services occupiers are piloting these architectures in new construction and deep retrofit projects. The shift is miniaturizing the traditional building management system into distributed micro-controllers that lower capital intensity per square foot.
CSRD disclosure mandates from the European Commission are compelling real estate investment trusts to granularly report Scope 3 emissions from tenant energy consumption. This regulatory pressure is accelerating submetering installations and green lease adoption across Dutch and German office portfolios. French institutional investors are now screening acquisitions against Science Based Targets initiative alignment.
Tenants are unbundling lease commitments from service provision, demanding cafeteria, conferencing, and IT infrastructure as separately metered a-la-carte offerings. Landlords in London and Singapore are responding with modular service tiers that decouple base rent from amenity activation. This restructuring is most pronounced among multinational professional services firms seeking balance-sheet flexibility.
Global Office Space Market Segmentation
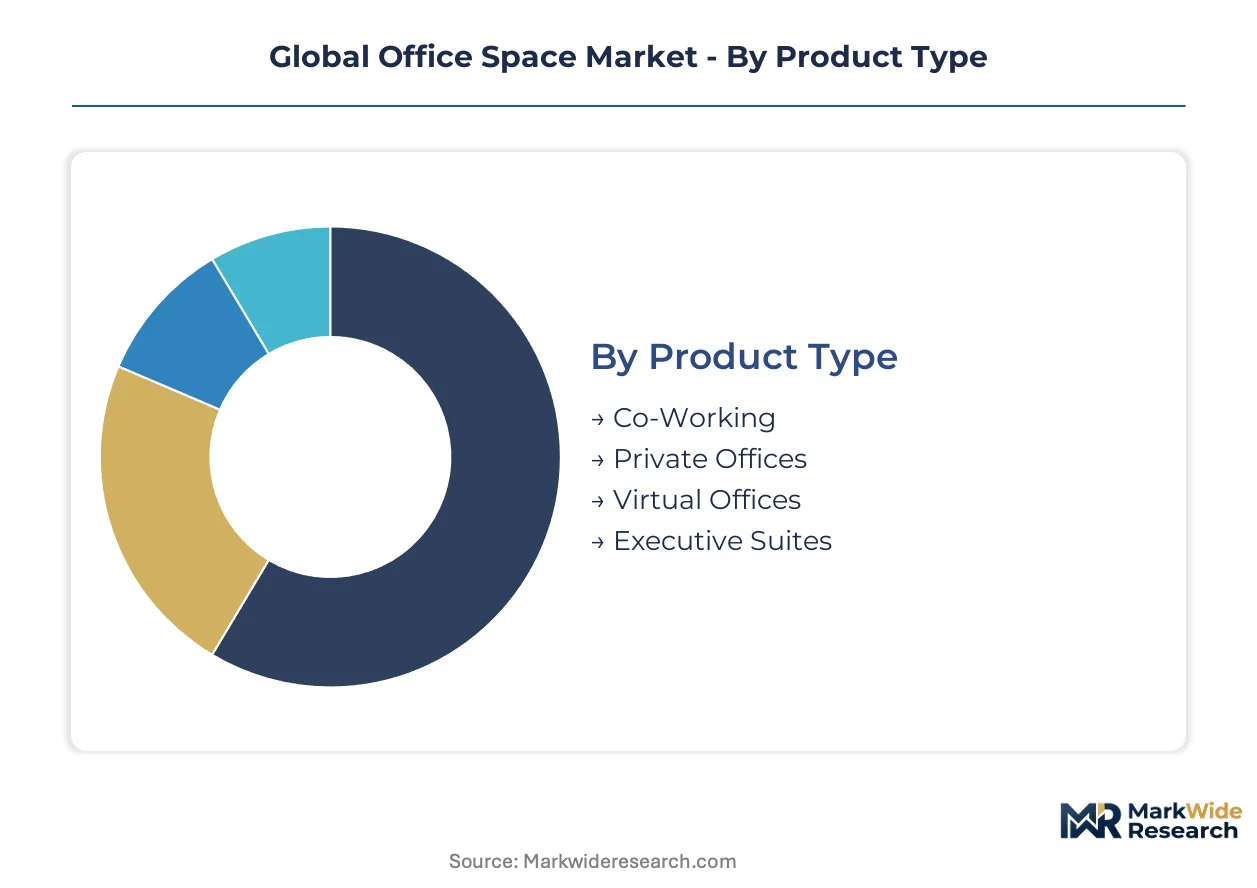
Office space segmentation reveals how hybrid work fragmentation is redirecting capital toward flexible occupancy models and technology-enabled environments. Distinct product, user, service, and technology dimensions expose where substitution pressures from remote work and digital collaboration tools threaten traditional lease structures.
Product Type:
Co-working and virtual offices face acute substitution pressure from home-based work and distributed team technologies, while private offices defend through security and brand control requirements.
- Co-Working:Open-plan environments with shared amenities and hot-desking protocols cater to mobile professionals seeking network effects without capital commitment. Demand concentrates among technology startups in Austin and Bangalore where venture-funded teams prioritize scalability over lease liability.
- Private Offices:Enclosed suites with dedicated infrastructure and access control serve organizations requiring confidentiality and customized branding. Law firms and financial services in London and Singapore sustain premium absorption despite hybrid compression elsewhere.
- Virtual Offices:Address and reception services without physical occupancy enable market presence at minimal cost. Freelancers and solo practitioners across European secondary cities adopt these for client credibility without commute burden.
- Executive Suites:Furnished turnkey offices with administrative support target interim executive teams and project-based staffing. Pharmaceutical regional headquarters in Switzerland and Germany utilize these for rapid market entry.
Private offices retain volume leadership; co-working holds the steepest expansion curve.
End User:
Cost tier stratification separates capital-constrained users seeking per-seat flexibility from balance-sheet-heavy organizations prioritizing long-term asset control.
- Startups:Venture-backed and bootstrapped companies with unpredictable headcount trajectories prioritize month-to-month terms and network access. Israeli and South Korean technology founders cluster in accelerator-linked spaces to access investor proximity.
- SMEs:Established mid-size enterprises with 50-250 employees balance cost discipline against professional image requirements. Australian professional services firms and Mexican manufacturing representatives drive stable absorption in suburban business parks.
- Corporations:Multinational and domestic large enterprises with compliance and security mandates maintain controlled environments for sensitive functions. Banking compliance teams in New York and Frankfurt sustain demand despite distributed work policies.
- Freelancers:Independent contractors and gig-economy workers seek community infrastructure and client meeting venues without residential distraction. Creative professionals in Barcelona and Lisbon populate arts district co-working conversions.
Corporations command the highest per-square-foot economics; freelancers are climbing the fastest in absolute user growth.
Service Type:
Volume concentration in long-term commitments is eroding as membership and short-term structures capture decision-cycle compression.
- Long-Term Lease:Conventional 5-10 year contracts with fixed escalations and tenant improvement allowances remain standard for creditworthy anchors. Japanese trading houses and German automotive suppliers in Stuttgart and Nagoya sustain this segment through balance-sheet preference for stability.
- Short-Term Lease:6-24 month agreements with limited customization serve project teams and transitional operations. Oil and gas engineering consortia in Houston and Aberdeen utilize these for contract-driven staffing fluctuations.
- Membership Plans:Subscription-based access with tiered usage allowances and no spatial exclusivity. Consulting partnerships in Chicago and Sydney adopt these for consultant mobility and client-site flexibility.
- Custom Solutions:Bespoke build-outs and managed services for single-tenant requirements with operational integration. Life sciences incubators in Cambridge and Basel negotiate these for laboratory-adjacent office configurations.
Long-term lease structures retain volume leadership; membership plans are gaining share fastest among new signings.
Technology:
Margin distribution favors integrated platforms that reduce operational friction and enable space-as-a-service monetization.
- Cloud Services:Distributed computing infrastructure enabling remote data access and application hosting without on-premise server investment. Nordic professional services firms and Dutch creative agencies prioritize these for workforce mobility compliance.
- Smart Office Solutions:Sensor networks and automated environmental controls optimizing energy consumption and space utilization. Singaporean government-specified buildings and Dubai commercial towers mandate these for sustainability certification.
- IoT Integration:Interconnected device ecosystems for access control, occupancy tracking, and predictive maintenance. Indian IT campuses in Hyderabad and Pune deploy these for density management and security integration.
- Unified Communications:Converged voice, video, and messaging platforms supporting seamless hybrid collaboration. Financial services trading floors in Hong Kong and Zurich require these for regulatory recording and latency-sensitive execution.
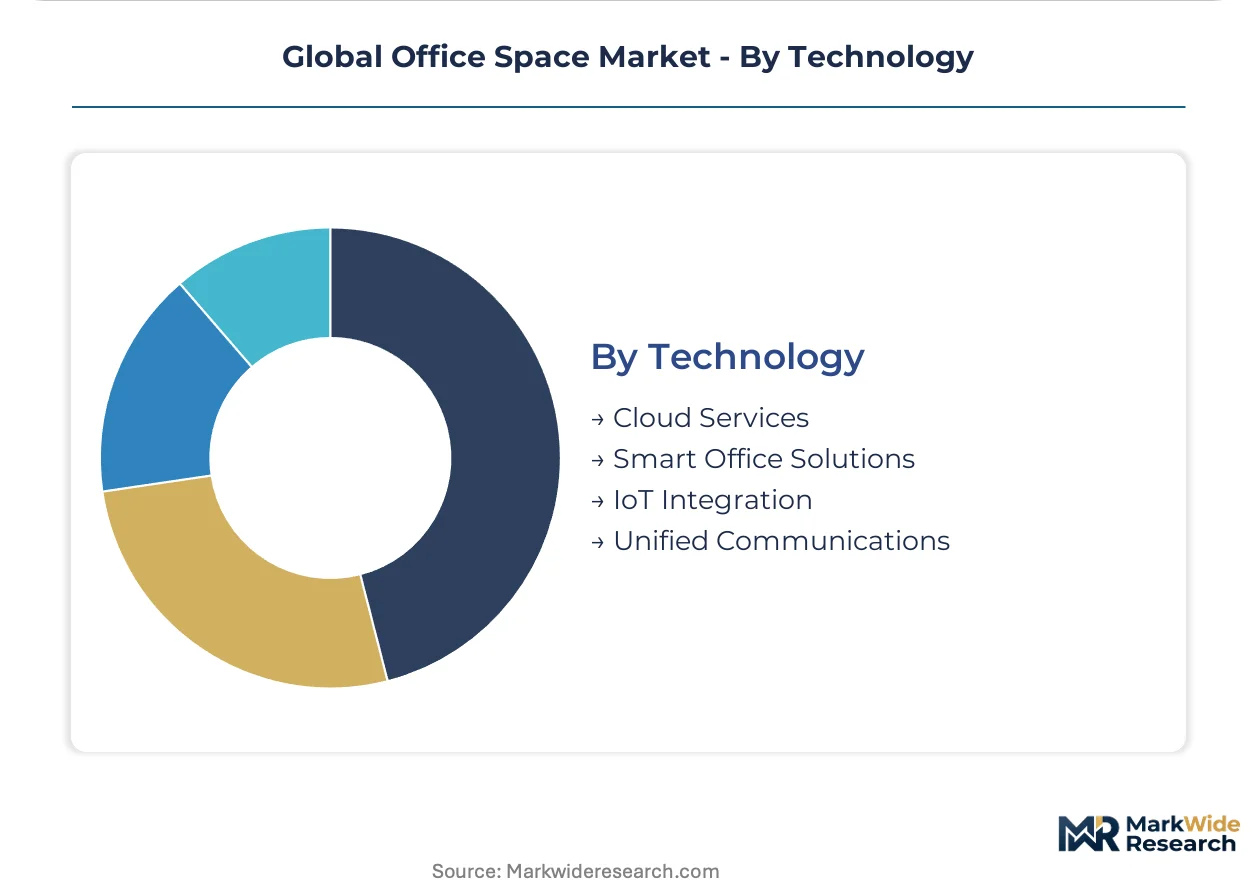
Cloud services retain volume leadership; smart office solutions command the steepest expansion trajectory among new construction specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan Class A assets command 40-60% rent premiums over comparable London City stock, while Singapore's Grade A towers trade at tighter yields than Sydney's emerging Barangaroo cluster. This pricing-power asymmetry reflects divergent capital depth, tenant covenant quality, and regulatory treatment of foreign ownership.
United States
Sun Belt metropolitan clusters in Austin, Nashville, and Raleigh-Durham absorb corporate relocations seeking lower basis costs and expedited permitting. OSHA workplace safety mandates constrain spatial density and egress design, directly influencing net rentable area calculations. Manhattan and San Francisco face elevated sublease availability as technology firms rightsized footprints, while Dallas-Fort Worth and Miami sustain positive absorption through financial services and life sciences expansion.
Germany
Frankfurt's banking district and Berlin's technology corridor sustain demand despite distributed work policies. The EU Energy Performance of Buildings Directive accelerates write-downs of concrete-heavy structures in continental portfolios. Stuttgart and Munich automotive supplier headquarters maintain controlled environments for sensitive R&D functions, resisting hybrid compression elsewhere.
United Kingdom
London's West End and City of London defend premium pricing through law firm and financial services requirements for confidentiality and branded environments. BREEAM standards reshape development specifications and retrofit timelines across major office markets. Manchester and Birmingham secondary markets capture spillover demand as tenants seek cost arbitrage against capital values.
Japan
Tokyo's Marunouchi and Otemachi districts sustain long-term lease structures through trading house and automotive supplier balance-sheet preferences for stability. METI building efficiency guidelines influence HVAC zoning and energy management specifications. Osaka's Umeda cluster and Nagoya's central business district maintain absorption through manufacturing headquarters proximity.
India
Hyderabad and Pune satellite markets offer first-mover advantage for flexible workspace operators targeting IT/ITES outsourcing clusters. State-level RERA implementation varies across Maharashtra, Karnataka, and Telangana, affecting project approval timelines. Bangalore's Electronic City and Gurgaon's Cyber Hub concentrate technology and financial services tenant demand.
Global Office Space Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the office space ecosystem. The market structures around a consolidated tier of global brokerage-scale operators and a fragmented layer of regional flexible-space specialists. Three archetypes dominate: full-service real estate services firms with integrated investment management capabilities, franchise-network flexible workspace operators, and technology-enabled membership-based platforms. Competitive intensity centers on portfolio diversification into adjacent asset classes and strategic partnerships with PropTech vendors for building automation integration.
Within the brokerage-dominant tier, CBRE Group Inc. and Jones Lang LaSalle Incorporated represent the scale-driven archetype, leveraging global transaction volumes to capture institutional capital flows. IWG plc anchors the franchise-network model through distributed secondary and tertiary market presence. WeWork Inc. occupies a restructuring-dependent position competing on short-term membership accessibility.
| Leading Market Players |
|---|
| CBRE Group Inc. |
| Jones Lang LaSalle Incorporated |
| Cushman & Wakefield plc |
| Mitsui Fudosan Co., Ltd. |
| IWG plc |
| WeWork Inc. |
| Colliers International Group Inc. |
| Industrious |
| Servcorp Limited |
| Others |
Value Chain & Pricing Dynamics
Sensor-based building management systems displacing legacy HVAC controls are simultaneously concentrating supplier networks in Singapore and Dubai while compressing installation pricing for Class A assets in gateway cities. This substitution dynamic redraws procurement geography as landlords prioritize integrated platform providers over fragmented mechanical contractors.
Pricing Analysis
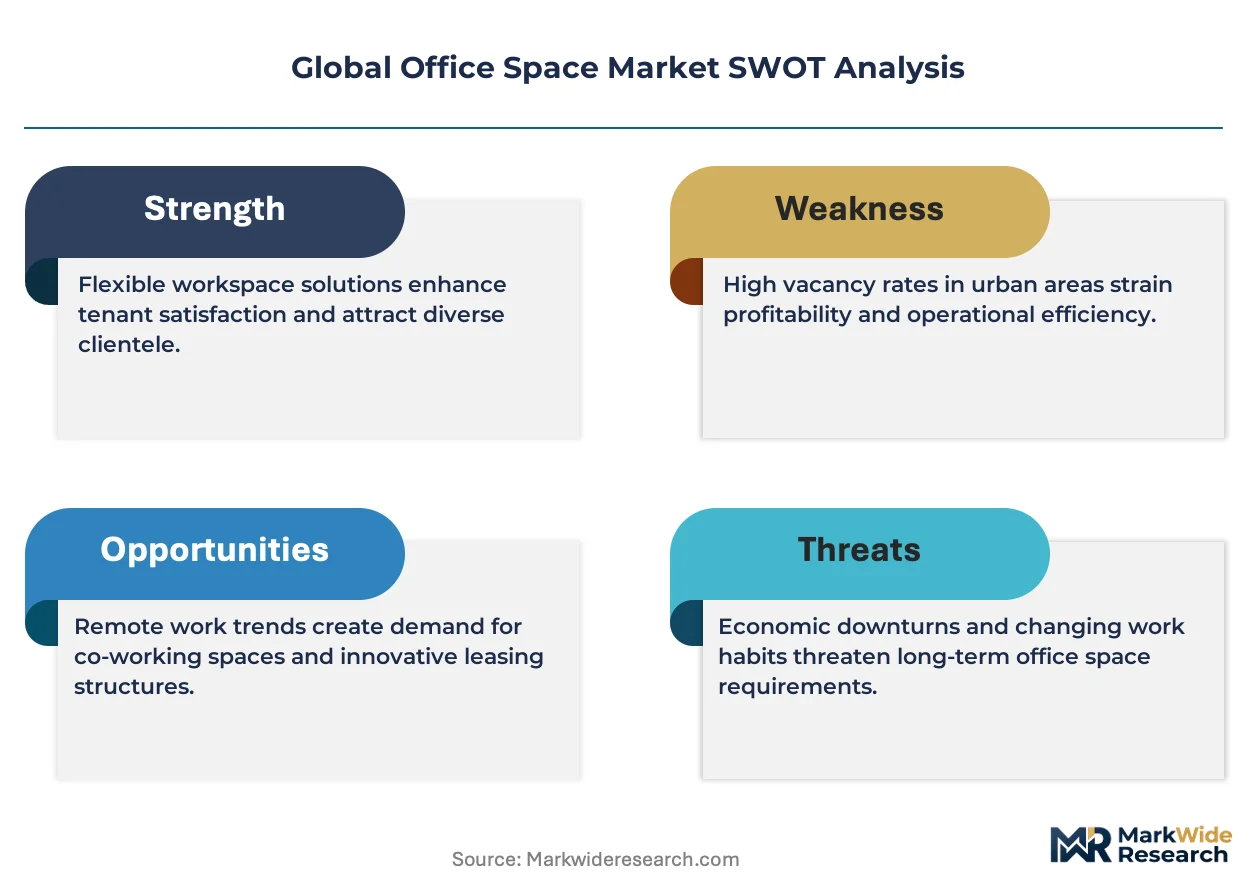
Manhattan Class A assets command 40-60% rent premiums over comparable London City stock, reflecting divergent capital depth and tenant covenant quality. Three-tier pricing structure across premium LEED-certified, standard Class A, and economy Class B inventory stratifies by certification grade and smart building infrastructure density. Cost compression in secondary market Class B inventory is intensifying because corporate tenants demand touchless systems and air quality upgrades without corresponding rent escalation tolerance. Freelancers and venture-backed startups exhibit highest price sensitivity; law firms and financial services compliance teams demonstrate least elasticity due to security mandates.
Supply Chain Analysis
Extended lead times for IoT sensors and raised-floor plenum systems now stretch 16-24 weeks, constraining retrofit velocity in occupied buildings. Manufacturing concentrates in China for sensor hardware, Germany for building automation controllers, and the United States for edge computing nodes. Raw material dependencies span rare earth elements for sensor magnets, copper for structured cabling, and specialized steel for raised-floor pedestals. Single-source vulnerability from Taiwanese semiconductor fabricators feeds into controller chip shortages. Distribution runs through integrated facilities management providers and specialized PropTech integrators serving institutional landlords.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern tenant-landlord relationships as space-as-a-service unbundling creates interoperability requirements between access control, HVAC, and conferencing systems. This ecosystem shift rewards operators who control the data layer rather than the physical asset alone.
For Market Incumbents: Compound defensive moats by acquiring PropTech sensor platforms and embedding them into long-term service contracts. Vertical integration into IoT installation capabilities counters margin pressure from pure-technology vendors. Pursue WELL and LEED certification at portfolio scale to differentiate against unaccredited competitors in gateway city bidding processes.
For New Entrants and Emerging Players: Differentiate on modular service tiering that decouples base rent from amenity activation, mirroring successful London and Singapore restructuring. Target India Tier-II satellite markets—Hyderabad and Pune—for flexible workspace penetration where IT/ITES outsourcing clusters lack incumbent coverage. Deploy franchise-operated networks rather than capital-heavy direct ownership to accelerate geographic footprint.
For Investors and Strategic Acquirers: Capital is best deployed toward distressed downtown core assets with adaptive reuse optionality under municipal zoning liberalization. Long-term viability hinges on repositioning pre-2000 vintage inventory for residential conversion or life sciences adjacency. Monitor sublease availability rates in Manhattan and San Francisco as inflection indicators for technology sector footprint normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| PropTech Platform Integration | Sensor-embedded buildings in Singapore and Dubai command tenant retention premiums through real-time utilization optimization. |
| Green Certification Program | LEED v4.1 compliance in U.S. gateway cities mandates sensor-based energy retrofits that displace legacy building management systems. |
| Adaptive Reuse Execution | Municipal zoning bonuses for office-to-residential conversion unlock alternative exit strategies for underwater loans in distressed downtown cores. |
| Flexible Workspace Expansion | Franchise-operated networks spanning secondary and tertiary markets capture corporate demand for hybrid work infrastructure without capital intensity. |
| Smart Building Technology Licensing | Edge computing nodes embedded in raised-floor plenums reduce latency for access control and enable recurring software revenue streams. |
Study Parameters
Operator-level perspectives from facilities management directors, tenant experience officers, PropTech integration specialists, and institutional asset managers anchored the qualitative base. Primary interviews combined with secondary validation from SEC REIT filings, U.S. Green Building Council certification databases, EU Energy Performance of Buildings Directive disclosures, and municipal zoning records. Bottom-up lease transaction analysis and top-down macroeconomic scenario modeling provided triangulation across data sources.
Sensitivity analysis tested forecast robustness across interest rate scenarios, hybrid work permanence assumptions, and embodied-carbon regulatory stringency variations. Segmentation dimensions modeled include product type, end user category, service structure, and technology integration level alongside regional regulatory cluster differentiation. CAGRs were derived from historical absorption patterns projected through the analysis window with adjustment for identified catalyst and restraint dynamics. Forecast inputs incorporated Sun Belt migration velocity, PropTech adoption curves, and adaptive reuse incentive program rollouts.
The analysis sits within stated boundaries; outcomes outside sustained hybrid work normalization or accelerated EU carbon disclosure timelines would require recalibration. Forecasts reflect documented assumptions regarding tenant decision-cycle compression and landlord retrofit cost absorption capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Flexible Office Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
Australia Flexible Office Space Market
Office Real Estate
Spain Office Real Estate Market