
 Asean Office Real Estate Market | 2026-2036
Asean Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Asean Office Real Estate Market Outlook
Malaysia's Uniform Building By-Laws is hardening the cost-of-entry calculus for new office developments across the Asean region. CapitaLand Group leverages its integrated development platform to sustain premium positioning in Singapore and Vietnam. Mapletree Investments Pte Ltd anchors its regional footprint through logistics-adjacent office assets in key ASEAN hubs. Frasers Property competes on sustainability credentials across its Bangkok and Kuala Lumpur portfolios.
Asean Office Real Estate encompasses commercial buildings designed for administrative, professional, and corporate activities, typically featuring floor plates of 500–2,000 square meters, centralized air conditioning systems, and structured cabling infrastructure for tenant connectivity. These assets generate income through lease contracts and serve as productive environments for knowledge-based services across Southeast Asian economies. Traditional offices retain the largest share of institutional capital deployment, though co-working spaces attract the fastest-growing tenant flow from technology and fintech startups. Flexible lease structures command premium rates per square meter while core investment strategies dominate pension fund allocations across Singapore and Bangkok.
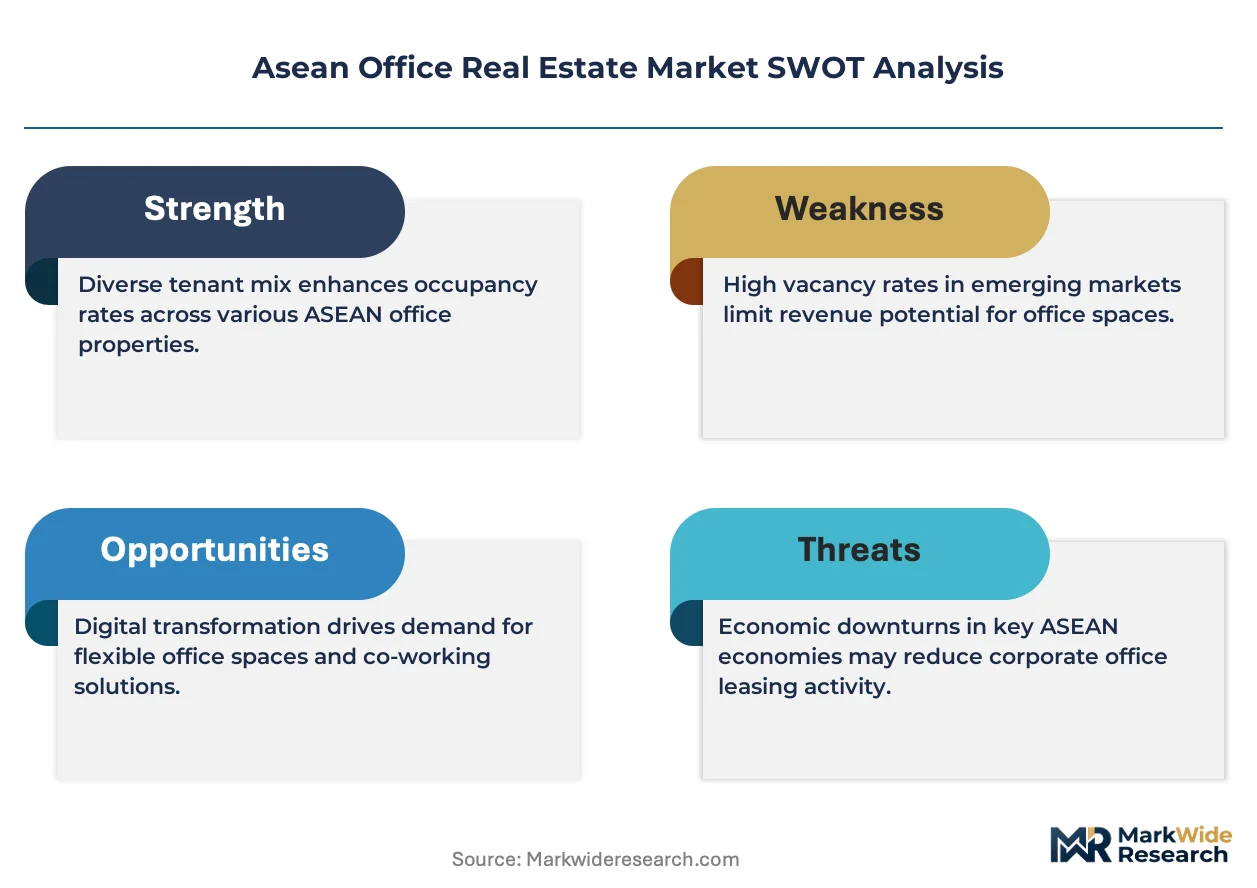
Singapore's Building and Construction Authority enforces Green Mark certification standards that dictate energy performance thresholds for new office supply. Thailand's Department of Public Works and Town & Country Planning regulates floor area ratios and setback requirements in Bangkok's central business district. Indonesia's Ministry of Public Works and Housing oversees building safety codes that affect high-rise office development timelines in Jakarta. Stakeholders must monitor how divergent national green building timelines reshape cross-border portfolio allocation decisions.
Market Dynamics
Technology sector tenants from Singapore and Kuala Lumpur are compressing lease cycles and demanding flexible footprints, forcing landlords to restructure income models around shorter-term contracts and service-based revenue streams.
Growth Catalysts
- Green Mark Certification:Singapore's Building and Construction Authority mandates energy performance thresholds that pull capital toward sustainable retrofit projects. Premium rents attach to certified assets.
- Technology Sector Expansion:Fintech and SaaS startups across Jakarta and Bangkok are absorbing co-working inventory at velocity. Flexible lease structures match their scaling headcount.
- Central Business District Concentration:Grade A supply tightness in Bangkok's Sukhumvit corridor and Jakarta's CBD is sustaining occupancy premiums. Limited new completions reinforce landlord pricing power.
Market Restraints
- Construction Input Volatility:Steel and aluminum price swings across Southeast Asia are squeezing development margins. Fixed-price contracts expose contractors to material cost spikes.
- Regulatory Timeline Friction:Indonesia's Ministry of Public Works and Housing enforces building safety codes that extend high-rise approval cycles. Pre-leasing windows compress against construction schedules.
- Substitution Pressure:Remote work protocols adopted by regional headquarters functions are reducing per-employee office square footage requirements. Landlords compete with home-based alternatives.
Strategic Opportunities
- Vietnam Secondary Cities:Da Nang and Ho Chi Minh City's District 2 remain underpenetrated by institutional-grade office supply. Early movers capture yield premiums ahead of infrastructure completion.
- Logistics-Adjacent Assets:E-commerce fulfillment networks in Malaysia and Thailand are generating demand for back-office space proximate to distribution nodes. Hybrid industrial-office formats capture this flow.
- Green Building Incentives:Malaysia's Uniform Building By-Laws embed energy efficiency standards that unlock tax advantages for compliant developments. Certification cost recovery accelerates through operational savings.
Industry Challenges
- Technical Talent Scarcity:Building systems integration specialists capable of deploying smart infrastructure across legacy assets are concentrated in Singapore. Regional landlords face recruitment premiums.
- Capex Intensity for Retrofits:Centralized air conditioning upgrades and structured cabling overhauls in 1990s-era stock require substantial capital deployment. Returns hinge on lease renewal timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asean Office Real Estate Market |
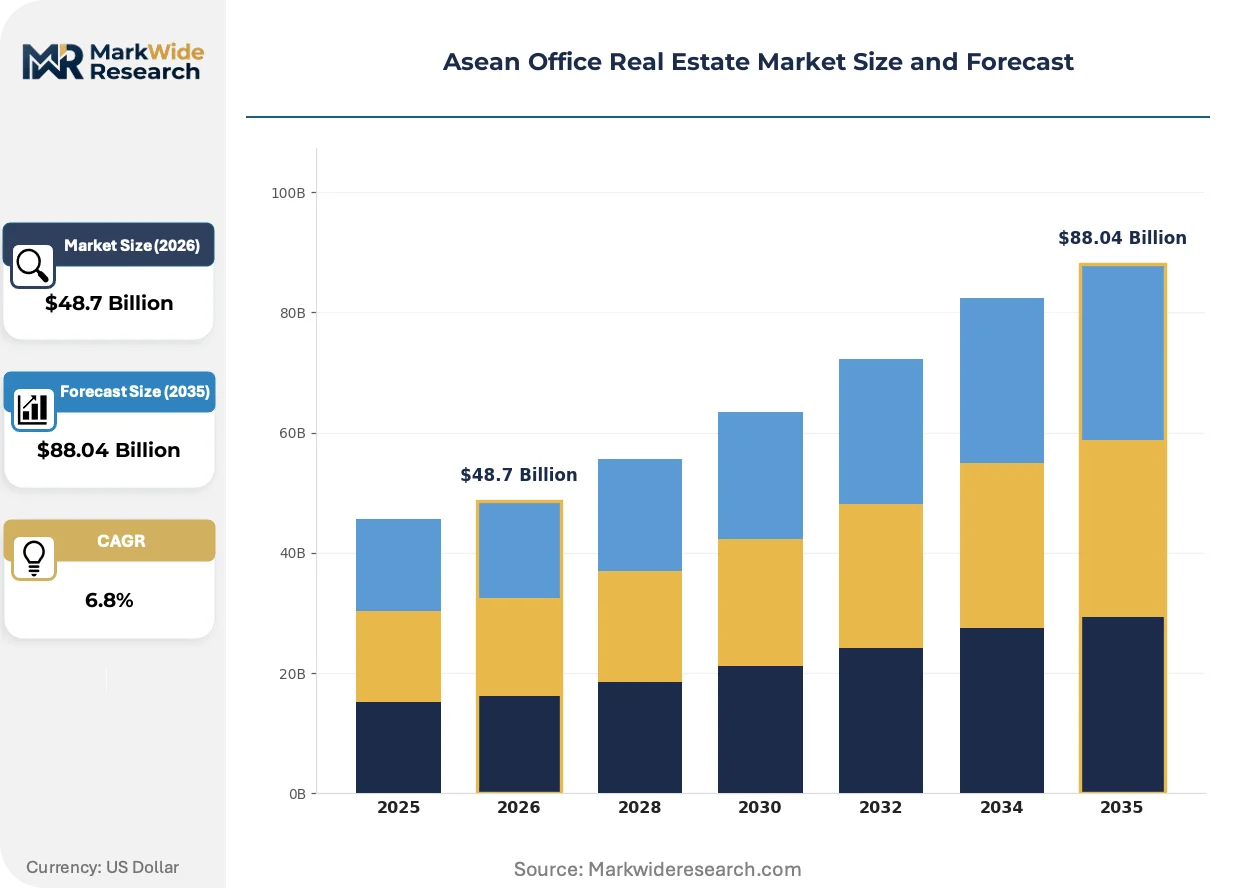
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Co-working Spaces, Traditional Offices, Serviced Offices, Executive Suites Client Type: Startups, SMEs, Corporates, Government Agencies Lease Type: Commercial Lease, Short-term Lease, Long-term Lease, Flexible Lease Investment Strategy: Value-add, Core, Opportunistic, Development |
| Companies Covered | CapitaLand Group, City Developments Limited, Frasers Property, UOL Group Limited, Keppel Land Limited, Mapletree Investments Pte Ltd, PT Ciputra Development Tbk, Malton Berhad, Hines, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asean Office Real Estate Market Strategic Shifts
Intelligent building systems and sustainability mandates are converging to redefine asset competitiveness across Southeast Asian office markets. Landlords now compete on operational technology as much as location.
Smart building management platforms are integrating IoT sensors, predictive maintenance algorithms, and tenant experience applications into unified control layers. Singapore-based property managers are deploying these systems fastest, using real-time energy optimization to meet Green Mark thresholds. The technology is integrating formerly siloed mechanical, electrical, and digital infrastructure into single-pane operations, compressing facility management headcount requirements while improving uptime metrics.
Thailand's Department of Public Works and Town & Country Planning has tightened floor area ratio enforcement in Bangkok's central business district, limiting developable density on constrained sites. Developers are responding with vertical efficiency strategies and mixed-use stacking to maximize permitted gross floor area. Premium-grade projects in Sukhumvit and Silom corridors face the strictest scrutiny, pushing design innovation toward smaller floor plates and higher ceiling heights to maintain leasable appeal.
Tenant decision-making is rotating toward wellness-certified environments and flexible term structures that accommodate headcount volatility. Technology sector occupiers in Kuala Lumpur and Jakarta are prioritizing buildings with WELL or equivalent indoor air quality credentials over traditional location metrics. This preference shift is most visible in co-working and managed office channels, where operators are bundling wellness amenities into base rent to capture premium positioning against conventional landlords.
Asean Office Real Estate Market Segmentation
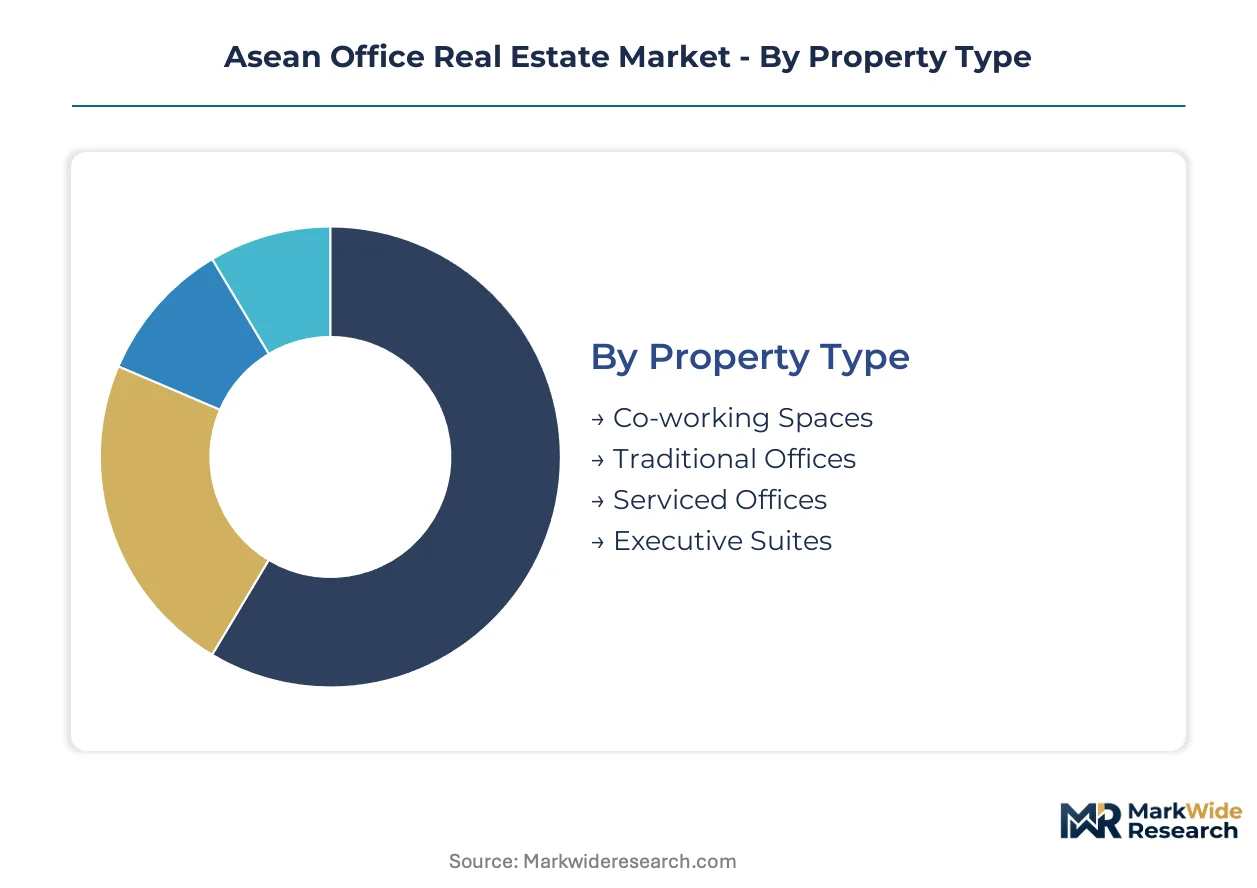
Office real estate investment in Southeast Asia fragments across lease structures, tenant risk profiles, and capital deployment horizons. Segmentation reveals where institutional capital concentrates versus where operational innovation unlocks yield premiums.
Property Type:
Tenant risk tolerance and headcount volatility determine which physical formats landlords prioritize in their development pipelines.
- Traditional Offices:Purpose-built commercial buildings with standardized floor plates of 500–2,000 square meters and centralized building systems. Singapore and Bangkok institutional investors anchor core portfolios here, though remote work protocols from regional headquarters functions are compressing per-employee square footage requirements and extending vacancy periods in secondary corridors.
- Co-working Spaces:Flexible membership-based environments featuring shared amenities and short-term desk licenses. Technology sector tenants from Kuala Lumpur and Jakarta are absorbing this inventory fastest, with fintech and SaaS startups matching scaling headcount to contract terms that avoid traditional lease liabilities.
- Serviced Offices:Fully fitted plug-and-play suites with reception, IT infrastructure, and facilities management bundled into headline rents. Demand concentrates among professional services firms establishing satellite presences in Vietnam's secondary cities.
- Executive Suites:Premium private offices targeting C-suite functions and board meeting requirements. Law firms and financial advisory practices in Singapore's Marina Bay district sustain occupancy premiums for harbor-view configurations.
Volume sits with Traditional Offices; growth tilts toward Co-working Spaces.
Client Type:
Tenant credit quality and contract duration shape landlord underwriting assumptions across Southeast Asian portfolios.
- Corporates:Multinational regional headquarters and established domestic conglomerates demanding 3,000+ square meter footprints with branding rights and dedicated building systems. Bangkok's Sukhumvit corridor and Jakarta's central business district concentrate this demand, where Grade A supply tightness reinforces landlord pricing power on 5–10 year lease structures.
- Startups:Venture-backed technology and fintech ventures prioritizing flexible expansion rights over location prestige. Co-working operators in Singapore and Kuala Lumpur capture this flow through membership models that convert to conventional leases at Series B funding milestones.
- SMEs:Mid-sized professional services and trading houses seeking 200–800 square meter fitted space with shorter commitment horizons. Malaysia's Uniform Building By-Laws energy standards are pushing this segment toward certified buildings that qualify for operational cost offsets.
- Government Agencies:Public sector administrative functions with procurement-constrained lease terms and security-modified space requirements. Indonesia's Ministry of Public Works and Housing oversight extends approval timelines for these specialized fit-outs.
Capital deployment favors Corporates; contract innovation targets Startups.
Lease Type:
Income stability and operational flexibility trade off differently across investor risk-return profiles.
- Long-term Lease:Conventional 5–10 year contracts with fixed or indexed escalations, typically signed by corporates and government agencies. Singapore pension funds and Bangkok insurance capital anchor core strategies around these cash flow streams.
- Flexible Lease:Short-dated or expansion-option contracts matching technology sector headcount volatility. Operators bundle service revenue into effective rents that exceed traditional lease rates on a per-square-meter basis.
- Commercial Lease:Standard business-to-business agreements with tenant responsibility for fit-out and utilities. This structure dominates Grade A stock in Jakarta's CBD where landlord capital constraints limit speculative pre-fitting.
- Short-term Lease:Sub-12 month arrangements common in transitional or repositioning assets. Pop-up professional services and project-based consulting teams absorb this inventory during building upgrade cycles.
Institutional allocation concentrates in Long-term Lease; yield expansion flows through Flexible Lease.
Investment Strategy:
Risk-adjusted return targets and capital horizon dictate which asset profiles attract deployment.
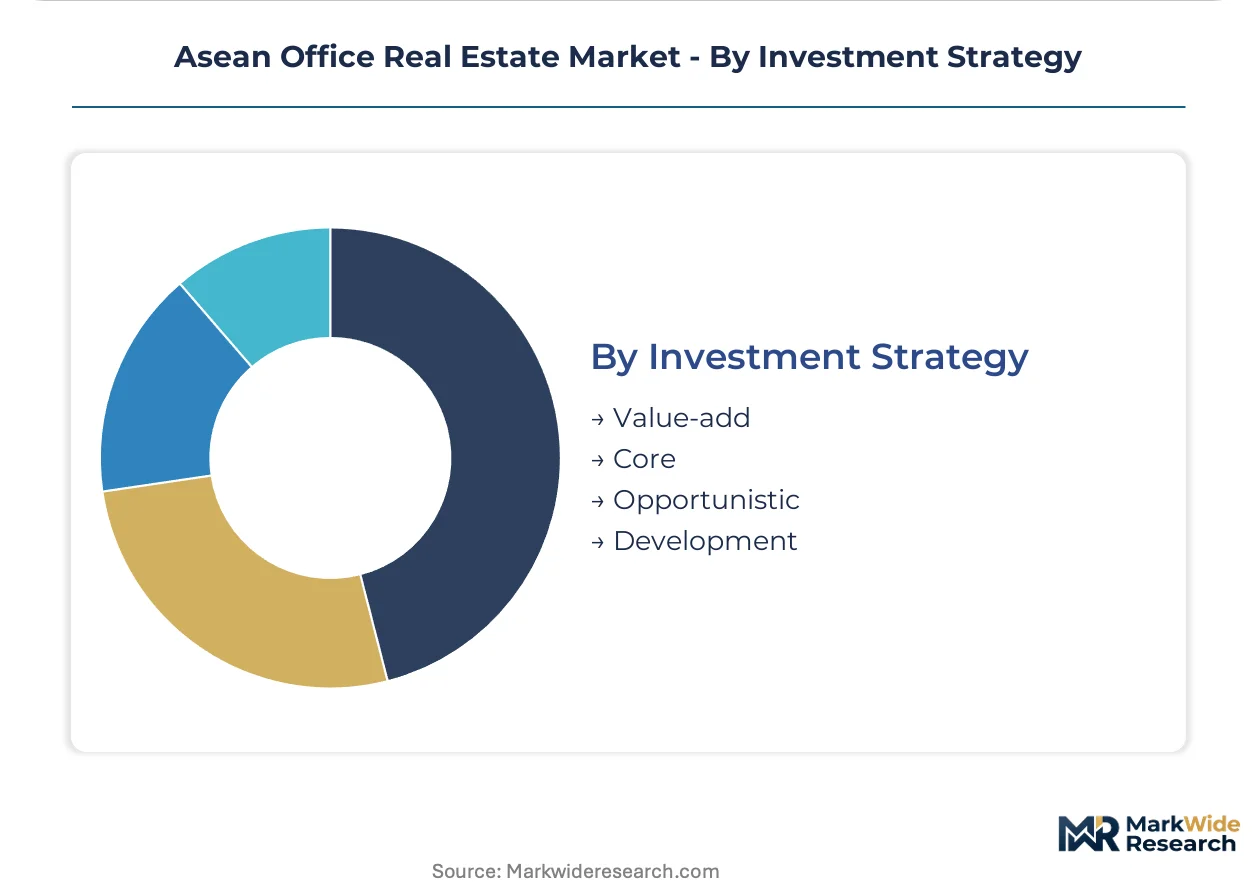
- Core:Stabilized, fully leased assets in prime locations with minimal capital expenditure requirements. Singapore's Green Mark certified buildings and Bangkok's Sukhumvit Grade A stock dominate this category for pension and sovereign wealth allocation.
- Value-add:Assets requiring active management, lease restructuring, or moderate physical repositioning to achieve market rents. 1990s-era stock in Kuala Lumpur's peripheral submarkets presents retrofit opportunities around Malaysia's energy efficiency compliance deadlines.
- Opportunistic:Distressed or complex situations demanding substantial capital restructuring or development rights monetization. Indonesia's extended approval timelines from the Ministry of Public Works and Housing create pricing dislocations for patient capital.
- Development:Ground-up construction or major redevelopment on entitled sites. Thailand's Department of Public Works and Town & Country Planning floor area ratio enforcement in Bangkok's CBD is pushing developers toward vertical efficiency strategies on constrained land parcels.
Capital stock concentrates in Core; return enhancement concentrates in Value-add.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology sector tenants from Singapore and Kuala Lumpur are compressing lease cycles and demanding flexible footprints across Southeast Asian office markets. Grade A supply tightness in Bangkok's Sukhumvit corridor and Jakarta's central business district sustains occupancy premiums. Divergent national green building timelines reshape cross-border portfolio allocation decisions.
Singapore
Fintech and SaaS startups are absorbing co-working inventory at velocity across Marina Bay and the Central Business District. The Building and Construction Authority enforces Green Mark certification standards that dictate energy performance thresholds for new office supply. CapitaLand Group leverages its integrated development platform to sustain premium positioning in prime submarkets.
Thailand
Multinational regional headquarters demand 3,000-plus square meter footprints with branding rights in Bangkok's core. The Department of Public Works and Town and Country Planning regulates floor area ratios and setback requirements in the central business district. Sukhumvit corridor developers deploy vertical efficiency strategies to maximize permitted gross floor area on constrained sites.
Indonesia
Established domestic conglomerates seek Grade A space in Jakarta's CBD where limited new completions reinforce landlord pricing power. The Ministry of Public Works and Housing oversees building safety codes that extend high-rise approval cycles and compress pre-leasing windows. PT Ciputra Development Tbk anchors development activity in emerging commercial submarkets.
Malaysia
Mid-sized professional services firms seek certified buildings that qualify for operational cost offsets under tightened energy standards. The Uniform Building By-Laws embed energy efficiency requirements that unlock tax advantages for compliant developments. Kuala Lumpur's peripheral submarkets present retrofit opportunities around compliance deadlines.
Vietnam
Professional services firms establishing satellite presences drive demand for serviced office formats in secondary cities. Infrastructure completion timelines in Da Nang and Ho Chi Minh City's District 2 create yield premiums for early movers. Mapletree Investments Pte Ltd anchors regional footprint through logistics-adjacent office assets in key hubs.
Asean Office Real Estate Market Competitive Environment
Singapore-based developers anchor the premium-tier segment; Malaysian and Thai specialists hold mid-market positioning through localized execution capabilities. The vendor base concentrates around integrated development platforms capable of bundling office, retail, and residential components. Three archetypes dominate: sovereign-linked property groups with patient capital, diversified conglomerates with cross-sector synergies, and specialized office REITs with yield-focused mandates. Portfolio diversification and sustainability credentialing constitute the dominant competitive moves across the region.
Within the sovereign-linked tier, CapitaLand Group and Mapletree Investments Pte Ltd exemplify platforms with integrated capabilities spanning development, investment, and asset management. Keppel Land Limited occupies a position among engineering-backed developers with distinctive technical infrastructure expertise. These entities represent the capital-intensive archetype that dominates core market allocation.
| Leading Market Players |
|---|
| CapitaLand Group |
| City Developments Limited |
| Frasers Property |
| UOL Group Limited |
| Keppel Land Limited |
| Mapletree Investments Pte Ltd |
| PT Ciputra Development Tbk |
| Malton Berhad |
| Hines |
| Others |
Value Chain & Pricing Dynamics
Technology sector tenants compressing lease cycles across Singapore and Kuala Lumpur are forcing landlords to restructure income models around shorter-term contracts and service-based revenue streams, which elevates operational complexity costs and compresses development margins across the supply chain.
Pricing Analysis
Volume concentrates in long-term lease structures anchored by corporates and government agencies, while margin expansion flows through flexible lease formats that bundle service revenue into effective rents exceeding traditional rates on a per-square-meter basis. Price differentiation rests on Green Mark certification tier, floor plate efficiency, and proximity to mass transit nodes. Pricing pressure stems from remote work protocols reducing per-employee square footage requirements. SMEs exhibit highest price sensitivity, while law firms and financial advisory practices in Singapore's Marina Bay district sustain premiums for harbor-view executive suites.
Supply Chain Analysis
Single-source vulnerability sits with steel and aluminum suppliers concentrated in China, South Korea, and Japan, where price volatility transmits directly into construction cost escalation. Development pipelines draw from imported HVAC equipment, specialized glazing systems, and smart building management platforms. Supply chain risk centers on extended approval timelines from Indonesia's Ministry of Public Works and Housing compressing pre-leasing windows against construction schedules. Distribution runs through integrated development platforms capable of bundling office, retail, and residential components across prime ASEAN hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ASEAN office real estate market functions as a consolidation play where construction input volatility and divergent national green building timelines are forcing capital-constrained developers to exit or partner with sovereign-linked platforms possessing patient capital access.
For Market Incumbents: Acquire logistics-adjacent office assets in Malaysia and Thailand to capture e-commerce back-office demand proximate to distribution nodes. Defend pricing power by accelerating Green Mark certification timelines ahead of regulatory deadlines, while restructuring legacy portfolios around flexible lease formats to retain technology sector tenants facing headcount volatility. For New Entrants and Emerging Players: Smart building management platforms integrating IoT sensors and predictive maintenance algorithms offer entry into Vietnam's secondary cities where institutional-grade supply remains underpenetrated. Target Da Nang and Ho Chi Minh City's District 2 with hybrid industrial-office formats, leveraging infrastructure completion timelines to capture yield premiums ahead of competitive supply. For Investors and Strategic Acquirers: Re-rating potential sits with value-add specialists possessing retrofit execution capabilities around Malaysia's Uniform Building By-Laws energy efficiency compliance deadlines. Long-term viability favors platforms with integrated development, investment, and asset management functions across multiple ASEAN jurisdictions. Monitor pre-leasing velocity against construction completion timelines as the inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Acceleration | Green Mark compliance ahead of Singapore's Building and Construction Authority deadlines secures premium rent attachment and tenant retention. |
| Flexible Lease Platform Development | Service-based revenue restructuring captures technology sector demand from Kuala Lumpur and Jakarta fintech scaling. |
| Retrofit Execution Capability Buildout | Centralized air conditioning and structured cabling upgrades in 1990s-era stock unlock Malaysia energy efficiency tax advantages. |
| Logistics-Adjacent Asset Acquisition | Back-office space proximate to e-commerce fulfillment nodes in Thailand and Malaysia captures hybrid demand flow. |
| Vertical Efficiency Design Innovation | Smaller floor plates and higher ceiling heights maximize permitted gross floor area under Bangkok's tightened floor area ratio enforcement. |
Study Parameters
Multi-period observation of lease transaction velocity, absorption rates, and certification timelines anchored the trend analysis, supplemented by interviews with property fund managers, development executives, facilities directors, and tenant representation brokers. Secondary validation drew from Building and Construction Authority certification databases, Thailand Department of Public Works and Town and Country Planning filings, Indonesia Ministry of Public Works and Housing approval records, and customs data on construction material imports. Bottom-up project pipelines were triangulated against top-down capital flow estimates from pension and sovereign wealth fund disclosures.
The input-output matrix framed demand-side segmentation against supply-side capacity constraints across the projection horizon. Modeled dimensions included property type, client risk profile, lease structure, and investment strategy tier, with geographic regulatory clusters as an industry-specific overlay. CAGRs were derived from lease rate trajectory analysis and development cost escalation patterns. Forecast inputs incorporated green building compliance deadlines and technology sector employment growth assumptions.
Several conditions sit outside the modeled scope, including sovereign debt stress scenarios, currency volatility beyond historical bands, and pandemic-scale remote work protocol reimposition. Forecasts reflect documented assumptions about infrastructure completion timelines and regulatory enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
China Flexible Office Space Market
Office Real Estate
Office Real Estate Market
Office Real Estate
Qatar Co-Working Office Spaces Market
Office Real Estate
United Kingdom Co-Working Office Spaces Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
India Flexible Office Space Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Europe Flexible Office Market