
 Asia Pacific Flexible Office Market | 2026-2036
Asia Pacific Flexible Office Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Flexible Office Market Outlook
Subscription-based workspace access is broadening what operators sell beyond physical desks to bundled digital services. JustCo leverages its multi-city network across Southeast Asia to sustain occupancy premiums in Singapore and Bangkok. IWG anchors its portfolio through franchise-heavy expansion into secondary Indian cities. WeWork competes on brand recognition among multinational tenants seeking standardized workspace experiences.
Asia Pacific flexible office space denotes commercially operated real estate delivering short-lease or no-lease workstations with shared infrastructure, typically provisioning gigabit internet, climate control, and ergonomic furnishings on a per-seat or per-square-meter basis. Its primary commercial purpose is to convert fixed real estate overhead into variable operating expenditure for organizations with fluctuating headcount. Coworking spaces occupy the volume tier where startups and freelancers drive utilization, while private offices capture margin concentration from enterprise clients demanding branded environments and dedicated security protocols. Membership-based service models are maturing fastest as operators seek predictable recurring revenue, whereas pay-as-you-go structures remain experimental outside Australia's major metros.
TRAI's broadband infrastructure mandates in India, Japan's METI building energy codes, and Australia's state-level workplace safety frameworks collectively shape fit-out standards and connectivity requirements across the region. Singapore's BCA Green Mark certification increasingly filters operator eligibility for government-leased premises. Stakeholders must weigh lease flexibility against capital commitment intensity as hybrid work policies crystallize across Asia Pacific headquarters strategies.
Market Dynamics
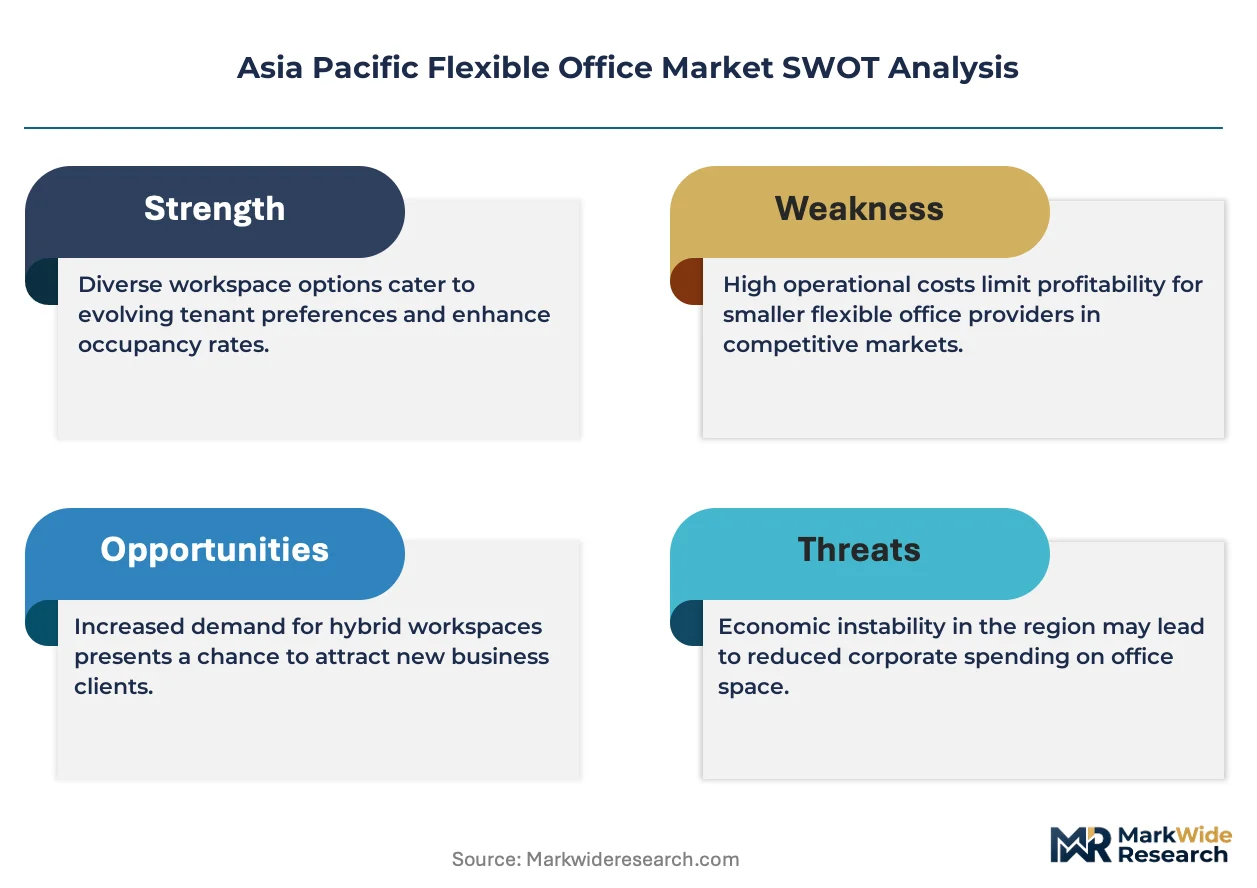
Enterprise hybrid work mandates are compressing traditional lease commitments into variable seat-based contracts across Asia Pacific, forcing landlords and operators to restructure asset yield models around utilization rates rather than square-meter absorption.
Growth Catalysts
- India's PLI scheme for IT hardware manufacturing:Domestic production incentives are dispersing technology employment into tier-two cities, generating satellite office demand that flexible operators capture without greenfield construction timelines.
- Technology sector headcount volatility:Quarterly workforce adjustments at software and fintech enterprises convert fixed real estate overhead into pay-per-seat arrangements, accelerating membership model adoption.
- TRAI broadband infrastructure mandates:Universal high-speed connectivity requirements in India enable professional-grade remote work in secondary urban centers previously excluded from enterprise location strategies.
Market Restraints
- Prime asset supply concentration:Grade-A commercial stock in Sydney, Singapore, and Tokyo commands premium rents that compress operator margins during occupancy troughs.
- Japan's METI building energy codes:Stringent efficiency retrofit requirements inflate fit-out capital intensity for existing stock conversion, extending payback periods on flexible space investments.
- Traditional lease arbitrage:Long-term commercial tenancies in Melbourne and Brisbane remain price-competitive for stable headcounts, limiting addressable market expansion.
Strategic Opportunities
- Vietnam and Philippines secondary cities:Da Nang and Cebu host underpenetrated professional services clusters where first-mover operators establish brand presence before local competition consolidates.
- Singapore's BCA Green Mark certification:Government lease eligibility filters increasingly require sustainability credentials, advantaging certified operators in public sector procurement.
- Embedded fintech and HR platforms:Workspace-as-a-service bundling converges physical infrastructure with payroll, expense management, and compliance tools for SME segments.
Industry Challenges
- Specialized asset management expertise:Dynamic pricing algorithms and demand forecasting for multi-location portfolios require talent scarce in traditional property sectors.
- Multi-jurisdiction compliance layering:Australia's state-level workplace safety frameworks, Japan's fire codes, and India's municipal occupancy permits create operational complexity for regional platform scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Flexible Office Market |
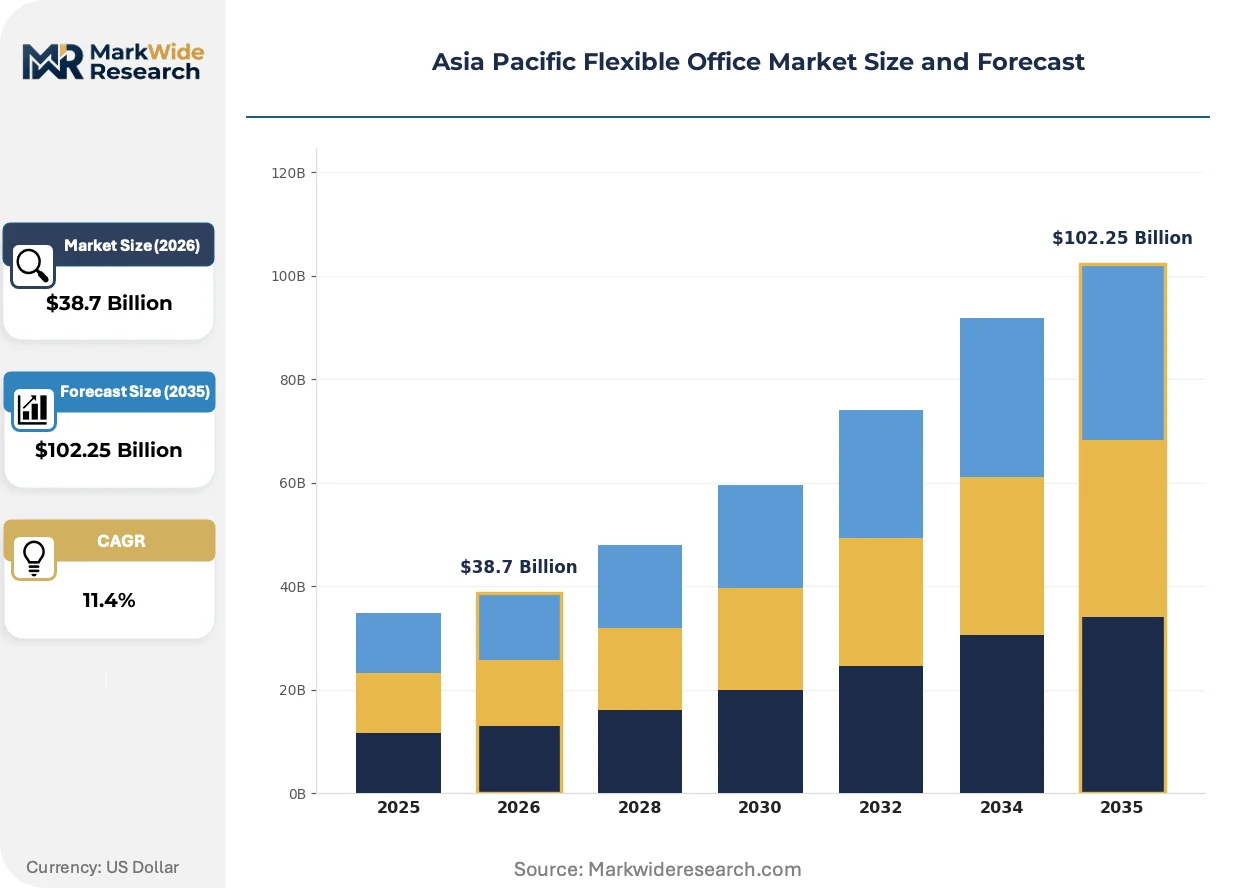
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coworking Spaces, Private Offices, Virtual Offices, Meeting Rooms Client Type: Startups, Freelancers, SMEs, Enterprises Service Model: On-Demand, All-Inclusive, Membership-Based, Pay-As-You-Go Market Segment: Corporate, Educational, Government, Non-Profit |
| Companies Covered | JustCo, Spaces, IWG, Ucommune, Hive Worldwide, WeWork, Awfis, Smartworks, The Executive Centre, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Flexible Office Market Strategic Shifts
Workspace technology stacks are fragmenting around modular platforms that separate physical infrastructure from service delivery, enabling operators to unbundle and rebundle offerings by customer segment without property-level reinvestment.
Smart building management systems are converging with access control and energy optimization platforms to deliver real-time space utilization analytics. Enterprise facilities managers deploy these tools to right-size footprint across hybrid schedules. The resulting data transparency is converging with lease negotiation power, compressing traditional landlord pricing premiums in competitive submarkets.
Australia's state-level workplace safety frameworks are tightening psychological hazard assessment requirements for shared environments. Operators must demonstrate documented wellbeing protocols to maintain enterprise tenancy eligibility. The compliance burden falls heaviest on mid-tier coworking brands lacking dedicated risk management functions, accelerating consolidation toward scaled platforms.
Enterprise procurement teams are consolidating vendor relationships through master service agreements covering multiple cities and workspace types. This behavior compresses the addressable market for single-location operators while rewarding networked providers with volume commitments. The shift is most visible in financial services and professional services verticals across the Sydney-Melbourne corridor.
Asia Pacific Flexible Office Market Segmentation
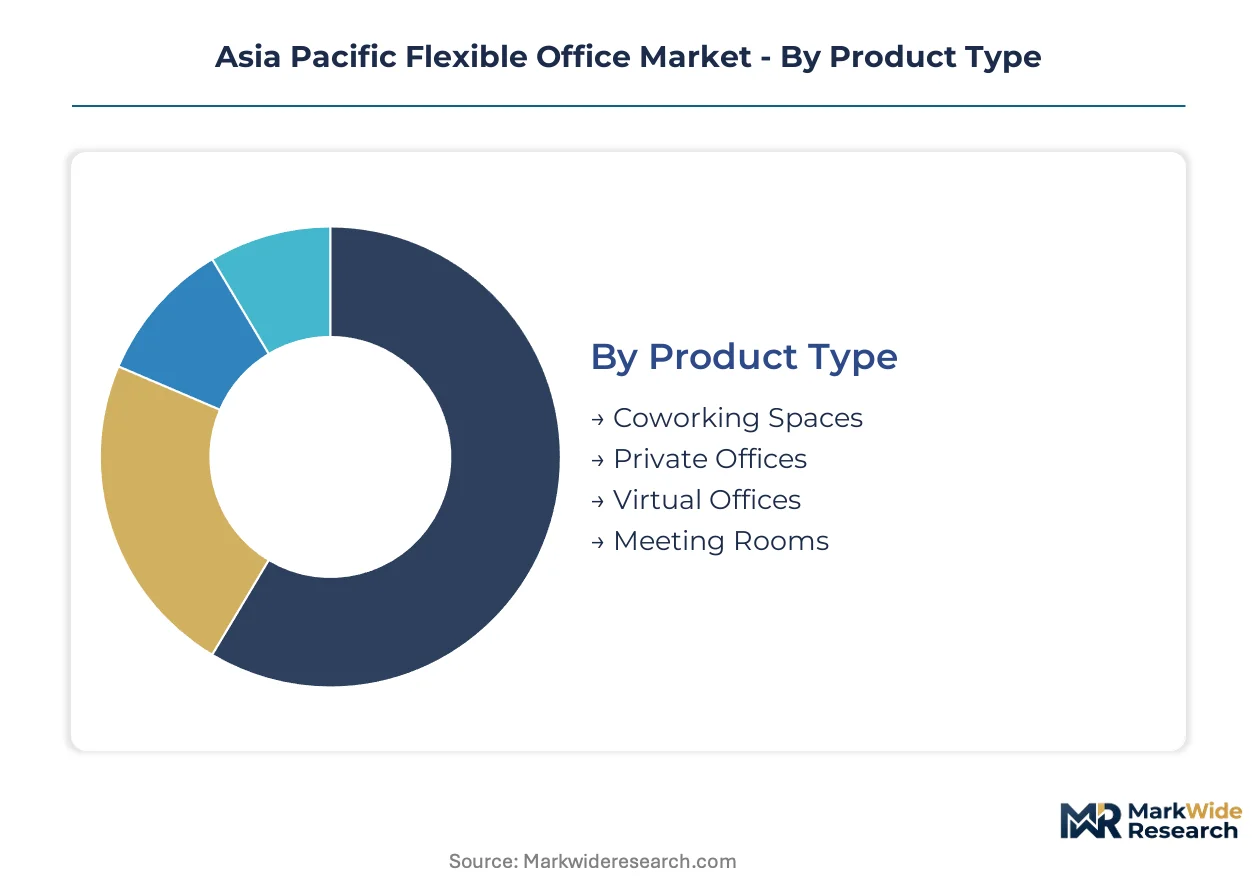
Flexible office segmentation in Asia Pacific reveals how operators balance volume-driven utilization against premium-margin capture. Distinct product architectures, client profiles, and service mechanics create divergent capital intensity and yield trajectories across the region.
Product Type:
Volume tiers dominate seat counts while premium configurations concentrate margin extraction.
- Coworking Spaces:Open-plan environments with hot-desking infrastructure and shared amenities. Demand clusters among Bangalore's technology startups and Manila's business process outsourcing clusters where headcount fluctuates seasonally.
- Private Offices:Enclosed suites with dedicated access controls and branded interiors. Singapore's financial services sector and Sydney's professional services firms drive absorption for compliance-sensitive operations requiring physical security protocols.
- Virtual Offices:Address registration and mail handling without physical workspace presence. Australian SMEs expanding into Southeast Asian markets leverage these for regulatory registration without relocation costs.
- Meeting Rooms:Bookable conference facilities with presentation technology and catering services. India's tier-two city professionals use these for client-facing engagements lacking home office credibility.
Today's leader: Private Offices. Tomorrow's challenger: Virtual Offices.
Client Type:
Enterprise procurement consolidation is displacing fragmented small-account acquisition strategies.
- Enterprises:Organizations with 500+ employees seeking standardized workspace portfolios across multiple cities. Technology and financial services verticals in the Sydney-Melbourne corridor negotiate master service agreements compressing operator margins through volume commitments.
- SMEs:Mid-market firms with 10-250 employees requiring professional environments without lease liability. Vietnam's manufacturing supply chain services and Thailand's logistics coordinators represent expanding demand pockets.
- Startups:Venture-backed companies prioritizing month-to-month flexibility over cost optimization. India's PLI scheme beneficiaries in hardware manufacturing establish satellite presences through flexible arrangements.
- Freelancers:Individual professionals purchasing single-seat access. This segment concentrates in creative industries across Melbourne and Bangkok where gig economy participation rates exceed regional averages.
Enterprises now drive revenue concentration. SMEs offer the steepest expansion trajectory as hybrid work policies crystallize across mid-market professional services.
Service Model:
Predictable recurring revenue structures are displacing transactional booking patterns.
- Membership-Based:Fixed monthly fees for guaranteed access tiers with rollover credits. Australia's enterprise procurement teams favor these for budget certainty across quarterly workforce planning cycles.
- All-Inclusive:Bundled pricing covering furniture, connectivity, utilities, and reception services. Singapore's BCA Green Mark certified operators leverage these to justify sustainability premiums in government lease competitions.
- On-Demand:Immediate booking without commitment through mobile applications. Japan's METI energy code compliance costs make this model marginally viable outside Tokyo's densest submarkets.
- Pay-As-You-Go:Per-hour or per-day consumption without recurring charges. Experimental adoption persists in Australia's secondary cities where utilization forecasting remains underdeveloped.
Membership-Based models anchor operator cash flow stability. All-Inclusive configurations gain share fastest as procurement teams consolidate vendor relationships.
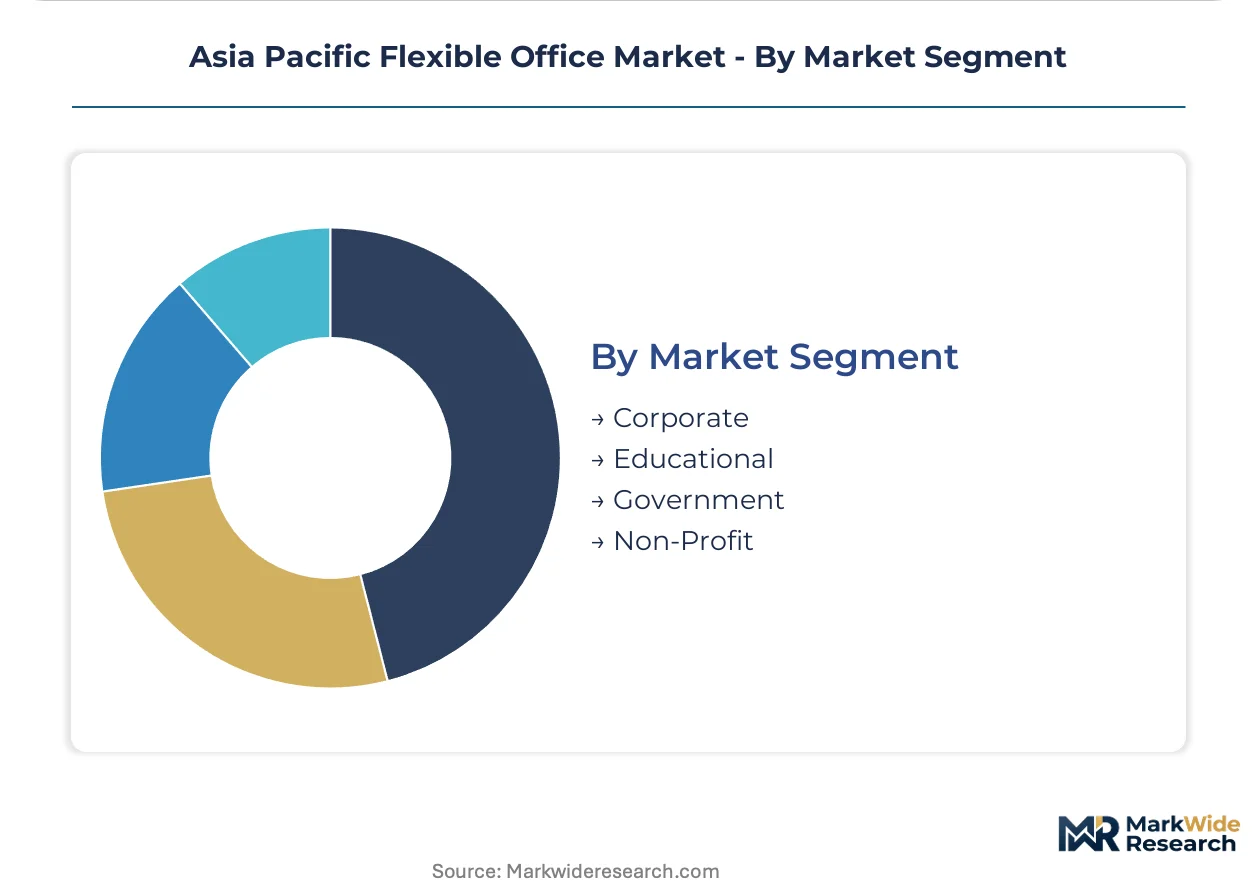
Market Segment:
Public sector eligibility requirements are filtering operator participation through certification barriers.
- Corporate:Profit-oriented entities across all industries. Financial services and technology sectors in India, Australia, and Singapore generate the majority of contracted seat volume through multi-location agreements.
- Government:Public sector agencies and state-owned enterprises. Singapore's BCA Green Mark certification functions as a gatekeeping requirement for lease eligibility, advantaging pre-certified operators.
- Educational:Universities, vocational training centers, and research institutions. Australia's state-level workplace safety frameworks impose psychological hazard assessment obligations for student-facing environments.
- Non-Profit:Charitable organizations and social enterprises. Cost sensitivity in this segment favors membership-based models with nonprofit pricing tiers available in Melbourne and Bangalore.
Corporate segments currently dominate revenue. Government procurement represents the fastest-climbing opportunity as certification standards harden across Asia Pacific capitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in the Asia Pacific flexible office market channel investment toward jurisdictions with streamlined compliance regimes and infrastructure subsidies. Cost-of-compliance gaps between mature and emerging markets accelerate operator expansion into secondary cities where fit-out standards remain less stringent.
Australia
Sydney and Melbourne anchor enterprise demand for premium flexible workspace as financial services firms consolidate vendor relationships through multi-city master agreements. State-level workplace safety frameworks in New South Wales and Victoria impose psychological hazard assessment obligations that filter mid-tier operators from public sector eligibility. The Sydney-Melbourne corridor concentrates Grade-A stock absorption where procurement teams negotiate utilization-based contracts.
Singapore
BCA Green Mark certification functions as a gatekeeping requirement for government lease eligibility, advantaging pre-certified operators in public sector procurement. The Building and Construction Authority mandates sustainability benchmarks that inflate capital intensity for new market entrants. Raffles Place and Marina Bay financial districts host the densest concentration of private office suites serving compliance-sensitive banking and wealth management operations.
India
TRAI broadband infrastructure mandates enable professional-grade remote work in Bangalore, Hyderabad, and Pune, dispersing technology employment beyond traditional headquarters clusters. The PLI scheme for IT hardware manufacturing accelerates satellite office demand in tier-two cities including Coimbatore and Kochi. Mumbai's Bandra-Kurla Complex and Delhi-NCR remain the primary markets for enterprise-grade flexible space serving multinational professional services firms.
Japan
METI building energy codes inflate fit-out capital intensity for existing stock conversion, extending payback periods on flexible space investments in Tokyo and Osaka. Stringent efficiency retrofit requirements compress operator margins during occupancy troughs in premium submarkets. The Marunouchi and Roppongi districts concentrate demand from financial services and technology enterprises seeking branded environments with dedicated security protocols.
Vietnam
Da Nang and Ho Chi Minh City host underpenetrated professional services clusters where first-mover operators establish brand presence before local competition consolidates. National infrastructure investment programs expand high-speed connectivity into secondary urban centers previously excluded from enterprise location strategies. The Thu Thiem new urban area in Ho Chi Minh City attracts speculative flexible office development targeting manufacturing supply chain services firms.
Asia Pacific Flexible Office Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with network-scale operators commanding enterprise procurement consolidation while single-location independents capture price-sensitive SME demand. The vendor base organizes around three strategic archetypes: multi-city platform operators leveraging density for utilization optimization, franchise-heavy expansion models minimizing capital deployment, and boutique providers competing on localized amenities. Competitive moves concentrate on geographic network expansion and sustainability certification acquisition as procurement filters harden.
Within the multi-city platform tier, JustCo and IWG exemplify divergent capital-light strategies for Asia Pacific penetration. JustCo leverages its Southeast Asian network density to sustain occupancy premiums in Singapore and Bangkok through cross-city membership portability. IWG anchors portfolio growth through franchise-heavy deployment into secondary Indian cities including Jaipur and Indore, transferring capital intensity to local partners. WeWork occupies a distinct position competing on brand recognition among multinational tenants seeking standardized workspace experiences across the Sydney-Melbourne corridor and Tokyo financial districts.
| Leading Market Players |
|---|
| JustCo |
| Spaces |
| IWG |
| Ucommune |
| Hive Worldwide |
| WeWork |
| Awfis |
| Smartworks |
| The Executive Centre |
| Others |
Value Chain & Pricing Dynamics
Singapore's BCA Green Mark certification gates both qualified supply and premium-tier pricing access, filtering operators from government lease eligibility while compressing margins for uncertified competitors. The mandate creates a bifurcated supply base where sustainability-compliant fit-out providers command pricing power over legacy operators.
Pricing Analysis
Direct-to-enterprise contracts bypass distributor markups entirely, compressing channel margins to near-zero for networked operators. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and geographic cluster density. Price differentiation hinges on BCA Green Mark tier and cross-city membership portability. Cost compression in economy tiers intensifies because franchise-heavy expansion transfers capital burden to local partners. Startups and freelancers exhibit highest price sensitivity; financial services procurement teams show lowest.
Supply Chain Analysis
Certification gating through Singapore's BCA Green Mark and Australia's state-level workplace safety frameworks fragments qualified supplier pools. Fit-out materials and smart building management systems concentrate supply from China, South Korea, and Japan. Single-source vulnerability runs through Taiwan-manufactured sensor hardware for occupancy analytics. Distribution runs through regional platform operators with multi-city density rather than independent location owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where enterprise procurement consolidation favors operators with certified sustainability credentials and cross-border network scale. Demand is shifting toward BCA Green Mark-compliant premium specifications that filter mid-tier competitors from public sector eligibility.
For Market Incumbents: Anchor portfolio yield through franchise-heavy deployment into India's tier-two cities, transferring fit-out capital intensity to local partners. Deepen cross-city membership portability to sustain occupancy premiums against emerging networked competitors. Certify additional locations under Singapore's BCA Green Mark to defend government lease eligibility as procurement filters harden. For New Entrants and Emerging Players: The premium-economy price-point gap in Vietnam's secondary cities offers first-mover positioning before local competition consolidates. Target Da Nang and Cebu professional services clusters with satellite office configurations serving manufacturing supply chain firms. Pursue embedded fintech bundling as a go-to-market angle for SME segments underserved by pure physical infrastructure plays. For Investors and Strategic Acquirers: Roll-up economics work for multi-city platform operators because enterprise procurement consolidation compresses addressable market for single-location independents. Long-term viability centers on network density enabling utilization optimization algorithms. Target acquisition archetype: scaled regional platforms with existing BCA Green Mark certification and cross-border membership systems. Watch hybrid work policy crystallization at Asia Pacific headquarters as the inflection indicator for seat-based contract velocity.| Strategic Initiative | Industry Significance |
|---|---|
| BCA Green Mark Certification Expansion | Unlocks Singapore government lease eligibility where procurement filters increasingly require sustainability credentials. |
| Franchise-Heavy Tier-Two City Expansion | Transfers capital intensity to local partners while capturing PLI scheme satellite office demand in India. |
| Cross-City Membership Portability | Sustains occupancy premiums through network density that single-location operators cannot replicate. |
| Embedded Fintech Platform Integration | Converges physical workspace with payroll and compliance tools for underserved SME segments. |
| Smart Building Management System Deployment | Delivers real-time utilization analytics that compress traditional landlord pricing premiums in competitive submarkets. |
Study Parameters
Coverage spans Australia, Singapore, India, Japan, and Vietnam, with primary inputs from each market's operator leadership and enterprise facilities managers. The study combines structured interviews with flexible office operators, commercial real estate landlords, and enterprise procurement directors with secondary validation. Secondary sources include BCA Green Mark certification databases, TRAI broadband infrastructure filings, METI building energy code compliance records, and state-level workplace safety framework documentation. Bottom-up seat-level modeling triangulates against top-down market sizing from commercial stock absorption data.
Rate-of-change decomposition separates volume expansion from yield compression dynamics across the analysis window. Segmentation dimensions modeled include product type, client archetype, service model, and market segment overlaid with certification tier and geographic cluster density. CAGRs derive from fitted trend analysis of historical absorption patterns adjusted for policy shock impacts. Forecast inputs incorporate hybrid work mandate diffusion rates and PLI scheme employment dispersion timelines.
Caveats apply where regulatory enforcement intensity or enterprise return-to-office directives could materially shift the outlook. Forecasts reflect assumptions about certification standard harmonization and infrastructure subsidy continuity. A model refresh is warranted upon material change in BCA Green Mark eligibility criteria or TRAI broadband mandate expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Australia Co-Working Office Spaces Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
Office Real Estate Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Italy Office Real Estate Market
Office Real Estate
Bahrain Co-Working Office Space Market
Office Real Estate
United Kingdom Flexible Office Space Market
Office Real Estate
Saudi Arabia Co-Working Office Spaces Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
France Office Real Estate Market