
 Qatar Co-Working Office Spaces Market | 2026-2036
Qatar Co-Working Office Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Co-Working Office Spaces Market Analytics
Subscription-based membership plans is expanding beyond traditional monthly desk rentals into bundled service tiers that incorporate meeting room credits, virtual office addresses, and event access. Regus leverages its international network to anchor premium positioning in Doha's West Bay corridor. Nest Qatar competes through localized community programming tailored to Qatari entrepreneurs and government contractors. Workinton differentiates by occupying mixed-use developments that combine retail, residential, and workspace functions in single footprints.
Co-working office spaces constitute commercially operated work environments featuring shared infrastructure, flexible lease terms, and professionally managed amenities, typically delivered through open-plan layouts with dedicated bandwidth allocation of 100 Mbps per workstation and ISO 14001-aligned facility management protocols. These spaces serve enterprises seeking capital-efficient real estate without long-term commercial lease obligations. Private offices command the highest margin pools among product types due to corporate demand for branded, secure environments, while hot desks represent the fastest-growing access tier as hybrid employees seek intermittent workspace. Membership plans dominate service type revenue through recurring billing structures, whereas virtual offices gain traction among foreign companies establishing Qatar legal presence without physical occupancy.
Qatar Financial Centre regulations shape market access by permitting full foreign ownership of co-working operators, while Qatar Central Bank compliance requirements influence fintech tenant onboarding procedures. The Ministry of Commerce and Industry's commercial licensing framework determines permissible activities within shared workspace premises. Stakeholders must monitor evolving municipal zoning interpretations for creative spaces outside designated business districts.
Market Dynamics
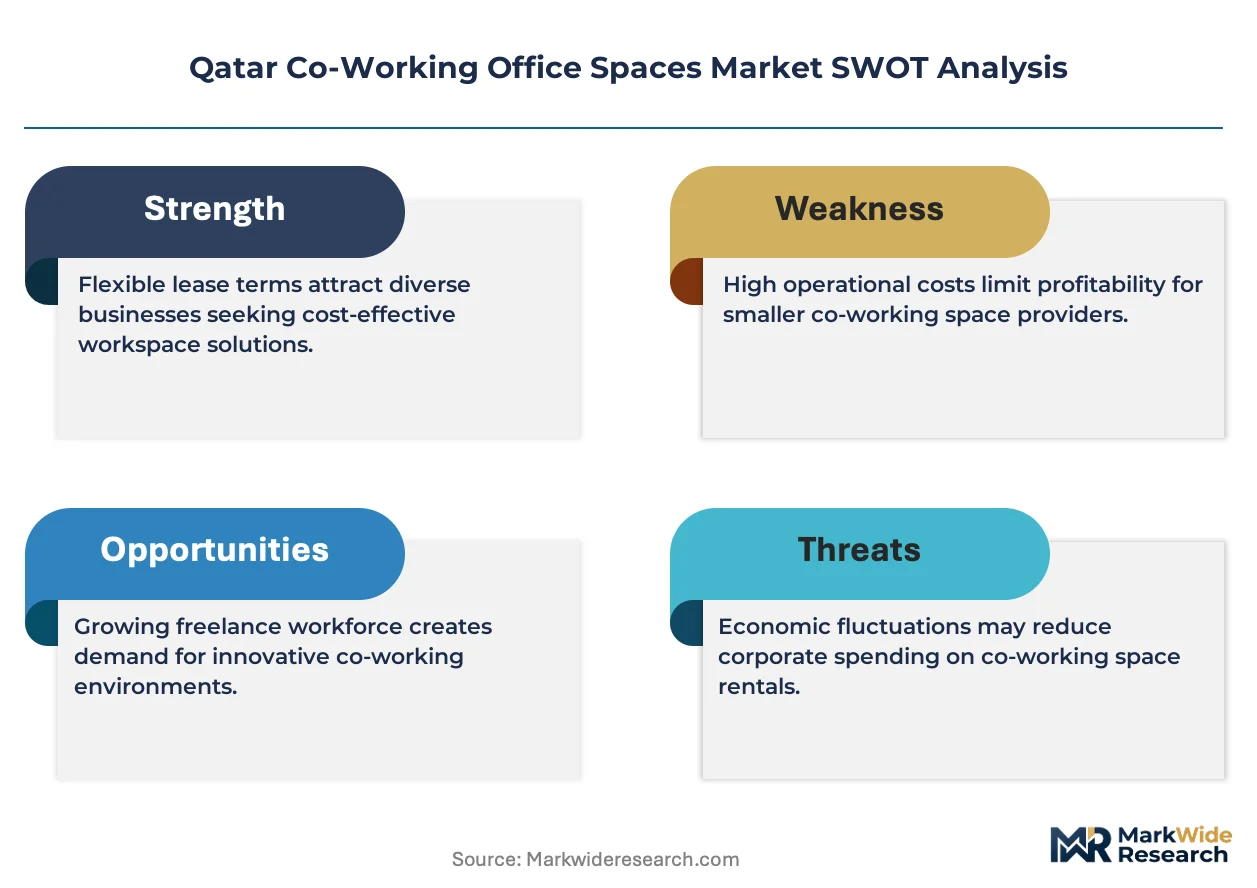
Qatar's hybrid work normalization is compressing traditional commercial lease cycles and redirecting tenant demand toward serviced workspace with embedded compliance infrastructure. This structural shift rewards operators capable of bundling physical space with regulatory navigation for foreign entrants.
Growth Catalysts
- Qatar Financial Centre licensing reforms:Full foreign ownership permissions for co-working operators eliminate joint-venture requirements, accelerating international brand entry into Doha and Lusail corridors.
- Fintech sector clustering:Qatar Central Bank compliance protocols for digital payment providers create captive demand for workspace with pre-certified data infrastructure and audit-ready documentation systems.
- Lusail City masterplan execution:Purpose-built mixed-use towers in the emerging district concentrate consulting and technology tenants seeking proximity to Qatar National Convention Centre and Lusail Stadium event traffic.
Market Restraints
- Prime real estate cost concentration:West Bay and Lusail commercial rents track oil-revenue cycles, creating margin compression for operators locked into long-dated property leases.
- Single-market dependency:Qatar's population base caps addressable demand versus regional peers, forcing operators to achieve occupancy rates above regional benchmarks to sustain unit economics.
- Visa sponsorship complexity:Ministry of Interior work permit requirements for foreign staff create operational friction distinct from free-zone jurisdictions elsewhere in the Gulf.
Strategic Opportunities
- Al Wakrah industrial corridor penetration:Logistics and maritime services tenants near Hamad Port remain underserved by premium workspace providers, creating first-mover positioning for port-adjacent facilities.
- Event-driven membership models:FIFA World Cup legacy infrastructure and recurring international summits enable operators to monetize transient executive demand through day-pass and week-pass tiers.
- Qatar Free Zones Authority expansion:New designated zones outside Doha proper offer regulatory sandbox environments for operators targeting manufacturing and R&D tenants with specialized facility requirements.
Industry Challenges
- ISO 14001 facility management certification:Environmental management system compliance requires specialized operational expertise scarce in local property management talent pools, extending onboarding timelines for new facilities.
- Bandwidth infrastructure scaling:100 Mbps per workstation specifications demand redundant fiber connectivity that outpaces telecommunications buildout in emerging districts, constraining rapid facility expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Co-Working Office Spaces Market |
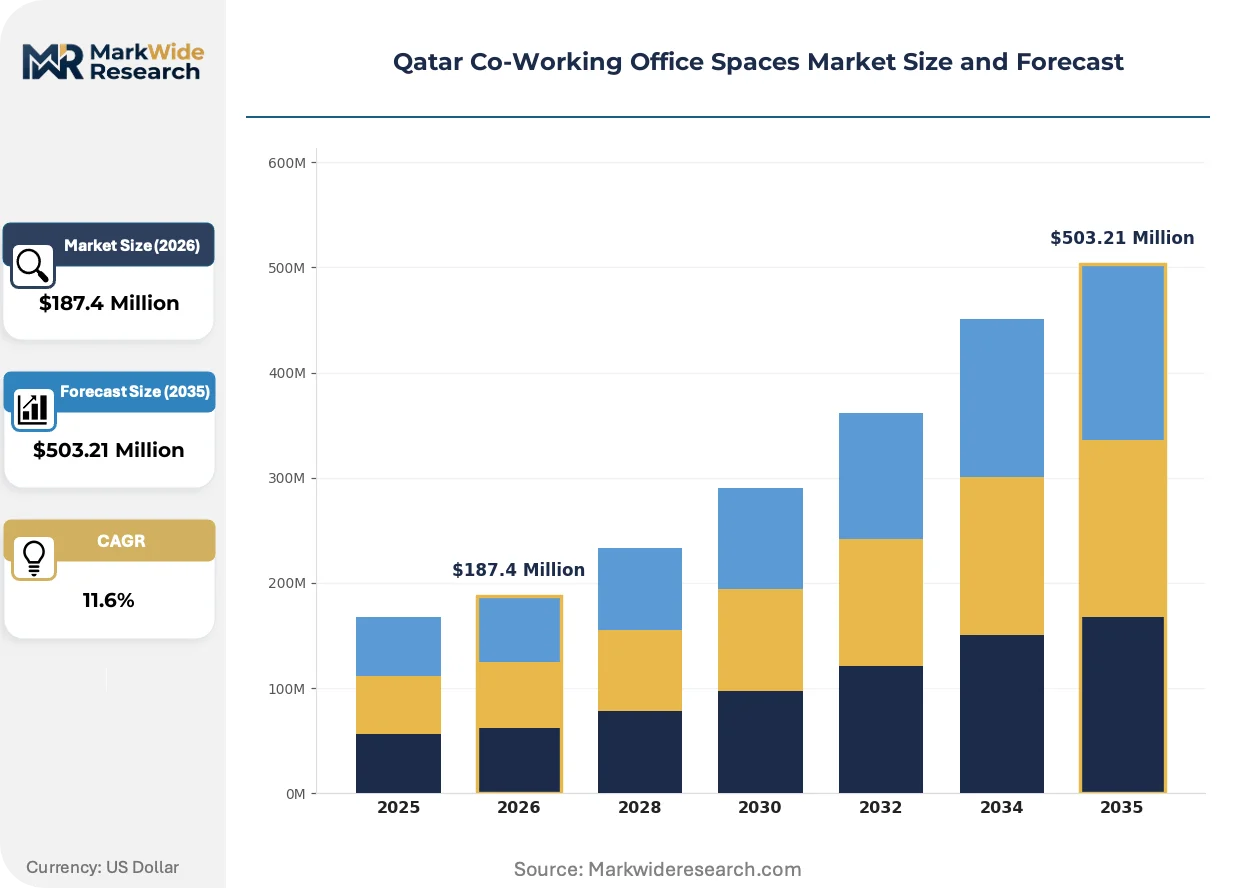
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Private Offices, Dedicated Desks, Hot Desks, Meeting Rooms Service Type: Membership Plans, Short-term Rentals, Event Hosting, Virtual Offices Industry Vertical: Freelancers, Startups, SMEs, Corporates Facility Type: Urban Centers, Suburban Areas, Business Hubs, Creative Spaces |
| Companies Covered | Alliance Business Centers Network, Ten Works Business Centre, Servcorp, EasyCowork, Coworker, Regus, Nest Qatar, Marhaba, Workinton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Co-Working Office Spaces Market Evolving Landscape
Workspace technology stacks are converging with building management systems to create environments where occupancy, energy, and security respond dynamically to tenant behavior patterns. This integration redefines competitive differentiation beyond square-meter pricing.
Smart building management platforms are integrating IoT sensor networks with automated climate and lighting controls to reduce per-workstation energy overhead. Fintech and consulting tenants with ESG reporting obligations prioritize these certified environments. The technology is integrating sustainability metrics directly into lease valuation models, compressing demand for legacy facilities lacking granular consumption tracking.
Qatar Central Bank's fintech sandbox regulations now mandate physical presence requirements for digital banking license applicants, reshaping workspace demand patterns. This policy creates captive demand for co-working locations with enhanced security clearances and segregated server room infrastructure. Fintech-focused operators in West Bay are responding by retrofitting private office suites with biometric access and dedicated power backup systems.
Enterprise procurement teams are consolidating vendor relationships through master service agreements covering multiple Gulf Cooperation Council markets. This behavior concentrates contract value with operators capable of delivering consistent service standards across Doha, Dubai, and Riyadh locations. Procurement pattern shifts are most visible among management consulting partnerships serving Qatar Petroleum and Qatar Investment Authority advisory mandates.
Qatar Co-Working Office Spaces Market Segmentation
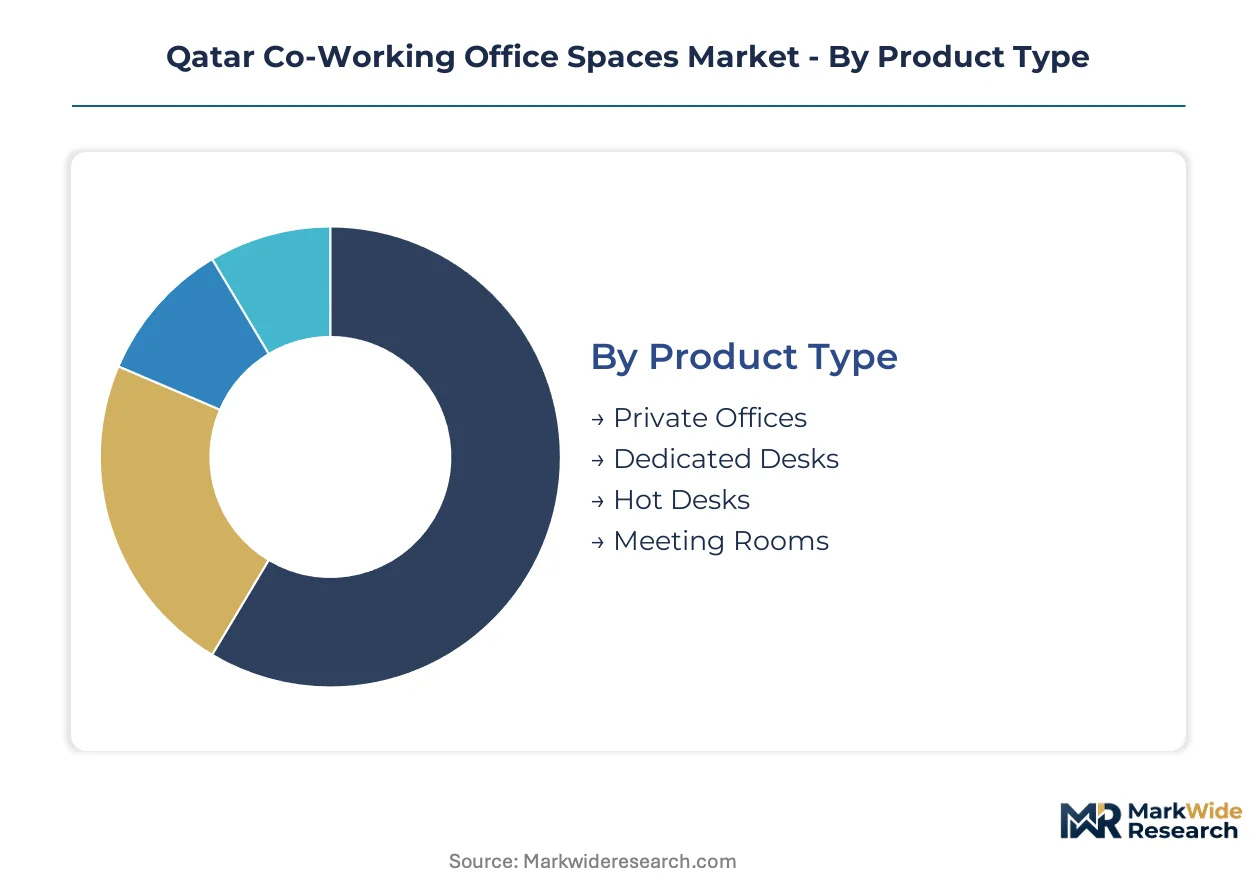
Qatar's co-working market segments reflect divergent tenant priorities across capital efficiency, regulatory compliance, and brand positioning. Understanding these splits enables operators to align facility investments with the specific infrastructure demands of fintech license applicants versus transient consulting teams.
Product Type:
Cost tier differentiation separates enterprise-grade secure environments from flexible access points for intermittent users.
- Private Offices:Enclosed suites with biometric access and dedicated server room proximity serve Qatar Central Bank fintech sandbox applicants requiring segregated infrastructure. Corporate advisory teams from Qatar Petroleum and Qatar Investment Authority mandate these environments for client confidentiality protocols.
- Hot Desks:Unassigned workstations with 100 Mbps dedicated bandwidth appeal to hybrid employees seeking intermittent presence without lease obligations. Demand concentrates in Lusail's emerging towers where consulting staff rotate between client sites and base operations.
- Dedicated Desks:Permanently assigned workstations in open floor plans balance cost control with territorial consistency for small product teams.
- Meeting Rooms:Bookable conference facilities with video infrastructure support pitch events and regulatory interviews without full office commitment.
Private offices lead volumes today; hot desks are gaining share fastest.
Service Type:
Application context determines whether tenants prioritize recurring access, episodic presence, or legal address utility.
- Membership Plans:Monthly billing structures with bundled meeting credits and virtual address services anchor operator revenue predictability. Fintech startups under Qatar Financial Centre licensing utilize tiered subscriptions to scale headcount without property lease renegotiation.
- Virtual Offices:Legal address provision without physical occupancy enables foreign companies to establish Qatar commercial presence for tender eligibility. Qatar Central Bank digital banking license mandates now require documented physical addresses, redirecting sandbox applicants toward compliant workspace providers.
- Short-term Rentals:Daily and weekly access tiers monetize transient demand from FIFA World Cup legacy event traffic and international summit delegations.
- Event Hosting:Conference and workshop facilitation services leverage proximity to Qatar National Convention Centre and Lusail Stadium infrastructure.
Membership plans dominate revenue composition; virtual offices are expanding most quickly.
Industry Vertical:
Customer maturity and procurement sophistication create diverging facility requirements across the tenant base.
- Corporates:Established enterprises with Qatar Petroleum or Qatar Investment Authority advisory mandates demand ISO 14001-certified environments with ESG-tracked energy consumption for sustainability reporting.
- Startups:Technology ventures scaling under Qatar Financial Centre streamlined licensing require flexible expansion terms and pre-certified data infrastructure.
- SMEs:Mid-sized professional services firms prioritize cost-efficient presence in West Bay corridor without capital-intensive fit-out investments.
- Freelancers:Independent contractors seek intermittent access with community programming for network development.
Corporate contracts anchor revenue stability; startup tenancy is climbing the fastest.
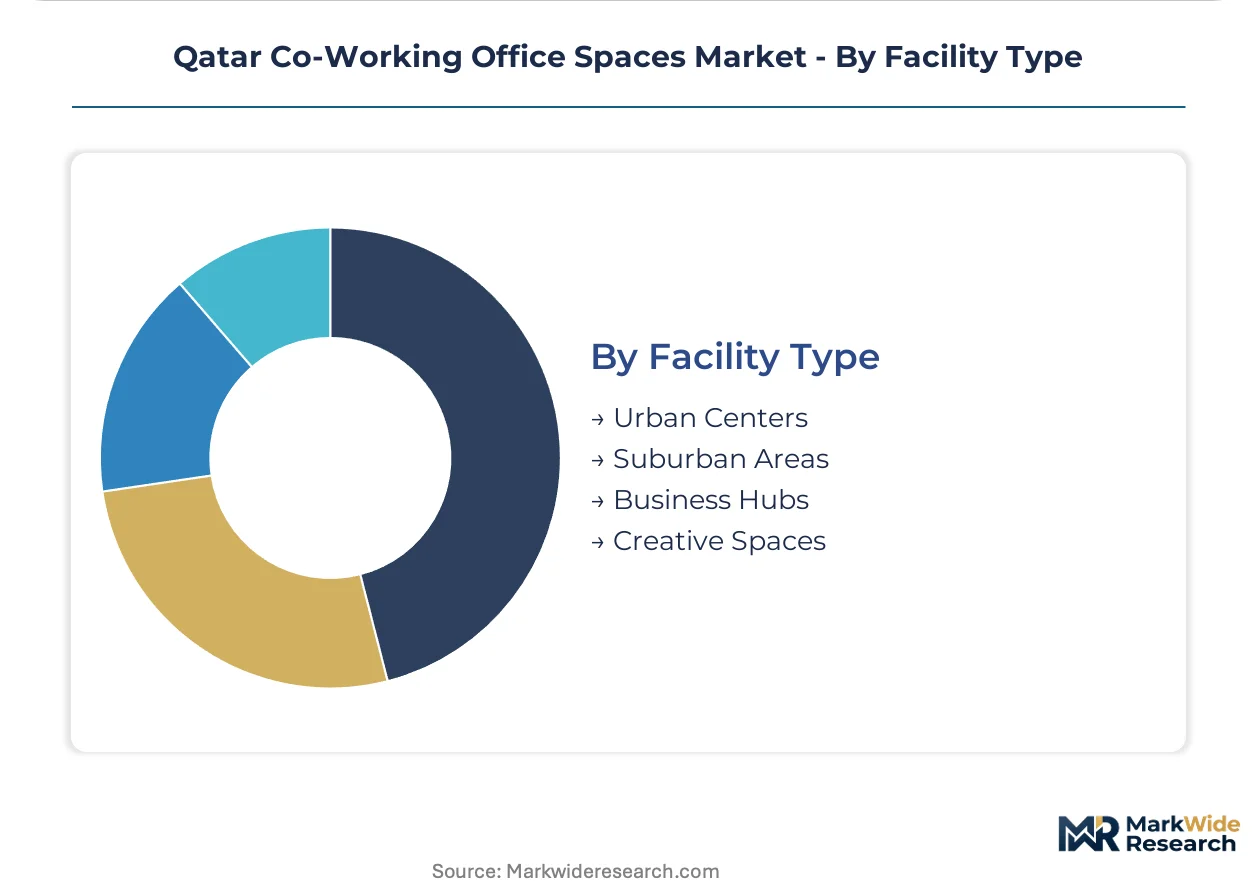
Facility Type:
Geography within Qatar determines accessibility to regulatory hubs, event traffic, and residential catchments.
- Business Hubs:West Bay and Lusail towers concentrate fintech and consulting demand through Qatar Financial Centre proximity and Qatar National Convention Centre access.
- Urban Centers:Doha proper locations capture government contractor demand requiring Ministry of Commerce and Industry accessibility.
- Suburban Areas:Al Wakrah corridor facilities near Hamad Port address underserved logistics and maritime services tenants with specialized workspace requirements.
- Creative Spaces:Municipal zoning interpretations outside designated business districts enable alternative format experimentation for design and media tenants.
Business hubs concentrate premium pricing power; suburban areas show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics in the Gulf co-working sector concentrate premium workspace investment in jurisdictions offering streamlined commercial licensing and full foreign ownership rights. Operators migrate capital toward markets where compliance costs compress setup timelines for international tenants.
West Bay
Qatar Financial Centre licensing reforms attract fintech sandbox applicants requiring segregated server infrastructure and biometric-secured private offices. The district's Grade A tower stock commands premium pricing from Qatar Petroleum advisory teams. Corporate procurement teams consolidate vendor relationships through master service agreements covering multiple Gulf Cooperation Council markets.
Lusail City
Purpose-built mixed-use developments concentrate consulting staff rotating between client sites and base operations. Proximity to Qatar National Convention Centre and Lusail Stadium infrastructure enables event-driven membership models monetizing transient executive demand. Ministry of Commerce and Industry accessibility supports government contractor tenancy.
Al Wakrah Corridor
Logistics and maritime services tenants near Hamad Port remain underserved by premium workspace providers. Qatar Free Zones Authority expansion creates regulatory sandbox environments for operators targeting manufacturing and R&D tenants with specialized facility requirements. First-mover positioning offers untapped industrial catchment penetration.
Doha Urban Core
Traditional commercial lease compression redirects tenant demand toward serviced workspace with embedded compliance infrastructure. Municipal zoning interpretations outside designated business districts enable creative space experimentation for design and media tenants. Hybrid work normalization accelerates demand for intermittent access tiers.
Qatar Co-Working Office Spaces Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with international network operators anchoring premium positioning while localized community programmers capture entrepreneurial demand. Market structure exhibits tiered concentration around three strategic archetypes: global workspace networks leveraging cross-border scale, regional specialists embedding regulatory navigation services, and mixed-use developers integrating retail-residential-workspace functions. Dominant competitive moves include portfolio diversification into virtual office tiers and strategic partnerships with property developers securing prime tower inventory.
Within the global network tier, Regus anchors premium positioning through international scale, while Servcorp occupies a position emphasizing serviced office infrastructure. Among localized specialists, Nest Qatar exemplifies community programming tailored to Qatari entrepreneurs, and Workinton represents mixed-use development integration. Alliance Business Centers Network sits within the regional expansion archetype, targeting multi-city coverage across Gulf markets. These players collectively illustrate how foreign ownership permissions under Qatar Financial Centre regulations accelerate brand entry while localized operators defend position through regulatory expertise and cultural programming.
| Leading Market Players |
|---|
| Alliance Business Centers Network |
| Ten Works Business Centre |
| Servcorp |
| EasyCowork |
| Coworker |
| Regus |
| Nest Qatar |
| Marhaba |
| Workinton |
| Others |
Value Network & Pricing Analysis
Corporate procurement teams consolidating vendor relationships through master service agreements spanning multiple Gulf Cooperation Council markets are compressing pricing power toward operators capable of delivering consistent service standards across Doha, Dubai, and Riyadh locations. This buyer concentration forces supply chain investments in cross-border facility standardization and certification alignment that elevate fixed costs while narrowing margin pools for single-market operators.
Pricing Analysis
Property developer margin layers dominate final tenant pricing, with tower owners capturing rent escalations tied to oil-revenue cycles that operators struggle to pass through in competitive submarkets. Three-tier pricing structure across premium biometric-secured private offices, standard dedicated desks, and economy hot desk tiers reflects ISO 14001 certification premiums and bandwidth allocation differentials. Cost compression in West Bay corridor intensifies as international brands anchor premium positioning while localized competitors undercut on community-programming value. Fintech sandbox applicants under Qatar Central Bank mandates exhibit lowest price sensitivity due to regulatory compliance requirements, whereas freelance intermittent users drive hot desk tier competition.
Supply Chain Analysis
ISO 14001 facility management certification requirements gate supplier eligibility, with environmental management system compliance demanding specialized operational expertise scarce in local property management talent pools. Supply concentrates in Qatar's domestic construction and telecommunications sectors for fit-out and fiber infrastructure, with redundant connectivity hardware sourced from UAE and Saudi distribution hubs. Raw material dependencies include imported climate control systems, biometric security hardware, and server room power backup equipment. Single-source vulnerability runs through Qatar's concentrated real estate developer base for prime tower inventory. Distribution runs through direct operator-developer negotiations for long-dated lease commitments, with sublease arrangements to enterprise tenants completing downstream value capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's co-working market has entered a late-cycle quality phase where premium specifications separating compliant fintech infrastructure from commodity desk rental now determine contract viability. Enterprise procurement consolidation toward multi-city master service agreements rewards operators with standardized certification stacks across Gulf Cooperation Council footprints.
For Market Incumbents: To counter margin compression from international brand entry under Qatar Financial Centre foreign ownership permissions, anchor defensive positioning through backward integration into property development partnerships securing prime West Bay and Lusail tower inventory. Prioritize ISO 14001 certification maintenance and biometric security infrastructure investments that fintech sandbox applicants under Qatar Central Bank mandates cannot source from commodity competitors. For New Entrants and Emerging Players: Logistics and maritime services tenants near Hamad Port in Al Wakrah corridor represent the most penetrable white-space segment, with Qatar Free Zones Authority expansion creating regulatory sandbox environments for specialized manufacturing and R&D facility requirements. Target event-driven membership models monetizing FIFA World Cup legacy infrastructure through day-pass and week-pass tiers for transient executive demand. Deploy port-adjacent positioning as differentiated go-to-market anchor against saturated Doha corridor competition. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists embedding regulatory navigation services for Qatar Financial Centre licensing and Qatar Central Bank compliance workflows. Long-term viability across a five-to-ten-year window favors operators with demonstrated multi-city standardization capability and property developer relationship depth. Monitor Qatar Central Bank digital banking license issuance velocity as inflection indicator for captive demand in biometric-secured private office tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Property Developer Partnership | Secures prime West Bay and Lusail tower inventory through long-dated lease commitments ahead of competitor entry. |
| ISO 14001 Certification Investment | Unlocks corporate advisory contracts from Qatar Petroleum and Qatar Investment Authority with ESG reporting obligations. |
| Biometric Security Infrastructure Deployment | Captures Qatar Central Bank fintech sandbox applicants requiring segregated server room access and audit-ready documentation. |
| Multi-City Master Service Agreement | Consolidates enterprise procurement relationships across Doha, Dubai, and Riyadh through standardized service tiers. |
| Event-Driven Membership Model | Monetizes Qatar National Convention Centre and Lusail Stadium traffic through transient day-pass and week-pass offerings. |
Research Methodology
Coverage spans West Bay, Lusail City, Al Wakrah corridor, and Doha urban core, with primary inputs from each sub-region combined with secondary validation across regulatory filings and trade data. Primary interviews engaged facility operations directors, property development leasing managers, fintech compliance officers under Qatar Central Bank supervision, and corporate real estate procurement leads at Qatar Petroleum and Qatar Investment Authority advisory firms. Secondary sources included Qatar Financial Centre licensing disclosures, Ministry of Commerce and Industry commercial permit databases, Qatar Central Bank fintech sandbox participant registries, and tower developer leasing reports. Bottom-up facility capacity and occupancy estimates triangulated against top-down market size derived from subscription revenue disclosures and virtual office registration trends.
Rate-of-change decomposition across the analysis window separated volume growth in workstation inventory from value growth in premium service tier mix and ancillary revenue per member. Segmentation dimensions modeled include product type, service tier, industry vertical, and facility geography, with cross-elasticities estimated between virtual office legal address demand and physical occupancy requirements under evolving Qatar Central Bank digital banking license mandates. CAGRs derived from logistic diffusion curves fitted to hybrid work adoption patterns and fintech sector employment growth, with sensitivity testing against oil-revenue cycle impacts on commercial rent escalations.
Underlying measurement precision varies by segment; West Bay and Lusail business hub data carry tighter precision than emerging suburban and creative space categories with less transparent leasing activity. Forecasts reflect assumptions around Qatar Financial Centre licensing reform continuity, Qatar Central Bank fintech sandbox expansion velocity, and Ministry of Interior work permit processing efficiency for foreign operator staff. A model refresh is warranted upon material change in Qatar Central Bank physical presence requirements for digital banking license applicants or Qatar Free Zones Authority zone designation announcements affecting industrial corridor facility permissions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Market
Office Real Estate
Saudi Arabia Real Estate Brokerage Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
United States Office Real Estate Market
Office Real Estate
Asean Office Real Estate Market
Office Real Estate
Global Office Space Market
Office Real Estate
India Office Real Estate Market
Office Real Estate
Germany Office Real Estate Market
Office Real Estate
UAE Flexible Office Space Market
Office Real Estate
United Kingdom Office Real Estate Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Saudi Arabia Flexible Office Space Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
Latin America Office Real Estate Market