
 UAE Clinical Laboratory Services Market | 2026-2036
UAE Clinical Laboratory Services Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Clinical Laboratory Services Market Analytics
Aftermarket service revenue from routine re-testing and chronic disease monitoring is narrowing the margin gap between hospital-affiliated laboratories and independent diagnostic chains. Al Borg Laboratories leverages its extensive branch network across the Emirates to sustain same-day turnaround commitments. Synlab competes through centralized hub-and-spoke logistics that anchor high-throughput processing in Abu Dhabi and Dubai. Purehealth differentiates by integrating laboratory data with its broader health informatics platform.
Clinical laboratory services encompass the analytical testing of patient specimens including blood, tissue, urine, and other biological samples using standardized protocols with turnaround times typically ranging from hours for stat chemistry panels to several days for complex molecular analyses, serving primarily to inform clinical decision-making, disease surveillance, and treatment monitoring. Biochemistry and hematology segments dominate routine test volumes due to their role in diabetes management and pre-operative screening across the UAE's hospital networks. PCR and mass spectrometry technologies are capturing expanding share in genetic testing and personalized medicine applications, where higher complexity commands premium pricing.
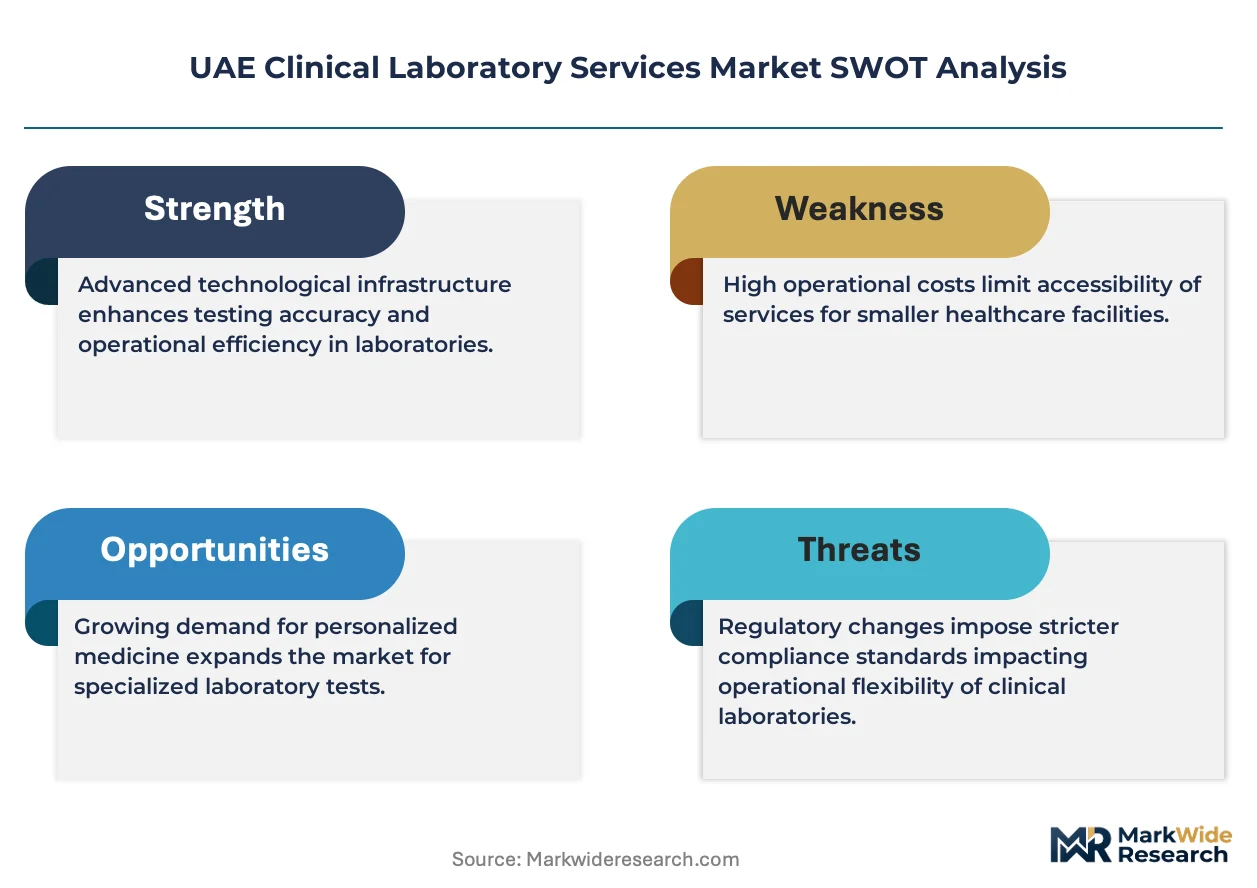
MOHAP enforces laboratory licensing and proficiency testing standards that shape capital investment decisions for new entrants, while the country's national pharmaceutical regulator mandates specific quality management systems for molecular diagnostic facilities. Dubai Health Authority and Abu Dhabi Department of Health maintain separate accreditation pathways that create localized compliance obligations for multi-emirate operators. Stakeholders must monitor evolving federal-unified licensing proposals that could reshape competitive barriers across the seven Emirates.
Market Dynamics
Hospital networks across the Emirates are consolidating diagnostic procurement under centralized agreements, compressing margins for independent laboratories while elevating volume guarantees that reshape competitive positioning.
Growth Catalysts
- MOHAP Quality Mandates:Mandatory accreditation protocols for independent laboratories are accelerating capital investment in automated platforms, filtering out undercapitalized competitors.
- Medical Tourism Clusters:Dubai's healthcare free zones concentrate specialized diagnostic demand from regional patients seeking complex genetic and molecular testing unavailable in home markets.
- PCR Platform Expansion:Post-pandemic infrastructure deployment has repurposed molecular testing capacity toward oncology screening and pharmacogenomics applications.
Market Restraints
- Reagent Import Dependency:Over 80% of diagnostic consumables flow through consolidated European and North American suppliers, exposing margins to currency volatility and shipping disruptions.
- MOHAP-DHA Regulatory Divergence:Separate licensing pathways between federal and emirate-level health authorities create duplicated compliance costs for multi-emirate operators.
- Point-of-Care Substitution:Bedside testing platforms in tertiary hospitals are capturing routine chemistry and hematology volumes previously referred to central laboratories.
Strategic Opportunities
- Abu Dhabi Biosurveillance Contracts:The emirate's public health authority is tendering population-scale screening programs for diabetes and cardiovascular risk stratification.
- AI-Enabled Pathology:Integration of digital slide scanning with machine learning classification algorithms is opening remote diagnostic services to smaller hospital networks.
- Direct-to-Consumer Channel:Wellness screening packages marketed through employer benefit programs and retail pharmacy partnerships bypass traditional physician referral workflows.
Industry Challenges
- Molecular Diagnostics Talent Scarcity:Qualified genetic counselors and bioinformatics specialists command premium compensation in Dubai's competitive healthcare labor market.
- ISO 15189 Certification Timelines:New entrants face 18-24 month accreditation cycles that delay revenue generation and strain pre-operational cash reserves.
- Legacy HIS Integration:Hospital information systems deployed across Emirates-based networks require customized middleware development for seamless laboratory data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Clinical Laboratory Services Market |
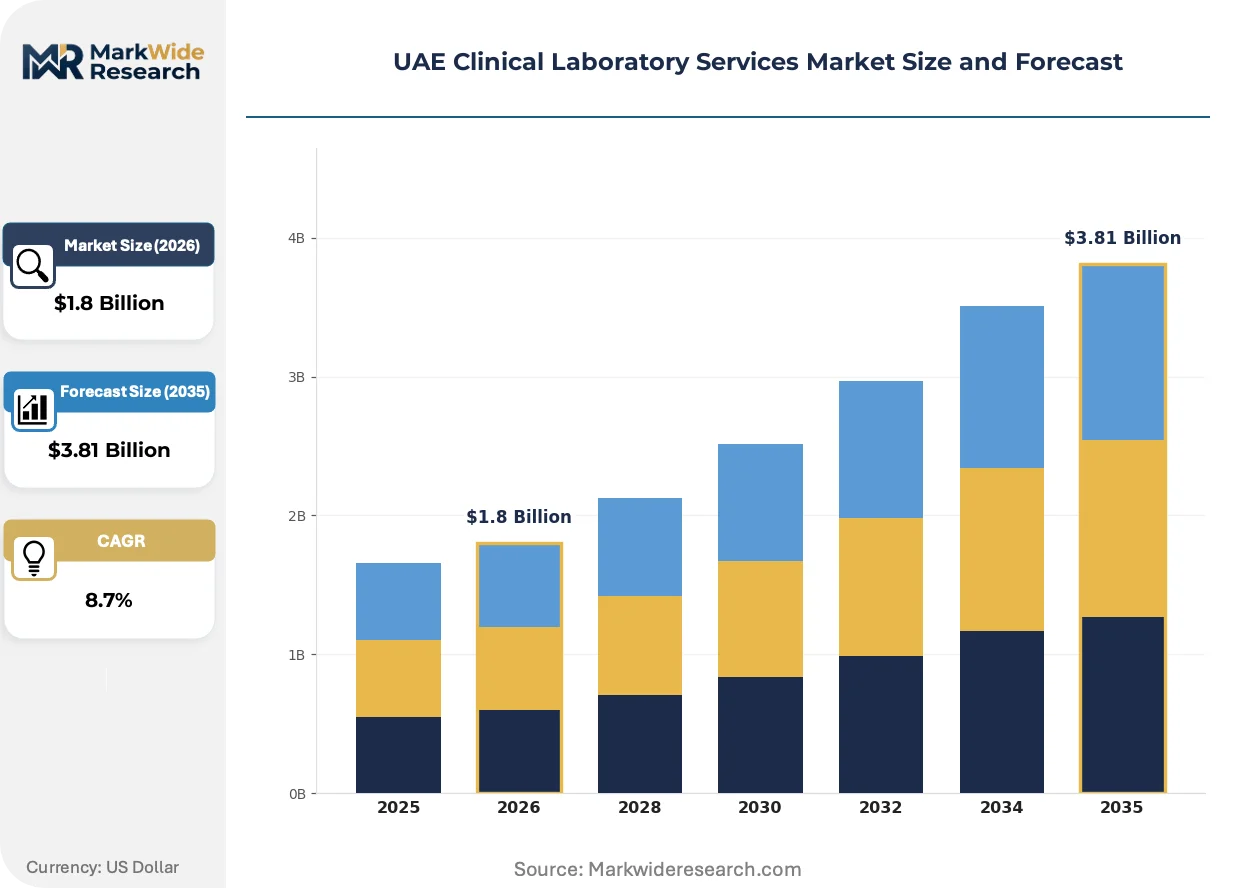
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biochemistry, Hematology, Microbiology, Pathology Technology: PCR, Immunoassays, Flow Cytometry, Mass Spectrometry End User: Hospitals, Diagnostic Centers, Research Labs, Outpatient Clinics Application: Clinical Diagnosis, Drug Testing, Disease Screening, Genetic Testing |
| Companies Covered | Al Borg Laboratories, MENA Labs, NMC Healthcare Labs, Unilabs, Purehealth, HealthHub Laboratories, Medsol, Synlab, National Reference Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Clinical Laboratory Services Market Evolving Landscape
Digital pathology platforms and automated pre-analytical systems are compressing turnaround commitments from days to hours, resetting customer expectations across outpatient and inpatient segments.
Liquid biopsy technologies are digitizing cancer surveillance workflows by enabling serial monitoring through peripheral blood draws rather than invasive tissue sampling. Oncology departments within Dubai Health Authority-affiliated hospitals are adopting these platforms for treatment response assessment. This shift is digitizing the traditional histopathology revenue model toward recurring testing relationships.
MOHAP's federal-unified licensing proposals are harmonizing quality standards that currently fragment across seven Emirates. The consolidation would eliminate redundant inspection cycles for multi-site operators. Independent diagnostic chains with existing ISO 15189 infrastructure are positioning to capture accelerated approval timelines under the streamlined framework.
Employer-sponsored wellness screening is displacing physician-gatekept laboratory access as the dominant channel for routine health assessments. Corporate benefit managers in Abu Dhabi's energy and finance sectors are negotiating direct contracts with diagnostic providers. This channel shift is most pronounced among expatriate professional populations with limited time availability for clinic appointments.
UAE Clinical Laboratory Services Market Segmentation
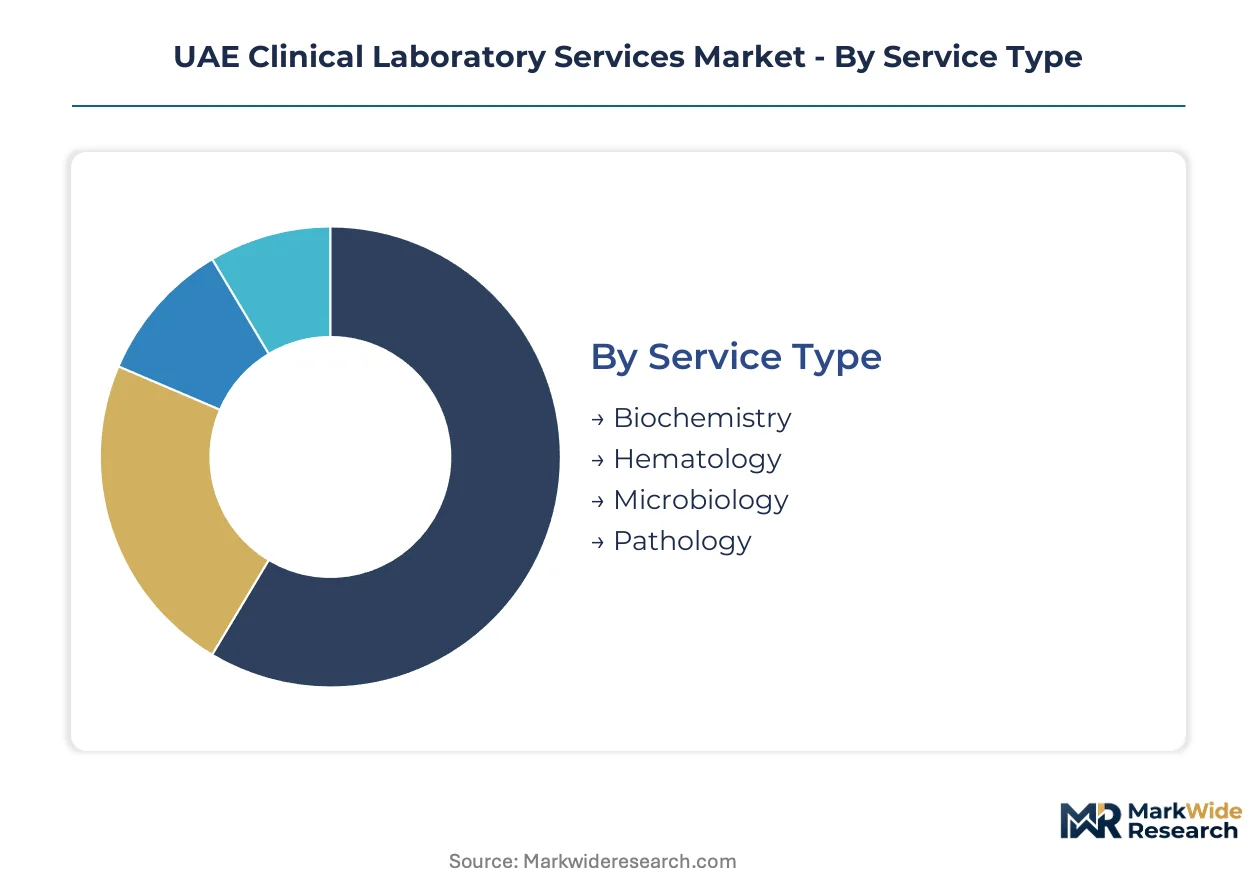
Segmentation in the UAE clinical laboratory services market reveals how testing complexity, regulatory requirements, and procurement patterns concentrate value across distinct service categories. Understanding these divisions exposes where capital investment flows and where margin compression threatens independent operators.
Service Type:
After-sales service intensity varies sharply across service types, with routine panels requiring minimal technical support while molecular diagnostics demand continuous calibration and reagent replenishment contracts.
- Biochemistry:Automated analyzers process blood glucose, lipid panels, and liver function tests through enzymatic and colorimetric methods. Demand concentrates in Dubai's hospital networks managing diabetes prevalence among South Asian expatriate populations, where same-day turnaround expectations sustain premium pricing for stat testing.
- Hematology:Complete blood count and coagulation profiling utilize automated cell counters and flow-based detection systems. Pre-operative screening protocols across Abu Dhabi's surgical centers drive volume concentration, though reimbursement compression under centralized procurement agreements is narrowing margins for independent chains.
- Microbiology:Culture-based identification and antimicrobial susceptibility testing address infectious disease management.
- Pathology:Histopathological examination and cytopathology services support oncology diagnostics through tissue processing and microscopic analysis.
Biochemistry holds the largest share; momentum sits with Pathology as digital platforms expand remote diagnostic capabilities.
Technology:
Capital deployment patterns across technology platforms reflect the tension between throughput economics and test complexity premiums.
- PCR:Polymerase chain reaction platforms amplify DNA sequences for infectious disease and genetic mutation detection. Post-pandemic infrastructure across Dubai Healthcare City now serves oncology screening and pharmacogenomics applications, repurposing installed capacity toward higher-margin recurring testing relationships.
- Immunoassays:Antibody-antigen binding reactions detect hormones, tumor markers, and cardiac biomarkers through chemiluminescence and ELISA formats. Endocrine testing demand from Abu Dhabi's employer wellness programs sustains volume, though point-of-care substitution in tertiary hospitals is capturing routine panels.
- Flow Cytometry:Laser-based cell sorting and immunophenotyping characterize hematological malignancies and immune status.
- Mass Spectrometry:Ion separation techniques enable precise quantification of small molecules, proteins, and metabolites in complex biological matrices.
Immunoassays dominate current installed base; mass spectrometry is climbing the fastest as personalized medicine applications expand.
End User:
Procurement concentration shapes competitive access, with hospital networks consolidating vendor agreements while outpatient channels fragment across independent operators.
- Hospitals:Tertiary and secondary care institutions operate captive laboratories or contract centralized diagnostic services. Dubai Health Authority-affiliated facilities are integrating AI-enabled pathology platforms, creating technology upgrade cycles that favor vendors with informatics capabilities.
- Diagnostic Centers:Independent chains and single-site operators serve walk-in patients and external referrals. Al Borg Laboratories and Synlab compete through branch density and hub-and-spoke logistics, though MOHAP accreditation timelines strain pre-operational cash reserves for new entrants.
- Research Labs:Academic and pharmaceutical research facilities require specialized analytical services for clinical trial support.
- Outpatient Clinics:Physician practices and polyclinics refer specimens to external laboratories for routine testing.
Hospitals command the greatest volume; diagnostic centers are gaining share fastest as employer-sponsored wellness screening bypasses traditional referral channels.
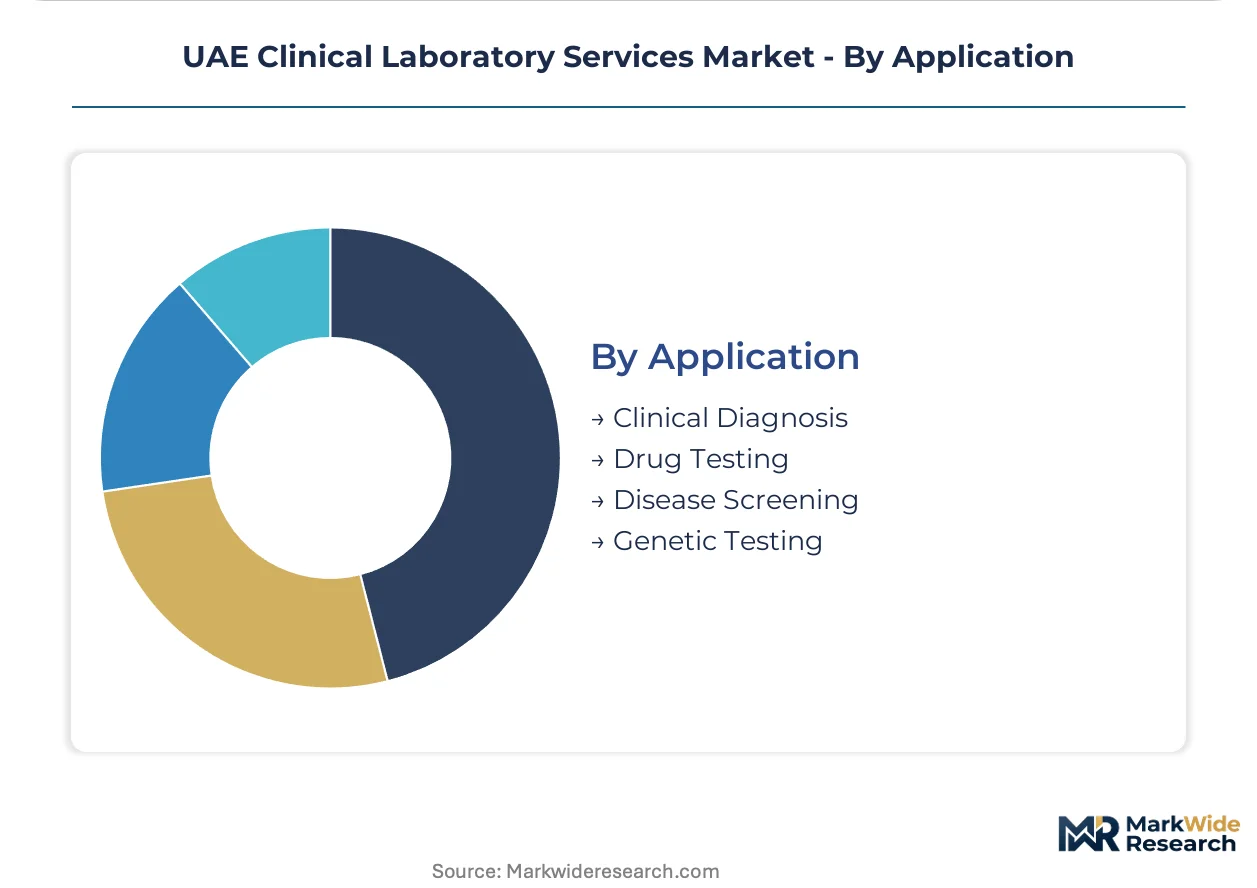
Application:
Revenue stability diverges across applications, with acute diagnosis yielding episodic revenue while chronic monitoring generates predictable recurring streams.
- Clinical Diagnosis:Acute and chronic disease confirmation through laboratory evidence supports treatment decisions across UAE hospital networks. Diabetes management protocols in Dubai's South Asian communities sustain biochemistry panel demand, with HbA1c and microalbumin testing forming core monitoring bundles.
- Drug Testing:Workplace compliance screening and therapeutic drug monitoring serve Abu Dhabi's energy and construction sectors. Pre-employment and random testing mandates in safety-critical industries create contracted revenue streams with lower price sensitivity than clinical diagnostics.
- Disease Screening:Asymptomatic population testing for cardiovascular, metabolic, and oncological risk factors.
- Genetic Testing:Inherited disorder carrier screening, prenatal diagnostics, and pharmacogenomic profiling.
Clinical Diagnosis represents the largest revenue pool; genetic testing shows the steepest expansion trajectory as medical tourism clusters attract regional patients seeking advanced molecular services unavailable in home markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic consumption patterns vary sharply across the Emirates, with Dubai prioritizing medical tourism and complex molecular testing while Abu Dhabi concentrates on population-scale screening contracts. Northern Emirates exhibit higher dependency on referral networks to centralized hubs.
Dubai
Medical tourism clusters in Dubai Healthcare City and Dubai Science Park concentrate specialized genetic and oncology diagnostic demand from regional patients. Dubai Health Authority maintains separate accreditation pathways from federal standards, creating localized compliance obligations. Healthcare free zones host specialized diagnostic facilities serving both international patients and local South Asian expatriate communities with diabetes management protocols.
Abu Dhabi
The emirate's public health authority tenders population-scale biosurveillance programs for diabetes and cardiovascular risk stratification. Department of Health Abu Dhabi enforces quality management systems distinct from MOHAP federal protocols. Khalifa City and Al Maryah Island medical districts anchor high-throughput processing capacity for employer-sponsored wellness screening in energy and finance sectors.
Sharjah
University teaching hospitals and research institutions drive clinical trial support and specialized analytical services demand. Sharjah Health Authority coordinates with federal regulators on laboratory licensing harmonization initiatives. Industrial zones near Sharjah International Airport facilitate logistics for diagnostic reagent import and distribution to northern catchment areas.
Northern Emirates
Ras Al Khaimah and Fujairah exhibit limited captive laboratory capacity, routing complex specimens to Dubai and Abu Dhabi hubs. Federal MOHAP protocols govern licensing for independent operators serving dispersed coastal and mountain populations. Expansion of primary care polyclinics is generating outbound referral volume for routine biochemistry and hematology panels.
Ajman and Umm Al Quwain
Smaller emirates rely heavily on branch networks of Dubai-based diagnostic chains for same-day turnaround commitments. MOHAP mandatory quality accreditation applies uniformly, filtering out undercapitalized local entrants. Emerging healthcare investment zones are attracting satellite collection centers from established multi-emirate operators.
UAE Clinical Laboratory Services Market Competitive Landscape
Capability concentration sits with hospital-affiliated networks possessing integrated informatics platforms; scale advantage sits with independent chains deploying hub-and-spoke logistics across multiple Emirates. The market structures around three tiers: tertiary hospital captives, multi-branch independent chains, and single-site specialty laboratories. Strategic archetypes include branch-density operators competing on turnaround time, centralized high-throughput processors competing on cost, and platform-integrated health systems competing on data continuity. Dominant competitive moves encompass geographic expansion through greenfield collection centers and technology licensing for digital pathology integration.
Within the branch-density tier, Al Borg Laboratories leverages its extensive network across the Emirates to sustain same-day service commitments. Synlab occupies a position exemplifying centralized hub-and-spoke logistics, anchoring high-throughput processing in Abu Dhabi and Dubai. Purehealth represents the platform-integrated archetype, connecting laboratory data with broader health informatics infrastructure.
| Leading Market Players |
|---|
| Al Borg Laboratories |
| MENA Labs |
| NMC Healthcare Labs |
| Unilabs |
| Purehealth |
| HealthHub Laboratories |
| Medsol |
| Synlab |
| National Reference Laboratories |
| Others |
Value Network & Pricing Analysis
Jebel Ali Port container handling costs filter through every diagnostic reagent shipment entering the UAE, concentrating pricing power among distributors with bonded warehouse capacity while fragmenting downstream price differentiation across hospital networks and independent laboratory tiers.
Pricing Analysis
Long-term reagent offtake agreements dominate procurement relationships between hospital networks and European diagnostic suppliers, locking in volume commitments that insulate large operators from spot market volatility. Price differentiation rests on ISO 15189 certification tier and after-sales technical support bundling, with accredited facilities commanding 15-20% premiums over uncertified competitors. Cost compression in routine biochemistry panels is intensifying because centralized hospital procurement agreements are squeezing independent chain margins. Employer wellness programs exhibit lowest price sensitivity due to corporate benefit budget structures, while outpatient walk-in segments face highest sensitivity as consumers compare transparent package pricing.
Supply Chain Analysis
Tariff exposure between Germany and the UAE shapes reagent import economics, with diagnostics consumables flowing through consolidated European suppliers creating currency-linked margin volatility for local distributors. Geographic supply concentration centers on Germany, Switzerland, and the United States for high-complexity analyzers and molecular testing platforms. Raw material dependencies encompass specialized enzymes, monoclonal antibodies, and fluorescent detection chemistries. Single-source vulnerability persists for mass spectrometry reference standards and PCR thermocycler components. Distribution runs through Jebel Ali free zone consolidation hubs before last-mile delivery to Dubai Healthcare City and Abu Dhabi medical districts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from reagent replenishment contracts and equipment maintenance agreements is expanding faster than capital equipment sales, creating recurring revenue pools that justify premium valuations for platform-integrated operators.
For Market Incumbents: Insulate core hospital network relationships through captive reagent supply agreements that raise switching costs for procurement committees. Deepen backward integration into pre-analytical automation to offset point-of-care substitution threats in tertiary facilities. Lock in multi-year ISO 15189 certification investments ahead of MOHAP's federal-unified licensing harmonization to capture accelerated approval timelines. For New Entrants and Emerging Players: Build out employer-sponsored wellness screening channels in Abu Dhabi's energy and finance sectors, where corporate benefit managers seek direct diagnostic contracts bypassing traditional physician referrals. Target Northern Emirates satellite collection center networks, where dispersed populations and limited captive laboratory capacity create white-space logistics opportunities. Pursue pharmacy-retail partnerships as the go-to-market angle for routine health assessment packages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-integrated health systems with informatics capabilities over pure-play branch-density operators. Long-term viability over the next decade rests on AI-enabled pathology integration and liquid biopsy platform adoption. Acquisition target archetype: centralized high-throughput processors with existing MOHAP accreditation and unused molecular testing capacity. The signal to watch is Dubai Health Authority's digital pathology tender awards as inflection indicator for technology upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15189 Certification Investment | Accelerates MOHAP approval timelines under federal-unified licensing proposals. |
| AI-Enabled Pathology Platform Integration | Opens remote diagnostic services to smaller hospital networks lacking in-house expertise. |
| Employer Wellness Program Direct Contracting | Bypasses physician-gatekept referral workflows in Abu Dhabi's corporate benefit sector. |
| Liquid Biopsy Technology Licensing | Digitizes oncology revenue models toward recurring serial monitoring relationships. |
| Hub-and-Spoke Logistics Expansion | Captures Northern Emirates referral volume through same-day turnaround commitments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors at Dubai Health Authority-affiliated hospitals, procurement managers at multi-emirate diagnostic chains, biomedical engineers overseeing analyzer platforms, and MOHAP regulatory affairs specialists. Secondary validation drew from hospital procurement databases, GPO contract filings, ISO 15189 accreditation registries, and customs reagent import records. Bottom-up test volume modeling and top-down healthcare expenditure allocation were triangulated to constrain estimate variance.
Calibration against historical accreditation timelines and capital deployment patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type complexity tier, technology platform maturity, end-user procurement concentration, and application revenue stability. CAGRs were derived from test volume elasticity assumptions and pricing trajectory scenarios. Industry-specific forecast inputs included MOHAP regulatory harmonization implementation pace and medical tourism patient inflow patterns.
Stress conditions across reagent import cost inflation, accreditation timeline delays, and point-of-care substitution penetration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology adoption curves. Molecular diagnostics talent scarcity and currency volatility represent specific risk factors that could materially revise projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Karyotyping Service Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
LIMS Market
Laboratory Services
US Clinical Laboratory Services Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Global Cell Viability Assays Market
Laboratory Services
US Laboratory Disposable Products Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Pathology Laboratories Market
Laboratory Services
Global Clinical Reference Laboratory Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Laboratory Developed Tests Market
Laboratory Services
AI in Laboratory Solution Market