
 Preeclampsia Laboratory Testing Market | 2026-2036
Preeclampsia Laboratory Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Preeclampsia Laboratory Testing Market Analytics
China is reconfiguring its domestic diagnostics supply chain through large-scale biomanufacturing investments in Shanghai and Suzhou. F. Hoffmann-La Roche Ltd leverages its automated immunoassay platforms to sustain high-throughput screening workflows in European hospital networks. Siemens Healthineers AG anchors its competitive position through integrated imaging and laboratory informatics systems that span prenatal care pathways. PerkinElmer Inc. specializes in neonatal and maternal health assay development, occupying a defined niche within the broader women's health diagnostics landscape.
Preeclampsia laboratory testing encompasses quantitative biochemical analysis of maternal serum and plasma biomarkers—particularly the soluble fms-like tyrosine kinase 1 to placental growth factor ratio—to assess endothelial dysfunction and placental insufficiency before clinical symptom onset. These assays serve the primary purpose of stratifying pregnant patients by risk severity, enabling clinicians to differentiate between gestational hypertension and true preeclampsia requiring intervention. Blood tests dominate current clinical practice due to established reimbursement pathways and standardized collection protocols, while molecular diagnostics represents the fastest-expanding technology segment as PCR and next-generation sequencing methods enter validation for early first-trimester prediction. Diagnostic laboratories capture the largest share of end-user demand through centralized processing economies, though outpatient clinics are building in-house capacity to reduce result turnaround times for urgent triage decisions.
The FDA regulates preeclampsia biomarker assays as Class II medical devices under 510(k) premarket notification requirements, while the EMA's In Vitro Diagnostic Medical Devices Regulation mandates clinical performance studies for CE marking across EU member states. China's NMPA enforces GB standard compliance for imported diagnostic reagents, creating layered market access conditions that favor localized manufacturing partnerships. Stakeholders must monitor evolving payer evidence requirements as health technology assessment bodies in Germany and France scrutinize cost-effectiveness data for predictive screening versus symptomatic diagnosis protocols.
Market Dynamics
Integrated biomarker panel adoption is compressing standalone assay demand as hospitals consolidate testing workflows around multi-analyte platforms that reduce per-patient diagnostic costs.
Growth Catalysts
- Statutory Reimbursement Expansion:Germany's statutory health insurance system now covers predictive sFlt-1/PlGF ratio screening, eliminating out-of-pocket barriers for routine maternal monitoring.
- Automated Platform Integration:High-throughput immunoassay systems in European hospital networks enable batch processing of risk stratification panels during first-trimester visits.
- FDA 510(k) Streamlining:The FDA's abbreviated review pathway for novel preeclampsia risk assays compresses commercialization timelines from 18 months to under 12 months for predicate-backed submissions.
Market Restraints
- Reagent Supply Concentration:Monoclonal antibody production for sFlt-1 and PlGF capture reagents clusters among three contract biomanufacturers in Switzerland and Germany.
- Validation Cost Burden:Clinical performance studies required under the EU's In Vitro Diagnostic Medical Devices Regulation impose six-figure certification costs on assay developers.
- Ultrasound Substitution:Doppler velocimetry and uterine artery screening protocols in tertiary care centers divert demand from biochemical testing for placental insufficiency assessment.
Strategic Opportunities
- First-Trimester Molecular Screening:PCR-based placental RNA signatures validated for pre-symptomatic detection open reimbursement negotiations with US maternal-fetal medicine networks.
- Point-of-Care Deployment:Portable immunoassay readers in US outpatient clinics reduce result turnaround from 48 hours to under 90 minutes for urgent triage decisions.
- China Localization Mandates:NMPA biomanufacturing partnerships in Shanghai and Suzhou bypass import reagent tariffs and accelerate hospital procurement approvals.
Industry Challenges
- Interoperability Friction:Laboratory information system integration with legacy electronic health record architectures delays biomarker result availability at the point of clinical decision.
- Specialist Workforce Constraints:Maternal-fetal medicine fellowship programs produce insufficient board-certified specialists to interpret complex multi-marker risk scores across expanding hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preeclampsia Laboratory Testing Market |
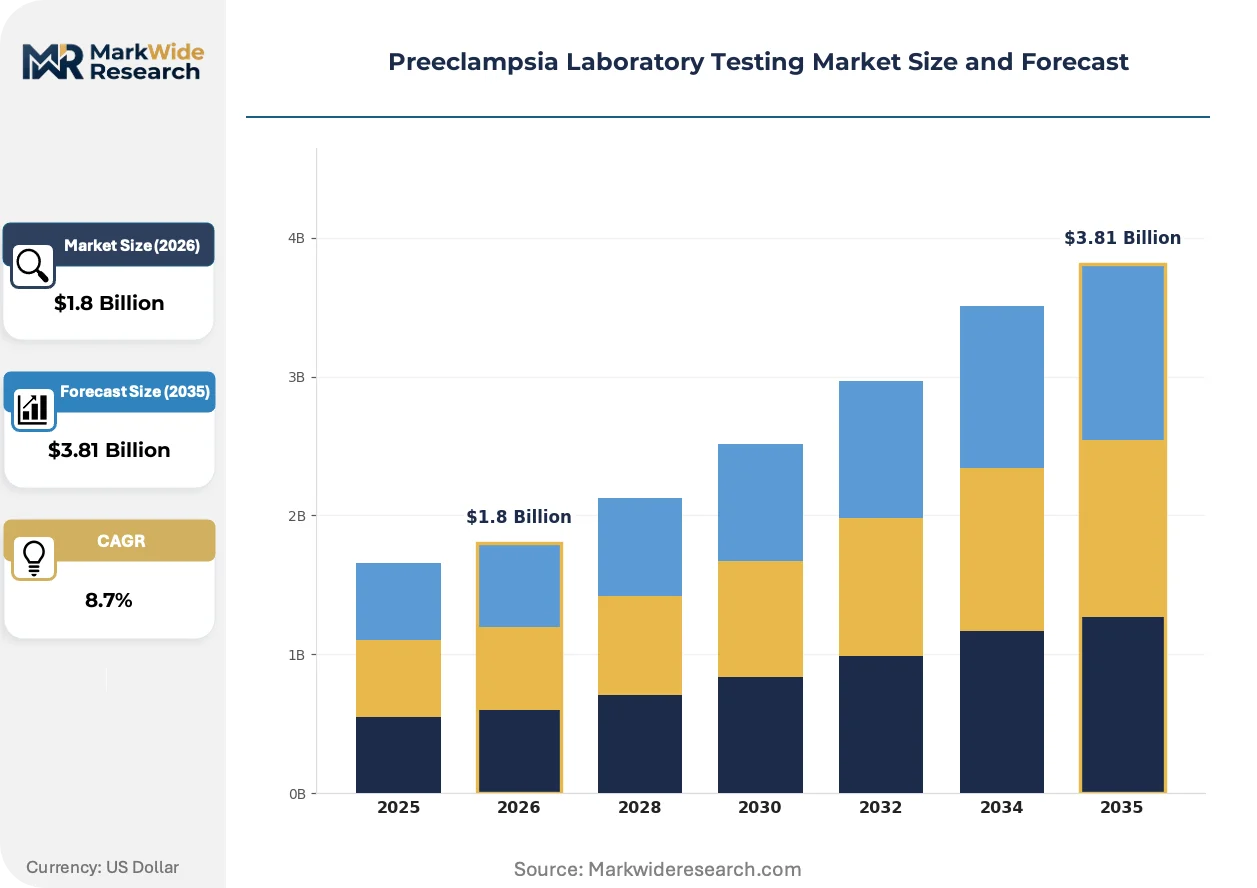
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Blood Tests, Urine Tests, Biochemical Markers, Imaging Techniques Sample Type: Plasma, Serum, Urine, Whole Blood End User: Hospitals, Diagnostic Laboratories, Research Institutions, Outpatient Clinics Technology: Immunoassays, Molecular Diagnostics, Colorimetric Techniques, Microfluidics |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., PerkinElmer Inc., Siemens Healthineers AG, Abbott Laboratories, Labcorp, QuidelOrtho Corporation, Sera Prognostics Inc., Revvity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preeclampsia Laboratory Testing Market Evolving Landscape
Digital pathology and cloud-based algorithmic interpretation are restructuring how placental biomarker data translates into clinical action, compressing the gap between laboratory output and bedside decision-making.
Next-generation sequencing panels targeting circulating placental RNA transcripts are virtualizing early risk detection by enabling first-trimester prediction months before soluble protein biomarkers become detectable. Academic medical centers in the United States are piloting these assays for high-risk nulliparous patients. The technology is virtualizing the traditional second-trimester screening window into pre-conception and early gestation phases.
The EU's In Vitro Diagnostic Medical Devices Regulation is mandating post-market surveillance systems that track assay performance across real-world clinical populations. Manufacturers must now maintain clinical evidence registries spanning multiple member states. Mid-sized diagnostic developers are responding by consolidating CE marking responsibilities through notified body partnerships in Germany and the Netherlands.
Consolidated laboratory procurement in US health systems is displacing fragmented purchasing of individual biomarker tests. Integrated delivery networks now negotiate multi-year supply agreements covering complete maternal health assay menus. This concentration is most visible in the Southeast and Midwest regions where Catholic health systems and academic medical centers dominate inpatient obstetric volume.
Preeclampsia Laboratory Testing Market Segmentation
Preeclampsia laboratory testing segments operate on divergent refresh cycles. Biochemical assays and immunoassay platforms turn over every 18-24 months as predicate-backed 510(k) clearances accelerate, while molecular diagnostics and microfluidic systems stretch toward 36-48 month validation windows due to clinical performance study requirements.
Test Type:
Cycle times compress from 48-hour batch processing for imaging referrals to under 90 minutes for point-of-care biochemical panels.
- Blood Tests:Quantitative serum and plasma analysis of sFlt-1/PlGF ratios dominates hospital laboratory workflows through standardized collection protocols and established CPT reimbursement codes. Demand concentrates in German statutory health insurance networks where predictive screening coverage eliminates patient cost barriers.
- Biochemical Markers:Soluble protein assays measuring endothelial dysfunction markers require refrigerated transport chains and centralized immunoassay platforms. US maternal-fetal medicine departments anchor demand as integrated biomarker panels consolidate previously fragmented testing menus.
- Urine Tests:Proteinuria dipstick and quantitative albumin assays serve resource-limited settings.
- Imaging Techniques:Doppler velocimetry and uterine artery screening divert biochemical demand in tertiary centers.
Blood tests anchor the volume base while biochemical markers gain share at the steepest rate.
Sample Type:
Processing economics favor anticoagulated plasma for high-throughput automation, while serum separation adds cost for smaller batch sizes.
- Plasma:EDTA-anticoagulated specimens enable immediate centrifugation and batch immunoassay processing on automated platforms. European hospital networks concentrate demand where Roche cobas and Siemens Atellica systems process sFlt-1/PlGF ratios during first-trimester screening windows.
- Serum:Clot-activated tubes require 30-minute separation delays but yield cleaner protein matrices for research-grade assays. Academic medical centers in the United States prefer serum for next-generation sequencing validation studies.
- Urine:Midstream collection protocols standardize proteinuria assessment.
- Whole Blood:Point-of-care readers bypass laboratory transport.
Plasma captures the highest throughput volume while whole blood expands most quickly through clinic-based deployment.
End User:
Capital intensity separates centralized laboratory infrastructure from distributed clinic instrumentation.
- Diagnostic Laboratories:Centralized processing economies consolidate maternal health assay menus through multi-year supply agreements with integrated delivery networks. US Southeast and Midwest regions concentrate demand where Catholic health systems and academic medical centers dominate inpatient obstetric volume.
- Hospitals:In-house maternal-fetal medicine departments require 24-hour turnaround for urgent triage decisions. German hospital networks anchor European demand through statutory reimbursement for risk stratification panels.
- Outpatient Clinics:Portable immunoassay readers reduce result delays.
- Research Institutions:Next-generation sequencing pilots drive early validation.
Diagnostic laboratories retain the volume anchor while outpatient clinics climb the fastest through point-of-care adoption.
Technology:
Margin structures separate mature immunoassay platforms from emerging molecular methods.
- Immunoassays:Chemiluminescent and electrochemiluminescent detection systems dominate commercial workflows through predicate-backed regulatory pathways. F. Hoffmann-La Roche Ltd and Siemens Healthineers AG anchor European hospital network supply through automated platform integration.
- Molecular Diagnostics:PCR-based placental RNA signatures and next-generation sequencing panels enable first-trimester prediction before soluble protein biomarkers become detectable. US academic medical centers pilot these assays for high-risk nulliparous patients.
- Microfluidics:Lab-on-chip formats miniimize sample volumes.
- Colorimetric Techniques:Visual endpoint detection serves low-resource settings.
Immunoassays anchor current revenue while molecular diagnostics expands most quickly through pre-symptomatic detection validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Monoclonal antibody production for sFlt-1 and PlGF capture reagents clusters among contract biomanufacturers in Switzerland and Germany, creating geographic dependencies that shape procurement patterns across testing networks.
United States
Integrated delivery networks in the Southeast and Midwest negotiate multi-year supply agreements covering complete maternal health assay menus. The FDA's 510(k) pathway compresses commercialization timelines for novel risk stratification assays. Academic medical centers in Greater Boston pilot next-generation sequencing panels for high-risk nulliparous patients.
Germany
Statutory health insurance reimbursement for predictive sFlt-1/PlGF ratio screening eliminates out-of-pocket barriers for routine maternal monitoring. The EU's In Vitro Diagnostic Medical Devices Regulation mandates clinical performance studies for CE marking across member states. Hospital networks in Bavaria and North Rhine-Westphalia anchor European demand through automated platform integration.
China
NMPA biomanufacturing partnerships in Shanghai and Suzhou bypass import reagent tariffs and accelerate hospital procurement approvals. The National Medical Products Administration enforces GB standard compliance for imported diagnostic reagents. Yangtze River Delta biomanufacturing investments reconfigure domestic diagnostics supply chains.
United Kingdom
Health technology assessment bodies scrutinize cost-effectiveness data for predictive screening versus symptomatic diagnosis protocols. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR requirements for post-market surveillance systems. London and Southeast England concentrate research institution demand for placental RNA signature validation.
Switzerland
Contract biomanufacturers in Basel and Zurich produce monoclonal antibodies for sFlt-1 and PlGF capture reagents serving European and US markets. Swissmedic maintains stringent quality requirements for diagnostic reagent exports. The country's pharmaceutical manufacturing infrastructure supports upstream reagent supply concentration.
Preeclampsia Laboratory Testing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and assay development. The market structure reflects consolidation around automated immunoassay platforms paired with fragmentation among biomarker assay developers. Three archetypes dominate: multinational diagnostics conglomerates with integrated hardware-software-reagent portfolios; mid-sized specialists in maternal-fetal health applications; and contract research organizations validating novel molecular signatures. Competitive moves center on strategic partnerships for regulatory co-development and capacity expansion in biomanufacturing hubs.
Within the multinational tier, F. Hoffmann-La Roche Ltd and Siemens Healthineers AG exemplify platform integrators with automated immunoassay systems embedded in European hospital networks. PerkinElmer Inc. occupies a defined position among maternal-fetal health specialists, representing the mid-sized archetype focused on neonatal and women's health assay development. These three entities anchor different competitive vectors—system integration, geographic penetration, and clinical specialization—without overlapping positioning.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Labcorp |
| QuidelOrtho Corporation |
| Sera Prognostics Inc. |
| Revvity |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Swiss and German contract biomanufacturers for monoclonal antibody production determines both the premium-to-economy pricing spreads across immunoassay tiers and the geographic clustering of supply chain nodes around Basel and Zurich production facilities.
Pricing Analysis
The EU's In Vitro Diagnostic Medical Devices Regulation dictates the pricing tier structure across European markets. Three-tier pricing separates predicate-backed immunoassay platforms from research-grade molecular assays and economy colorimetric alternatives. Price differentiation hinges on CE marking certification level and automated platform integration depth. Cost compression in the economy tier is intensifying because outpatient clinics demand portable reader formats. Academic medical centers show least price sensitivity due to grant-funded validation budgets.
Supply Chain Analysis
Monoclonal antibody feedstock production draws from Switzerland, Germany, and China in descending volume share. Capture reagents for sFlt-1 and PlGF assays rest on recombinant protein expression systems, lyophilized stabilizer matrices, and precision-molded microtiter plates. Single-source vulnerability concentrates in the Basel biomanufacturing corridor where three contract facilities serve overlapping European and US demand. Distribution runs through diagnostic laboratory procurement consortia and integrated delivery network master agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where automated immunoassay system interoperability with legacy electronic health record architectures determines competitive lock-in and switching costs for hospital network procurement committees.
For Market Incumbents: Entrench platform dominance through backward integration into monoclonal antibody production capacity in the Yangtze River Delta biomanufacturing corridor. Deepen assay menu bundling to raise switching costs for integrated delivery networks evaluating multi-year supply renewals. The FDA's 510(k) streamlining for predicate-backed submissions accelerates competitive assay replication, compressing proprietary window periods. For New Entrants and Emerging Players: China's outpatient clinic network represents the most penetrable geography for point-of-care immunoassay reader deployment. NMPA localization partnerships in Shanghai and Suzhou bypass import tariff barriers that disadvantage foreign reagent suppliers. First-trimester molecular screening assays for high-risk nulliparous patients offer the clearest white-space entry vector through maternal-fetal medicine specialist networks. For Investors and Strategic Acquirers: The EU MDR's post-market surveillance mandate reshapes the acquisition landscape toward developers with established clinical evidence registries spanning multiple member states. Long-term viability favors platform-agnostic assay specialists with validated RNA signature pipelines over hardware-dependent system integrators. The signal to watch is German statutory health insurance expansion into predictive screening coverage for additional biomarker panels beyond sFlt-1/PlGF ratios.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical performance studies validate assay reliability for German statutory reimbursement eligibility. |
| Hospital System Partnership | Integrated delivery network master agreements lock in multi-year reagent supply volumes across Southeast and Midwest regions. |
| Reimbursement Strategy | US CPT code establishment for predictive screening panels determines outpatient clinic adoption economics. |
| Software Companion Development | Cloud-based algorithmic interpretation compresses biomarker-to-bedside decision latency for urgent triage protocols. |
| FDA Submission | 510(k) predicate-backed clearances accelerate commercialization timelines for novel risk stratification assays. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maternal-fetal medicine specialists, hospital laboratory directors, diagnostic assay procurement managers, and regulatory affairs leads at IVD developers. Secondary validation drew from FDA 510(k) premarket notification databases, EMA CE marking registries, German statutory health insurance reimbursement schedules, and CMS CPT code proposals. Bottom-up assay volume modeling triangulated against top-down health system expenditure tracking.
Calibration against historical adoption curves for immunoassay platform transitions anchored the projection framework across the analysis window. Segmentation dimensions modeled include test type, sample processing format, end-user setting, and technology platform maturity. CAGRs were derived from logistic diffusion curves fitted to biomarker panel penetration rates. Forecast inputs incorporated EU MDR implementation timelines and NMPA localization mandate enforcement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese biomanufacturing consortia or point-of-care microfluidic specialists would shift outcomes beyond modeled ranges. Cross-checking against German health technology assessment body cost-effectiveness evaluations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Histopathology Services Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
LIMS Market
Laboratory Services
Central Lab Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Global Office Based Lab Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Cytotoxicity Assays Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Enterprise Laboratory Informatics Market
Laboratory Services
Autosampler Vials Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
Karyotyping Service Market